
 Limestone Aggregates Market | 2026-2036
Limestone Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Limestone Aggregates Market Insights
Maintenance and rehabilitation service contracts are broadening what limestone suppliers actually sell, shifting transactions from raw tonnage to performance-based road lifecycle agreements. Vulcan Materials Company leverages its Gulf Coast quarry network to anchor regional supply for highway agencies. Martin Marietta Materials sustains competitive density through vertical integration into asphalt and ready-mix operations. CRH plc differentiates by controlling distribution logistics across fragmented rural construction markets.
Limestone aggregates consist of mechanically crushed sedimentary rock with calcium carbonate content typically exceeding 50 percent, produced through drilling, blasting, crushing, and screening operations for use as structural fill, concrete aggregate, and road base material. Crushed stone dominates product type revenue due to its specification flexibility across infrastructure grades, while high-grade lime commands premium positioning in chemical manufacturing and environmental remediation. Construction anchors end-use demand through federal and state infrastructure programs, though agriculture represents a faster-growing outlet as soil amendment regulations tighten.
The EPA enforces National Ambient Air Quality Standards that restrict particulate emissions from quarry crushing and screening operations, while OSHA mandates silica exposure limits that reshape workplace practices and equipment investment. State departments of transportation impose aggregate quality specifications that determine market access for suppliers bidding on public projects. Stakeholders must monitor how evolving federal infrastructure funding mechanisms and state-level environmental compliance timelines reshape regional competitive boundaries.
Market Dynamics
Highway agencies across the United States are converting raw material contracts into performance-based road lifecycle agreements, forcing limestone suppliers to restructure their value propositions around guaranteed pavement durability rather than delivered tonnage.
Growth Catalysts
- IIJA Infrastructure Funding:The Infrastructure Investment and Jobs Act directs federal capital toward bridge rehabilitation and interstate expansion, channeling demand through state transportation departments for specification-grade crushed stone.
- Petrochemical Corridor Expansion:Gulf Coast port modernization and chemical plant construction in Texas and Louisiana is concentrating aggregate procurement around coastal quarry networks with barge access.
- Precision Agriculture Mandates:State environmental agencies in the Midwest are tightening soil amendment regulations, accelerating lime consumption for pH correction on commercial row-crop operations.
Market Restraints
- Diesel Fuel Cost Volatility:Quarry hauling and crushing operations remain exposed to petroleum price swings that compress margins on fixed-price highway contracts.
- Appalachian Supply Concentration:High-calcium limestone reserves cluster in Kentucky, Tennessee, and Pennsylvania, creating geographic dependency for chemical-grade material specifications.
- OSHA Silica Enforcement:Respirable crystalline silica exposure limits are forcing capital expenditure on dust suppression systems and wet-cutting equipment retrofits.
Strategic Opportunities
- Carbon Capture Utilization:Reacted limestone derivatives for direct air capture and cement kiln emissions scrubbing represent emerging demand from industrial decarbonization projects.
- Rural Last-Mile Logistics:Fragmented county road networks in the Great Plains lack proximate supply, rewarding distributors who stage mobile crushing operations near project sites.
- EPA Beneficial Use Designations:Streamlined permitting for flue gas desulfurization gypsum and quarry fines in structural fill applications opens waste-to-product revenue streams.
Industry Challenges
- Blasting Engineer Shortage:Licensed shotfirer retirements outpace vocational pipeline replenishment, delaying mine plan execution and reserve access timelines.
- Legacy ERP Integration:Real-time load tracking and automated weighbridge systems require costly middleware development to interface with decades-old quarry management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limestone Aggregates Market |
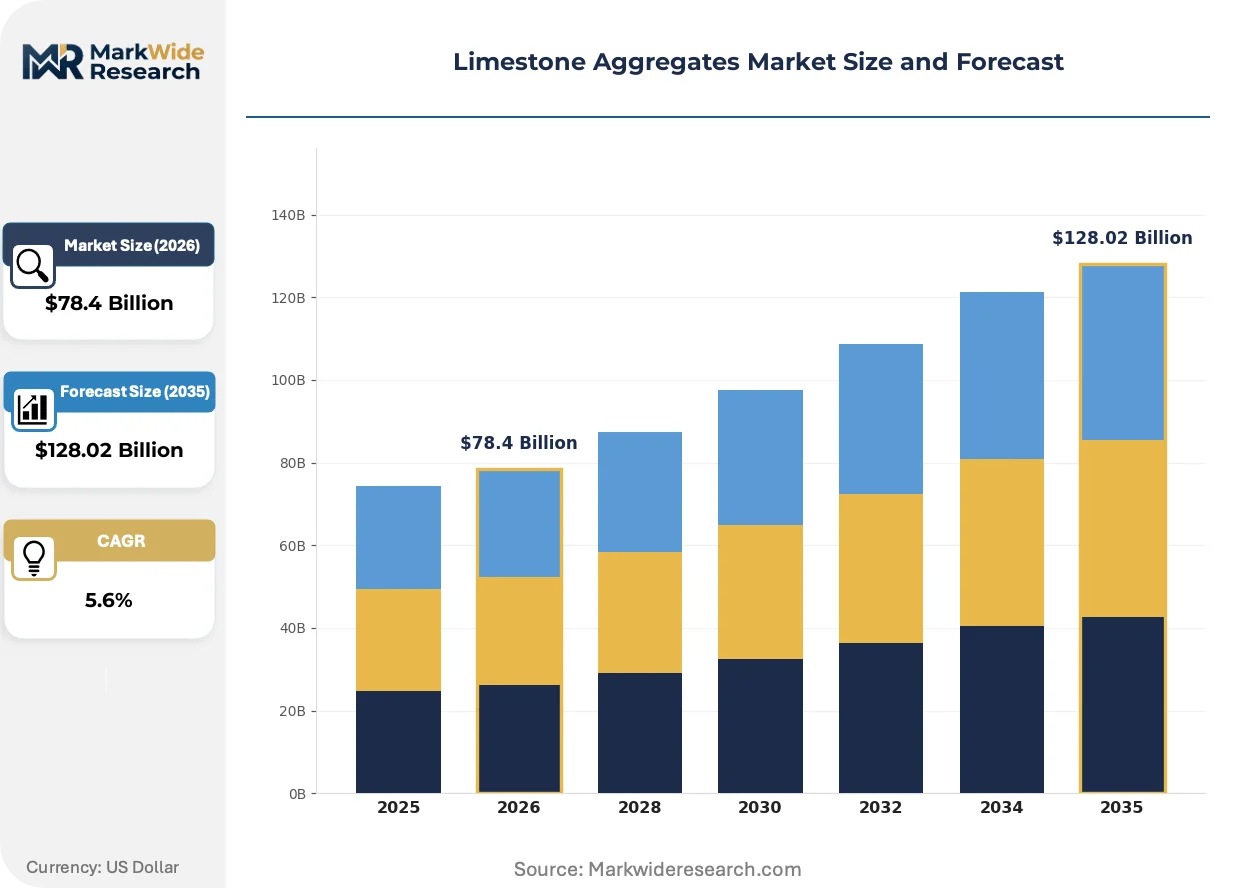
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Stone, Gravel, Sand, High-Grade Lime End Use Industry: Construction, Agriculture, Chemical Manufacturing, Landscaping Size: 3/4 Inch, 1 Inch, 2 Inch, Custom Size Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Vulcan Materials Company, Martin Marietta Materials, CRH plc, Heidelberg Materials, Holcim, CEMEX, Carmeuse, Lhoist Group, Graymont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limestone Aggregates Market Trends and Innovations
Digital quarry management and alternative material recovery are compressing traditional supply chain configurations while environmental compliance technology reshapes operational investment priorities.
Telematics-enabled fleet optimization is decentralizing dispatch authority from centralized quarry offices to field-based logistics coordinators. Regional contractors in the Southeast are adopting these platforms fastest, cutting empty haul miles by enabling real-time job site demand signaling. Load-matching algorithms are compressing the traditional broker-mediated spot market for construction aggregate delivery.
EPA National Ambient Air Quality Standards enforcement is tightening particulate matter thresholds for crushing and screening operations. Quarry operators in Arizona, California, and Texas are retrofitting baghouse systems and water mist cannons to maintain operating permits. Chemical-grade lime producers face the steepest compliance costs due to finer particulate generation during calcination.
State transportation departments are unbundling material supply from construction contracts, forcing aggregate suppliers to bid as standalone vendors rather than subcontracting through general contractors. Ohio, Indiana, and Illinois DOTs have pioneered this procurement split, requiring suppliers to certify quality continuity across multi-year rehabilitation schedules. Independent material testing laboratories are capturing value previously retained by vertically integrated construction firms.
Limestone Aggregates Market Segmentation
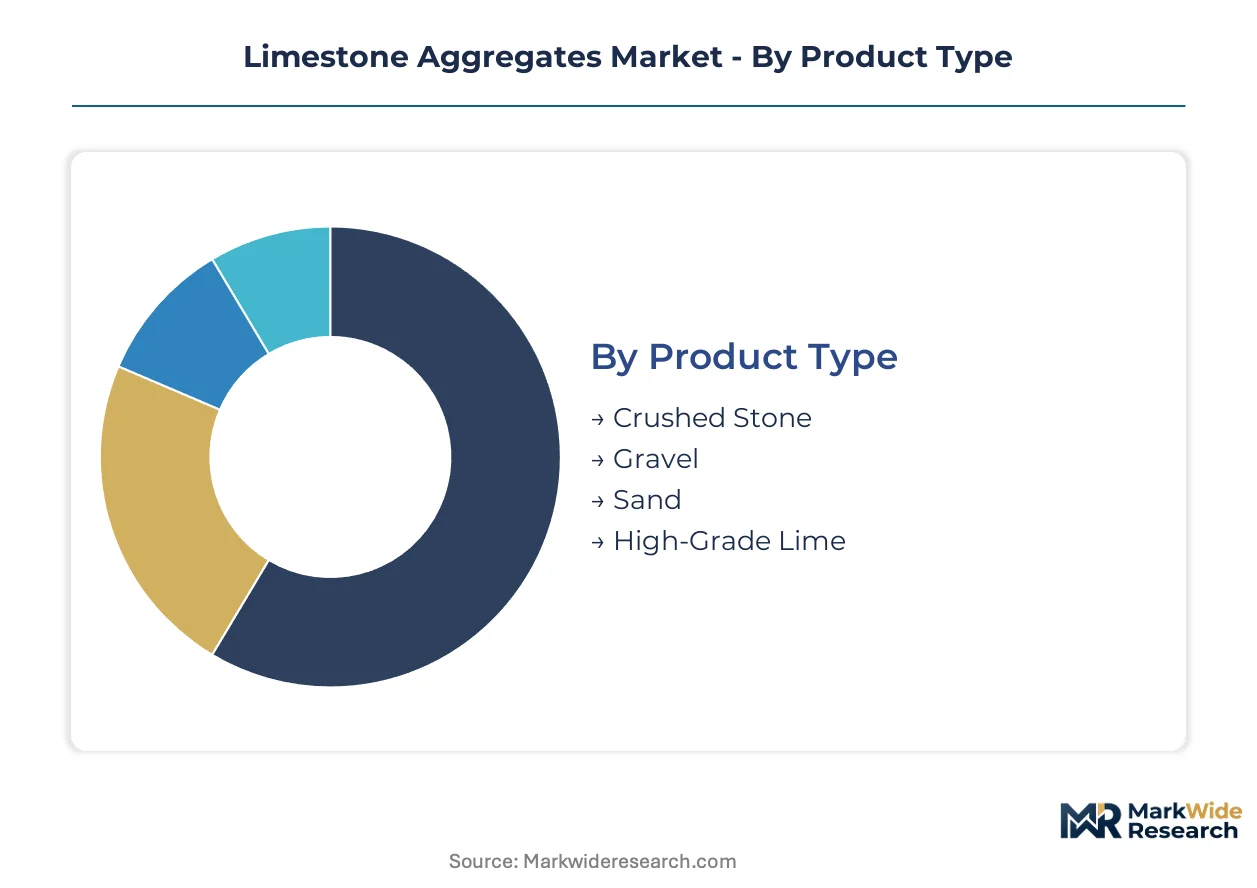
Segmentation in limestone aggregates determines which suppliers qualify for public infrastructure contracts versus specialty chemical applications. Specification-grade material commands certification burdens that reshape competitive boundaries across product categories and end-use channels.
Product Type:
State transportation departments impose aggregate quality specifications that determine market access for crushed stone, while chemical-grade lime faces distinct purity certifications from industrial buyers.
- Crushed Stone:Mechanically crushed sedimentary rock with calcium carbonate content typically exceeding 50 percent, produced through drilling, blasting, crushing, and screening operations. Highway agencies across the United States are converting raw material contracts into performance-based road lifecycle agreements, forcing suppliers to certify pavement durability guarantees. Crushed stone sits at the top of the volume ranking, with high-grade lime climbing the fastest.
- High-Grade Lime:Calcined limestone with elevated calcium oxide content serving chemical manufacturing and environmental remediation. Chemical-grade lime producers face the steepest EPA National Ambient Air Quality Standards compliance costs due to finer particulate generation during calcination.
- Gravel:Naturally rounded coarse aggregate used in concrete production and drainage applications where angularity is not specified.
- Sand:Fine aggregate fraction serving mortar, asphalt, and filtration applications with strict gradation requirements.
Crushed stone dominates tonnage flows through state DOT procurement channels, while high-grade lime captures premium positioning in industrial decarbonization projects.
End Use Industry:
Application-specific certification regimes separate infrastructure-grade supply from agricultural and chemical market entry requirements.
- Construction:Federal and state infrastructure programs anchor aggregate consumption through bridge rehabilitation and interstate expansion projects. The Infrastructure Investment and Jobs Act channels demand through state transportation departments for specification-grade material with certified quality continuity across multi-year rehabilitation schedules.
- Agriculture:Soil amendment applications for pH correction on commercial row-crop operations. State environmental agencies in the Midwest are tightening regulations, accelerating lime consumption as precision agriculture mandates expand.
- Chemical Manufacturing:High-calcium limestone feedstock for cement kiln emissions scrubbing and direct air capture derivatives.
- Landscaping:Decorative stone and erosion control applications with lower specification burdens than structural grades.
Construction commands the largest volume position, with agriculture expanding most quickly as soil amendment regulations tighten across Midwestern states.
Size:
Gradation specifications in public contracts create tiered qualification barriers that filter supplier participation by crushing capability.
- 3/4 Inch:Standard specification for concrete aggregate and asphalt surface courses. State DOTs in Ohio, Indiana, and Illinois require independent material testing laboratory certification for multi-year supply contracts.
- 1 Inch:Base course and structural fill applications with moderate crushing investment requirements.
- 2 Inch:Road base and drainage layer specifications common in heavy-load highway rehabilitation.
- Custom Size:Project-specific gradations for specialized industrial or architectural applications.
3/4 inch material leads in specification frequency, with custom sizes gaining share fastest in petrochemical corridor construction projects.
Distribution Channel:
Channel structure determines logistics cost allocation and quality liability positioning between quarries and end users.
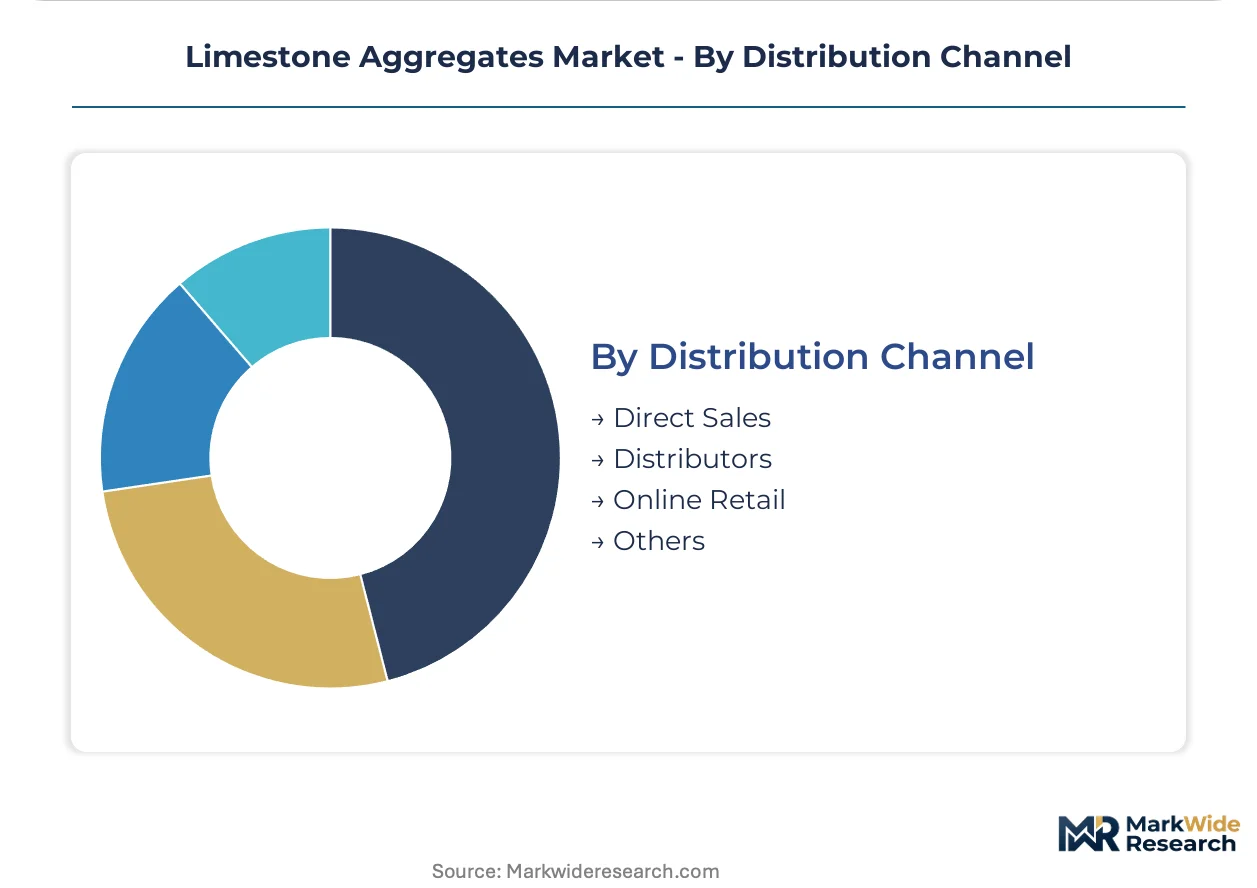
- Direct Sales:Quarry-to-contractor relationships dominating large infrastructure projects. Gulf Coast port modernization and chemical plant construction concentrates procurement around coastal quarry networks with barge access, compressing broker-mediated spot markets.
- Distributors:Regional material yards staging inventory for fragmented county road networks in the Great Plains.
- Online Retail:Emerging platform for small-volume landscaping and residential construction orders.
- Others:Cooperative purchasing agreements and municipal consortium arrangements.
Direct sales maintains volume leadership, with distributors gaining traction fastest in rural last-mile logistics gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's limestone exports to Great Lakes steel mills contrast with Mexico's import dependence for Gulf Coast petrochemical construction, revealing divergent supply security models across North American quarry networks.
United States
Texas and Louisiana port modernization drives barge-dependent aggregate procurement along the Gulf Coast corridor. The EPA enforces National Ambient Air Quality Standards that restrict particulate emissions from crushing operations in Arizona, California, and Texas. Vulcan Materials Company anchors regional supply networks serving state transportation departments converting to performance-based road lifecycle contracts.
Germany
Rhineland cement kiln emissions scrubbing and direct air capture projects accelerate high-calcium limestone consumption. The EU Green Deal carbon border adjustment mechanism pressures quarry operators to document embodied carbon in construction aggregate shipments. Heidelberg Materials maintains integrated supply positions across the Rhine-Ruhr industrial cluster serving chemical-grade specifications.
China
Yangtze River Delta infrastructure rehabilitation and western high-speed rail expansion channel demand through provincial transportation bureaus. MIIT emissions standards for non-metallic mineral processing tighten dust control requirements for calcination operations. Sichuan-Chongqing limestone quarries supply pH correction material for precision agriculture mandates across southwestern commercial farming zones.
India
Maharashtra and Gujarat cement capacity expansion drives crushed stone procurement through state public works departments. BIS aggregate quality specifications determine market access for suppliers bidding on national highway authority contracts. Rajasthan high-calcium deposits feed chemical manufacturing clusters around Vadodara and Mumbai.
Brazil
São Paulo state highway rehabilitation and Minas Gerais iron ore mine tailing stabilization expand specification-grade aggregate demand. ANVISA environmental licensing timelines for quarry expansion compress reserve access schedules. Southeast Brazilian limestone producers serve agricultural lime requirements for soybean belt pH correction programs.
Limestone Aggregates Market Competitive Landscape
Top-tier vendors anchor integrated quarry-to-construction networks, while mid-scale regional operators concentrate on single-state transportation department contracts. The vendor base stratifies across multinational building materials conglomerates, specialized lime calcination firms, and family-owned quarry operations. Three archetypes dominate: vertically integrated construction material suppliers, chemical-grade lime specialists, and regional crushed stone distributors. Competitive moves center on reserve acquisition near growing metropolitan areas and automated dispatch system deployment for logistics cost compression.
Among North American-based integrated suppliers, Vulcan Materials Company and Martin Marietta Materials exemplify the scale-driven archetype with Gulf Coast and Southeast quarry network density. CRH plc occupies a position representing European-headquartered multinational diversification across fragmented rural construction markets. These three entities anchor competitive positioning around state department of transportation certification regimes and performance-based supply contract structuring.
| Leading Market Players |
|---|
| Vulcan Materials Company |
| Martin Marietta Materials |
| CRH plc |
| Heidelberg Materials |
| Holcim |
| CEMEX |
| Carmeuse |
| Lhoist Group |
| Graymont |
| Others |
Pricing and Supply Chain Analysis
State transportation department procurement concentration is compressing pricing power toward specification-grade suppliers with certified quality continuity. Highway agencies unbundling material supply from construction contracts forces aggregate vendors into standalone bidding with durability guarantees rather than tonnage-based pricing.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for Gulf Coast barge-accessible material. Three-tier pricing structure across specification-grade, industrial-grade, and agricultural-grade levels stratifies by certification burden and calcium carbonate purity. Cost compression in standard crushed stone is intensifying because diesel fuel volatility erodes margins on fixed-price highway contracts. Small-scale landscaping distributors exhibit highest price sensitivity, while petrochemical corridor developers accept premium positioning for guaranteed supply security.
Supply Chain Analysis
Licensed shotfirer retirements in Kentucky, Tennessee, and Pennsylvania are constraining reserve access timelines for high-calcium limestone deposits. Quarry operations draw from ammonium nitrate fuel oil, diesel equipment fleets, and wear-resistant crushing media as core inputs. Single-source vulnerability concentrates in Appalachian chemical-grade reserves where geographic clustering limits alternative supply. Distribution runs through direct quarry-to-contractor relationships for infrastructure projects, with regional distributors staging mobile crushing for rural last-mile gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as state DOTs mandate performance-based road lifecycle agreements over raw tonnage transactions. Specification-grade certification is displacing commodity supply relationships.
For Market Incumbents: Deepen reserve acquisition near metropolitan growth corridors to anchor regional supply density. Integrate automated weighbridge and telematics systems to compress logistics costs against diesel price volatility. Cement state transportation department certification regimes as defensive moats against emerging mobile crushing operators.
For New Entrants and Emerging Players: Capture rural last-mile logistics gaps in the Great Plains where fragmented county road networks lack proximate supply. Stage mobile crushing operations near active project sites to bypass fixed quarry infrastructure requirements. Pursue EPA beneficial use designations for quarry fines as differentiated waste-to-product revenue streams.
For Investors and Strategic Acquirers: Building materials conglomerates with Gulf Coast quarry networks are the most active acquirer in this space. Target family-owned operations with permitted reserves near interstate corridor expansion zones. Watch IIJA funding disbursement velocity as the inflection indicator for specification-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reserve Acquisition Near Metro Corridors | Positions suppliers for state DOT performance-based contracts with guaranteed pavement durability terms. |
| Telematics Fleet Optimization | Enables real-time job site demand signaling that cuts empty haul miles for Southeast regional contractors. |
| EPA Beneficial Use Permitting | Opens waste-to-product revenue streams for flue gas desulfurization gypsum and quarry fines applications. |
| Mobile Crushing Deployment | Addresses rural last-mile logistics gaps in Great Plains county road networks lacking fixed quarry access. |
| Carbon Capture Derivative Development | Captures emerging demand from cement kiln emissions scrubbing and direct air capture projects. |
Research Methodology
Multiple input streams — quarry operations managers, state transportation department procurement officers, chemical manufacturing procurement leads, and agricultural lime distributors — were reconciled against trade association production data, EPA enforcement records, state DOT contract awards, and SEC 10-K filings from listed building materials firms. Bottom-up reserve capacity estimates and top-down infrastructure spending allocations were triangulated to validate volume assumptions across product categories.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, gradation size, and distribution channel. CAGRs were derived from elasticity-adjusted demand curves incorporating IIJA funding trajectories, petrochemical corridor construction schedules, and precision agriculture mandate adoption curves.
Diesel fuel price spikes, OSHA silica enforcement delays, and blasting engineer supply constraints are the dominant revision risks for quarry output assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Canada Asphalt Shingles Market