
 Poland Ceramic Tiles Market | 2026-2036
Poland Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Ceramic Tiles Market Analytics
Aftermarket service revenue is fragmenting across Poland's ceramic tile distribution network as installers and retailers compete for recurring maintenance contracts. Ceramika Paradyż leverages its nationwide dealer network to capture refurbishment work. Cersanit S.A. sustains loyalty through certified installer programs. Tubądzin Group anchors premium project specification through architect-direct relationships.
Poland ceramic tiles are kiln-fired clay-based surfacing materials, typically pressed at 300-450 kg/cm² and fired at 1,100-1,250°C, serving primarily as durable interior and exterior architectural finishes. Floor tiles dominate volume throughput in Polish manufacturing, while porcelain tiles command the fastest expansion due to frost resistance specifications for outdoor applications. Mosaic tiles occupy a specialized niche where designer-driven residential projects generate above-average margins.
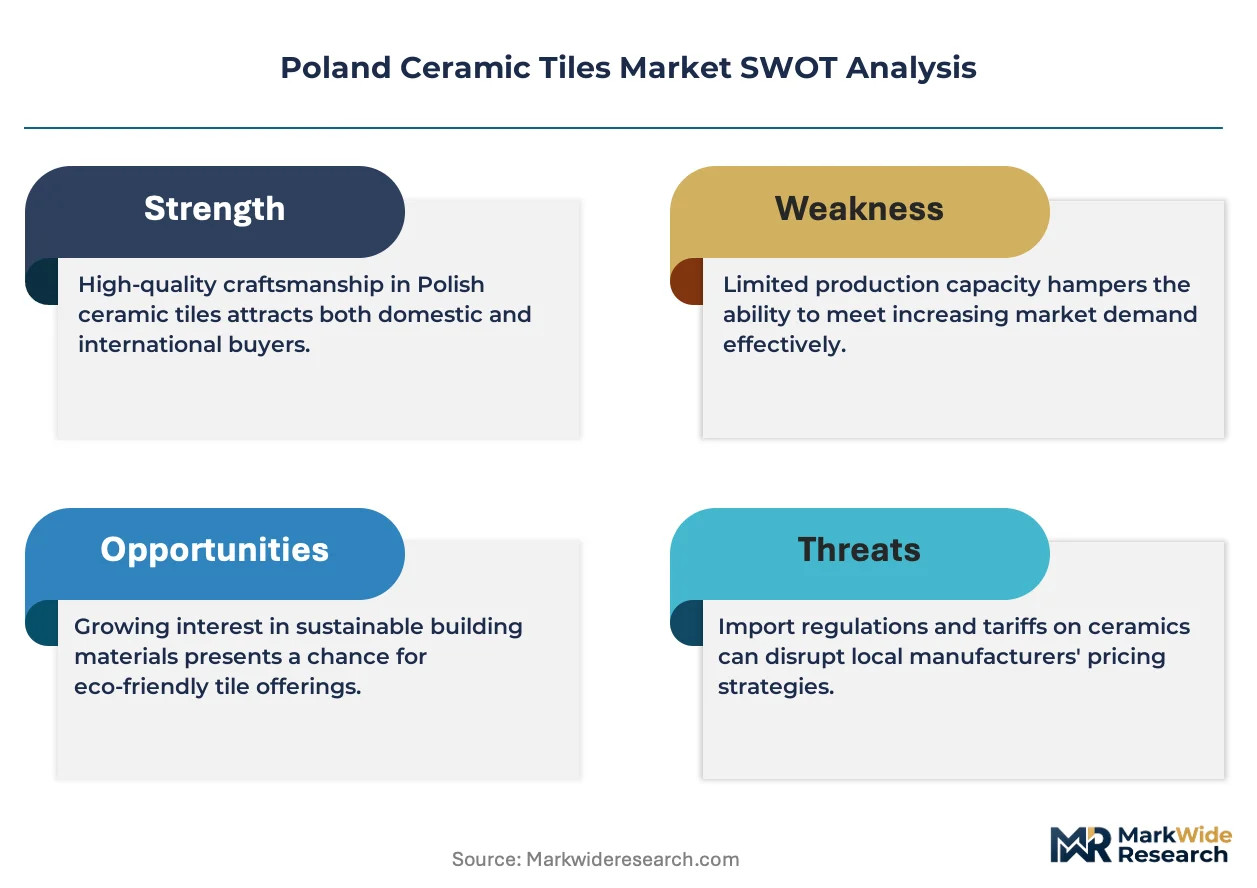
Polish manufacturers navigate BIS-equivalent quality certifications alongside EU CE marking requirements for construction products under the Construction Products Regulation. The country's national building regulator enforces thermal performance standards that increasingly favor porcelain and thick-format tiles in energy-efficient building envelopes. Stakeholders must monitor how the EU Ecodesign for Sustainable Products Regulation reshapes material composition rules and recycled content thresholds for ceramic goods.
Market Dynamics
The EU Green Deal's building renovation targets are restructuring material specifications across Polish construction, forcing manufacturers to reconfigure product portfolios around thermal performance and recycled content thresholds.
Growth Catalysts
- EU Green Deal renovation mandates:The European Commission's binding targets for energy-efficient building retrofits are pulling porcelain and thick-format tiles into exterior envelope applications.
- Frost-resistant porcelain technology:Advanced kiln-firing processes enable outdoor specifications that capture specification share from natural stone in Polish climate conditions.
- Silesian manufacturing cluster concentration:Proximity to raw material deposits and established logistics infrastructure compresses production-to-market lead times for domestic distribution.
Market Restraints
- Natural gas price volatility:Kiln operations depend on fossil fuel inputs, exposing margins to energy cost swings that resist full pass-through to price-sensitive renovation segments.
- Kaolin supply concentration:High-grade clay deposits concentrate in select Ukrainian and Czech extraction zones, creating inbound material vulnerability.
- REACH chemical compliance:ECHA substance restrictions on glazes and pigments extend reformulation timelines and certification costs for export-bound production.
Strategic Opportunities
- EU Ecodesign for Sustainable Products Regulation:Early alignment with recycled content thresholds positions compliant manufacturers for preferential public procurement access.
- Architect-direct specification channels:Bypassing traditional distributor layers through certified designer programs captures premium-margin project work.
- Thick-format ventilated facade systems:Integration with external wall insulation configurations opens commercial building envelope applications beyond traditional flooring.
Industry Challenges
- Certified installer scarcity:Complex large-format and facade mounting techniques outpace vocational training pipeline output, constraining premium segment rollout.
- Dual BIS-equivalent and CE marking burden:Parallel national quality certification and Construction Products Regulation compliance extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Ceramic Tiles Market |
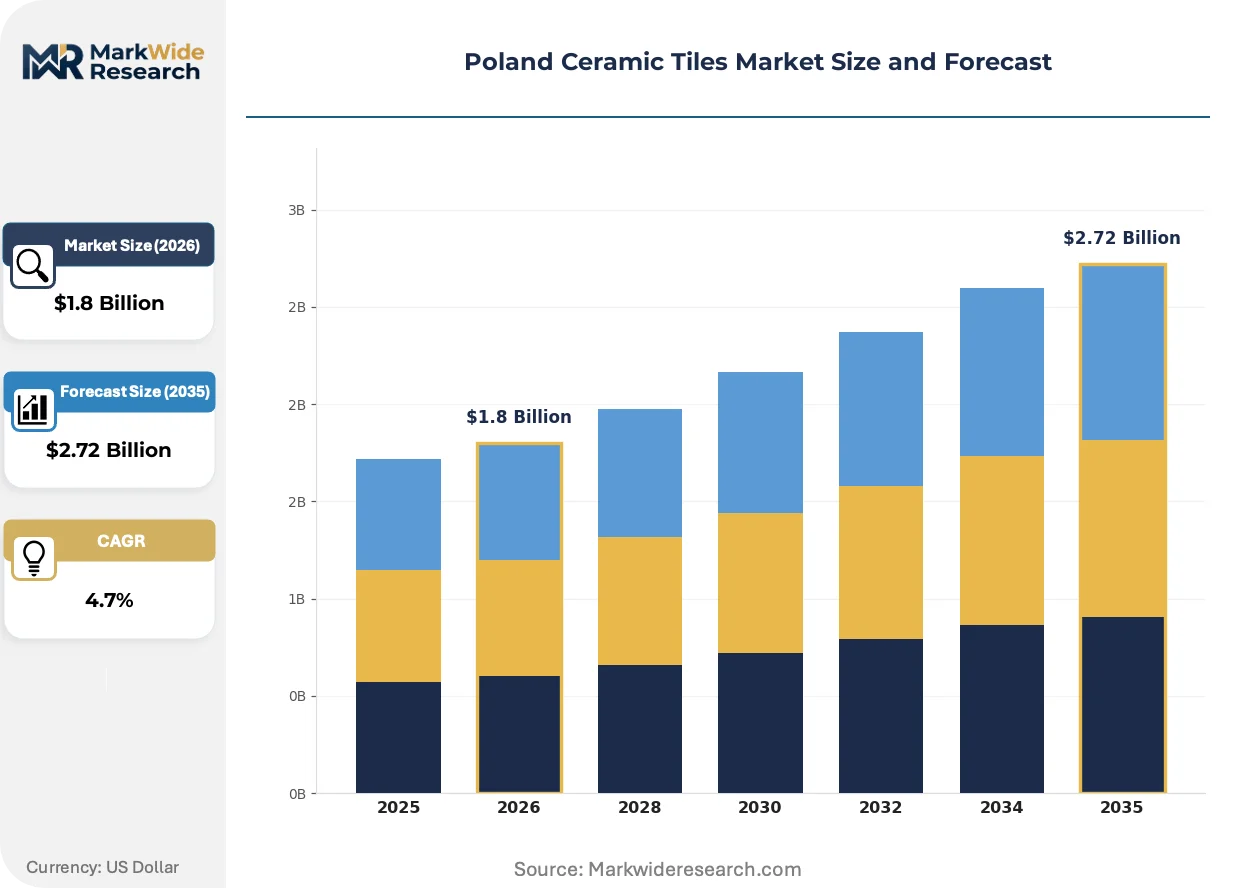
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Tiles, Wall Tiles, Mosaic Tiles, Porcelain Tiles Application: Residential, Commercial, Industrial, Outdoor Material: Ceramic, Stoneware, Glazed, Terracotta End User: Contractors, Homeowners, Architects, Designers |
| Companies Covered | Cerrad Sp. z o.o., Marazzi Poland, Ceramika Paradyż, RAK Ceramics, Ceramika Końskie, Cersanit S.A., Opoczno S.A., Kale Group, Tubądzin Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Ceramic Tiles Market Evolving Landscape
Digital decoration and press technology are compressing design-to-production cycles, enabling batch-size flexibility that responds to project-specific architectural specifications.
Single-pass digital inkjet printing is collapsing the traditional separation between high-volume standard lines and short-run custom production. Polish manufacturers serving designer-driven residential projects now run economically viable lots below 500 square meters. This capability is collapsing minimum order thresholds that previously locked small architectural studios out of direct factory relationships.
The EU Ecodesign for Sustainable Products Regulation is mandating digital product passports and recycled content disclosure for construction products entering the European market. Polish manufacturers must reconfigure supply chain documentation and material sourcing to meet verified circularity claims. Floor tile categories face the steepest compliance ramps due to higher material throughput and glaze complexity.
Specification decisions are migrating earlier in project development, with architects and interior designers consolidating material choices before contractor involvement. This shift compresses the window for distributor-led influence and elevates manufacturer investment in continuing education and sample logistics. Warsaw and Kraków design studios demonstrate the most pronounced consolidation of early-stage material authority.
Poland Ceramic Tiles Market Segmentation
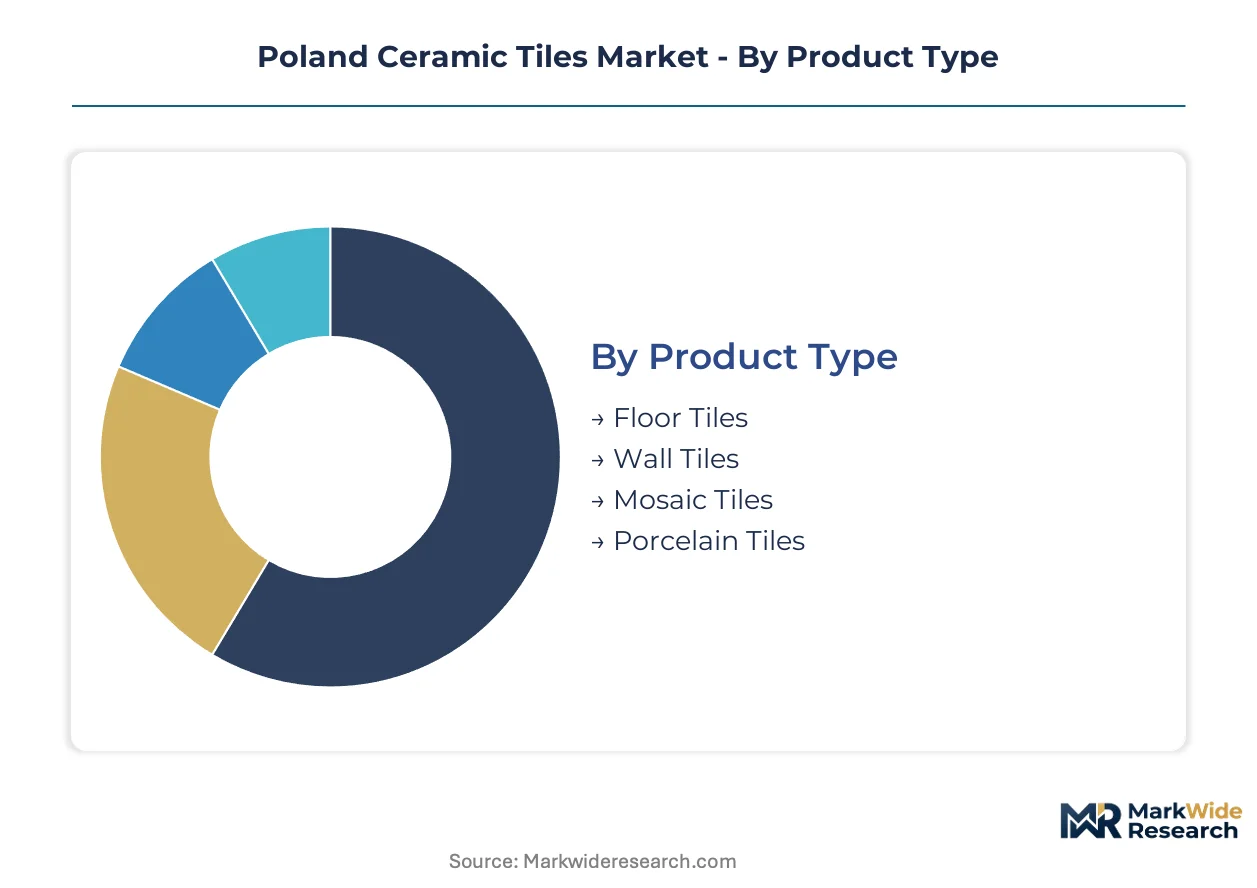
Segmentation in Poland's ceramic tiles market reveals divergent service intensity requirements across product categories. Floor tiles demand recurring maintenance contracts that reshape distributor profitability. Wall tiles and porcelain formats require certified installation support that fragments margin capture between manufacturers and specialized contractors.
Product Type:
After-sales service intensity varies sharply across product categories, with large-format and outdoor-rated tiles requiring specialized installer networks that manufacturers must certify and retain.
- Floor Tiles:Pressed at 300-450 kg/cm² and fired at 1,100-1,250°C, these high-volume products serve residential renovation and commercial flooring across Silesian manufacturing cluster distribution zones. Demand concentrates in Polish homeowner refurbishment projects where durability specifications outweigh premium design considerations, though natural gas price volatility compresses margins on standard-grade production.
- Porcelain Tiles:Advanced kiln-firing achieves frost resistance for outdoor envelope applications, capturing specification share from natural stone in Polish climate conditions. EU Green Deal renovation mandates are pulling thick-format porcelain into external wall insulation configurations across Greater Poland manufacturing cluster output, with architect-direct channels dominating premium project placement.
- Wall Tiles:Glazed ceramic surfacing for interior vertical applications, primarily specified through retail distributor networks serving bathroom and kitchen renovation segments.
- Mosaic Tiles:Designer-driven residential projects generate above-average margins through small-batch digital decoration capabilities, with Warsaw and Kraków studios consolidating early-stage material authority.
By volume, Floor Tiles leads. By growth pace, Porcelain Tiles is ahead.
Application:
Cost tier differentiation separates specification-grade commercial envelope work from price-sensitive residential renovation, with public procurement compliance requirements adding a third tier.
- Residential:Renovation spending among Polish homeowners accelerates uptake of mid-range floor and wall tiles, with retail distributor networks competing for recurring maintenance contract capture.
- Commercial:Thick-format ventilated facade systems integrate with external wall insulation configurations, opening building envelope applications beyond traditional flooring for Silesian cluster manufacturers.
- Outdoor:Frost-resistant porcelain specifications displace natural stone in Polish climate conditions, with EU Green Deal mandates tightening material compliance for energy-efficient retrofits.
- Industrial:Heavy-duty stoneware and thick-format tiles serve manufacturing facility flooring where chemical resistance and load-bearing capacity dominate specification criteria.
Residential commands volume throughput. Commercial applications are climbing the fastest.
Material:
Volume concentration in ceramic and stoneware production reflects raw material proximity to Silesian kaolin processing infrastructure.
- Ceramic:Standard-grade body composition dominates Polish manufacturing output, serving price-sensitive renovation segments through established distributor networks.
- Stoneware:Higher-density firing yields commercial-grade durability specifications, with thick-format variants penetrating facade and industrial flooring applications.
- Glazed:Digital inkjet decoration enables batch-size flexibility below 500 square meters, collapsing minimum order thresholds for Warsaw and Kraków architectural studios.
- Terracotta:Traditional clay body composition serves heritage restoration and designer-driven residential niches with specialized sourcing requirements.
Ceramic leads by production volume. Glazed materials are gaining share fastest.
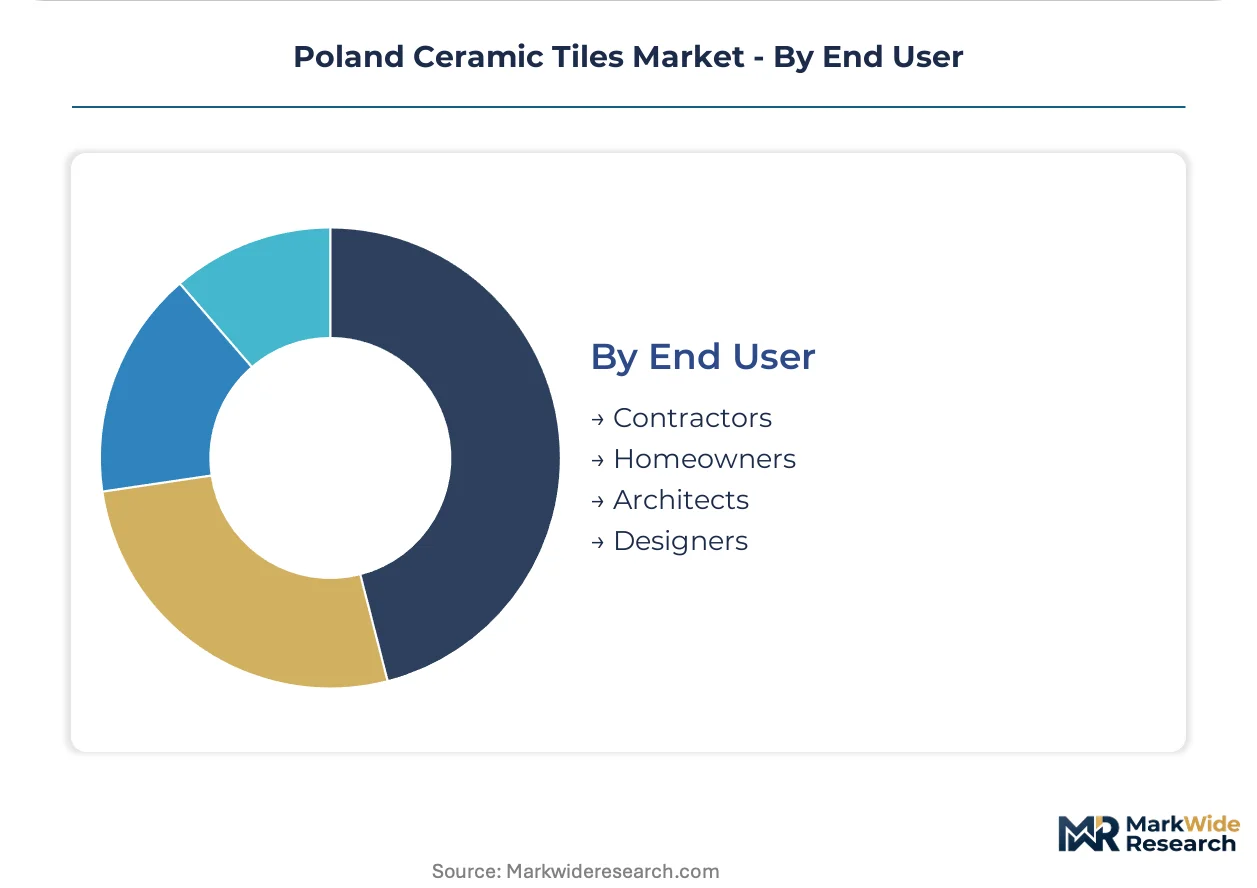
End User:
Customer type determines channel configuration, with architect-direct specification bypassing traditional distributor layers for premium-margin project work.
- Contractors:Volume procurement through distributor networks dominates standard-grade floor and wall tile placement, with certified installer scarcity constraining large-format rollout.
- Homeowners:Retail-driven selection for residential renovation concentrates in bathroom and kitchen applications, with maintenance contract competition fragmenting aftermarket revenue.
- Architects:Early-stage material authority consolidation in Warsaw and Kraków design studios elevates manufacturer investment in continuing education and sample logistics.
- Designers:Small-batch digital decoration capabilities enable direct factory relationships for project-specific specifications below traditional minimum order thresholds.
Contractors drive volume procurement. Architects are expanding their specification influence most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish consumption tilts heavily toward renovation-driven floor tiles, whereas neighboring markets allocate larger shares to new-build porcelain specifications for commercial envelopes.
Silesian Voivodeship
Residential refurbishment projects dominate tile consumption across Katowice and Gliwice metro zones, with homeowners prioritizing durability over premium design. The EU Green Deal's binding renovation targets pull thick-format porcelain into exterior envelope applications. Cerrad Sp. z o.o. anchors production capacity in this cluster, leveraging proximity to kaolin processing infrastructure.
Greater Poland Voivodeship
Commercial building retrofits accelerate demand for frost-resistant porcelain in Poznań and surrounding industrial zones. REACH compliance requirements from ECHA extend reformulation timelines for glaze-intensive product lines. Tubądzin Group concentrates architect-direct specification activity here, bypassing traditional distributor layers for premium-margin project work.
Masovian Voivodeship
Warsaw design studios consolidate early-stage material authority, driving small-batch digital decoration demand below 500 square meter thresholds. The national building regulator enforces thermal performance standards favoring energy-efficient building envelopes. Retail distributor networks compete intensively for recurring maintenance contract capture across residential renovation segments.
Lesser Poland Voivodeship
Kraków's architectural community increasingly specifies mosaic tiles for designer-driven residential projects generating above-average margins. EU Ecodesign for Sustainable Products Regulation mandates digital product passports and recycled content disclosure. Ceramika Paradyż leverages its nationwide dealer network to capture refurbishment work in this heritage-rich region.
Lower Silesian Voivodeship
Industrial flooring applications concentrate around Wrocław manufacturing corridors, where heavy-duty stoneware specifications dominate procurement criteria. Natural gas price volatility exposes kiln operation margins to energy cost swings. Cersanit S.A. sustains contractor loyalty through certified installer programs addressing large-format mounting complexity.
Poland Ceramic Tiles Market Competitive Landscape
Capability concentration sits with premium-tier specialists commanding architect-direct channels; scale advantage sits with volume manufacturers serving renovation-driven retail networks. The vendor base organizes around three strategic archetypes: design-forward boutiques capturing specification influence, integrated producers controlling raw material-to-distribution pipelines, and regional champions defending price-sensitive home improvement segments. Dominant competitive moves include backward integration into kaolin processing infrastructure and technology licensing agreements for digital inkjet decoration systems.
Among Poland-based producers, Cerrad Sp. z o.o. and Ceramika Paradyż occupy positions within the integrated manufacturer tier, while Cersanit S.A. exemplifies the scale-driven renovation specialist archetype. These entities represent contrasting strategic postures: one emphasizes production-to-market compression through captive raw material access, another prioritizes nationwide distribution density for recurring maintenance revenue capture, and the third anchors contractor loyalty through vocational certification investments. Their collective positioning illustrates how Polish ceramic tile competition fragments across capability specialization rather than converging on undifferentiated volume rivalry.
| Leading Market Players |
|---|
| Cerrad Sp. z o.o. |
| Marazzi Poland |
| Ceramika Paradyż |
| RAK Ceramics |
| Ceramika Końskie |
| Cersanit S.A. |
| Opoczno S.A. |
| Kale Group |
| Tubądzin Group |
| Others |
Value Network & Pricing Analysis
The Silesian manufacturing cluster's kiln capacity dynamics compress production-to-market lead times, translating upstream efficiency into pricing power for domestic distribution networks serving Polish renovation contractors. Natural gas price volatility feeds directly into margin compression across standard-grade floor tile output, while frost-resistant porcelain commands premium positioning through architect-direct channels.
Pricing Analysis
Long-term offtake contracts dominate procurement between Silesian manufacturers and national distributor networks, insulating volume commitments from spot market energy swings. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified porcelain specifications from basic ceramic grades, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from natural gas cost volatility that resists full pass-through to price-sensitive residential renovation segments. Polish homeowners exhibit highest price sensitivity, while commercial envelope specifiers demonstrate lowest elasticity due to EU Green Deal compliance mandates.
Supply Chain Analysis
Tariff exposure between Poland and Ukrainian kaolin extraction zones dominates inbound material vulnerability for high-grade clay inputs. Manufacturing capacity concentrates in Poland, Czech Republic, and Germany, with the Silesian cluster drawing from captive kaolin processing infrastructure and cross-border Czech deposits. Raw material dependencies center on Ukrainian kaolin, Czech feldspar, and domestic clay reserves. Single-source vulnerability in Ukrainian high-grade clay feeds creates supply chain risk. Distribution runs through manufacturer-owned dealer networks and specialized tile distributors serving contractor and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue from certified installer programs and recurring maintenance contracts is expanding faster than hardware throughput, positioning service-attach models as the priority growth layer for Polish ceramic tile stakeholders.
For Market Incumbents: Pre-empt certified installer scarcity by expanding vocational training pipeline output before large-format porcelain rollout constraints premium segment capture. Anchor backward integration into kaolin processing infrastructure to defend margin position against Ukrainian supply disruption. Prioritize CE marking and BIS-equivalent certification investments to compress dual-compliance launch timelines. For New Entrants and Emerging Players: Lesser Poland Voivodeship's heritage restoration segment offers underpenetrated white-space for terracotta and mosaic tile specialization with above-average margin potential. Target Kraków design studios through small-batch digital decoration capabilities below 500 square meter thresholds. Deploy architect-direct specification channels bypassing established distributor layers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive raw material access and digital inkjet decoration capabilities. Long-term viability across the analysis window rests on EU Ecodesign compliance infrastructure and recycled content verification systems. Watch for EU Ecodesign for Sustainable Products Regulation enforcement timing as inflection indicator for preferential public procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Processing | Captive supply of high-grade clay reduces Ukrainian import dependency for Silesian manufacturers. |
| Certified Installer Program Expansion | Vocational training pipeline addresses scarcity constraining large-format porcelain rollout. |
| Digital Inkjet Decoration Licensing | Single-pass printing enables economically viable sub-500 square meter custom production runs. |
| EU Ecodesign Compliance Investment | Recycled content verification positions manufacturers for preferential public procurement access. |
| Architect-Direct Specification Channel | Bypassing distributor layers captures premium-margin commercial envelope project placement. |
Research Methodology
Desk research of trade association production statistics, EU regulatory filings, and customs import records preceded structured interviews with plant operations directors, distributor procurement managers, certified installation contractors, and Warsaw-based specification architects. Primary fieldwork combined with secondary validation from Ceramika Paradyż and Cersanit S.A. public disclosures, Central Statistical Office of Poland construction output data, and ECHA substance restriction updates. Bottom-up volume modeling triangulated against top-down construction spending elasticity estimates.
Assumptions held natural gas price volatility within observed ranges and EU Green Deal renovation targets at stated enforcement levels across the analysis window. Segmentation modeling incorporated product type, application, material composition, and end-user channel dimensions. CAGRs derived from polynomial trend fitting to historical production volumes, adjusted for regulatory compliance phase-in schedules and certified installer training capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Czech or German competitors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Limestone Aggregates Market