
 Hollow Concrete Block Market | 2026-2036
Hollow Concrete Block Market Size, Share, and Industry Trends Forecast 2026-2036
Hollow Concrete Block Market Analysis
Skilled mason availability is bifurcating the hollow concrete block landscape into machine-dependent and labor-dependent supply tiers. UltraTech Cement Ltd. leverages its captive cement-to-block pipeline to dominate western India production. Heidelberg Materials anchors European demand through automated block plants with consistent dimensional tolerance. CEMEX S.A.B. de C.V. competes across Latin American infrastructure bids with standardized hollow core designs.
Hollow concrete blocks are load-bearing masonry units with one or more voids comprising 25-50% of gross volume, manufactured from Portland cement, aggregates, and water through vibration or pressing. These voids reduce unit weight, improve thermal insulation, and allow steel reinforcement grouting for seismic-resistant walls. Thermal blocks lead product type margins due to energy code enforcement in residential buildings, while infrastructure projects represent the fastest-growing end use as governments prioritize flood-resilient retaining walls. Machine-made manufacturing dominates volume but vibrated cast methods occupy premium positioning for architectural applications requiring exposed finishes.
India's BIS compressive strength standards, Europe's CE marking under the Construction Products Regulation, and the US EPA's National Ambient Air Quality Standards collectively shape block chemistry, curing emissions, and market access protocols. India's PLI scheme for construction material localization amplifies domestic capacity expansion incentives. Stakeholders must monitor how carbon border adjustments and embodied carbon disclosure rules recalibrate sourcing decisions across supply footprints.
Market Dynamics
India's Bureau of Indian Standards compressive strength mandate is forcing quality upgrades across the hollow concrete block supply base, bifurcating production between automated machine-dependent and labor-dependent tiers.
Growth Catalysts
- India's PLI scheme for construction material localization:Domestic capacity expansion incentives amplify manufacturing investment across Maharashtra and Gujarat states where urban housing clusters expand fastest.
- Thermal block specification:Energy code enforcement in residential buildings drives specification of void-optimized units that improve thermal insulation performance.
- Flood-resilient infrastructure prioritization:Government retaining wall mandates accelerate hollow core adoption for seismic-resistant, steel-reinforced grouting applications.
Market Restraints
- Portland cement input cost volatility:Energy-intensive clinker production exposes block margins to fuel price swings and carbon border adjustment exposure.
- Western India supply concentration:Maharashtra and Gujarat production clusters concentrate capacity risk against monsoon logistics disruptions.
- Clay brick substitution in rural segments:Traditional fired clay masonry retains cost advantage in unregulated construction zones outside urban building codes.
Strategic Opportunities
- Architectural exposed-finish positioning:Vibrated cast methods command premium pricing for aesthetic wall applications in commercial facades.
- Carbon disclosure alignment:Embodied carbon tracking rules create first-mover advantage for producers with lifecycle-assessed block chemistry.
- Captive cement-to-block pipeline integration:Backward integration into cement sourcing secures margin control and quality consistency.
Industry Challenges
- Skilled mason availability compression:Machine-dependent manufacturing requires retraining programs for vibration equipment operation and automated curing management.
- CE marking compliance timeline:Europe's Construction Products Regulation demands third-party certification for dimensional tolerance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hollow Concrete Block Market |
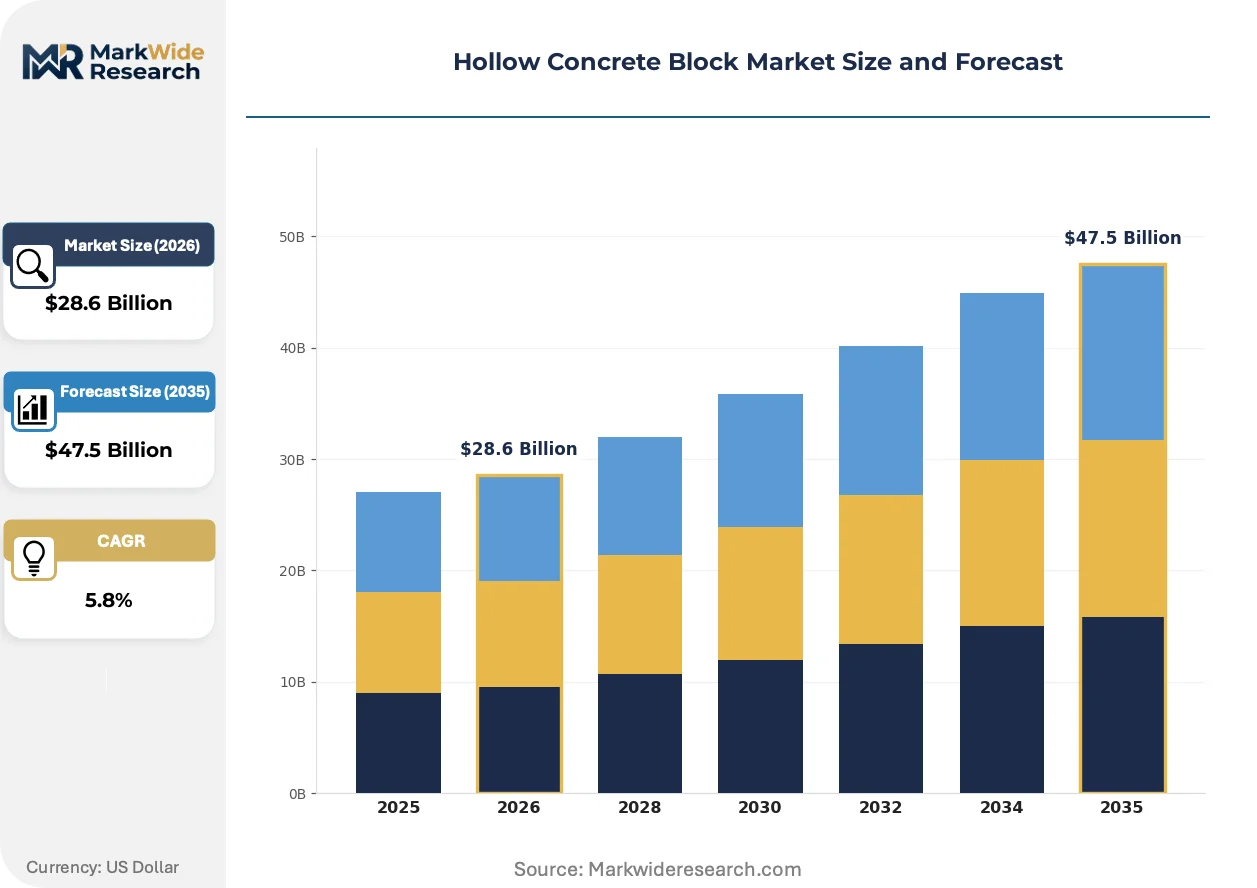
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blocks, Thermal Blocks, Soundproof Blocks, Decorative Blocks End Use: Residential Buildings, Commercial Properties, Industrial Structures, Infrastructure Projects Manufacturing Method: Machine-Made, Hand-Made, Vibrated Cast, Lightweight Application: Building Construction, Garden Walls, Retaining Walls, Partition Walls |
| Companies Covered | UltraTech Cement Ltd., Heidelberg Materials, CEMEX S.A.B. de C.V., Acme Brick Company, Wienerberger, CRH plc, Boral Limited, General Shale, Holcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hollow Concrete Block Market Emerging Trajectories
Automation is compressing the hollow concrete block manufacturing base toward consistent dimensional tolerance, while regulatory pressure on embodied carbon recalibrates material chemistry and curing protocols.
Self-compacting concrete mix designs are supplanting traditional vibration-dependent production in premium architectural block segments. High-rise residential developers in urban India specify these units for exposed finish walls that eliminate surface honeycombing. The technology is supplanting conventional pressed-block methods in projects where aesthetic quality commands specification premiums.
Europe's CE marking under the Construction Products Regulation mandates third-party assessment of compressive strength and dimensional consistency for market access. Block exporters to the European Union must maintain factory production control systems audited by notified bodies. Thermal block categories face intensified scrutiny as energy performance declarations become mandatory for residential building permits.
Builder procurement is consolidating around certified supply chains that document compressive strength compliance and carbon footprint. Large residential developers in Gujarat and Maharashtra now mandate BIS-certified suppliers with automated quality testing. This specification compression favors machine-made producers with captive laboratory testing over informal vibrated-cast operations.
Hollow Concrete Block Market Segmentation
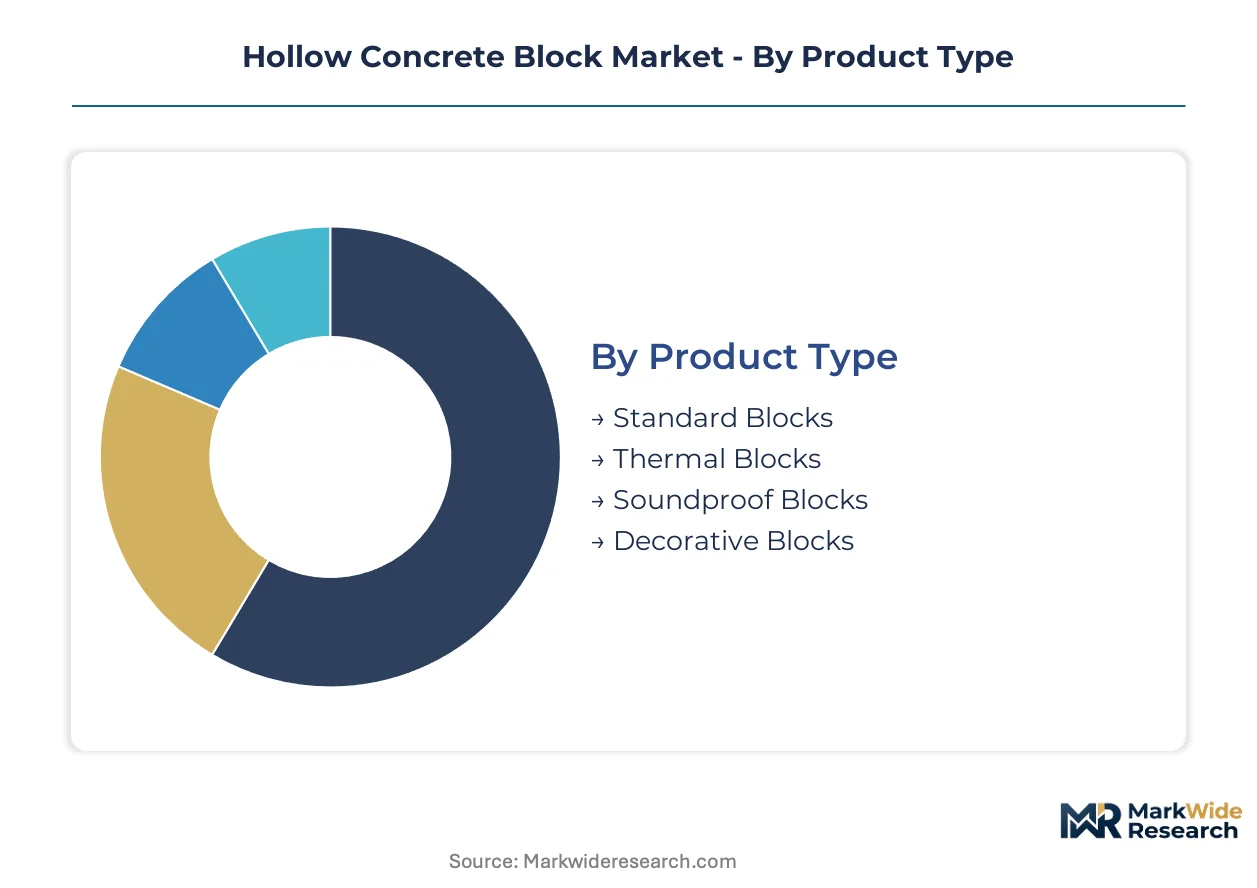
Hollow concrete block segmentation reveals how product specifications, manufacturing methods, and end-use requirements create distinct supply tiers. Each category shapes procurement patterns, pricing bands, and regulatory compliance obligations across construction value chains.
Product Type:
Domestic demand concentrates on thermally efficient variants, while export volumes favor standardized load-bearing units for infrastructure.
- Thermal Blocks:Void-optimized designs with expanded polystyrene or mineral wool inserts improve thermal resistance values for energy code compliance in residential envelopes. Maharashtra and Gujarat developers specify these for green building certifications as electricity costs climb. Demand concentrates in urban housing clusters where BIS energy efficiency mandates apply.
- Standard Blocks:Conventional load-bearing units with 25-50% void ratios serve general masonry applications across cost-sensitive construction. Rural contractors in unregulated zones substitute these for fired clay brick where transport economics favor local block production. Volume leadership rests with this segment due to universal applicability across building types.
- Soundproof Blocks:Dense aggregate mixes with increased wall thickness attenuate airborne noise for commercial and institutional buildings.
- Decorative Blocks:Architectural finishes including split-face, scored, or colored surfaces command premium positioning for exposed facade applications.
Standard blocks hold the largest share; momentum sits with thermal blocks.
End Use:
Cost tier differentiation separates specification-grade projects from informal construction where price sensitivity dominates procurement.
- Residential Buildings:Multi-story apartment construction in Maharashtra and Gujarat drives machine-made block absorption for structural walls and thermal envelopes. BIS compressive strength enforcement filters out informal suppliers from permitted developments. Single-family rural housing retains clay brick preference where building codes lack enforcement.
- Infrastructure Projects:Government retaining wall mandates and flood-resilient drainage structures accelerate hollow core adoption for steel-reinforced grouting applications. Seismic-resistant specifications in high-risk zones require certified compressive strength documentation. This end use is expanding most quickly as public works budgets prioritize climate adaptation.
- Commercial Properties:Office and retail developments specify architectural-grade units with consistent dimensional tolerance for exposed finishes.
- Industrial Structures:Warehouse and manufacturing facilities prioritize load-bearing capacity and fire resistance over aesthetic considerations.
Residential buildings command volume leadership; infrastructure projects are gaining share fastest.
Manufacturing Method:
Volume concentration favors automated production, while margin capture requires vibrated cast or specialized lightweight processes.
- Machine-Made:Automated pressing and vibration systems deliver consistent dimensional tolerance for certified supply chains serving large developers. UltraTech Cement and similar integrated producers deploy captive cement-to-block pipelines across western India. Quality testing protocols satisfy BIS certification requirements for permitted construction.
- Vibrated Cast:Pouring self-compacting concrete into molds produces premium architectural blocks with exposed finish quality eliminating surface honeycombing. High-rise residential developers in urban India specify these for aesthetic wall applications. This method occupies the highest margin tier despite lower throughput.
- Hand-Made:Labor-intensive production persists in rural supply zones outside formal building code enforcement.
- Lightweight:Expanded clay or shale aggregates reduce unit weight for high-rise construction and seismic zones.
Machine-made dominates volume; vibrated cast leads margin capture.
Application:
Customer type bifurcation separates structural load-bearing from non-structural partition applications with divergent certification requirements.
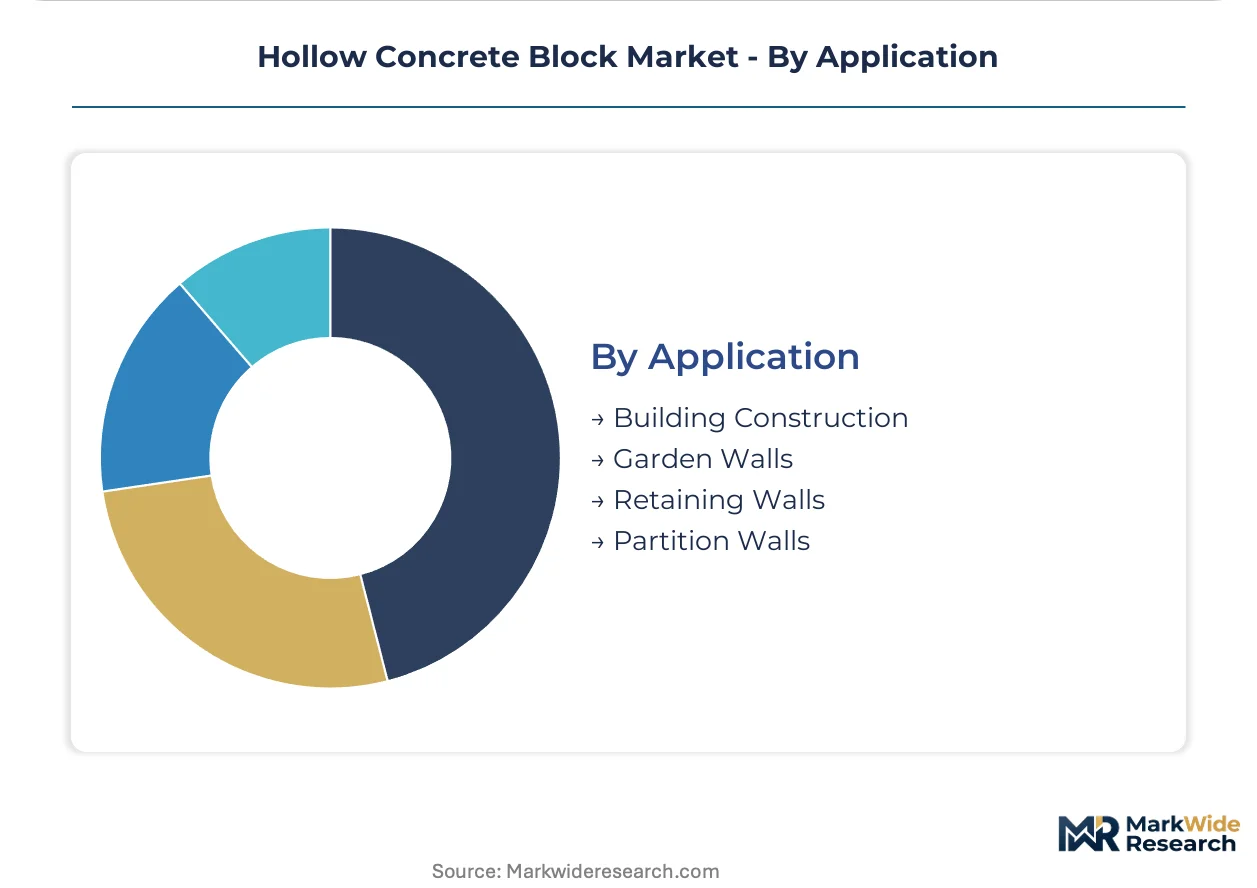
- Building Construction:Structural walls, foundations, and envelope assemblies constitute the core demand driver across all geographies. Load-bearing specifications require compressive strength certification under BIS, CE marking, or local equivalents. Procurement consolidation around certified suppliers favors machine-made producers with laboratory testing capabilities.
- Retaining Walls:Hollow core designs allow steel reinforcement grouting for seismic-resistant infrastructure in flood-prone and hillside developments. Government prioritization of climate-resilient public works accelerates specification. This application shows the steepest expansion trajectory as adaptation spending increases.
- Partition Walls:Non-load-bearing interior divisions prioritize speed of installation and acoustic performance over structural certification.
- Garden Walls:Decorative and boundary applications tolerate lower strength grades and informal supply sources.
Building construction holds the largest share; retaining walls are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS compressive strength mandates are restructuring India's hollow concrete block supply base while CE marking requirements reshape European export protocols. Production clusters concentrate where urban housing expansion intersects with automated manufacturing investment.
India
Maharashtra and Gujarat urban housing clusters absorb machine-made thermal blocks for multi-story residential construction. BIS tightened compressive strength norms filter informal suppliers from permitted developments. Mumbai and Ahmedabad production zones expand captive cement-to-block pipeline capacity.
United States
Flood-resilient infrastructure spending accelerates hollow core adoption for steel-reinforced retaining walls. EPA National Ambient Air Quality Standards constrain curing emissions from block manufacturing plants. Texas and Florida construction corridors concentrate automated production serving coastal climate adaptation projects.
Germany
Energy performance declarations for residential permits intensify thermal block specification. CE marking under the Construction Products Regulation mandates third-party dimensional tolerance verification. Bavaria and North Rhine-Westphalia automated plants supply consistent tolerance units across Central European building codes.
Mexico
Informal construction zones retain clay brick substitution pressure outside urban code enforcement zones. Latin American infrastructure bids standardize hollow core designs for seismic-resistant specifications. Mexico City Metro and Nuevo León production bases serve cross-border supply chains into US Southwest construction markets.
United Arab Emirates
High-rise commercial developments specify architectural-grade blocks with exposed finish requirements. Dubai and Abu Dhabi building codes enforce thermal performance standards for envelope assemblies. Local production clusters integrate with Saudi Arabian cement supply networks for Gulf Cooperation Council project bids.
Hollow Concrete Block Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cement-to-block pipeline control separating scale players from regional fabricators. Automated quality testing capabilities and captive raw material sourcing define the upper tier. Three archetypes populate the landscape: integrated cement-block producers, automated machinery specialists, and regional vibrated-cast operators. Competitive moves concentrate on backward integration into cement sourcing and certification-driven capacity expansion.
Among integrated cement-to-block producers, UltraTech Cement Ltd. anchors western India supply chains through Maharashtra and Gujarat production clusters. Heidelberg Materials exemplifies European automated plant deployment with CE marking compliance infrastructure. CEMEX S.A.B. de C.V. occupies a position across Latin American infrastructure bidding networks. These three represent the scale-tier archetype where captive material sourcing meets regulatory certification requirements.
| Leading Market Players |
|---|
| UltraTech Cement Ltd. |
| Heidelberg Materials |
| CEMEX S.A.B. de C.V. |
| Acme Brick Company |
| Wienerberger |
| CRH plc |
| Boral Limited |
| General Shale |
| Holcim |
| Others |
Supply Flow & Price Mechanics
Machine-made capacity utilization above 85% in Maharashtra and Gujarat production clusters compresses price floors for standardized blocks while elevating premiums for vibrated-cast architectural grades. Scale economies at integrated cement-block producers like UltraTech Cement anchor western India supply chains, forcing smaller vibrated-cast operators toward exposed-finish positioning to escape margin compression.
Pricing Analysis
Geographic price spreads between machine-made standard blocks in rural Gujarat and vibrated-cast architectural units in Mumbai exceed 40% on a per-unit basis. Pricing stratifies across premium, standard, and economy tiers defined by BIS certification grade, dimensional tolerance, and captive cement sourcing. Cost compression in standard blocks is intensifying because Portland cement input volatility and monsoon logistics disruptions squeeze informal producers. Rural contractors in unregulated zones exhibit highest price sensitivity, while high-rise residential developers in urban Maharashtra demonstrate lowest sensitivity for certified thermal blocks with energy code compliance documentation.
Supply Chain Analysis
Just-in-time delivery preferences dominate among large residential developers in Maharashtra and Gujarat, while infrastructure contractors maintain strategic stockpiles of certified load-bearing units for retaining wall projects. Supply concentrates in India, Germany, and Mexico as automated production hubs serving distinct regulatory zones. Raw material dependencies rest on Portland cement clinker, graded aggregates, and chemical admixtures for self-compacting mixes. Single-source vulnerability in western India monsoon logistics threatens delivery reliability during peak construction windows. Distribution runs through direct developer contracts for machine-made volumes and regional masonry-yard networks for informal vibrated-cast supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where BIS compressive strength certification creates regulatory entrenchment that informal producers cannot easily replicate. Switching costs for large developers rise as automated quality testing and documented carbon footprinting become procurement mandates.
For Market Incumbents: Consolidate around captive cement-to-block pipeline expansion in Maharashtra and Gujarat to deepen cost advantages against emerging regional fabricators. Acquire vibrated-cast specialists in urban India to capture architectural-grade premiums before self-compacting concrete technology proliferates. CE marking compliance infrastructure represents a priority certification investment for European export positioning.
For New Entrants and Emerging Players: Differentiate on carbon-disclosure alignment by securing lifecycle-assessed block chemistry ahead of embodied carbon tracking rule enforcement. Target infrastructure retaining wall applications in flood-prone Indian states where certified compressive strength documentation filters out informal competition. Pursue joint-venture partnerships with existing cement producers to shortcut raw material sourcing barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cement-block producers with long-term offtake agreements from Maharashtra and Gujarat residential developers. Five-to-ten-year viability favors automated plant operators with BIS laboratory certification and backward integration into clinker sourcing. Monitor carbon border adjustment implementation timelines as the signal to watch for sourcing footprint reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Sourcing | Captive clinker supply secures margin control against fuel price volatility and carbon border exposure. |
| BIS Certification Laboratory Investment | Automated compressive strength testing filters informal competitors from permitted construction procurement. |
| CE Marking Compliance Infrastructure | Third-party dimensional tolerance verification unlocks European Union infrastructure and residential building access. |
| Carbon Footprint Documentation Systems | Lifecycle-assessed block chemistry creates first-mover positioning as embodied carbon disclosure rules tighten. |
| Vibrated-Cast Capacity Addition | Self-compacting concrete production captures premium pricing for exposed-finish architectural applications. |
Methodological Framework
Desk research of BIS technical standards, EPA emission protocols, and CE marking directives preceded structured interviews with plant managers at automated block facilities, procurement leads at Maharashtra residential developers, and regulatory affairs specialists at integrated cement producers. Primary fieldwork combined with secondary validation from construction industry association reports, customs trade data for block machinery imports, and SEC filings from publicly traded building materials companies. Bottom-up capacity estimates across Maharashtra and Gujarat production clusters were triangulated against top-down demand projections from urban housing permit data.
Variance decomposition across product type, manufacturing method, end use, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price-band positioning. Forecast inputs incorporated BIS enforcement intensity indices for compressive strength compliance, monsoon logistics disruption frequencies, and Portland cement clinker price elasticity assumptions.
Forecasts assume regulatory continuity in India's BIS regime, Europe's Construction Products Regulation, and US EPA National Ambient Air Quality Standards; material policy shifts would require re-modeling of certification-driven procurement patterns. Revision becomes warranted when carbon border adjustment implementation crosses thresholds that recalibrate sourcing economics across integrated versus non-integrated supply footprints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
South America Industrial Flooring Market