
 North America Wood Based Panel Market | 2026-2036
North America Wood Based Panel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wood Based Panel Market Analytics
Asset-light leasing models for panel presses and finishing lines is reconfiguring capital barriers for mid-tier producers across the region. West Fraser leverages its integrated timber-to-panel network across British Columbia and the US South to sustain feedstock security. Georgia-Pacific anchors its position through scale manufacturing of oriented strand board and medium density fiberboard. Boise Cascade specializes in structural panels for commercial construction, differentiating through engineered wood certification programs.
Wood based panels are composite or engineered sheet materials manufactured from wood fibers, particles, strands, or veneers bonded with synthetic resins under heat and pressure, typically ranging from 4 by 8 feet to specialized structural dimensions. These products serve as primary substrates for load-bearing construction, furniture fabrication, and interior finish systems where dimensional stability and uniform strength properties outperform solid lumber. Oriented strand board dominates structural applications in North American residential framing due to cost-performance ratios and code acceptance. Medium density fiberboard captures margin pools in cabinetry and millwork where surface uniformity enables direct lamination and paint finishing. Plywood retains share in wet-service and exterior applications where moisture resistance and fastening strength remain critical.
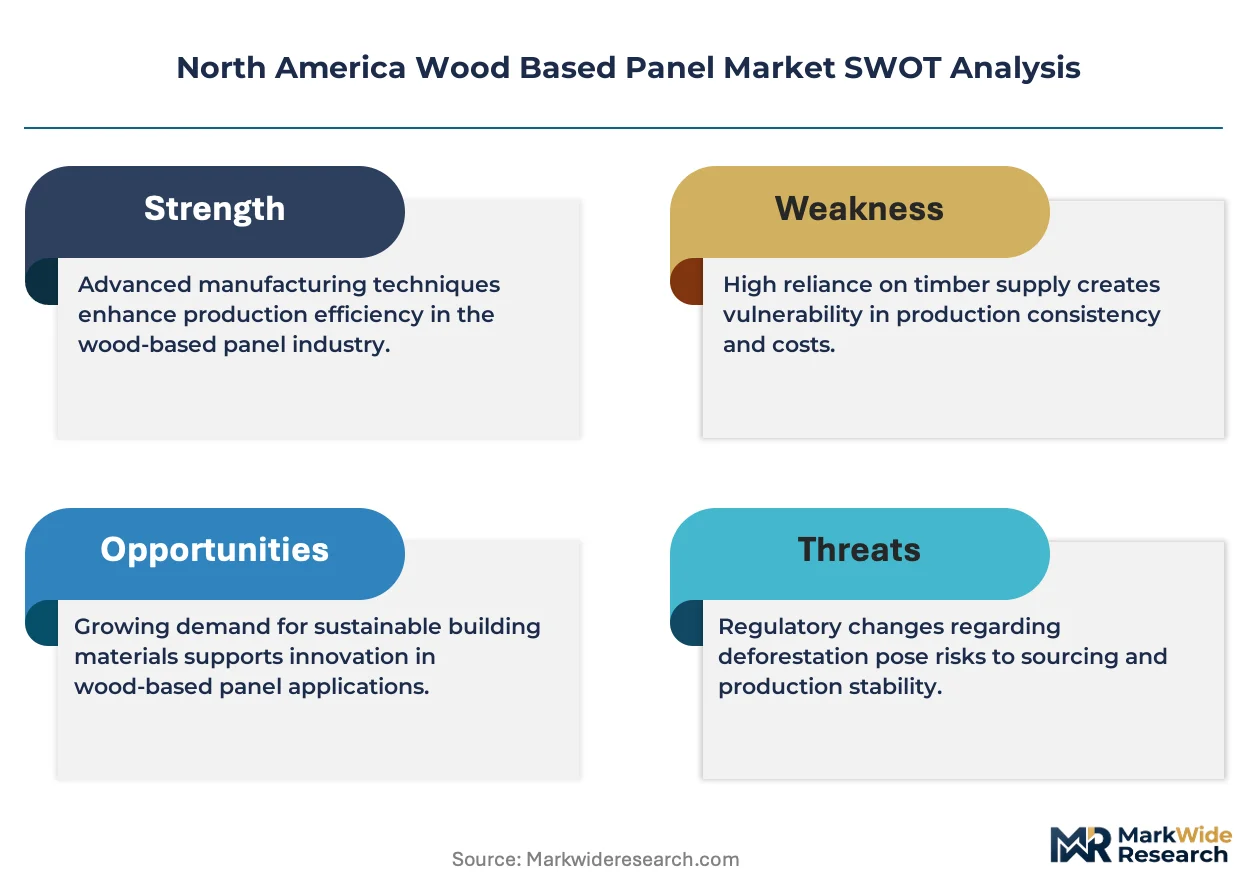
EPA TSCA Title VI limits formaldehyde emissions from composite wood products, compelling manufacturers to shift resin formulations and testing protocols. The US Department of Housing and Urban Development maintains manufactured housing construction standards that specify panel grades for structural and non-structural applications. California Air Resources Board maintains stricter emission thresholds that de facto shape national product lines. Stakeholders must monitor evolving state-level amendments to federal standards and assess resin chemistry transitions before capacity commitments lock in multi-year formulations.
Market Dynamics
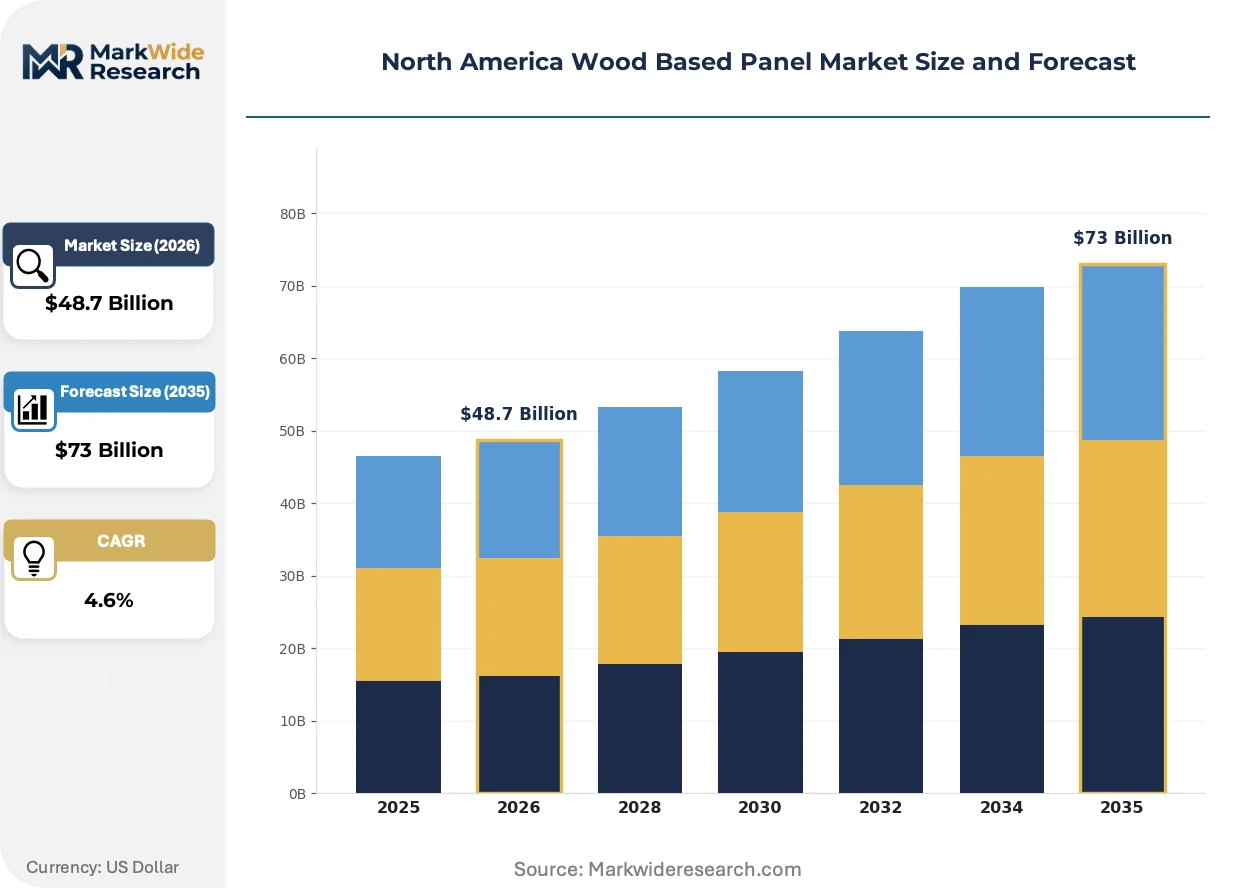
EPA TSCA Title VI formaldehyde emission limits are compressing resin formulation choices across the North America Wood Based Panel Market, forcing manufacturers to retool adhesive chemistry and testing infrastructure before multi-year capacity commitments lock in non-compliant processes.
Growth Catalysts
- Multi-family residential construction:US Southeast builders are expanding procurement of engineered structural panels for five-over-one wood-frame apartment complexes. Code acceptance for mid-rise timber construction is accelerating specification rates.
- EPA emission standard enforcement:TSCA Title VI third-party certification requirements are creating compliance barriers that favor capitalized producers with in-house testing laboratories.
- Cross-laminated timber adoption:British Columbia and US Pacific Northwest architects are specifying mass timber systems for commercial projects, pulling demand for specialty panel substrates.
Market Restraints
- Methanol price volatility:Urea-formaldehyde resin production depends on methanol feedstock tied to natural gas pricing, creating margin compression during energy market spikes.
- Southeast timber supply concentration:Softwood fiber procurement clusters in Georgia, Alabama, and Mississippi, exposing mills to weather-related harvest disruptions and hauling cost inflation.
- Steel and concrete substitution:Commercial developers in seismic zones default to steel moment frames and post-tensioned concrete for high-rise construction, capping wood panel penetration.
Strategic Opportunities
- California retrofit demand:ADU (accessory dwelling unit) mandates in Los Angeles and San Francisco metro areas are creating incremental panel demand for backyard cottage construction.
- Low-emitting bio-based adhesives:Soy-protein and lignin-based resin formulations align with CARB Phase 2 thresholds and open specification channels for pediatric healthcare furniture.
- Direct-to-builder digital platforms:E-procurement channels are disintermediating traditional two-step distribution for mid-sized regional homebuilders in Texas and Florida.
Industry Challenges
- Resin chemist talent scarcity:Formulation expertise for zero-added-formaldehyde systems concentrates at a handful of adhesive suppliers, constraining in-house R&D ramp rates.
- Continuous press reconfiguration capex: Shifting from formaldehyde-based to PMDI (polymeric methylene diphenyl diisocyanate) bonding requires press temperature and dwell-time modifications costing eight figures per line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wood Based Panel Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Particleboard, Plywood, Medium Density Fiberboard, Oriented Strand Board End User: Furniture Manufacturers, Construction, Interior Design, Packaging Application: Flooring, Wall Paneling, Cabinetry, Roof Structure Technology: Engineered Wood, Laminated Veneer Lumber, Solid Wood, Composite Wood |
| Companies Covered | Georgia-Pacific, West Fraser, Boise Cascade, Weyerhaeuser Company, Arauco, Egger, Roseburg Forest Products, Kronospan, Woodgrain Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wood Based Panel Market Evolving Landscape
Digital moisture detection systems and automated panel grading are compressing quality variance in North American production facilities. Three parallel developments are restructuring competitive capabilities.
Thermally modified fiber processing is rendering obsolete traditional kiln-drying cycles for hardwood-based MDF substrates. Cabinetry manufacturers in the US Northeast are adopting these panels at accelerating rates. The technology is compressing energy input requirements and enabling denser fiber packing without internal stress fractures.
CARB Phase 2 emission thresholds continue to de facto shape national product lines despite federal preemption debates. Manufacturers serving California must maintain dual inventory streams or upgrade all lines to the stricter standard. The compliance burden falls heaviest on particleboard producers serving the ready-to-assemble furniture segment.
Builder-direct specification platforms are consolidating purchasing power among the top fifty US homebuilders. Regional distributors in the Southeast are losing volume to centralized procurement teams at D.R. Horton and Lennar. The shift is most visible in OSB structural sheathing where price transparency has compressed traditional distributor margins.
North America Wood Based Panel Market Segmentation
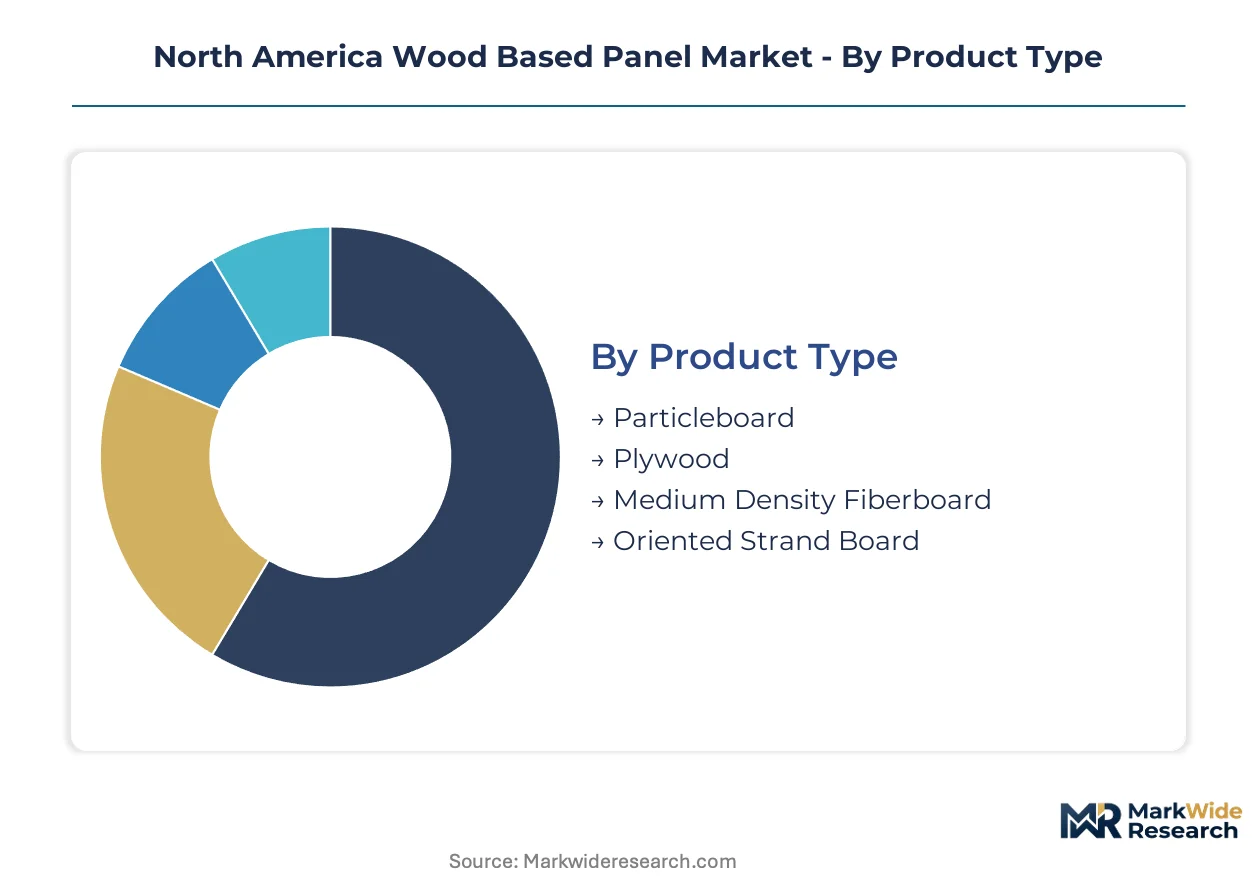
Segmentation in the North America Wood Based Panel Market reveals distinct technical specifications, compliance burdens, and service requirements that reshape procurement patterns across construction and manufacturing verticals. Each dimension carries unique aftermarket service intensity, from TSCA Title VI certification support to moisture-content monitoring during builder storage.
Product Type:
After-sales service intensity varies sharply across panel categories, with formaldehyde compliance documentation and moisture-content warranties driving post-purchase engagement for structural grades.
- Oriented Strand Board:Manufactured from cross-oriented wood strands bonded with waterproof phenol-formaldehyde or isocyanate resins under controlled heat and pressure, yielding dimensional stability superior to plywood at equivalent thickness. US Southeast builders specify OSB for wall and roof sheathing in tract housing developments where code-minimum performance and cost compression dominate procurement decisions. The segment demands intensive builder education on edge-sealing practices and moisture exposure limits during construction delays.
- Medium Density Fiberboard:Composed of refined wood fibers distributed in a uniform mat and pressed to densities between 600-800 kg/m³, delivering surface smoothness that accepts direct paint or thermofoil lamination without intermediate sanding. Cabinetry manufacturers in the US Northeast and California specify MDF for painted door fronts and drawer boxes where surface telegraphing of substrate defects is unacceptable. After-sales support concentrates on moisture-content management during seasonal storage and VOC emission documentation for LEED project submissions.
- Plywood:Cross-laminated veneer construction with odd-numbered plies balanced around a central core, providing bidirectional strength and fastener-holding capacity that OSB cannot replicate. Exterior grades retain specification in hurricane-prone Florida and Gulf Coast markets where building codes mandate enhanced fastening resistance.
- Particleboard:Flake-and-chip mat formation bonded with urea-formaldehyde resins, offering the lowest cost substrate for ready-to-assemble furniture and laminate flooring underlayment. CARB Phase 2 compliance documentation dominates post-sale customer service requirements.
By volume, Oriented Strand Board leads residential construction procurement. By growth pace, Medium Density Fiberboard is expanding most quickly in premium cabinetry applications.
End User:
Cost tier stratification separates specification-grade buyers from commodity purchasers, with compliance documentation and technical support bundled into premium pricing for regulated segments.
- Construction:Multi-family residential developers and commercial general contractors purchasing structural sheathing, subflooring, and concrete forming panels in high volumes with stringent jobsite delivery windows. Demand concentrates in Texas and Florida metro corridors where five-over-one wood-frame construction is displacing steel-stud mid-rise structures.
- Furniture Manufacturers:Millwork shops and casegoods producers sourcing laminated substrates for cabinetry, closet systems, and hospitality fixtures. California-based manufacturers face the strictest emission documentation requirements, forcing dual inventory strategies or universal CARB Phase 2 compliance upgrades.
- Interior Design:Specification-driven procurement of decorative veneered panels, thermally treated surfaces, and custom dimensions for commercial and high-end residential fit-outs. Project-based purchasing patterns demand flexible minimum order quantities and rapid sample turnaround.
- Packaging:Industrial crating and pallet manufacturers consuming lower-grade OSB and plywood where structural performance is secondary to cost and availability. Minimal after-sales service requirements characterize this price-sensitive tier.
Construction commands the largest volume share. Furniture Manufacturers are gaining share fastest as millwork reshoring accelerates from Asian supply chains.
Application:
Geographic concentration of demand tracks housing permit issuance and commercial construction spending, with distinct regional preferences for panel grades and thicknesses.
- Wall Paneling:Interior finish-grade MDF and decorative plywood specified for feature walls, wainscoting, and commercial lobby installations. Moisture-resistant MDF variants are displacing traditional gypsum in high-end residential renovations across Pacific Northwest markets.
- Cabinetry:Premium MDF and particleboard substrates for kitchen, bath, and closet systems where surface quality and machining precision determine fabrication yields. Texas and Arizona production facilities are expanding to serve Sun Belt population migration.
- Roof Structure:Structural OSB and plywood sheathing specified by engineered truss manufacturers and site builders for pitched and flat roof assemblies. Hurricane-prone Gulf Coast jurisdictions maintain plywood preference for enhanced uplift resistance.
- Flooring:Underlayment-grade OSB and high-density fiberboard for laminate and engineered hardwood installations. Moisture-content sensitivity drives regional specification differences between humid Southeast and arid Southwest markets.
Wall Paneling leads by current volume. Cabinetry is climbing the fastest as accessory dwelling unit construction accelerates in California metro areas.
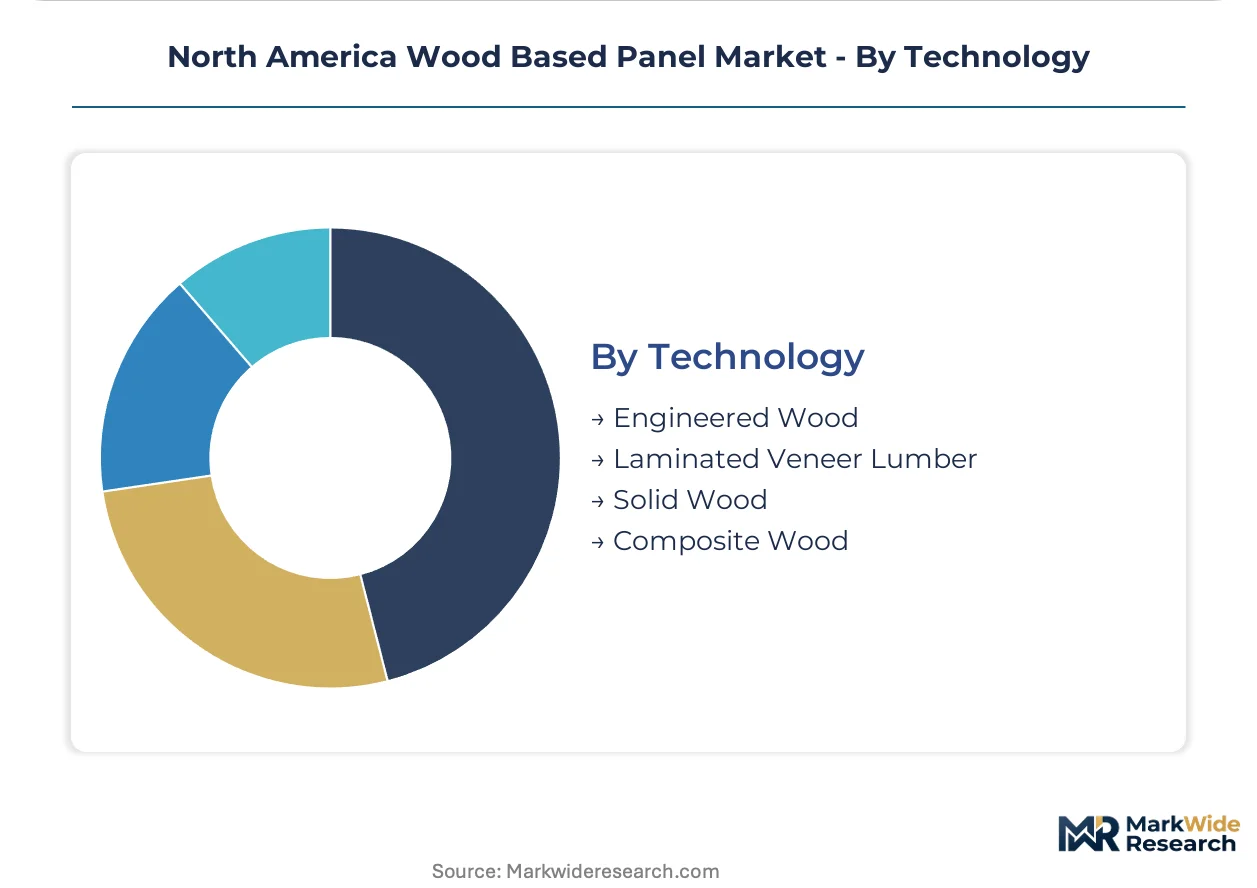
Technology:
Margin structure diverges across manufacturing approaches, with capital-intensive continuous pressing and resin formulation complexity separating profitable producers from commodity competitors.
- Engineered Wood:Broad category encompassing OSB, LVL, and I-joist systems where wood fiber orientation and adhesive bonding create structural performance exceeding solid lumber of equivalent dimensions. US South manufacturing clusters dominate capacity.
- Composite Wood:Particleboard and MDF manufactured from refined or fragmented wood fibers bonded with synthetic resins, representing the highest-volume production technology with the thinnest margins and strictest emission compliance burdens.
- Laminated Veneer Lumber:Parallel-laminated veneer construction for structural beams and headers, commanding premium pricing in commercial mass timber applications. British Columbia and Pacific Northwest production serves cross-laminated timber integrators.
- Solid Wood:Traditional plywood and lumber-core panels retaining specification in wet-service and exterior applications where fastening strength and moisture resistance cannot be replicated by reconstituted products.
Composite Wood dominates by production volume. Laminated Veneer Lumber is gaining share fastest as mass timber commercial construction expands beyond Pacific Northwest early-adopter markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a modest trade surplus in wood based panels with Canada and Mexico under USMCA provisions, though cross-border resin chemistry harmonization remains incomplete. Regional demand clusters track timber supply corridors and construction permit issuance patterns.
United States
Five-over-one wood-frame apartment construction in Texas and Florida metro corridors is pulling structural OSB volumes from Georgia and Alabama mills. EPA TSCA Title VI third-party certification requirements are compressing the supplier base toward capitalized producers with in-house testing laboratories. The US Southeast manufacturing cluster—spanning Georgia, Alabama, and Mississippi—hosts the densest concentration of continuous press capacity serving domestic and export markets.
Canada
Cross-laminated timber commercial projects in British Columbia and Ontario are generating specialty panel substrate demand beyond traditional construction grades. Health Canada maintains aligned emission standards with EPA TSCA Title VI, reducing dual-certification burdens for integrated North American producers. British Columbia's integrated timber-to-panel networks leverage coastal and interior softwood supply basins to serve Pacific Northwest US and Asian export destinations.
Mexico
Industrial furniture manufacturing in Guanajuato and Jalisco is expanding MDF procurement for cabinetry and millwork serving US residential renovation markets. Mexico's federal environmental regulator enforces composite wood emission standards that generally track California Air Resources Board thresholds. The Bajío Region manufacturing corridor is attracting panel distribution investments to serve central Mexican construction growth.
Pacific Northwest
Mass timber architecture adoption in Seattle and Portland metro areas is accelerating specification of engineered panel systems for commercial and institutional buildings. State-level procurement preferences for low-carbon building materials in Washington and Oregon are reshaping resin chemistry requirements. The Columbia River timber basin and I-5 manufacturing corridor sustain integrated supply chains for specialty structural products.
North America Wood Based Panel Market Competitive Landscape
On the supply side, the industry is consolidating around integrated timber-to-panel networks and specialized regional fabricators with distinct resin formulation capabilities. Capital requirements for continuous press reconfiguration and TSCA Title VI compliance testing are elevating barriers for mid-tier entrants. Two strategic archetypes dominate: vertically integrated forest products conglomerates controlling fiber supply from stump to finished panel, and technology-focused specialists commanding premium positioning through emission-certified product lines. Capacity expansion and backward integration into adhesive chemistry represent the dominant competitive vectors.
Within the integrated conglomerate tier, Georgia-Pacific and West Fraser exemplify scale-driven positioning through multi-state manufacturing footprints and captive timber supply arrangements. Boise Cascade occupies a specialist position in structural panel distribution and engineered wood certification programs. These three entities anchor the competitive structure by representing divergent strategic postures—chemical integration, fiber security, and specification-grade distribution—rather than competing head-to-head on identical product lines.
| Leading Market Players |
|---|
| Georgia-Pacific |
| West Fraser |
| Boise Cascade |
| Weyerhaeuser Company |
| Arauco |
| Egger |
| Roseburg Forest Products |
| Kronospan |
| Woodgrain Inc. |
| Others |
Value Network & Pricing Analysis
Methanol price volatility tied to natural gas markets determines both margin compression in resin-dependent tiers and the geographic clustering of manufacturing capacity near petrochemical supply basins. This dual dependency forces producers to balance spot-market exposure against long-term offtake commitments while navigating EPA compliance cost differentials across state boundaries.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where volume scale and CARB Phase 2 certification grade drive price differentiation. Three-tier pricing structure across premium emission-certified, standard TSCA Title VI compliant, and economy grades separates furniture manufacturers from commodity construction purchasers. Pricing pressure stems from urea-formaldehyde resin cost spikes during energy market volatility. Packaging and industrial crating segments exhibit highest price sensitivity, while pediatric healthcare furniture specification channels show lowest elasticity due to mandatory low-emitting adhesive requirements.
Supply Chain Analysis
Extended payment terms from Southeast US distributors to Georgia and Alabama mills are compressing working capital cycles and accelerating supply-chain finance facility adoption among mid-tier producers. Fiber procurement draws from British Columbia, US Southeast, and Pacific Northwest timber basins. Urea-formaldehyde resin, isocyanate adhesives, and phenolic bonding agents constitute critical input dependencies. Single-source vulnerability concentrates in methanol feedstock channels tied to Gulf Coast petrochemical infrastructure. Distribution runs through builder-direct specification platforms consolidating purchasing power among top fifty US homebuilders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized resin formulation expertise concentrates at a handful of adhesive suppliers, constraining in-house R&D ramp rates and elevating acquisition premiums for zero-added-formaldehyde capability. This scarcity dynamic favors early movers in bio-based adhesive chemistry.
For Market Incumbents: Insulate fiber security through captive timber arrangements in British Columbia and US South basins while accelerating PMDI bonding line conversions ahead of state-level emission standard amendments. Defend against steel and concrete substitution in seismic zones by expanding engineered wood certification programs for mass timber commercial applications. For New Entrants and Emerging Players: Build out low-emitting bio-based adhesive production capacity serving California ADU retrofit demand and pediatric healthcare furniture channels where specification premiums offset capital intensity. Target Texas and Florida five-over-one apartment construction corridors with moisture-resistant MDF variants. Establish direct-to-builder digital procurement platforms disintermediating traditional Southeast distributors. For Investors and Strategic Acquirers: EPA TSCA Title VI third-party certification mandates reshape the acquisition landscape toward capitalized producers with in-house testing laboratories and compliant resin chemistry portfolios. Long-term viability centers on backward integration into adhesive formulation or captive fiber supply. Monitor state-level amendments to federal emission standards as the primary inflection signal for capacity stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Captive resin formulation secures EPA compliance margins against methanol price spikes. |
| Continuous Press Reconfiguration | PMDI bonding line upgrades lock in CARB Phase 2 capacity ahead of state mandates. |
| Direct-to-Builder Platform Launch | E-procurement channels capture margin from consolidating US homebuilder purchasing power. |
| Zero-Added-Formaldehyde Certification Investment | Pediatric healthcare and California ADU channels command specification premiums. |
| Timber Supply Basin Expansion | British Columbia and US South fiber security insulates against harvest disruption risk. |
Research Methodology
Desk research of trade association production data, EPA regulatory filings, and customs import records preceded structured interviews with plant managers, resin R&D directors, homebuilder procurement officers, and distribution channel partners. Primary fieldwork with continuous press operators and TSCA Title VI certification auditors combined with secondary validation against SEC filings from integrated forest products conglomerates. Bottom-up capacity modeling and top-down construction spending triangulation anchored volume estimates.
Assumptions held housing permit issuance patterns and natural gas price corridors fixed while varying resin chemistry transition timelines and state-level emission standard adoption rates across the analysis window. Segmentation dimensions encompassed product type, end-use vertical, application, and manufacturing technology tier. CAGRs derived from regression against historical panel consumption intensity per housing unit and commercial square footage. Mass timber adoption curves and ADU permitting velocity served as industry-specific demand inputs.
Sensitivities concentrate around methanol price volatility, hurricane-related timber harvest disruptions, and steel substitution acceleration in seismic zones. Forecasts reflect documented assumptions regarding regulatory harmonization and fiber supply stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Spray Foam Market