
 Blanket Insulation Market | 2026-2036
Blanket Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Blanket Insulation Market Analytics
Aftermarket service revenue for insulation removal and replacement is narrowing as building codes tighten replacement cycles. Owens Corning leverages its fiberglass manufacturing scale across North American distribution networks. Johns Manville sustains technical leadership in high-temperature mineral wool formulations for industrial applications. Rockwool International anchors its competitive position through stone wool specialization in fire-resistant building envelopes.
Blanket insulation consists of flexible, pre-formed sheets of fibrous or cellular materials manufactured in rolls or batts, typically ranging from one to eight inches in thickness, designed to reduce thermal transfer in building cavities and mechanical systems. The product serves primarily to limit conductive heat flow, control condensation, and attenuate sound transmission in residential, commercial, and industrial envelopes. Fiberglass retains the largest installed base due to cost efficiency and established contractor familiarity, while mineral wool commands premium positioning in fire-rated assemblies where ASTM E136 noncombustibility certification determines specification. Residential application volumes dominate current consumption patterns, though HVAC retrofit demand is expanding fastest as ductwork insulation requirements intensify under updated energy codes.
EPA ENERGY STAR certification requirements and the EU Green Deal building renovation mandates are elevating minimum thermal performance thresholds across both new construction and retrofit activity. OSHA permissible exposure limits for synthetic vitreous fibers and REACH substance restrictions on certain binder chemistries are reshaping manufacturing process investments and product formulation strategies. Stakeholders must monitor evolving code harmonization between federal efficiency standards and state-level stretch codes that increasingly exceed baseline requirements.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing replacement cycles and elevating thermal performance minimums across Western Europe's aging residential stock, forcing manufacturers to recalibrate formulation strategies around REACH-compliant binders.
Growth Catalysts
- EU Green Deal renovation targets:Mandatory energy performance upgrades for existing structures in Germany and France are accelerating fiberglass and mineral wool retrofit volumes.
- HVAC ductwork codes:Updated energy efficiency standards for mechanical systems are expanding demand for flexible blanket insulation in commercial and industrial applications.
- Fire-rated assembly specifications:ASTM E136 noncombustibility certification requirements are driving premium positioning for stone wool in building envelope applications.
Market Restraints
- Binder chemistry restrictions:REACH substance limitations on formaldehyde-based and phenolic binders are forcing costly manufacturing process investments and supply chain requalification.
- Raw material concentration:High-purity silica sand and basalt feedstock supply concentrates in select extraction regions, exposing producers to input cost volatility and logistics constraints.
- Synthetic vitreous fiber exposure limits:OSHA permissible exposure standards are elevating installation labor costs and contractor training requirements.
Strategic Opportunities
- Deep energy retrofit programs:Residential renovation subsidies in France and Germany offer volume expansion pathways for contractors specializing in exterior wall and attic insulation.
- Industrial high-temperature applications:Process heat recovery systems and power generation infrastructure present underserved demand for mineral wool formulations rated above 1,000°C.
- Prefab building envelope integration:Offsite construction manufacturers are specifying pre-cut blanket insulation kits to accelerate assembly timelines and reduce field waste.
Industry Challenges
- Certification timeline compression:Harmonization gaps between federal efficiency standards and state-level stretch codes are forcing manufacturers to maintain multiple product variants and testing protocols.
- Installation labor scarcity:Skilled insulator availability constraints in major metropolitan construction markets are elongating project schedules and elevating wage pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blanket Insulation Market |
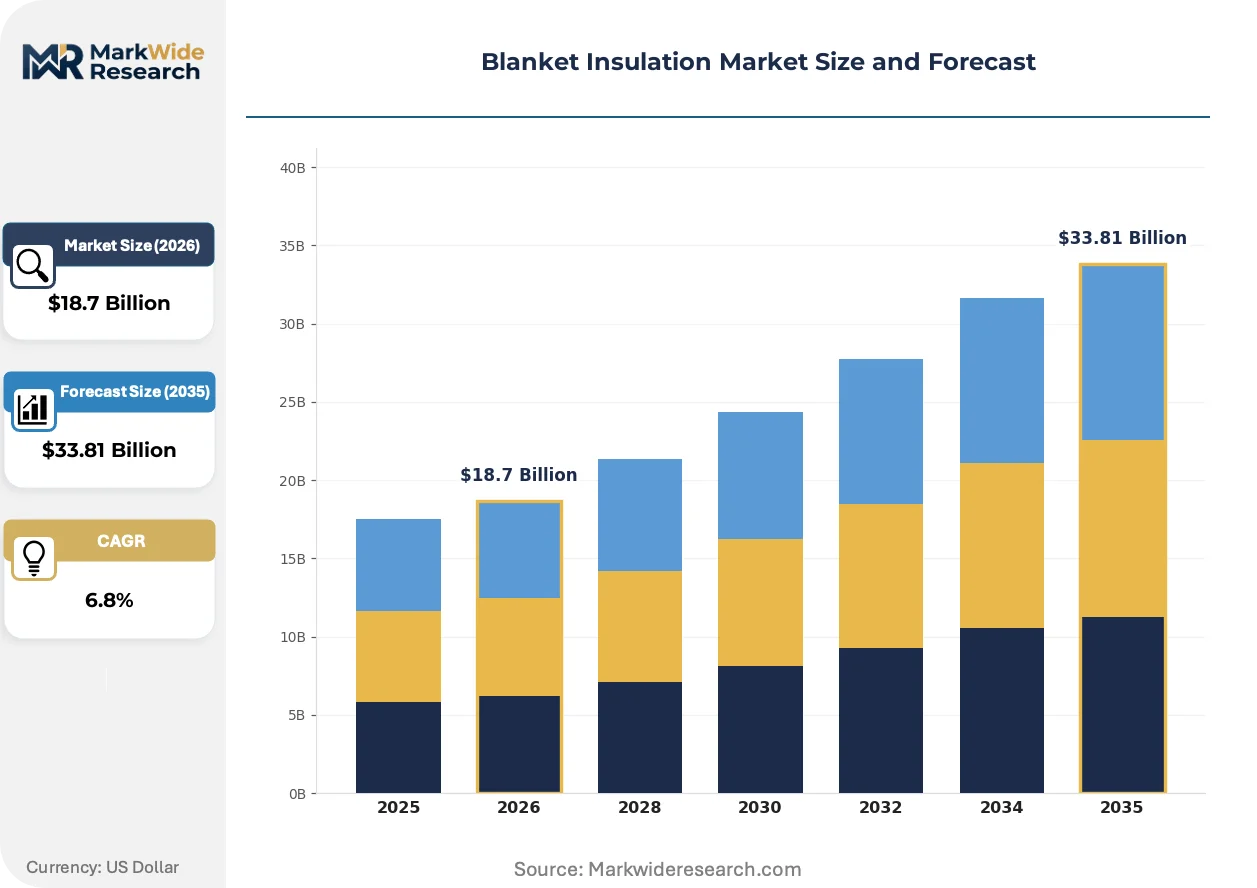
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Mineral Wool, Cotton, Foam Application: Residential, Commercial, Industrial, HVAC Thickness: 1-inch, 3-inch, 6-inch, 8-inch End User: Contractors, Builders, Homeowners, Engineers |
| Companies Covered | Owens Corning, Johns Manville, Rockwool International, Knauf Insulation, Armacell, Saint-Gobain, BASF, Kingspan Group, Refmon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blanket Insulation Market Evolving Landscape
Aerogel-integrated composites and bio-based binder chemistries are disrupting conventional fiberglass and mineral wool formulations, while digital building energy modeling is compressing specification cycles and elevating performance transparency requirements.
Bio-based polyurethane and plant-derived binder systems are virtualizing the synthetic chemistry foundation of traditional blanket insulation. Sustainable construction certifiers and institutional developers in Scandinavia are specifying these formulations at accelerating rates. The technology is virtualizing the competitive moat around petrochemical-dependent incumbents by enabling carbon-accounting advantages in public procurement.
EPA ENERGY STAR certification requirements and the EU Green Deal building renovation mandates are elevating minimum thermal performance thresholds across both new construction and retrofit activity. Manufacturers must now maintain dual compliance pathways for transatlantic product portfolios. Residential retrofit contractors in Germany and France are experiencing the steepest compliance cost increases as documentation requirements intensify.
Building energy modeling software integration is compressing specification cycles from months to weeks. Architects and energy consultants now simulate thermal performance in real-time, displacing traditional manufacturer-driven product selection. This behavioral shift concentrates most visibly in commercial new construction markets where LEED and BREEAM certification deadlines dominate procurement timelines.
Blanket Insulation Market Segmentation
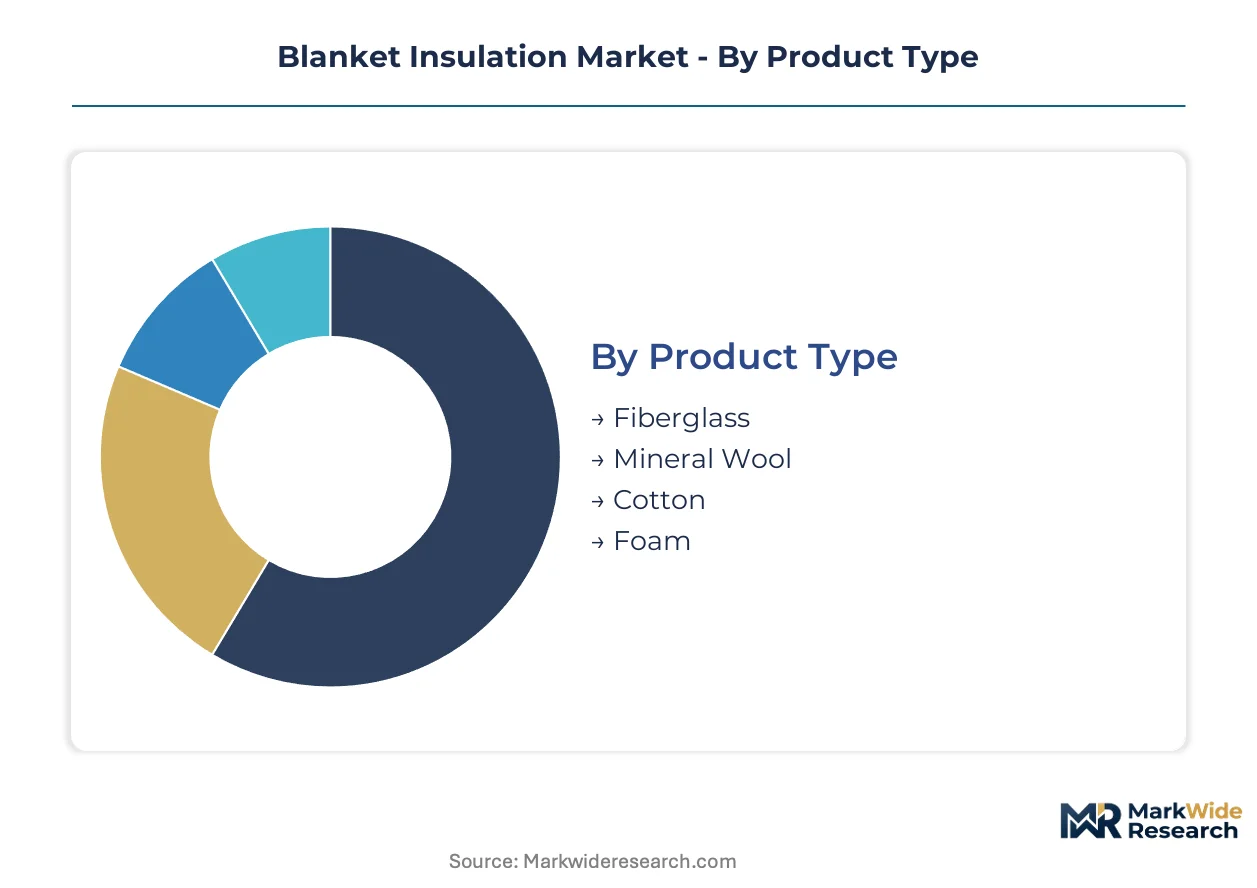
Segmentation in blanket insulation reveals divergent margin profiles and service intensity requirements across material chemistries and installation contexts. Product type determines manufacturing capital intensity, while application segment governs specification complexity and contractor training depth.
Product Type:
After-sales service intensity varies sharply across material platforms, with mineral wool demanding specialized fire-certification support and fiberglass relying on volume logistics.
- Fiberglass:Composed of spun glass fibers bound with phenolic or bio-based resins, this material delivers cost-efficient thermal resistance in standard R-value configurations. Demand concentrates in German and French residential retrofit programs where contractor familiarity and distribution density accelerate installation velocity.
- Mineral Wool:Manufactured from molten basalt or slag fibers, this noncombustible formulation achieves ASTM E136 certification for fire-rated assemblies. Specification intensity is highest in commercial building envelopes across Western Europe where EU Green Deal renovation mandates tighten safety-performance thresholds.
- Cotton:Recycled denim and textile fiber formulations offer bio-based alternatives with lower embodied carbon profiles. Scandinavian sustainable construction certifiers are driving specification in institutional projects.
- Foam:Flexible polyurethane and polyisocyanurate sheets provide higher R-value per inch for space-constrained cavities. HVAC ductwork applications in commercial mechanical retrofits represent the primary demand concentration.
By volume, fiberglass leads. By growth pace, mineral wool is ahead.
Application:
Application segment dictates specification cycle length and energy-code compliance burden, with industrial and HVAC retrofit carrying the steepest documentation requirements.
- Residential:Attic, wall cavity, and basement installations dominate current consumption, driven by France's MaPrimeRénov and Germany's BEG subsidy programs accelerating exterior envelope retrofits.
- Commercial:Office, retail, and institutional buildings require fire-rated assembly documentation and BREEAM certification alignment. Specification cycles compress as digital energy modeling displaces traditional manufacturer-driven selection.
- Industrial:Process equipment, piping, and vessel insulation demand mineral wool formulations rated above 1,000°C for power generation and heat recovery infrastructure.
- HVAC:Flexible duct liner and external wrap applications are expanding under updated energy efficiency standards for mechanical systems in commercial buildings.
Residential captures the largest installed base. HVAC retrofit is climbing the fastest.
Thickness:
Thickness selection correlates directly with cavity depth constraints and thermal performance targets, with thicker configurations commanding premium positioning in deep energy retrofits.
- 1-inch:Slim-profile batts serve confined spaces and HVAC ductwork where clearance limits dominate specification.
- 3-inch:Standard wall cavity configurations balance R-value achievement with framing compatibility in residential construction.
- 6-inch:Attic and roof deck applications in cold climates achieve higher thermal resistance without multi-layer installation labor.
- 8-inch:Deep energy retrofit specifications in Germany's aging housing stock maximize thermal performance per installation pass.
3-inch configurations dominate unit volume. 8-inch specifications are gaining share fastest in subsidy-driven renovation markets.
End User:
End-user type determines procurement channel structure and technical support intensity, with engineers and contractors requiring divergent specification resources.
- Contractors:Retrofit installation specialists in France and Germany source through distributor networks with just-in-time logistics for renovation timeline compression.
- Builders:New construction developers prioritize cost efficiency and code-minimum compliance in high-volume residential projects.
- Homeowners:Direct procurement remains limited to DIY attic retrofits, with most residential volume flowing through contractor intermediaries.
- Engineers:Mechanical and energy consultants specify HVAC and industrial applications, driving mineral wool demand through performance-based selection criteria.
Contractors move the highest volume. Engineers are expanding their specification influence fastest as energy modeling penetrates commercial procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand and basalt feedstock extraction concentrates in select geological formations, exposing manufacturers to regional input cost volatility. Germany, France, and the United States anchor installed manufacturing capacity for fiberglass and mineral wool formulations. Distribution networks radiate from these hubs into renovation-intensive markets where EU Green Deal mandates and state-level stretch codes tighten compliance timelines.
Germany
Residential retrofit contractors source fiberglass batts through dense distributor networks serving renovation timelines compressed by BEG subsidy deadlines. The Federal Office for Economic Affairs and Export Control administers building energy grant programs that accelerate exterior wall and attic insulation volumes. Industrial clusters in North Rhine-Westphalia concentrate mineral wool production for fire-rated commercial assemblies.
France
MaPrimeRénov subsidies channel homeowner demand toward contractor-installed blanket insulation in aging urban housing stock. ANSM oversees chemical safety compliance for binder formulations used in residential applications. The Lyon-Grenoble corridor hosts technical centers where energy consultants model thermal performance for commercial envelope specifications.
United States
OSHA permissible exposure limits for synthetic vitreous fibers elevate contractor training costs and installation labor scarcity in major metropolitan construction markets. EPA ENERGY STAR certification requirements tighten thermal performance thresholds for new residential construction. Manufacturing scale concentrates in the Ohio River Valley where fiberglass production serves North American distribution networks.
United Kingdom
BREEAM certification alignment drives specification complexity in commercial new construction where digital energy modeling compresses procurement cycles. The Building Safety Regulator enforces fire performance standards that elevate mineral wool demand in high-rise residential retrofits. Greater Manchester and Birmingham metro areas concentrate contractor capacity for deep energy renovation programs.
China
Dual carbon goals and GB standards for building energy efficiency expand addressable market for thermal insulation in new urban construction. The Ministry of Ecology and Environment monitors industrial emissions from mineral wool furnace operations. Yangtze River Delta manufacturing bases supply fiberglass formulations for domestic retrofit campaigns and export markets.
Blanket Insulation Market Competitive Landscape
Scale-driven integrated producers and specialized fire-performance formulators split the market into divergent margin architectures. The vendor base organizes around manufacturing capital intensity rather than technology differentiation. Three archetypes dominate: diversified building materials conglomerates with captive mineral supply, pure-play insulation specialists with technical certification depth, and regional fabricators serving just-in-time renovation logistics. Capacity expansion and REACH-compliant binder reformulation represent the dominant competitive moves as regulatory timelines compress.
Among North American building materials conglomerates, Owens Corning and Johns Manville occupy positions defined by manufacturing scale and distribution density. Rockwool International anchors the fire-performance specialist tier through stone wool specialization. These three entities exemplify the strategic divergence between volume-driven fiberglass positioning and premium mineral wool certification depth that characterizes competitive structure in Western European and North American markets.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Rockwool International |
| Knauf Insulation |
| Armacell |
| Saint-Gobain |
| BASF |
| Kingspan Group |
| Refmon |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions on formaldehyde-based and phenolic binders compress pricing tier spreads while forcing supply chain reconfiguration toward compliant feedstock sources and certified manufacturing nodes. This regulatory chokepoint simultaneously elevates premium positioning for bio-based formulations and standardizes base-tier pricing as manufacturers absorb reformulation costs across product lines.
Pricing Analysis
EU Green Deal building renovation mandates dictate the pricing tier structure across Western European markets, stratifying offerings by certification depth and thermal performance grade. Three-tier pricing separates fire-rated mineral wool assemblies from standard fiberglass batts and economy-grade recycled cotton alternatives. Cost compression in mid-tier fiberglass intensifies because REACH-compliant binder chemistry adds 15-20% to raw material outlays. Residential retrofit contractors in Germany and France exhibit the highest price sensitivity due to compressed subsidy-driven project timelines, while industrial engineers specifying high-temperature mineral wool demonstrate minimal elasticity.
Supply Chain Analysis
Integrated fiberglass producers in the Ohio River Valley and North Rhine-Westphalia mineral wool clusters hold captive capacity for high-purity silica sand and basalt feedstock processing. Manufacturing gravity centers on Germany, the United States, and China, with Yangtze River Delta facilities serving export markets and domestic retrofit campaigns. Basalt extraction from select volcanic formations and phenolic resin supply from petrochemical hubs tether production to commodity volatility. Single-source vulnerability concentrates in high-purity silica sand deposits. Distribution runs through regional building materials distributors with just-in-time logistics for renovation timeline compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
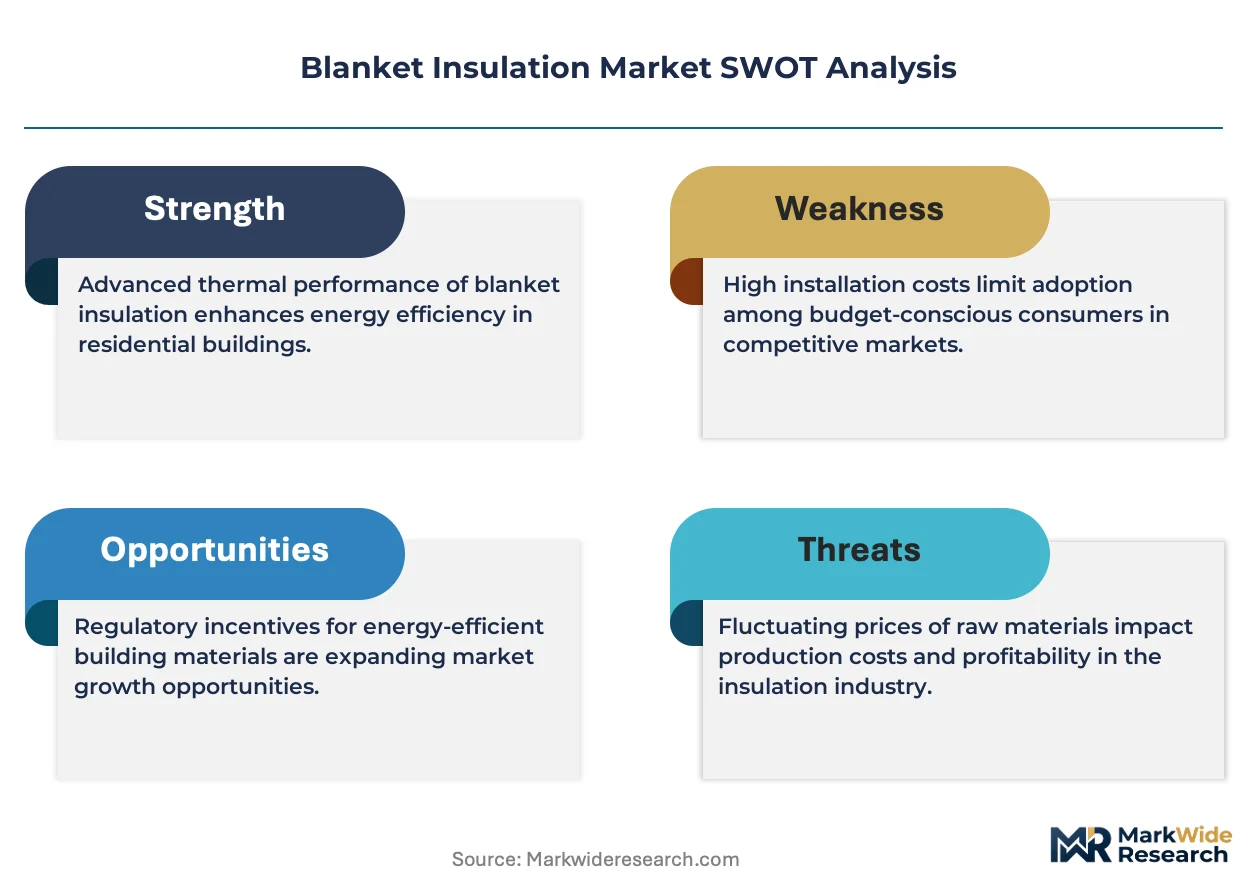
Certified installer networks represent the scarcest capability layer in this market, constraining volume capture even where manufacturing capacity and subsidy funding are abundant. This bottleneck separates manufacturers who control contractor certification pathways from those competing on price alone.
For Market Incumbents: Build certification moats around REACH-compliant binder formulations and ASTM E136 fire-rating depth. Secure backward integration into basalt feedstock extraction to insulate margin structures from raw material volatility. Expand captive installer training capacity in German and French metropolitan markets where labor scarcity elongates project schedules and elevates wage pressure. For New Entrants and Emerging Players: China's industrial high-temperature applications offer the most penetrable white-space target, with mineral wool demand for process heat recovery systems outpacing established supply capacity. Target HVAC retrofit specifications in commercial mechanical systems where updated energy codes expand addressable volume. Enter through bio-based binder differentiation to capture Scandinavian sustainable construction procurement and public-sector carbon-accounting requirements. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated specialists with captive feedstock and certified distribution. Long-term viability hinges on control of compliant manufacturing nodes rather than brand equity or technology differentiation. Monitor REACH substance restriction expansion timelines as the primary inflection signal for consolidation acceleration and margin repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Feedstock | Captive supply of high-purity volcanic rock insulates Rockwool International and Knauf from input cost volatility. |
| REACH-Compliant Binder Reformulation | Bio-based resin platforms enable Owens Corning and Johns Manville to maintain EU market access under tightening chemical restrictions. |
| Certified Installer Network Expansion | Contractor training capacity in German and French metro markets compresses project timelines and captures BEG and MaPrimeRénov subsidy flows. |
| Fire-Rated Assembly Certification Investment | ASTM E136 and EN 13501-1 documentation depth secures premium positioning in high-rise residential retrofits across the United Kingdom. |
| Prefab Building Envelope Partnership | Pre-cut insulation kit supply agreements with offsite construction manufacturers reduce field waste and accelerate assembly timelines. |
Research Methodology
The analysis maps fiberglass, mineral wool, cotton, and foam insulation sub-sectors, each validated through insulation contractor interviews, building materials distributor consultations, energy consultant surveys, and regulatory affairs director input. Primary fieldwork combined with secondary validation from EU Green Deal implementation reports, EPA ENERGY STAR certification databases, REACH substance restriction filings, and national building energy grant program disclosures. Bottom-up volume estimates from installer capacity and top-down market sizing from manufacturing capacity triangulate to produce segment-level outputs.
Assumptions held fixed include current EU Green Deal renovation target enforcement intensity, OSHA permissible exposure limit stability, and REACH substance restriction scope. The modeling period varies regulatory timeline scenarios across material chemistry, application segment, thickness configuration, and end-user procurement channel dimensions. CAGRs derive from installed base turnover rates, subsidy program budget trajectories, and energy code update frequencies. Forecast inputs incorporate HVAC efficiency standard adoption curves and industrial heat recovery infrastructure investment patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bio-based formulation specialists or cross-border building materials conglomerates would shift outcomes. Quarterly review of REACH substance restriction expansion proposals, EU member state BEG and MaPrimeRénov budget allocations, and OSHA synthetic vitreous fiber exposure limit revision dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Balustrade Market