
 Europe I-Joist Market | 2026-2036
Europe I-Joist Market Size, Share, and Industry Trends Forecast 2026-2036
Europe I-Joist Market Intelligence
Multi-family housing developers are reorganizing floor system procurement across Europe, displacing traditional solid timber with engineered I-joist assemblies. Binderholz GmbH leverages vertical integration from sawmill to prefabricated floor cassettes across Austria and Germany. Metsä Wood sustains technology leadership through its Finnjoist line optimized for Nordic moisture conditions. Steico SE differentiates via bio-based web materials that reduce thermal bridging in energy-efficient envelopes.
An I-joist consists of oriented strand board or plywood webs bonded to laminated veneer lumber or solid sawn flanges, creating a high stiffness-to-weight ratio beam designed for long-span floor and roof systems without intermediate bearing walls. Engineered wood joists dominate value pools where architects specify open-plan layouts requiring spans exceeding six meters. Floor systems anchor volume demand across German and French residential markets, while roof systems represent the fastest-growing application as pitched-roof retrofits accelerate under national renovation targets. Composite material variants are gaining share in commercial construction where fire ratings and acoustic performance drive specification.
CE marking under the Construction Products Regulation governs structural performance declarations for I-joists sold across EU member states, while national building codes in Germany, France, and Sweden impose supplementary deflection and vibration criteria that filter supplier eligibility. The EU Green Deal's embodied carbon reporting requirements through CSRD are reshaping procurement documentation, forcing manufacturers to publish environmental product declarations. Stakeholders must monitor whether upcoming revisions to Eurocode 5 will tighten deflection limits and disqualify legacy flange geometries from new construction permits.
Market Dynamics
EU Green Deal embodied carbon reporting through CSRD is forcing German and French developers to requalify floor system suppliers based on verified environmental product declarations rather than historical specification patterns.
Growth Catalysts
- Passive house construction mandates:Scandinavian building codes now require thermal bridge-free assemblies that I-joist floor cassettes deliver through continuous insulation integration.
- REACH-compliant bio-based web materials:Flax and hemp fiber webs reduce lifecycle carbon intensity while satisfying EU chemical safety thresholds for indoor air quality.
- Multi-family housing densification:German municipalities are rezoning brownfield sites for six-to-eight story residential blocks requiring long-span floor systems without intermediate columns.
Market Restraints
- Oriented strand board supply concentration:OSB web production clusters in Austria and Poland, creating vulnerability to regional pulp price volatility and transport capacity constraints.
- Eurocode 5 deflection criteria:National annexes in Sweden and France impose vibration limits that disqualify shallow I-joist depths from open-plan residential specifications.
- Cross-laminated timber substitution:CLT floor panels capture share in commercial mid-rise construction where mass timber aesthetics and two-way spanning dominate architect preference.
Strategic Opportunities
- Polish residential retrofit pipeline:National renovation targets for Soviet-era housing stock create demand for lightweight floor replacement systems compatible with existing masonry walls.
- Acoustic-rated web configurations:Mineral wool infill and decoupled flange designs address stricter airborne sound requirements in German multi-family building codes.
- Prefabricated cassette direct-to-site delivery:Bypassing traditional merchant distribution, manufacturers are contracting directly with French volume housebuilders for just-in-sequence installation.
Industry Challenges
- Structural timber engineering talent scarcity:German and Austrian technical universities produce insufficient graduates familiar with engineered wood connection design and fire-rated assembly detailing.
- CE marking documentation lag:Manufacturers face six-to-twelve month delays obtaining performance declarations under the Construction Products Regulation for novel flange-to-web adhesive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe I-Joist Market |
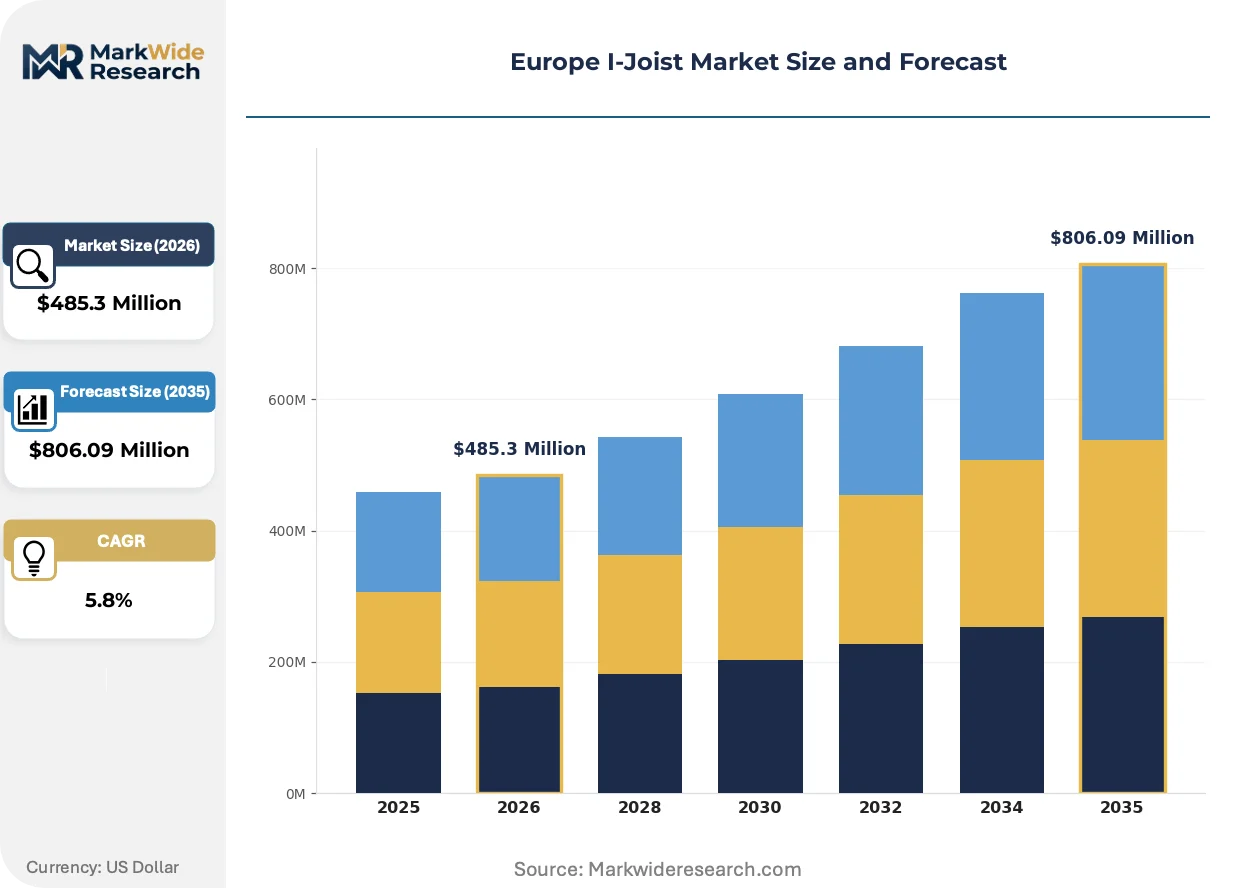
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Steel, Composite, Laminated Veneer Lumber End User: Residential Construction, Commercial Construction, Industrial Applications, Infrastructure Projects Product Type: Open Web Joists, Solid Joists, Engineered Wood Joists, Heavy Timber Joists Application: Floor Systems, Roof Systems, Wall Systems, Bridge Applications |
| Companies Covered | Binderholz GmbH, Wienerberger AG, Metsä Wood, Södra Wood Ltd., Norbord Inc., Steico SE, Rotho Blaas SRL, Egger Group, Stora Enso Oyj, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe I-Joist Market Strategic Shifts & Innovations
Specification authority is migrating from structural engineers to sustainability consultants as embodied carbon metrics penetrate European procurement workflows. Three forces are compressing traditional competitive positions.
Bio-based web technologies are decomposing the OSB monopoly in I-joist construction. Flax fiber and recycled wood fiber webs from Steico SE and similar suppliers reduce thermal bridging coefficients by fifteen to twenty percent compared to conventional strand board. German passive house developers are specifying these configurations for floor-to-exterior wall junctions where psi-values determine compliance. The technology is decomposing incumbent OSB suppliers' grip on high-performance envelope specifications.
CSRD mandatory environmental product declarations are restructuring supplier qualification protocols. Large German developers now require third-party verified EPDs before tender inclusion, filtering out smaller mills lacking lifecycle assessment capabilities. French social housing operators have adopted similar pre-qualification thresholds. The regulation is compressing the vendor base toward vertically integrated producers with in-house LCA competence.
Floor cassette pre-assembly is displacing stick-built installation on multi-family sites. Austrian and German manufacturers now deliver complete floor decks with pre-installed services and finished soffits, cutting site labor hours by half. French volume builders in the Paris basin have adopted this procurement model for projects exceeding fifty units. The shift is concentrating contract value with prefabrication-capable suppliers and marginalizing traditional merchant distribution channels.
Europe I-Joist Market Segmentation
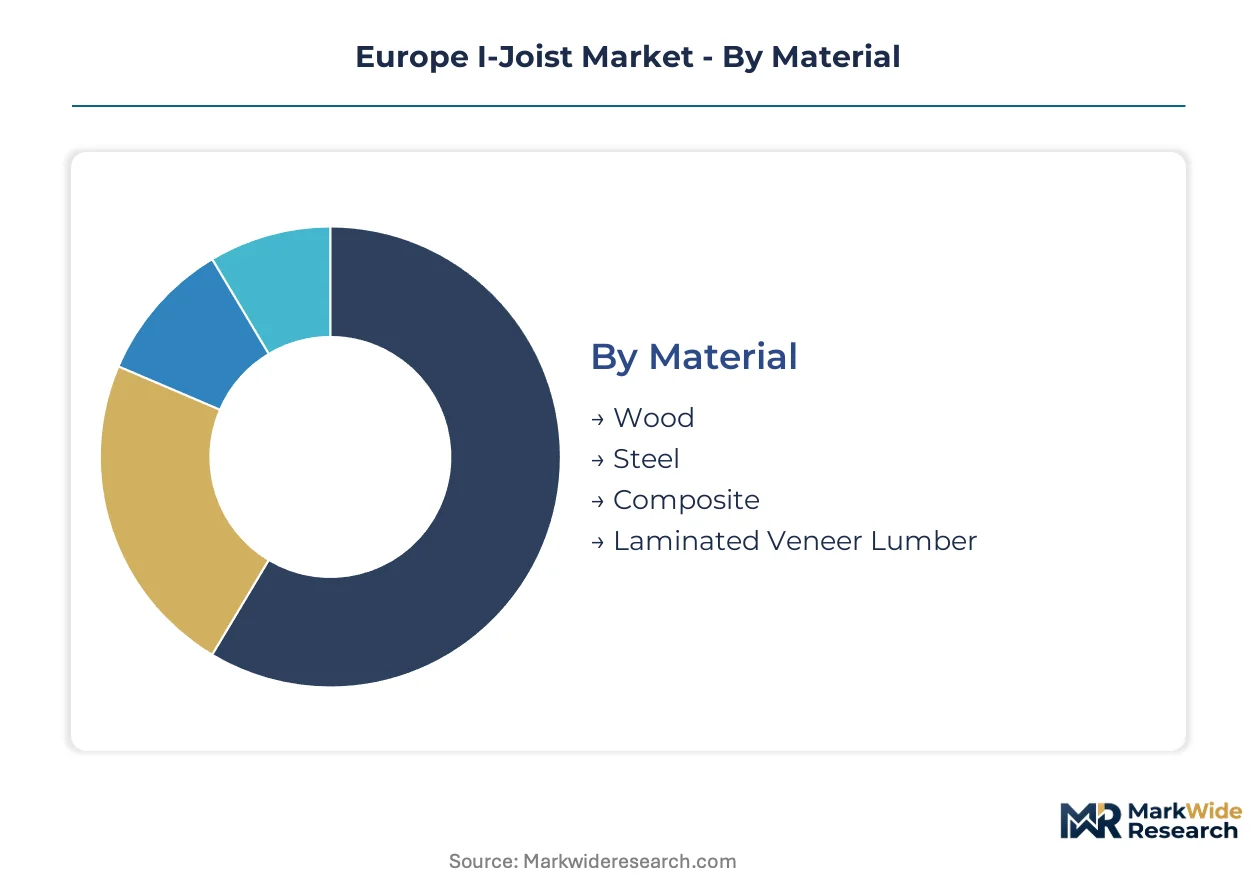
I-joist specification across Europe fragments along material composition, end-use intensity, and structural application. CE marking requirements under the Construction Products Regulation create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Material:
REACH chemical safety thresholds and EU Green Deal embodied carbon reporting differentiate material eligibility across member states.
- Wood:Solid sawn and engineered wood flanges dominate German and French residential construction. Nordic passive house developers specify wood-based I-joists for thermal bridge-free floor assemblies under stringent national building codes.
- Laminated Veneer Lumber:LVL flanges deliver superior span-to-depth ratios for open-plan layouts exceeding six meters. German multi-family housing developers prioritize LVL-strengthened configurations to eliminate intermediate columns in densified brownfield rezonings.
- Composite:Mineral wool and bio-based web infill variants address acoustic and fire rating requirements in commercial mid-rise construction across Austria and Switzerland.
- Steel:Cold-formed steel flanges penetrate industrial applications requiring enhanced load-bearing capacity and dimensional stability under variable moisture conditions.
Established volume favors Wood; emerging adoption favors Laminated Veneer Lumber.
End User:
Procurement authority concentrates differently across customer types, with sustainability consultants displacing structural engineers in large-developer qualification workflows.
- Residential Construction:Floor systems anchor demand as German municipalities rezone for six-to-eight story blocks. French volume housebuilders adopt prefabricated cassette delivery for projects exceeding fifty units.
- Commercial Construction:Fire-rated and acoustic assemblies drive specification where CSRD mandatory EPDs filter supplier eligibility. Composite material variants gain share in mid-rise developments across the Paris basin and Vienna.
- Industrial Applications:Heavy load requirements and vibration resistance prioritize steel-flange configurations in manufacturing facility construction.
- Infrastructure Projects:Bridge applications remain nascent, constrained by Eurocode 5 national annex deflection criteria in Sweden and France.
Contract value concentrates in Residential Construction; specification complexity climbs fastest in Commercial Construction.
Product Type:
Manufacturing capability and prefabrication scale determine competitive access within each product configuration.
- Engineered Wood Joists:OSB or plywood webs bonded to LVL or solid flanges constitute the core technology. Austrian and German manufacturers leverage backward integration from sawmill to finished cassette for cost control.
- Open Web Joists:Triangular steel web configurations enable mechanical routing integration. French and Belgian commercial developers specify these for flexible service distribution in renovation projects.
- Solid Joists:Traditional solid timber joists retain share in heritage-sensitive renovations and low-span agricultural buildings.
- Heavy Timber Joists:Mass timber aesthetics drive architect preference in exposed-structure commercial spaces, though CLT floor panels capture overlapping specification territory.
Technology leadership sits with Engineered Wood Joists; Open Web Joists climb the fastest in commercial retrofit pipelines.
Application:
Structural function determines span requirements, connection detailing complexity, and regulatory scrutiny intensity.
- Floor Systems:Long-span open-plan layouts without intermediate bearing walls define the primary value pool. German multi-family developers specify continuous insulation integration at floor-to-wall junctions for passive house compliance.
- Roof Systems:Pitched-roof retrofits accelerate under national renovation targets in Poland and the Czech Republic. Steico SE and similar suppliers optimize bio-based web materials for thermal performance.
- Wall Systems:Vertical I-joist applications in curtain wall and infill construction remain specialized, constrained by connection engineering talent scarcity.
- Bridge Applications:Pedestrian and light vehicular spans in Nordic countries test durability under extreme moisture cycling.
Revenue concentration favors Floor Systems; steepest expansion trajectory belongs to Roof Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German multi-family housing developers and Scandinavian passive house builders concentrate procurement authority for engineered floor systems. French volume housebuilders and Polish renovation contractors represent emerging demand clusters with distinct specification requirements.
Germany
Municipal brownfield rezoning for six-to-eight story residential blocks drives I-joist specification for long-span floor systems without intermediate columns. The EU Green Deal's embodied carbon reporting through CSRD forces developers to requalify suppliers based on verified environmental product declarations. Industrial concentration clusters in Bavaria and Baden-Württemberg where prefabricated cassette manufacturers deliver direct-to-site for Paris basin projects.
France
Social housing operators in the Paris basin adopt prefabricated floor cassette delivery for projects exceeding fifty units. National building codes impose supplementary deflection and vibration criteria that filter supplier eligibility for open-plan layouts. The Auvergne-Rhône-Alpes region anchors manufacturing capacity for acoustic-rated web configurations addressing stricter airborne sound requirements.
Sweden
Passive house construction mandates now require thermal bridge-free assemblies that I-joist floor cassettes deliver through continuous insulation integration. National annexes to Eurocode 5 impose vibration limits that disqualify shallow I-joist depths from residential specifications. Industrial activity concentrates in southern forest regions where Metsä Wood sustains technology leadership through moisture-optimized product lines.
Poland
National renovation targets for Soviet-era housing stock create demand for lightweight floor replacement systems compatible with existing masonry walls. REACH-compliant bio-based web materials gain traction as developers seek reduced lifecycle carbon intensity. Warsaw and Kraków metropolitan areas anchor retrofit contractor networks specifying engineered wood solutions for pitched-roof upgrades.
Austria
Timber engineering expertise clusters around Salzburg and Upper Austria where manufacturers leverage backward integration from sawmill to prefabricated components. CE marking under the Construction Products Regulation governs structural performance declarations for cross-border EU sales. The region supplies German and French developers with bio-based web technologies reducing thermal bridging coefficients in passive house envelopes.
Europe I-Joist Market Key Industry Players
Player mix skews toward vertically integrated forest products groups with captive timber supply and dedicated engineered wood divisions. The competitive structure concentrates around Austrian and Nordic producers controlling upstream fiber access. Two strategic archetypes dominate: sawmill-integrated fabricators with cassette prefabrication capability, and specialized bio-material developers targeting thermal performance differentiation. Capacity expansion and direct-to-site distribution partnerships constitute the prevailing competitive moves.
Among German and Austrian integrated producers, Binderholz GmbH and Egger Group exemplify the sawmill-to-cassette archetype with backward control over fiber supply. Steico SE occupies a distinct position as a bio-based materials specialist leveraging flax and recycled wood fiber technologies. These three entities anchor the vendor base restructuring around CSRD-mandated environmental product declarations and prefabrication scale.
| Leading Market Players |
|---|
| Binderholz GmbH |
| Wienerberger AG |
| Metsä Wood |
| Södra Wood Ltd. |
| Norbord Inc. |
| Steico SE |
| Rotho Blaas SRL |
| Egger Group |
| Stora Enso Oyj |
| Others |
Cost & Logistics Intelligence
Mill-scale economies in Austrian and Polish OSB web production anchor cost floors across the European I-joist market, concentrating supply-side leverage among integrated producers with captive timber access and compressing margin structures for merchant distributors lacking backward control over fiber supply.
Pricing Analysis
Cost-plus contracts with pulp price indexation dominate procurement between German multi-family developers and Austrian manufacturers. Price differentiation hinges on CE marking tier and volume scale, with prefabricated cassette suppliers commanding premiums over stick-built component vendors. Cost compression in standard-grade engineered wood joists is intensifying as French volume housebuilders consolidate supplier panels. Residential construction buyers exhibit highest price sensitivity, while passive house developers prioritize thermal performance over unit cost.
Supply Chain Analysis
Inventory cycles extending twelve to sixteen weeks from Austrian sawmills to German construction sites expose the market to regional transport capacity constraints. Production clusters in Austria, Poland, and southern Sweden feed raw material dependencies on Nordic spruce, Baltic birch veneer, and formaldehyde-free adhesives. Single-source vulnerability concentrates in OSB web supply from upper Austrian mills. Distribution runs through direct-to-site cassette delivery partnerships that bypass traditional merchant channels for projects exceeding fifty units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber substitution in commercial mid-rise construction threatens I-joist incumbents, demanding defensive repositioning around prefabrication scale and embodied carbon verification.
For Market Incumbents: Shield core German multi-family housing relationships by securing EPD verification under CSRD ahead of developer requalification cycles. Deepen upstream control over bio-based web material supply to differentiate against CLT floor panel competitors in passive house specifications. For New Entrants and Emerging Players: Lead with acoustic-rated web configurations targeting Polish Soviet-era housing retrofits where lightweight floor replacement systems face limited domestic competition. Establish direct contracting relationships with Warsaw-based renovation contractors bypassing established Austrian supply chains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated producers with in-house LCA competence and cassette prefabrication assets. Long-term viability rests on CSRD compliance infrastructure rather than commodity volume scale. Monitor embodied carbon reporting threshold enforcement as inflection signal for vendor base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Cassette Scale-Up | Direct-to-site delivery cuts German multi-family project labor hours by half versus stick-built installation. |
| Bio-Based Web Material Investment | Flax fiber webs reduce thermal bridging coefficients fifteen to twenty percent for passive house compliance. |
| EPD Verification Infrastructure | Third-party lifecycle assessment capabilities filter supplier eligibility under CSRD procurement protocols. |
| Polish Distribution Partnership | Warsaw retrofit contractor networks access Soviet-era housing stock renovation demand. |
| Acoustic-Rated Product Development | Mineral wool infill configurations address stricter German airborne sound requirements in multi-family codes. |
Research Approach
Desk research of Eurocode 5 national annexes, CE marking performance declarations, and EU Green Deal regulatory filings preceded structured interviews with timber structural engineers, multi-family housing procurement directors, passive house certifiers, and prefabricated component manufacturers. Secondary validation drew from Austrian and German industry association production statistics, Nordic timber trade flow data, and national building code amendment records. Bottom-up volume estimates from mill-level capacity triangulated against top-down construction permit analytics.
Variance decomposition across material composition, end-use intensity, and application type segments shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand modeling incorporating German municipal rezoning pipelines, French social housing procurement schedules, and Polish renovation target compliance timelines. Modeled inputs included spruce log price trajectories, adhesive formulation regulatory transitions, and prefabrication adoption rates by developer scale tier.
Underlying assumptions cover sustained EU Green Deal enforcement, stable Nordic timber harvest levels, and REACH compliance continuity for bio-based web materials, with deviation risk concentrated in Eurocode 5 deflection limit revisions and OSB supply disruptions from Austrian pulp price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Vinyl Windows Market