
 Storefront Glass Market | 2026-2036
Storefront Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Storefront Glass Market Analysis
Energy-efficiency mandates such as the EU Green Deal and updated IECC codes in the United States is expanding the cost-of-entry calculus for storefront glass suppliers. Saint-Gobain leverages its integrated float-coating capabilities to dominate European specification channels. Guardian Glass sustains technology leadership through advanced low-E sputter-coating platforms. YKK AP anchors its position via systems-level control over framing and glazing integration.
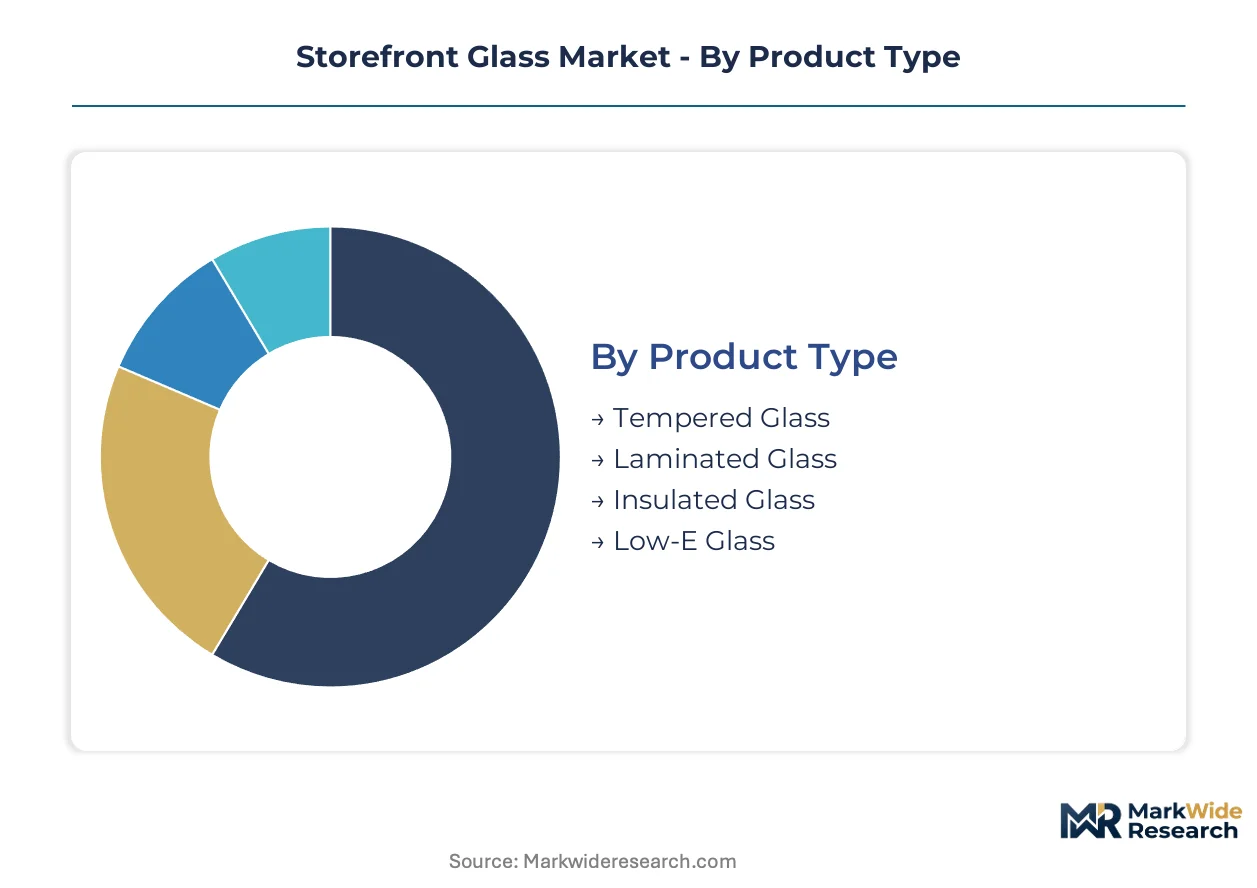
Storefront glass comprises heat-treated or coated flat glass assemblies engineered to thermal, optical, and safety specifications—typically fabricated through tempering, laminating, or insulating processes—to enclose commercial building entrances and display apertures while managing solar heat gain and structural loads. Low-E glass commands the specification premium as building codes tighten thermal performance thresholds, while insulated glass units capture retrofit volume from aging single-pane commercial stock across temperate climates. Tempered glass retains baseline share in high-traffic retail applications where impact resistance governs liability exposure.
EPA Energy Star certification, ASHRAE standards, and EU F-Gas Regulation collectively shape product roadmaps by penalizing high-U-value assemblies and restricting fluorinated gas use in insulating unit fabrication. Contractors and property managers in California, New York, and Germany now face compliance deadlines that disqualify conventional glazing from permitted commercial renovations. Stakeholders must monitor code divergence between jurisdictions to avoid specification mismatches that strand inventory or trigger costly change orders.
Market Dynamics
Energy-efficiency mandates across multiple jurisdictions are compressing the specification window for conventional glazing assemblies. Contractors now face compliance deadlines that disqualify single-pane and high-U-value systems from permitted commercial renovations in key states and European markets.
Growth Catalysts
- Retail Renovation Cycles:Aging commercial stock across the United States and Germany is driving replacement demand for thermally upgraded storefront systems. Property managers prioritize glazing that meets current code while preserving aesthetic continuity.
- EU F-Gas Regulation:Restrictions on fluorinated gas use in insulating unit fabrication are accelerating adoption of alternative spacer technologies and warm-edge designs across European fabrication channels.
- Low-E Sputter-Coating:Advanced coating platforms now deliver solar heat gain coefficients below 0.25 without sacrificing visible light transmission, satisfying California Title 24 and New York City Local Law 97 thresholds simultaneously.
Market Restraints
- Silica and Soda Ash Volatility:Float glass production depends on concentrated soda ash supply from Wyoming trona deposits and synthetic sources in China, creating input cost exposure that fabricators cannot fully pass through.
- Regional Supply Concentration:Tempering and laminating capacity clusters in the Ohio River Valley and northern Mexico, leaving coastal renovation markets vulnerable to freight cost spikes and extended lead times.
- Triple-Glazing Substitution:High-performance commercial projects in Germany and Scandinavia are bypassing conventional Low-E IGUs entirely in favor of triple-pane assemblies with suspended films.
Strategic Opportunities
- Electrochromic Integration:Dynamic glazing is converging with building management systems to enable real-time tint adjustment, opening specification pathways in Class A office towers and airport terminals.
- India Commercial Build-Out:Organized retail expansion in Mumbai, Delhi, and Bangalore is creating first-mover advantage for suppliers establishing local fabrication partnerships ahead of BIS thermal performance mandates.
- Utility Rebate Stacking:California investor-owned utilities and New York State Energy Research and Development Authority incentives now cover 15-30% of incremental glazing upgrade costs for qualifying commercial retrofits.
Industry Challenges
- Thermal Bridging Expertise Gap:Framing system integration requires specialized knowledge of psi-value calculations and 3D thermal modeling that remains scarce among regional glazing contractors outside major metropolitan markets.
- Coating Line Capital Intensity:Magnetron sputtering equipment for high-performance Low-E production demands eight-figure capital commitments with payback periods exceeding seven years, limiting new entrant participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storefront Glass Market |
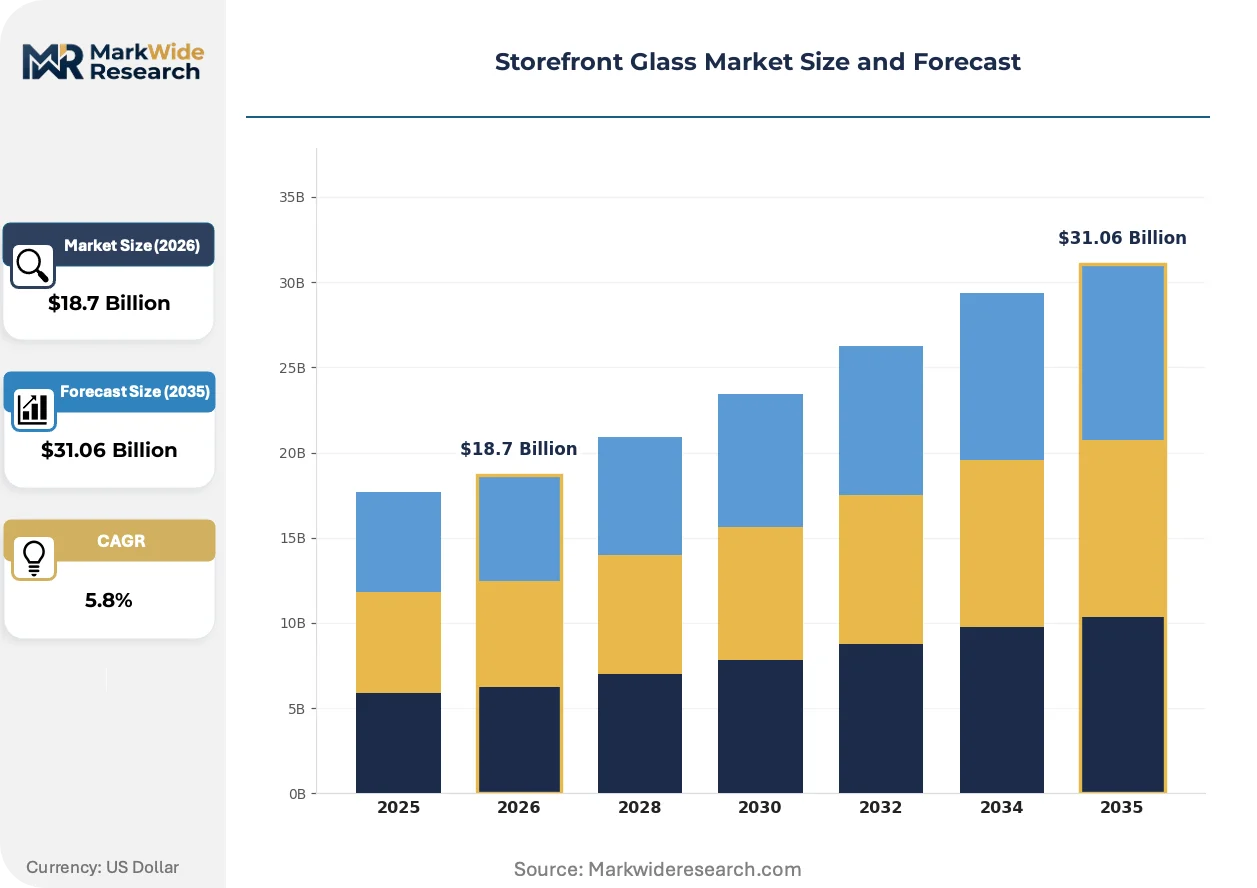
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Low-E Glass Application: Retail Stores, Restaurants, Commercial Buildings, Shopping Malls Installation Type: Framed, Frameless, Semi-Frameless, Curtain Wall End User: Architects, Builders, Contractors, Property Managers |
| Companies Covered | Vitro Architectural Glass, YKK AP, Guardian Glass, Pilkington Glass, Asahi Glass Co., Saint-Gobain, Cardinal Glass Industries, Vallisco, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storefront Glass Market Emerging Trajectories
Digital fabrication and smart materials are redefining how storefront assemblies are specified, procured, and commissioned. Three developments are compressing traditional supply chain timelines while expanding performance boundaries.
Vacuum-insulated glass (VIG) is converging with conventional curtain wall framing systems to deliver R-values above R-12 in profiles thinner than one inch. High-rise developers in New York and London are specifying VIG for floor-to-ceiling applications where structural load limits prohibit triple-pane weight. This convergence is compressing the performance gap between residential and commercial glazing specifications.
The EU Green Deal's Renovation Wave strategy is mandating staged thermal upgrades for commercial buildings exceeding 1,000 square meters. Member states must transpose minimum energy performance standards by 2026, forcing property owners in France, Italy, and Spain to prioritize glazing replacement in initial retrofit phases. German fabricators are responding with pre-certified assembly packages that streamline permitting.
Performance-based specification is displacing prescriptive product selection among national retail chains and logistics operators. Buyers now contract for guaranteed U-value and SHGC outcomes rather than nominating specific glass compositions, transferring technical risk to glazing contractors. This shift is most visible in the United States, where REITs and big-box retailers are consolidating vendor panels around outcome-verification capabilities.
Storefront Glass Market Segmentation
Storefront glass procurement splits between specification-driven projects where architects control material selection and cost-driven renovations where contractors optimize for code compliance. Understanding these segment boundaries clarifies why Low-E glass commands premium positioning in new construction while tempered glass dominates retrofit volume.
Product Type:
The customization-to-standardization spectrum spans from project-engineered coatings to commodity tempering, with fabrication complexity determining margin capture.
- Low-E Glass:Sputter-coated surfaces achieve solar heat gain coefficients below 0.25 while preserving visible light transmission. Demand concentrates in California and New York where Title 24 and Local Law 97 mandate thermal performance thresholds that conventional glazing cannot satisfy.
- Tempered Glass:Heat-strengthened through controlled thermal shock to deliver 4-5x mechanical strength of annealed alternatives. Retail renovation cycles across the United States and Germany drive replacement volume where impact resistance governs liability exposure in high-traffic entrances.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for post-breakage retention and acoustic dampening.
- Insulated Glass:Dual-pane assemblies with dehydrated air or gas fill address thermal bridging in temperate climate commercial stock.
Most installed capacity flows through Tempered Glass. Expansion is steepest in Low-E Glass.
Application:
Cost tier stratification separates trophy assets with unlimited specification budgets from commodity retail refresh programs with strict square-foot caps.
- Retail Stores:Street-facing display apertures demand optical clarity for merchandise visibility combined with thermal performance to protect inventory. Aging commercial stock across North America is strengthening replacement demand as property managers prioritize glazing that meets current code while preserving aesthetic continuity.
- Commercial Buildings:Class A office towers specify dynamic glazing and vacuum-insulated assemblies where structural load limits prohibit triple-pane weight. High-rise developers in New York and London are driving adoption of thin-profile high-R-value solutions for floor-to-ceiling applications.
- Restaurants:Food service environments require easy-clean surfaces and thermal comfort for patron seating areas adjacent to glazing.
- Shopping Malls:Large-format curtain wall systems enclose multi-tenant common areas with standardized specification packages.
Volume concentrates in Retail Stores. Value capture is climbing fastest in Commercial Buildings.
Installation Type:
Customer type divides between design-led architects specifying frameless aesthetics and operations-focused property managers prioritizing thermal bridging control through framed systems.
- Framed:Aluminum or steel perimeter members provide structural support and thermal break accommodation for code-compliant assemblies. Contractors and property managers in California and Germany face compliance deadlines that disqualify conventional framing from permitted renovations, accelerating warm-edge spacer adoption.
- Curtain Wall:Factory-assembled unitized systems integrate glazing, framing, and anchorage for high-rise application. New York and London developers specify these assemblies where VIG convergence delivers R-values above R-12 in profiles thinner than one inch.
- Frameless:Point-supported or patch-fitted hardware creates uninterrupted sightlines for flagship retail and hospitality.
- Semi-Frameless:Minimal vertical mullions with structural silicone retention balance aesthetics and economy.
Most specification volume routes through Framed systems. Curtain Wall is gaining share fastest in high-performance commercial segments.
End User:
Supply concentration clusters around fabrication channels serving metropolitan glazing contractors, with expertise scarcity limiting regional contractor participation outside major markets.
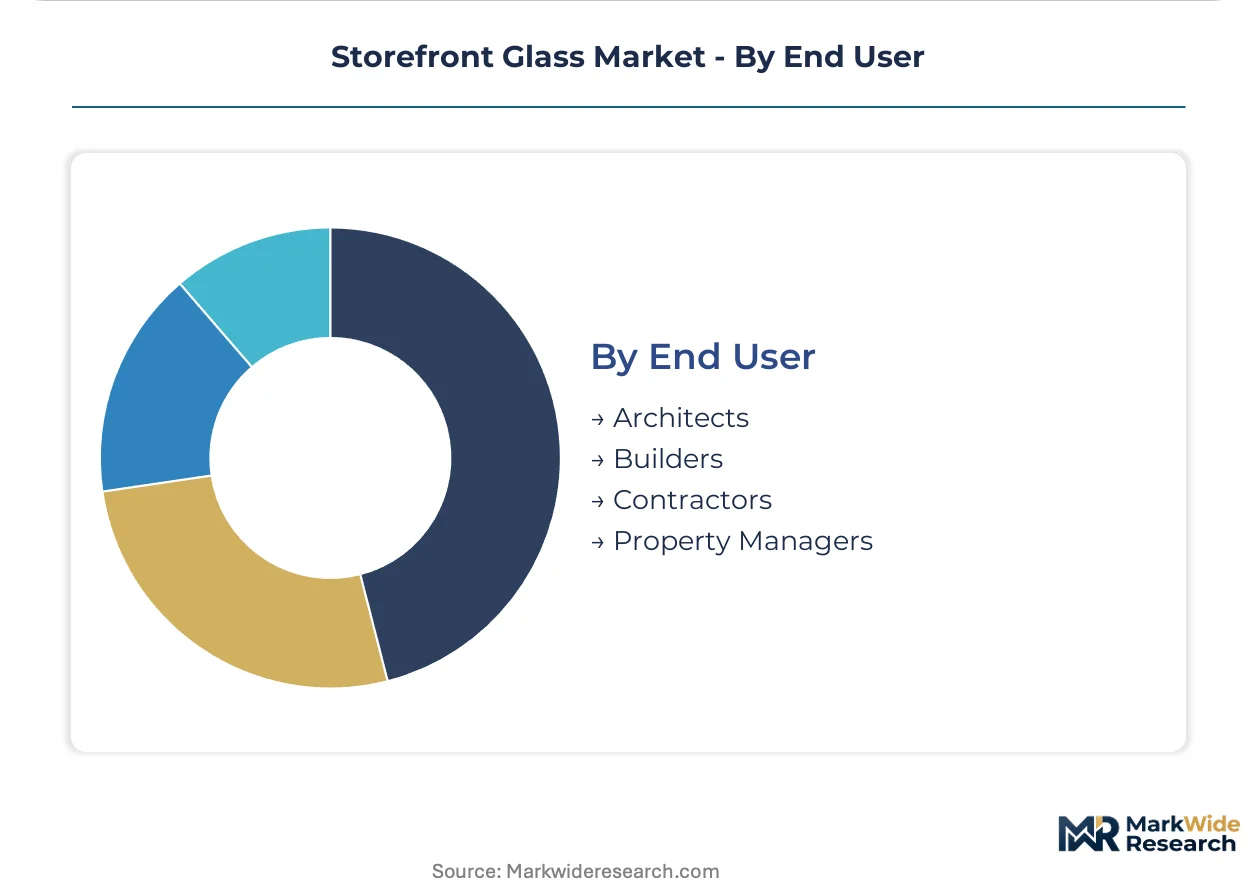
- Contractors:Regional glazing specialists execute fabrication and field installation with psi-value calculation and 3D thermal modeling capabilities. The EU Green Deal's Renovation Wave is forcing property owners in France, Italy, and Spain to prioritize glazing replacement, expanding contractor panel consolidation around outcome-verification capabilities.
- Architects:Design professionals specify guaranteed U-value and SHGC outcomes rather than nominating specific glass compositions, transferring technical risk to glazing contractors. This performance-based specification shift is most visible in the United States where REITs and big-box retailers are consolidating vendor relationships.
- Builders:General construction firms subcontract glazing as part of broader commercial envelope packages.
- Property Managers:Asset operators prioritize lifecycle cost and code compliance in renovation decision-making.
Most project flow passes through Contractors. Architect-led specification is expanding most quickly in Class A commercial development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glazing contractors cluster in California, New York, and Germany where thermal performance mandates have created certification bottlenecks. These workforce concentrations anchor regional fabrication capacity and dictate specification expertise availability.
United States
Retail renovation cycles across the Sun Belt and Northeast are accelerating replacement demand for thermally upgraded storefront systems. California Title 24 and New York City Local Law 97 impose compliance deadlines that disqualify conventional glazing from permitted commercial renovations. Fabrication capacity concentrates in the Ohio River Valley, leaving coastal markets vulnerable to freight cost spikes.
Germany
Property owners face staged thermal upgrade mandates under the EU Green Deal's Renovation Wave strategy for commercial buildings exceeding 1,000 square meters. The EU F-Gas Regulation restricts fluorinated gas use in insulating unit fabrication, accelerating warm-edge spacer adoption. German fabricators in Bavaria and North Rhine-Westphalia are responding with pre-certified assembly packages that streamline permitting.
China
Organized retail expansion in Shanghai, Beijing, and Shenzhen is creating first-mover advantage for suppliers establishing local fabrication partnerships. The country's national building efficiency regulator is developing thermal performance mandates modeled on European standards. Yangtze River Delta fabricators are investing in magnetron sputtering capacity to serve domestic low-E glass demand.
India
Commercial build-out in Mumbai, Delhi, and Bangalore is driving specification demand for storefront glazing in organized retail and office developments. BIS thermal performance mandates are advancing through consultation phases, creating compliance preparation windows for fabricators. Regional glazing contractors in Maharashtra and Karnataka are acquiring psi-value calculation capabilities to serve metropolitan markets.
United Kingdom
High-rise developers in London are specifying vacuum-insulated glass for floor-to-ceiling applications where structural load limits prohibit triple-pane weight. The country's building regulations are tightening U-value thresholds for commercial envelope renovations. Fabricators in the Southeast and Midlands are consolidating around outcome-verification capabilities to serve REIT procurement panels.
Storefront Glass Market Vendor Landscape
The competitive structure tilts toward integrated material suppliers with captive float-coating capabilities. Market concentration is moderate, with global glass manufacturers competing against regional fabricators and systems specialists. Three archetypes dominate: integrated float-to-fabrication players, framing systems integrators, and regional tempering specialists. Capacity expansion and warm-edge technology licensing represent the dominant competitive moves as fabricators respond to tightening thermal codes.
Among integrated material suppliers, Saint-Gobain and Guardian Glass exemplify the float-coating archetype with upstream control over glass substrate and sputter-coating processes. YKK AP occupies a position within the systems integration tier, anchoring specification channels through combined framing and glazing expertise. These three companies represent the structural poles around which regional fabricators and specialized coating houses organize competitive positioning.
| Leading Market Players |
|---|
| Vitro Architectural Glass |
| YKK AP |
| Guardian Glass |
| Pilkington Glass |
| Asahi Glass Co. |
| Saint-Gobain |
| Cardinal Glass Industries |
| Vallisco |
| AGC Inc. |
| Others |
Supply Flow & Price Mechanics
California Title 24 and New York City Local Law 97 compliance deadlines are compressing procurement timelines for thermally upgraded storefront systems, forcing fabricators to absorb certification costs and restructure quoting models around guaranteed performance outcomes rather than commodity glass grades.
Pricing Analysis
Project-based bundled contracts dominate specification-driven segments, separating premium Low-E coating packages from commodity tempering work. Price differentiation rests on U-value certification tier and warm-edge spacer technology integration, with coastal freight surcharges widening geographic cost spreads. Cost compression in standard tempering runs through silica and soda ash volatility that fabricators cannot fully pass to renovation contractors. Big-box retail procurement panels exhibit highest price sensitivity, while Class A office developers prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-contractor channels handle metropolitan renovation demand, with specification support bundled for architect-led projects. Float glass production concentrates in the United States, Germany, and China, drawing from Wyoming trona deposits and synthetic soda ash sources. Tempering and laminating capacity clusters in the Ohio River Valley and northern Mexico, creating single-source vulnerability for coastal markets. Distribution runs through regional glazing contractors with psi-value calculation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas restrictions and California Title 24 mandates continuously reset baseline performance thresholds, creating durable replacement demand cycles.
For Market Incumbents: Extend captive coating capacity through magnetron sputtering investments to defend against triple-glazing substitution in German and Scandinavian commercial segments. Anchor specification channels via pre-certified assembly packages that streamline Title 24 and Local Law 97 permitting. Deepen warm-edge spacer technology licensing to capture EU F-Gas compliance premiums before alternative fabrication methods mature. For New Entrants and Emerging Players: Digital specification platforms offer low-friction entry into outcome-based procurement panels where REITs and national retail chains consolidate vendor relationships. Target Indian metropolitan markets ahead of BIS thermal performance mandates through local fabrication partnerships in Maharashtra and Karnataka. Lead with psi-value calculation services to differentiate from commodity tempering specialists lacking thermal bridging expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing certified warm-edge capabilities and established contractor panels in California, New York, and Germany. Long-term viability hinges on positioning ahead of staged EU Green Deal renovation mandates and emerging economy code convergence. Monitor electrochromic integration milestones as inflection indicators for dynamic glazing specification share.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Sputtering Capacity Expansion | Captures Low-E specification premiums in California and New York compliance markets. |
| Warm-Edge Spacer Technology Licensing | Addresses EU F-Gas restrictions while streamlining German and Italian permitting pathways. |
| Pre-Certified Assembly Package Development | Reduces contractor thermal bridging expertise gaps and accelerates renovation cycle capture. |
| Regional Fabrication Partnership Formation | Establishes first-mover positioning in Indian organized retail expansion ahead of BIS mandates. |
| Electrochromic Integration Investment | Opens Class A office and airport terminal specifications through building management system convergence. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with glazing contractors, architectural specification leads, property management procurement officers, and regional fabrication plant managers against secondary validation through customs trade data, ASHRAE and IECC code documentation, EU Green Deal implementation reports, and SEC filings from publicly traded glass manufacturers. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts.
Granularity-level modeling disaggregates volume and value across product type, application, installation configuration, and end-user channel throughout the forecast period. CAGRs derive from segment-level growth rate synthesis applied to baseline installed stock estimates. Forecast inputs incorporate thermal code adoption timelines, renovation cycle frequency by building vintage, and Low-E coating technology diffusion curves.
The model assumes a particular technology adoption path; alternative pathways for vacuum-insulated glass or suspended-film triple-glazing would alter the outlook for conventional Low-E insulated glass unit demand. Forecasts reflect assumptions regarding regulatory enforcement consistency, raw material price stability, and contractor certification capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Glass Railing System Market