
 Australia and New Zealand Industrial Flooring Market | 2026-2036
Australia and New Zealand Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Industrial Flooring Market Outlook
Asset-light leasing models for flooring installation equipment is fragmenting competitive dynamics across the Australia and New Zealand Industrial Flooring Market. Sika Australia leverages its Swiss-parent technical heritage to dominate specification-driven projects in pharmaceutical cleanrooms. Mapei Australia Pty Ltd anchors its position through captive supply of cementitious screeds, backward integration that shields margin from resin volatility. Roxset Australia specializes in rapid-cure polyurethane systems for operational facilities requiring minimal downtime.
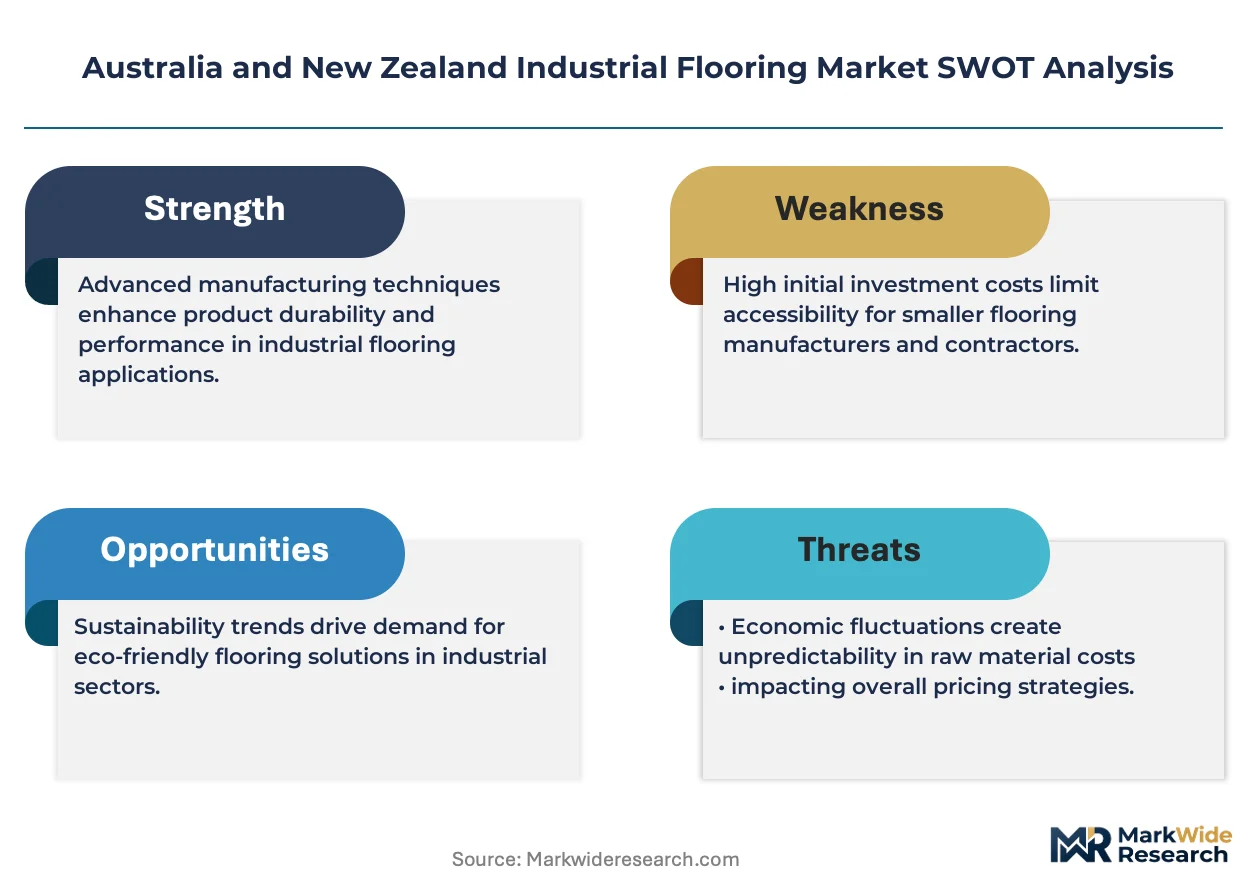
Australia and New Zealand industrial flooring encompasses resinous, cementitious, and polymer-modified surface systems engineered to withstand mechanical abrasion, chemical exposure, and thermal cycling in commercial and industrial environments. Epoxy formulations typically achieve compressive strengths exceeding 80 MPa and bond to concrete substrates through amine-cured crosslinking, serving primarily to protect structural slabs while enabling hygienic, dust-free operations. Heavy-duty application segments lead value generation due to replacement cycles in mining maintenance bays and heavy manufacturing, while chemical-resistant installations represent the fastest-growing margin pool as battery recycling and pharmaceutical processing expand. New construction installations command premium pricing but renovation and overlay work now constitute the larger volume opportunity as building stock ages across both countries.
Food Standards Australia New Zealand (FSANZ) mandates HACCP-aligned surfaces in food contact zones, directly specifying seamless, coving-compatible resin systems that eliminate bacterial harborage points. Standards Australia AS 4586 and AS 4663 govern slip resistance classification and on-site verification, creating compliance barriers for imported products lacking local slip-rating certification. The Building Code of Australia (BCA) Section J energy efficiency provisions increasingly influence flooring selection in conditioned spaces where thermal mass contribution matters. Stakeholders must monitor convergence between WHS harmonization pressures and emerging PFAS restrictions on fluorinated slip additives that currently dominate anti-slip formulations.
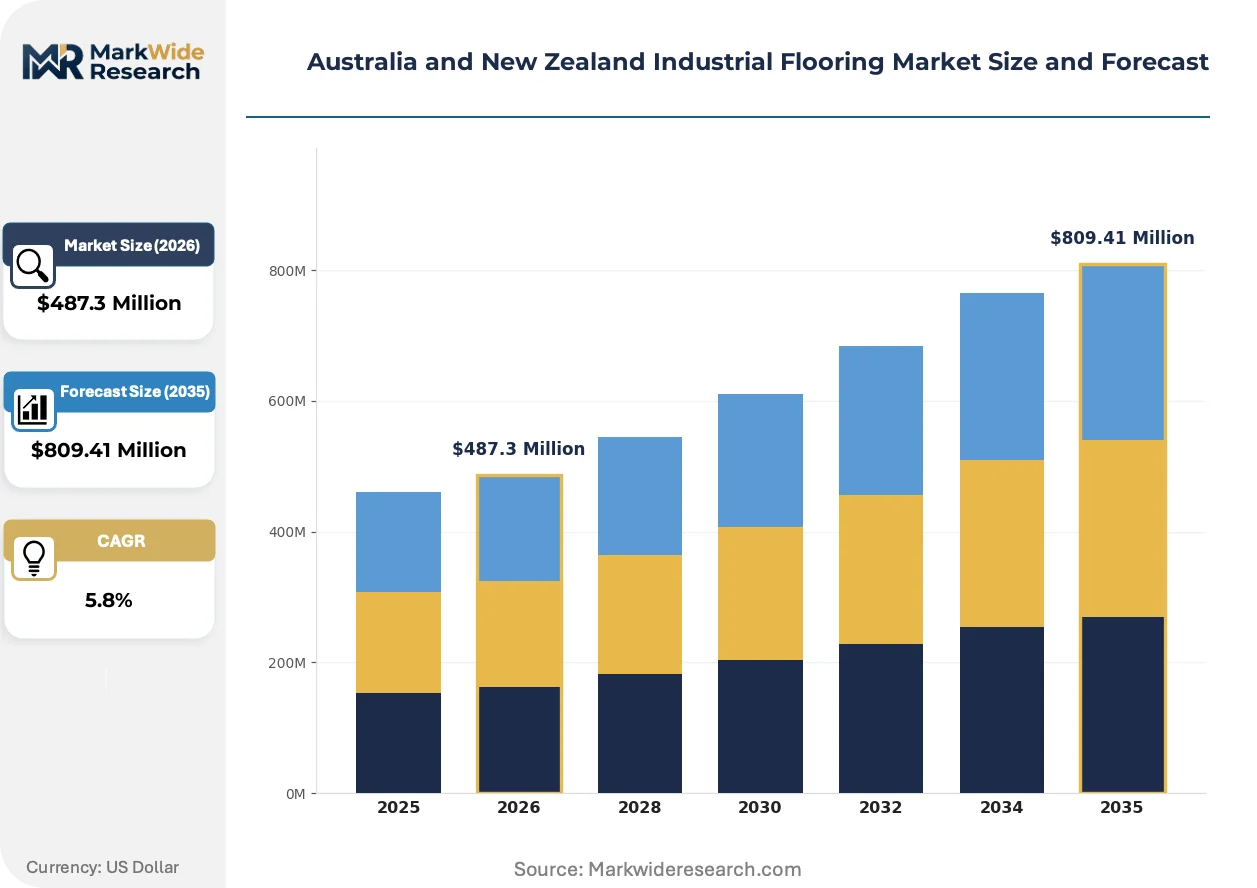
Market Dynamics
Asset-light equipment leasing is fragmenting competitive dynamics across the Australia and New Zealand Industrial Flooring Market, eroding capital barriers that once protected established installers while enabling regional specialists to scale rapidly without balance-sheet strain.
Growth Catalysts
- FSANZ hygiene mandates:Food Standards Australia New Zealand HACCP-aligned surface requirements in food contact zones mandate seamless resin systems with integral coving, eliminating bacterial harborage points and driving specification upgrades across processing facilities.
- Battery recycling expansion:Chemical-resistant installations for lithium-ion battery recycling plants in Victoria and South Australia are pulling specialized epoxy formulations with enhanced acid resistance and thermal cycling tolerance.
- Queensland manufacturing corridor concentration:Heavy-duty application demand from mining maintenance bays and heavy manufacturing in Brisbane-Gladstone corridor sustains replacement cycle volumes.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol A and epichlorohydrin price swings compress installer margins on fixed-price contracts, particularly for large-footprint warehouse projects with extended completion timelines.
- Import certification barriers:Standards Australia AS 4586 slip-rating requirements create friction for Asian-manufactured systems lacking local wet-pendulum test verification, limiting sourcing flexibility.
- Cementitious screed substitution:Polymer-modified cementitious overlays compete aggressively on cost for light-to-medium duty applications where chemical resistance demands are moderate.
Strategic Opportunities
- Auckland industrial precincts:New Zealand's concentrated industrial base offers scale efficiencies for rapid-cure polyurethane specialists targeting operational facilities with minimal downtime tolerance.
- PFAS transition tailwind:Emerging restrictions on fluorinated slip additives under Australian environmental regulations create first-mover advantage for silica-based and recycled glass anti-slip alternatives.
- Building stock aging:Renovation and overlay work now exceeds new construction volumes across both countries, favoring service-intensive providers with diagnostic and substrate remediation capabilities.
Industry Challenges
- Skilled applicator scarcity:Moisture-tolerant epoxy and polyurethane installation requires certified technicians with substrate moisture testing and dew-point calculation competencies that outpace vocational training pipeline output.
- Multi-standard compliance timelines:Projects must simultaneously satisfy Food Standards Australia New Zealand hygiene mandates, Standards Australia slip classifications, and Building Code of Australia Section J thermal provisions, extending specification approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Industrial Flooring Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, PVC, Concrete End User: Manufacturing, Warehousing, Retail, Food Processing Application: Heavy-Duty, Chemical Resistant, Anti-Slip, Aesthetic Installation Type: New Construction, Renovation, Overlay, Repair |
| Companies Covered | MBCC Group, Antiskid Industries, Sika Australia, Mapei Australia Pty Ltd, Bethell Flooring, Roxset Australia, Multiblast Flooring Pty Ltd, Interface Inc, RPM International Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Industrial Flooring Market Strategic Shifts
Formulation chemistry and installation methodology are converging around speed-to-service and environmental compliance, compressing traditional trade-offs between durability, safety, and sustainability that previously segmented product tiers.
Water-dispersible epoxy technology is migrating from marginal specialty status toward mainstream specification in food processing and pharmaceutical cleanrooms. Facility operators in Sydney and Melbourne are specifying these systems for operational environments where solvent odor and VOC exposure trigger WHS complaints or production halts. The shift is compressing market share for conventional solvent-borne formulations while elevating premium pricing power for suppliers with certified low-emission product lines.
Food Standards Australia New Zealand is tightening interpretation of HACCP-aligned surface requirements through enhanced audit protocols for bacterial harborage risk. This regulatory pressure is forcing specification upgrades from trowel-applied coatings toward self-leveling systems with integral coving and flash-coving details at wall-floor junctions. Queensland meat processing and dairy facilities are experiencing the most intensive compliance scrutiny, driving accelerated replacement of legacy tile and sealed concrete surfaces.
Facility engineering teams are unbundling installation from material supply, engaging directly with resin formulators for specification authority while sourcing labor through qualified contractor networks. This disintermediation is compressing traditional distributor margins and shifting commercial relationships toward technical service agreements. The pattern is most visible in Auckland pharmaceutical manufacturing and Perth mining services, where capital project teams prioritize direct manufacturer accountability for warranty and performance claims.
Australia and New Zealand Industrial Flooring Market Segmentation
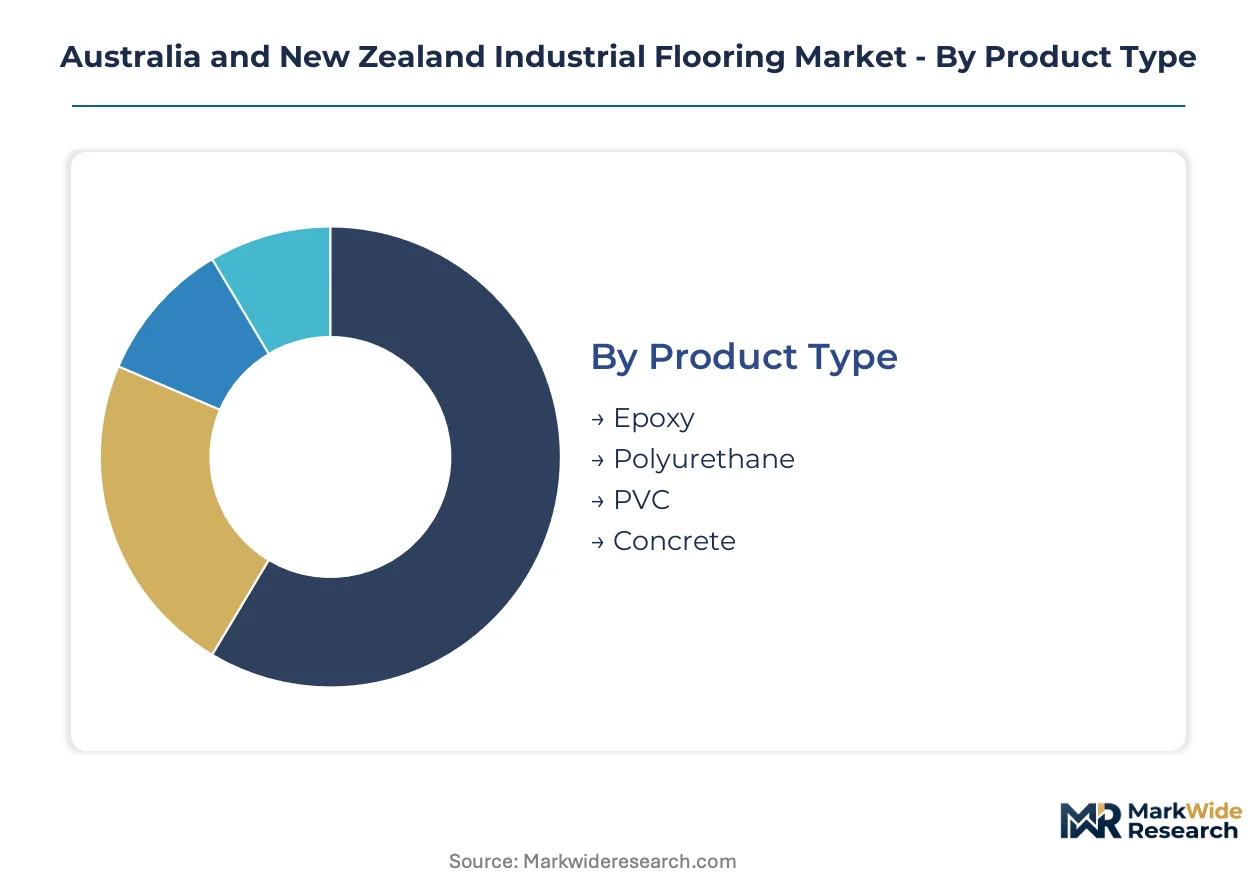
Industrial flooring specifications across Australia and New Zealand fragment sharply by performance tier and regulatory exposure. Material chemistry, installation methodology, and end-use hygiene mandates create distinct commercial battlegrounds that reward specialized formulation capabilities over commodity supply.
Product Type:
Mature resin technologies dominate specification authority while polymer alternatives carve cost-sensitive niches.
- Epoxy:Amine-cured thermoset systems achieve compressive strengths exceeding 80 MPa through crosslinking density. Queensland meat processing and dairy facilities specify seamless epoxy with integral coving under FSANZ audit pressure, driving premium-grade demand despite feedstock volatility in bisphenol A and epichlorohydrin markets.
- Polyurethane:Rapid-cure aliphatic and aromatic formulations enable return-to-service within 24 hours. Auckland pharmaceutical manufacturing and Perth mining maintenance bays prioritize these systems for operational environments where downtime tolerance approaches zero, cementing polyurethane's position in facility upgrade cycles.
- PVC:Homogeneous and heterogeneous sheet goods compete on installed cost for light-duty warehousing and retail back-of-house zones.
- Concrete:Densified and polished structural slabs serve budget-constrained applications where chemical resistance demands remain minimal.
Epoxy handles the majority of throughput; polyurethane is the fastest mover on share.
End User:
Regulatory intensity varies dramatically across facility types, concentrating margin in compliance-heavy segments.
- Manufacturing:Heavy machinery vibration and thermal cycling demand thick-film epoxy screeds with aggregate reinforcement. Victoria's emerging battery recycling plants specify acid-resistant formulations with enhanced thermal shock tolerance, pulling specialized system development from formulators with chemical resistance testing capabilities.
- Food Processing:FSANZ mandates HACCP-aligned seamless surfaces with flash-coving at wall-floor junctions. Queensland's intensive audit protocols for bacterial harborage risk are forcing accelerated replacement of legacy tile and sealed concrete, creating specification upgrade momentum.
- Warehousing:Medium-duty epoxy coatings with silica anti-slip additives address forklift traffic and pallet jack abrasion in distribution centers.
- Retail:Aesthetic polyurethane and epoxy systems with decorative flake or quartz finishes serve showroom and customer-facing zones.
Manufacturing commands the largest project scale; food processing is expanding most quickly on regulatory tailwinds.
Application:
Performance tier stratification separates specification-driven premium opportunities from price-sensitive volume plays.
- Heavy-Duty:Epoxy mortar systems with broadcast aggregate achieve 6-9 mm thickness for impact resistance. Mining maintenance bays across the Brisbane-Gladstone corridor sustain replacement cycle volumes as equipment weight and traffic intensity accelerate wear profiles.
- Chemical Resistant:Novolac and vinyl ester formulations withstand sulfuric acid exposure and thermal cycling. Lithium-ion battery recycling expansion in Victoria and South Australia is pulling specialized acid-resistant systems with enhanced thermal tolerance, representing the steepest expansion trajectory in application tiering.
- Anti-Slip:Silica, aluminum oxide, and recycled glass aggregates embedded in resin matrices satisfy Standards Australia AS 4586 wet-pendulum requirements.
- Aesthetic:Metallic epoxy and decorative quartz systems serve corporate facilities and retail showrooms where visual impact complements functional performance.
Heavy-duty applications anchor replacement revenue; chemical-resistant installations are gaining share fastest on industrial diversification.
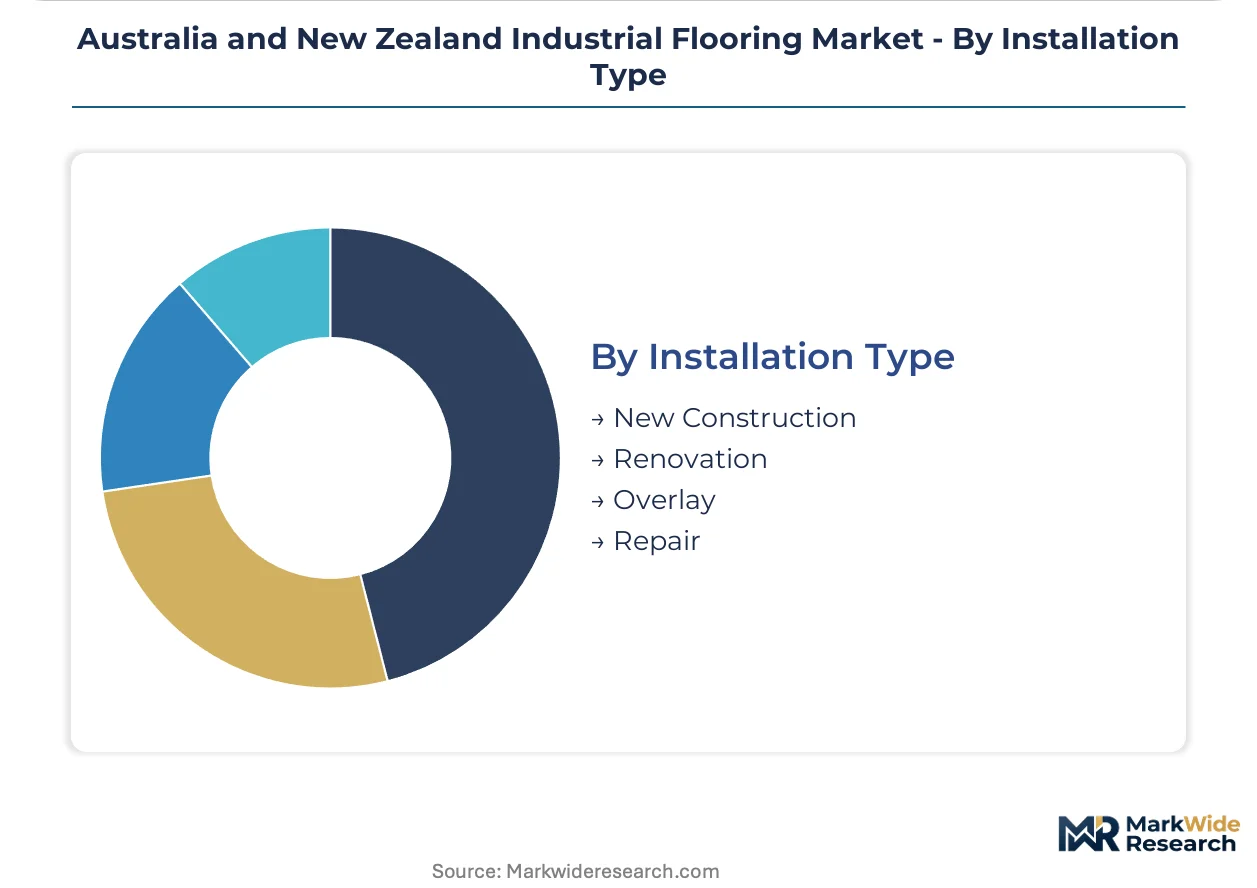
Installation Type:
Building stock age across both countries is inverting the traditional new-build dominance toward service-intensive retrofit work.
- Renovation:Substrate remediation, moisture mitigation, and surface preparation precede resin overlay in aging industrial stock. Sydney and Melbourne facility operators are unbundling material supply from installation labor, engaging directly with formulators for specification authority while sourcing certified applicators through qualified contractor networks.
- Overlay:Thin-film epoxy and polyurethane systems bond to prepared concrete for functional upgrade without slab replacement. Building Code of Australia Section J thermal provisions increasingly influence overlay selection in conditioned spaces where thermal mass contribution affects energy efficiency compliance.
- New Construction:Green-field specification offers premium pricing but shrinking volume share as industrial building permits moderate.
- Repair:Patching and localized resurfacing addresses spalling, cracking, and coating failure in operational facilities.
Renovation handles the majority of throughput; overlay work is climbing the fastest on building stock aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ hygiene mandates and Building Code of Australia energy provisions are redirecting specification authority toward compliant resin systems across both markets. State-level procurement patterns diverge based on industrial base composition and enforcement intensity.
New South Wales
Sydney pharmaceutical manufacturing and food processing clusters drive demand for water-dispersible epoxy systems with low-VOC certification. The state's WHS harmonization pressures compound compliance requirements for solvent-borne alternatives. Parramatta and Western Sydney industrial precincts concentrate renovation activity as aging warehouse stock requires substrate remediation and overlay work.
Victoria
Lithium-ion battery recycling plant construction in Melbourne's outer industrial corridors pulls specialized acid-resistant epoxy formulations with enhanced thermal cycling tolerance. EPA Victoria's emerging PFAS restrictions on fluorinated slip additives accelerate specification shifts toward silica-based alternatives. Geelong and Dandenong manufacturing zones anchor chemical-resistant installation volumes.
Queensland
Brisbane-Gladstone corridor mining maintenance bays sustain heavy-duty epoxy mortar replacement cycles under extreme equipment loads. FSANZ audit intensification for meat processing and dairy facilities forces seamless system upgrades with integral coving. Rockhampton and Townsville industrial precincts concentrate rapid-cure polyurethane demand for operational facilities with minimal downtime tolerance.
Western Australia
Perth mining services and remote resource extraction infrastructure prioritize chemical-resistant novolac formulations for sulfuric acid exposure environments. The state's building stock aging outpaces new construction permits, favoring overlay specialists with diagnostic capabilities. Kwinana industrial area and Pilbara maintenance hubs drive specification for thick-film screeds with aggregate reinforcement.
New Zealand
Auckland's concentrated pharmaceutical manufacturing base engages directly with resin formulators for specification authority, bypassing traditional distribution channels. Standards New Zealand alignment with AS 4586 slip-rating requirements creates certification friction for non-local products. Canterbury and Waikato food processing facilities face parallel FSANZ hygiene audit pressures, driving seamless resin system adoption.
Australia and New Zealand Industrial Flooring Market Competitive Environment
On the supply side, the industry is consolidating around formulation specialists with captive raw material positions and certified applicator networks. Three strategic archetypes dominate: Swiss-parent technical heritage players leveraging global R&D, regional specialists with backward-integrated cementitious supply, and rapid-cure polyurethane experts serving operational downtime constraints. Competitive moves center on disintermediation of distribution channels and direct engagement with facility engineering teams for specification authority.
Among the named participants, Sika Australia anchors the specification-driven premium tier through its parent company's technical heritage, while Mapei Australia Pty Ltd exemplifies margin protection through captive supply of cementitious screeds. Roxset Australia occupies a position within the rapid-cure specialization archetype, serving facilities where operational continuity dictates minimal installation windows. These three represent distinct strategic postures rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| MBCC Group |
| Antiskid Industries |
| Sika Australia |
| Mapei Australia Pty Ltd |
| Bethell Flooring |
| Roxset Australia |
| Multiblast Flooring Pty Ltd |
| Interface Inc |
| RPM International Inc |
| Others |
Value Chain & Pricing Dynamics
Swiss and German resin precursor concentration upstream funnels pricing power toward formulation specialists with captive amine hardener supply, compressing margin for installers locked into spot epoxy purchases. Certification-grade premiums now separate viable competitors from commodity installers across Australia and New Zealand.
Pricing Analysis
Certification level under Standards Australia AS 4586 and AS 4663 creates the primary spread between premium specification and economy installation tiers. Project-based pricing dominates, with differentiation driven by slip-rating verification burden and FSANZ hygiene compliance depth. Cost compression in standard epoxy coatings is intensifying because bisphenol A and epichlorohydrin feedstock volatility erodes fixed-contract margins. Warehouse operators exhibit highest price sensitivity, while pharmaceutical cleanroom specifiers prioritize warranty depth over unit cost.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk calculus for imported resin systems lacking local wet-pendulum certification. Geographic supply concentrates in Switzerland, Germany, and China for epoxy precursors; Australia and New Zealand domestic production centers on cementitious screed blending and aggregate processing. Raw material dependencies rest on bisphenol A, epichlorohydrin, and specialty amine curing agents. Single-source vulnerability runs through Swiss-parent technical resin supply for pharmaceutical-grade formulations. Distribution runs through specification-influencing formulators with direct facility engineering engagement, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified applicator scarcity defines competitive viability in this market, with substrate moisture testing and dew-point calculation competencies outstripping vocational training output. The capability gap rewards firms that internalize technical certification pipelines.
For Market Incumbents: Harden specification authority through captive supply of cementitious screeds and direct engagement with facility engineering teams for warranty accountability. Cementitious screed substitution by polymer-modified overlays demands backward integration into screed production to defend margin. Invest in rapid-cure polyurethane R&D to capture operational downtime intolerance in Auckland pharmaceutical and Perth mining services segments. For New Entrants and Emerging Players: Western Australia overlay demand outpaces certified applicator supply, creating white-space entry for diagnostic-capable service providers. Target building stock aging in Sydney and Melbourne warehouse precincts with substrate remediation and moisture mitigation bundled offerings. Lead with silica-based anti-slip alternatives to capture PFAS transition tailwind before incumbents reformulate. For Investors and Strategic Acquirers: Capital is best deployed toward rapid-cure polyurethane specialists with established contractor networks and FSANZ audit-response capabilities. Long-term viability hinges on regulatory compliance depth rather than commodity resin volume. Watch for convergence between WHS harmonization pressures and emerging PFAS restrictions as inflection indicator for formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Screed Production | Captive cementitious supply shields margin from resin volatility and substitution pressure. |
| Direct Formulator-Facility Engineering Engagement | Disintermediation of distribution channels compresses traditional margins while capturing specification authority. |
| Silica-Based Anti-Slip Formulation Development | PFAS restrictions under Australian environmental regulations create first-mover advantage over fluorinated additives. |
| Certified Applicator Network Expansion | Moisture-tolerant installation competency scarcity outpaces training pipeline, creating bottleneck control. |
| Rapid-Cure Polyurethane R&D Investment | Operational downtime intolerance in pharmaceutical and mining segments commands premium pricing power. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with resin formulators, certified flooring applicators, facility engineering managers, and procurement leads at food processing and pharmaceutical operators; and secondary validation through Building Code of Australia Section J compliance documentation, Standards Australia certification registries, FSANZ audit protocol updates, and customs trade data on epoxy resin imports. Bottom-up project pipeline assessment triangulated against top-down construction permit and industrial building stock aging estimates.
Forecast inputs span product type chemistry tiers, end-use regulatory exposure intensity, application performance requirements, and installation type retrofit share across the projection horizon. Segmentation dimensions modeled include material formulation, facility hygiene mandate exposure, performance duty rating, and building age cohort. CAGRs were derived from replacement cycle analysis and industrial diversification trajectories, with specific weighting for battery recycling facility construction and PFAS regulatory transition timelines.
Practitioners should monitor FSANZ audit protocol intensification, EPA Victoria PFAS restriction implementation, and skilled migration policy shifts affecting certified applicator supply for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Concrete Cooling Market