
 PVC Window Market | 2026-2036
PVC Window Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Window Market Analysis
CE marking under the Construction Products Regulation is unwinding competitive access across European markets, forcing extruders to recertify formulations for fire performance and thermal transmittance. VEKA leverages captive compounding capacity to control resin grades across its profile plants. Rehau anchors its position through systems house partnerships with mid-sized fabricators. Schuco differentiates via steel-reinforced PVC hybrid frames that penetrate commercial specification channels.
A PVC window consists of a rigid polyvinyl chloride extruded frame with multi-chambered hollow profiles, typically reinforced with galvanized steel inserts, glazed with double or triple insulated glass units, and sealed with ethylene propylene diene monomer gaskets to achieve U-values below 1.0 W/m²K. The product serves as a fixed or operable building envelope element engineered to control thermal, acoustic, and moisture transmission between conditioned interior space and exterior environments. Tilt and turn hardware configurations command premium positioning in residential replacement cycles across Central Europe. Energy-efficient performance features absorb disproportionate R&D investment as fabricators chase Passivhaus component certification and national subsidy eligibility. Custom color foiling represents a maturing margin pool where laminating lines at Eurocell and Deceuninck achieve faster batch turnaround than wet-coat alternatives.
The EU Green Deal and F-Gas Regulation shape product roadmaps by phasing down blowing agents with high global warming potential used in thermal break construction. ECHA scrutiny of PVC stabilizer chemistries, particularly legacy lead and emerging organotin alternatives, forces compounders to validate calcium-zinc formulations across accelerated weathering protocols. The European Commission's proposed revision of the Energy Performance of Buildings Directive tightens minimum U-value thresholds that PVC systems must meet to qualify for public procurement and renovation grant schemes. Stakeholders must monitor whether national transpositions accelerate retrofit mandates faster than supply chains can scale certified profile capacity.
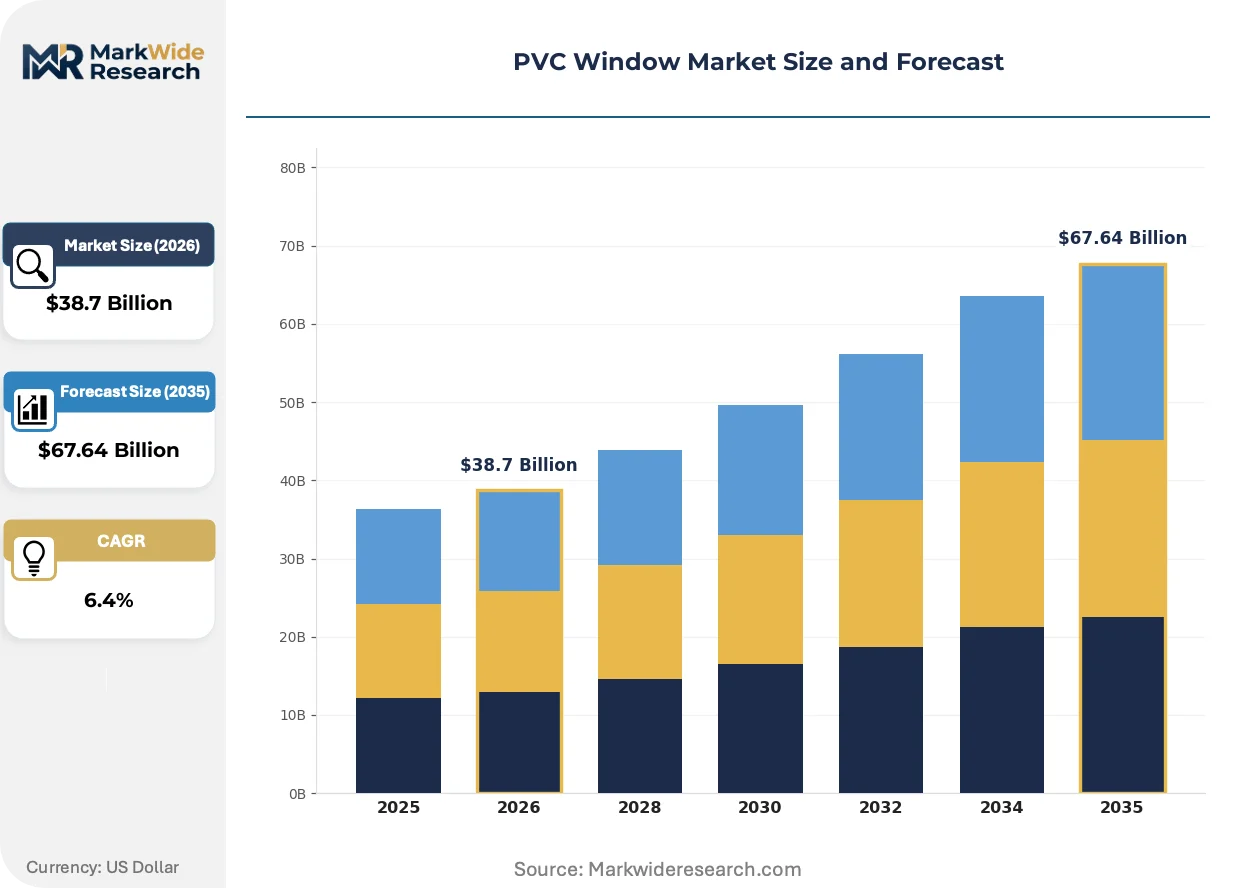
Market Dynamics
EU Green Deal enforcement is compressing the retrofit timeline for residential building envelopes, forcing fabricators to scale multi-chamber profile capacity ahead of certified supply availability.
Growth Catalysts
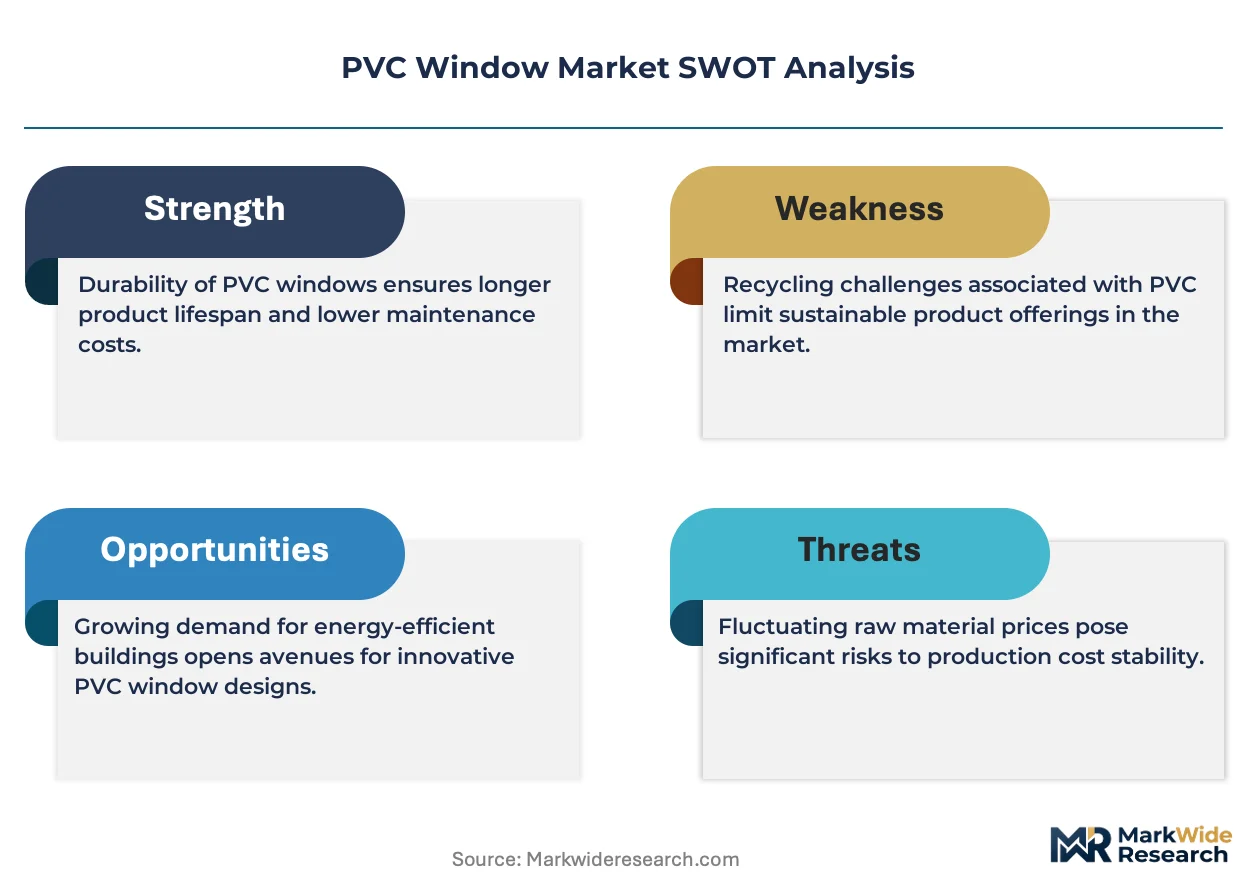
- EPBD revision:Tighter U-value thresholds in the Energy Performance of Buildings Directive qualify PVC systems for national renovation grants across member states.
- Passivhaus certification:Component-level thermal performance standards pull fabricators toward triple-glazed configurations with warm-edge spacers.
- F-Gas phase-down:Blowing agent restrictions under EU regulation accelerate calcium-zinc stabilizer validation in profile extrusion.
Market Restraints
- Resin cost volatility:PVC compound pricing tracks ethylene and chlorine feedstock swings, compressing extruder margins during upstream shocks.
- CE marking friction:Construction Products Regulation recertification for fire performance creates 12-18 month approval bottlenecks for new formulations.
- Aluminum substitution:Steel-reinforced PVC hybrids face competition from thermally broken aluminum in commercial specification channels.
Strategic Opportunities
- Polish retrofit wave:National building renovation plans under EU Recovery Funds concentrate demand for replacement window capacity in Central Europe.
- Color foiling scale:Laminating line investments enable batch-size flexibility that wet-coat alternatives cannot match in custom residential specification.
- Systems house consolidation:Mid-sized fabricators seek captive profile supply partnerships to secure thermal break technology access.
Industry Challenges
- Accelerated weathering protocols:ECHA scrutiny of stabilizer chemistries forces compounders to validate calcium-zinc alternatives across 10,000-hour test cycles.
- Steel reinforcement logistics:Galvanized insert sourcing from rolling mills requires inventory coordination that strains working capital at smaller extruders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Window Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Windows, Casement Windows, Fixed Windows, Tilt and Turn Windows End User: Residential Homes, Commercial Buildings, Industrial Facilities, Institutional Buildings Color: White, Brown, Grey, Custom Colors Performance Feature: Energy Efficient, Soundproof, UV Resistant, Impact Resistant |
| Companies Covered | Profine Group, Aluplast GmbH, VEKA, Andersen Corporation, Eurocell, Rehau, Schuco, Pella Corporation, Deceuninck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Window Market Emerging Trajectories
Profile technology and certification requirements are rewriting competitive differentiation, with thermal performance tiers separating fabricators who control formulation from those who outsource compounding.
Calcium-zinc stabilizer chemistry is supplanting legacy lead and organotin alternatives in extrusion compounds. Compounders with captive blending capacity are securing faster ECHA validation timelines. This shift is compressing the supplier base toward integrated resin controllers.
EU F-Gas Regulation phase-down timelines are forcing thermal break manufacturers to reformulate with lower-GWP blowing agents. Profile plants must requalify foam-filled chambers for CE marking under revised fire performance protocols. German fabricators are absorbing the bulk of compliance costs ahead of 2027 mandates.
Replacement cycle compression is shortening residential window procurement from 20-year intervals to 12-15 years in efficiency-conscious markets. Tilt-turn hardware specification is migrating from premium new-build segments into mid-market renovation channels. France and Belgium exhibit the fastest adoption of performance-tiered product catalogs.
PVC Window Market Segmentation
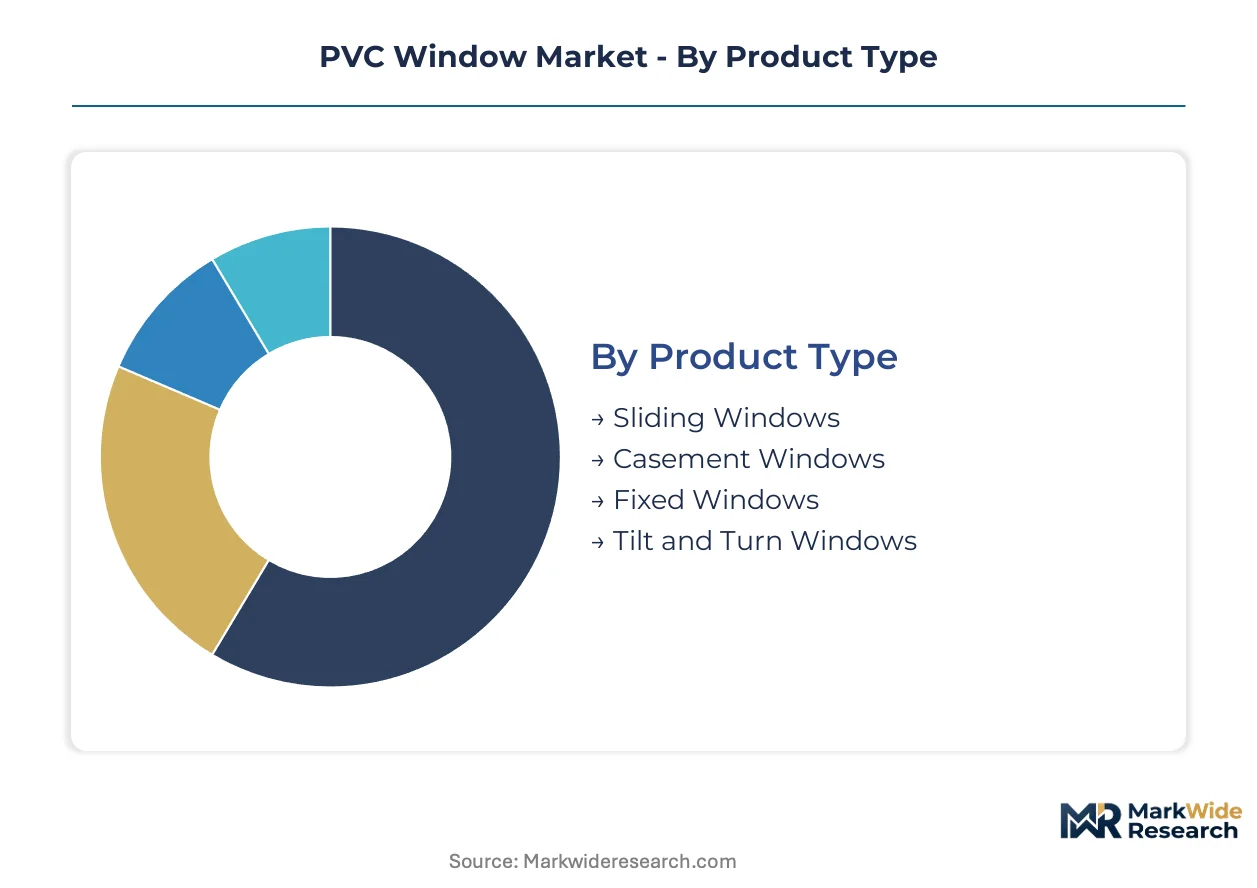
PVC window segmentation separates fabricators pursuing volume scale from those extracting premium through specialized performance tiers. Category boundaries increasingly blur as multi-chamber profiles and warm-edge spacers become baseline requirements across residential and commercial specification channels.
Product Type:
Margin pools concentrate in operable configurations where hardware complexity and thermal break engineering justify tiered pricing.
- Tilt and Turn Windows:Dual-axis hardware enables inward tilting for secure ventilation and full swing opening for cleaning access. German and Polish residential replacement cycles favor this specification where Passivhaus certification requirements pull fabricators toward triple-glazed configurations with reinforced multi-chamber frames.
- Casement Windows:Side-hinged sash construction with compression seal closure achieves U-values below 1.0 W/m²K when paired with warm-edge spacer systems. French homebuilders specify this format in new-build segments where CE marking under the Construction Products Regulation mandates validated fire performance protocols.
- Sliding Windows:Horizontal track systems with tandem roller hardware suit balcony and terrace access applications where space constraints prohibit swing clearance.
- Fixed Windows:Non-operable frame construction maximizes glazed area in curtain wall and picture window applications where thermal performance depends solely on glass and spacer specification.
The dominant share belongs to Casement Windows, while Tilt and Turn Windows is closing the gap fastest.
End User:
Volume concentration tracks EU Recovery Fund disbursement patterns, with renovation grant eligibility steering procurement toward certified fabricators.
- Residential Homes:Single-family and multi-family replacement cycles drive specification of white and custom-foiled profiles with double or triple insulated glass units. Polish and German markets exhibit the steepest expansion trajectory as national building renovation plans concentrate demand for energy-efficient envelope upgrades.
- Commercial Buildings:Office and retail facades demand larger format fixed and curtain wall configurations with steel-reinforced hybrid frames. Thermally broken aluminum competes aggressively in this segment where specification architects prioritize slim sightlines over PVC's thermal advantages.
- Industrial Facilities:Warehouse and manufacturing envelope applications favor cost-optimized sliding and fixed configurations with standard double glazing.
- Institutional Buildings:Schools, hospitals, and public administration procurement channels require extended warranty terms and documented CE marking compliance under tightened Energy Performance of Buildings Directive thresholds.
Residential Homes commands the largest volume position, with Commercial Buildings gaining share through steel-reinforced hybrid specification.
Color:
Custom batch flexibility determines margin capture as laminating line investments displace wet-coat alternatives.
- Custom Colors:Foiled finishes replicate timber grain and metallic effects through heat-laminated PVC films that withstand accelerated weathering protocols. Eurocell and Deceuninck laminating lines achieve faster turnaround than coat-applied alternatives, enabling specification-matched production for renovation contractors.
- White:Standard unpigmented PVC compound dominates volume production where cost sensitivity outweighs aesthetic differentiation in social housing and rental property segments.
- Grey:Anthracite and slate pigmentation captures mid-market positioning between standard white and premium custom foiling.
- Brown:Woodgrain-foiled and pigmented variants serve heritage and conservation area specifications where planning restrictions mandate traditional appearance.
White retains the volume base, while Custom Colors is expanding most quickly through laminating line scale advantages.
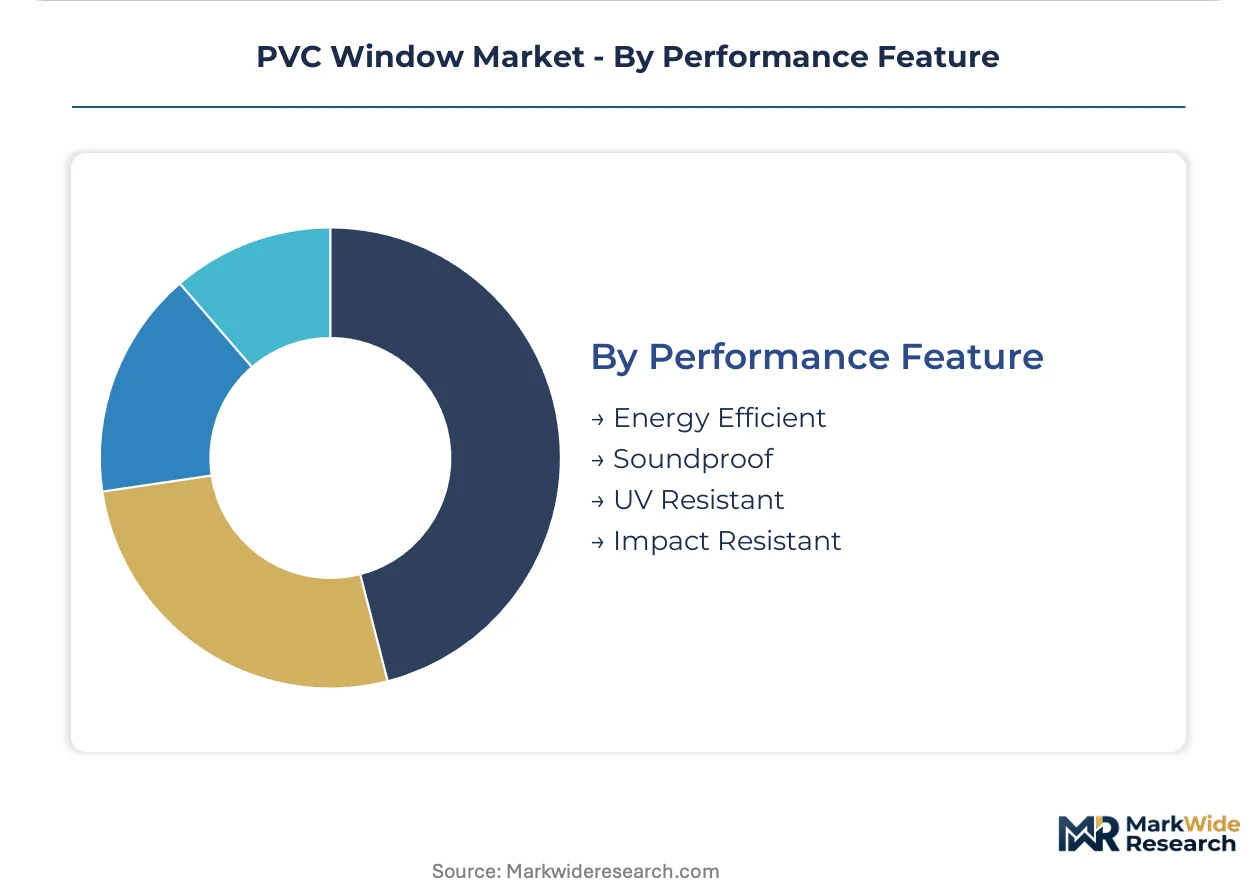
Performance Feature:
Certification tiers separate fabricators with captive compounding capacity from those dependent on outsourced resin supply.
- Energy Efficient:Multi-chamber profiles with foam-filled thermal breaks and warm-edge spacer systems achieve U-values qualifying for national renovation grants. ECHA scrutiny of stabilizer chemistries forces compounders to validate calcium-zinc formulations across 10,000-hour test cycles, compressing the supplier base toward integrated resin controllers.
- Soundproof:Acoustic laminated glass and multi-chamber frame construction address urban noise pollution in airport flight paths and dense city centers. Belgian and Dutch specifications lead adoption where regulatory noise limits tighten for residential development approvals.
- UV Resistant:Titanium dioxide pigmentation and capstock layering prevent chalking and color shift in high-solar-exposure facades.
- Impact Resistant:Laminated glass and reinforced frame construction meets security and severe weather requirements in ground-floor and coastal applications.
Energy Efficient holds the dominant specification share, with Soundproof climbing the fastest on urban density and regulatory noise limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and national renovation grant schemes are steering specification toward certified fabricators with captive thermal break capacity. Member states transposing the Energy Performance of Buildings Directive are compressing retrofit timelines faster than supply chains can scale multi-chamber profile production.
Germany
Passivhaus-certified component demand pulls fabricators toward triple-glazed tilt-turn configurations with reinforced frames. KBA and federal building codes under the EPBD national transposition mandate U-values below 0.85 W/m²K for grant eligibility. The Rhine-Ruhr industrial corridor concentrates extrusion capacity where VEKA and Rehau operate integrated compounding plants.
Poland
EU Recovery Fund disbursements are accelerating residential replacement cycles in single-family housing stock. The national building renovation plan channels subsidies toward energy-efficient envelope upgrades meeting tightened thermal transmittance thresholds. The Silesian and Greater Poland voivodeships host expanding fabricator clusters serving Central European export markets.
France
ANAH renovation grants and tightened RT2012 thermal regulations are displacing single-glazed alternatives in social housing retrofits. Casement window specifications dominate new-build segments where CE marking mandates validated fire performance protocols. The Hauts-de-France and Auvergne-Rhône-Alpes regions exhibit the steepest fabricator capacity expansion.
United Kingdom
Building Regulations Part L revisions and Future Homes Standard alignment are tightening U-value requirements for replacement windows. Fabricators pursuing PAS 24 security certification are capturing insurance-backed installation channels. The Midlands and North West England concentrate profile extrusion and systems house distribution networks.
Belgium
Regional noise limit regulations in Flanders and Brussels are driving specification of acoustic-rated multi-chamber frames with laminated glass. Urban density mandates pull fabricators toward soundproof performance tiers. The Flemish manufacturing belt around Ghent and Antwerp hosts specialized laminating lines for custom color foiling.
PVC Window Market Vendor Landscape
Listed leaders compete with private specialists across formulation control and thermal break technology. The vendor base clusters around three tiers: integrated resin compounders with captive extrusion, systems houses partnering with mid-sized fabricators, and regional specialists focused on custom color batch flexibility. Strategic differentiation centers on CE marking speed, laminating line scale, and Passivhaus certification access. Consolidation pressure is mounting as ECHA validation timelines compress the supplier base toward integrated players with accelerated weathering protocol capabilities.
Among German-based integrated compounders, VEKA and Rehau exemplify the resin-control archetype that dominates thermal break technology access. Deceuninck represents the Belgian specialist position in custom color foiling scale. These three anchors illustrate how geographic concentration around regulatory hubs shapes competitive positioning across formulation validation and laminating line investment cycles.
| Leading Market Players |
|---|
| Profine Group |
| Aluplast GmbH |
| VEKA |
| Andersen Corporation |
| Eurocell |
| Rehau |
| Schuco |
| Pella Corporation |
| Deceuninck |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month CE marking recertification timelines for fire performance and thermal transmittance create inventory positioning advantages for German and Belgian compounders with captive blending capacity, compressing pricing power toward integrated extruders while fragmenting margin capture among outsourced resin buyers.
Pricing Analysis
Certification level under the Construction Products Regulation creates the primary spread between premium Passivhaus-certified systems and standard CE-marked alternatives. Pricing stratifies across premium, standard, and economy tiers where multi-chamber profile thermal performance and warm-edge spacer specification drive differentiation. Cost compression in economy-grade single-glazed replacement segments intensifies as Polish fabricators scale capacity ahead of EU Recovery Fund disbursement. Social housing procurement channels exhibit highest price sensitivity, while commercial specification through systems house partnerships demonstrates lowest.
Supply Chain Analysis
Galvanized steel insert sourcing from German and Polish rolling mills represents a chokepoint that strains working capital at smaller extruders lacking rolling mill partnerships. PVC resin supply concentrates in Germany, Belgium, and the Netherlands where integrated compounders control formulation validation. Feedstock costs hinge on ethylene and chlorine derivative pricing volatility. Distribution runs through systems house partnerships with mid-sized fabricators rather than direct specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVC window market is approaching a platform-economics inflection where thermal break technology access and CE marking speed determine ecosystem participation, with interoperability between profile extruders and hardware suppliers reshaping competitive boundaries.
For Market Incumbents: Shield formulation control advantages by accelerating calcium-zinc stabilizer validation ahead of ECHA scrutiny timelines, and secure captive thermal break capacity through backward integration into foam-filled chamber production to offset aluminum substitution threats in commercial channels. For New Entrants and Emerging Players: Lead with custom color foiling batch flexibility in Polish and French renovation markets where laminating line scale advantages enable specification-matched production for mid-sized contractors, leveraging faster turnaround than wet-coat alternatives to capture margin pools in heritage and conservation area specifications. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EPBD national transpositions and F-Gas phase-down timelines compress the supplier base toward integrated compounders with accelerated weathering protocol capabilities. Target acquisition archetypes include mid-sized fabricators with systems house partnerships seeking thermal break technology access. The signal to watch is Polish national building renovation plan disbursement velocity against certified profile capacity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Calcium-Zinc Stabilizer Validation | ECHA compliance timelines compress supplier base toward integrated resin controllers with captive compounding. |
| Systems House Partnership Expansion | Mid-sized fabricators seek captive profile supply to secure thermal break technology and CE marking speed. |
| Laminating Line Capacity Investment | Custom color foiling scale enables batch-size flexibility that wet-coat alternatives cannot match. |
| Passivhaus Component Certification | Triple-glazed tilt-turn configurations qualify for national renovation grants across German and Polish markets. |
| Steel-Reinforced Hybrid Frame Development | Thermally broken aluminum competition in commercial channels demands differentiated structural performance. |
Methodological Framework
A standing panel of profile extrusion plant managers, systems house procurement directors, ECHA regulatory affairs specialists, and national building renovation plan administrators provided ongoing calibration across primary interview cycles. Secondary validation drew from CE marking notification body filings, Construction Products Regulation harmonized standards databases, EU Recovery Fund disbursement trackers, and national energy agency renovation grant registries. Bottom-up fabricator capacity assessments triangulated against top-down envelope retrofit demand modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, end user, color specification, and performance feature dimensions. CAGRs were derived from fitted growth curves incorporating EPBD transposition timelines, F-Gas phase-down mandates, and replacement cycle compression patterns. Industry-specific forecast inputs included ECHA stabilizer validation pipeline status and systems house partnership formation velocity.
Forecasts assume regulatory continuity in EU Green Deal implementation and EPBD national transposition regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
North America Ceiling Tiles Market