
 Precast Concrete Market | 2026-2036
Precast Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Concrete Market Analysis
ISO 9001 quality management certification is redrawing competitive boundaries in precast concrete supply. Holcim leverages its vertically integrated cement-to-concrete pipeline to secure specification-grade projects across multiple continents. CEMEX sustains market presence through R&D intensity in low-carbon mix designs. Gulf Precast anchors its position via manufacturing scale and channel control across Middle Eastern infrastructure corridors.
Precast concrete refers to factory-cast structural and architectural elements produced under controlled conditions using Portland cement, aggregates, admixtures, and reinforcement, then transported to site for assembly. Standard compressive strengths range from 4,000 to 6,000 psi depending on application, with curing cycles typically spanning 12 to 24 hours in steam-assisted environments. Flooring Systems currently occupy the largest product-type position due to repetitive span requirements in commercial and residential mid-rise construction. Modular Construction technology is displacing traditional casting in labor-scarce markets, though margin pools remain thicker in Architectural Elements where customization commands specification premiums. Infrastructure Projects as an end-user segment leads volume absorption, driven by bridge decks, tunnel segments, and drainage systems with long replacement cycles.
The EU Green Deal's embodied carbon thresholds and the EPA's construction sector emissions guidelines are tightening material sourcing and transport protocols. India's BIS certification for precast structural elements and the PLI scheme for building-product manufacturing are reshaping domestic capacity expansion. China's dual carbon goals and GB standards for green building materials are filtering import eligibility and mix-design approvals. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to partition supply chains into incompatible technical zones.
Market Dynamics
EU Green Deal embodied carbon thresholds are forcing material substitutions across precast supply chains, compressing Portland cement volumes while accelerating supplementary cementitious material adoption in factory casting environments.
Growth Catalysts
- India PLI Scheme:Production-linked incentives for construction-linked manufacturing are channeling domestic capacity expansion toward structural precast elements for smart city corridors.
- Modular Construction:Offsite fabrication protocols are accelerating project delivery timelines in labor-scarce Middle Eastern and Southeast Asian urban centers.
- EU Green Deal:Embodied carbon regulations are mandating cleaner mix designs and low-carbon transport protocols across European infrastructure procurement.
Market Restraints
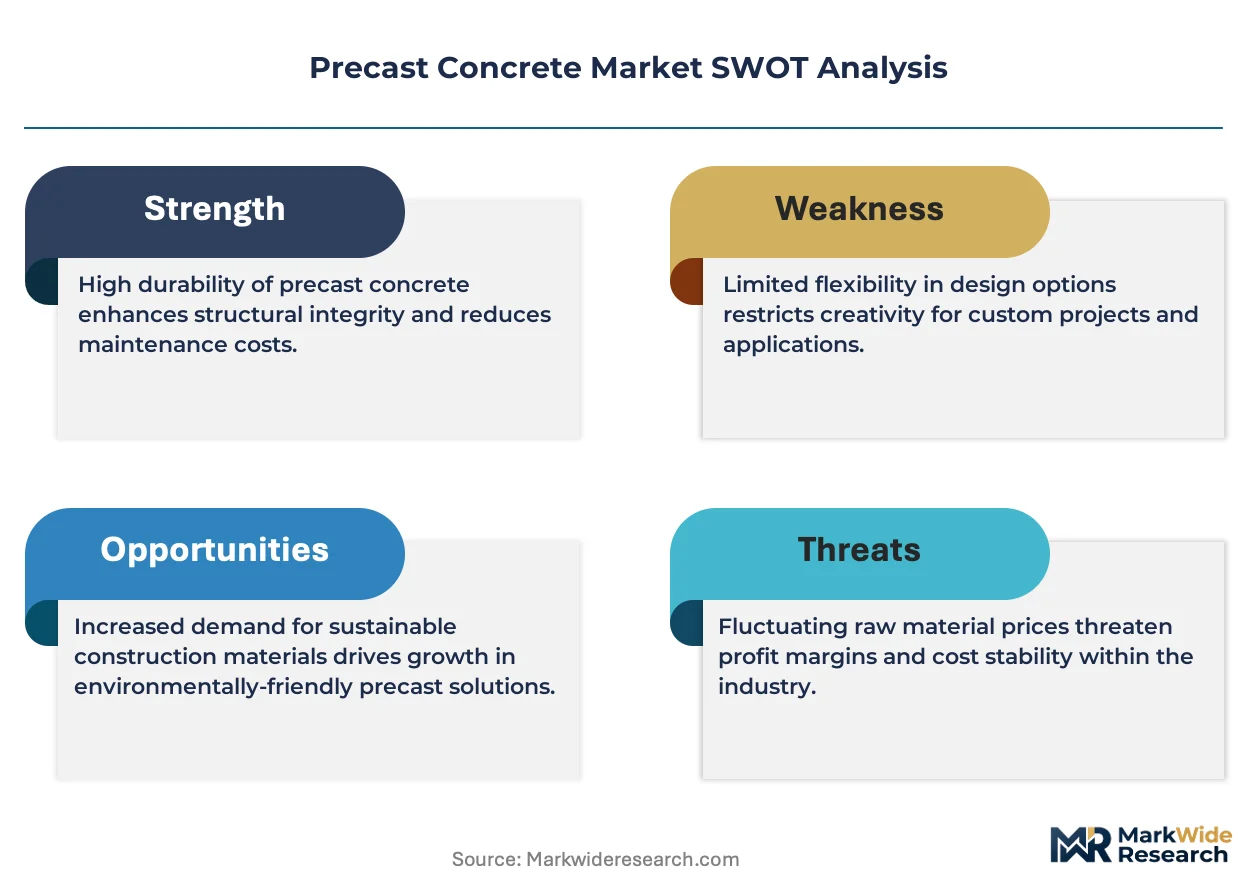
- Portland Cement Price Volatility:Energy-intensive clinker production exposes margins to natural gas and electricity cost swings in European and Asian manufacturing zones.
- Transport Radius Limitations:Precast elements face 200-300 kilometer economic haul limits, fragmenting supply into geographically captive sub-markets.
- Steel Reinforcement Substitution:Fiber-reinforced polymer and carbon fiber alternatives are capturing specification share in corrosion-sensitive coastal infrastructure.
Strategic Opportunities
- Saudi Giga-Projects:NEOM and Red Sea developments are generating concentrated demand for architectural precast cladding and structural tunnel segments.
- Carbon Capture Integration:Post-combustion capture systems at precast plants can monetize CO2 as feedstock for concrete curing acceleration.
- Digital Fabrication Convergence:BIM-to-CAM workflows are compressing design-to-delivery cycles for complex geometric facade elements.
Industry Challenges
- ISO 9001 Certification Timelines:Quality management system accreditation requires 12-18 month implementation cycles, gating specification-grade project access.
- Steam Curing Energy Costs:Accelerated curing chambers consume 40-60% of plant energy budgets, exposing margins to utility tariff volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Concrete Market |
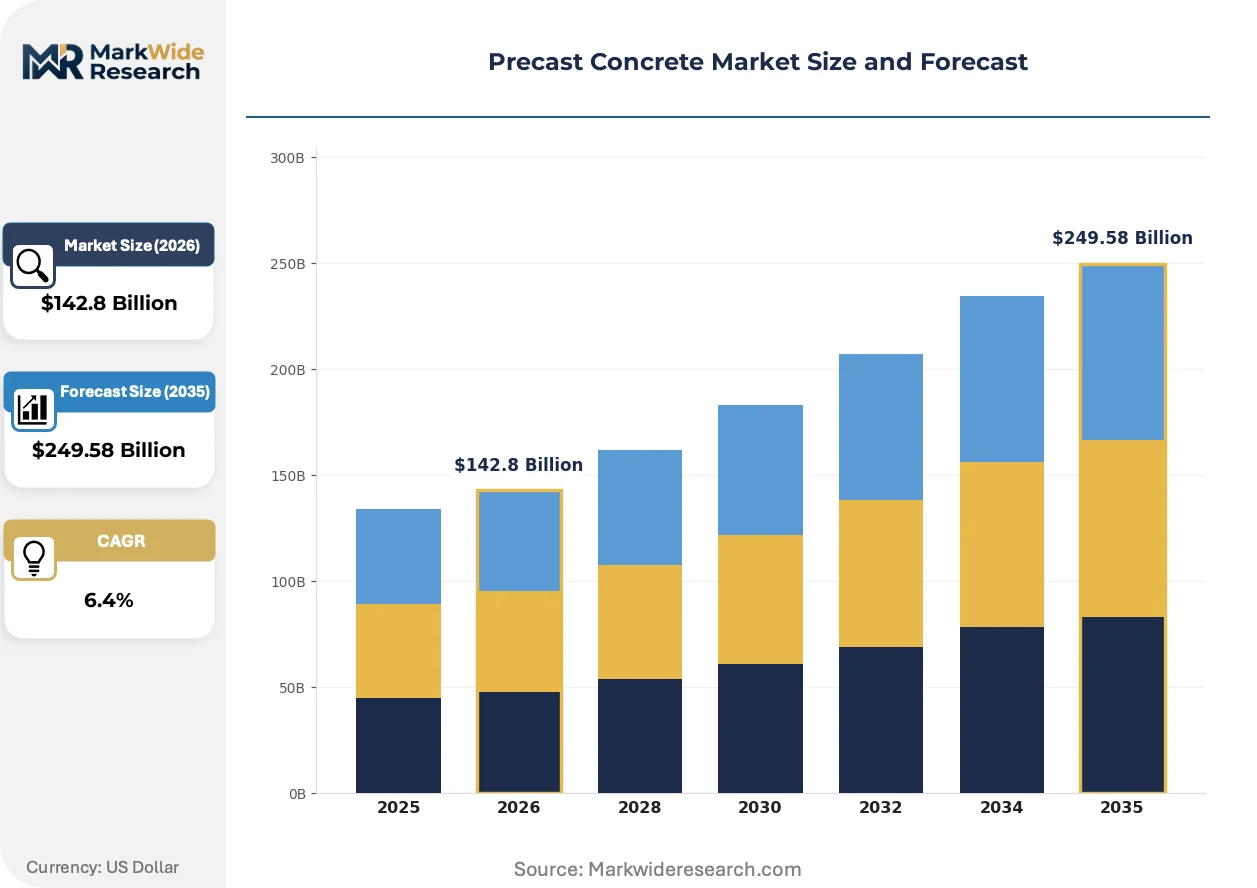
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $249.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Flooring Systems, Concrete Beams, Architectural Elements End User: Residential Buildings, Commercial Structures, Infrastructure Projects, Industrial Facilities Application: Building Construction, Transportation, Heavy Civil Engineering, Pre-Engineered Structures Technology: Traditional Casting, 3D Printing, Automated Manufacturing, Modular Construction |
| Companies Covered | Forterra, Holcim, Oldcastle Infrastructure, CRH, HeidelbergCement, Tindall Corporation, CEMEX, Gulf Precast, Spancrete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Concrete Market Emerging Trajectories
Factory automation and carbon accounting protocols are converging to reshape competitive positioning in precast manufacturing, compressing legacy batch-and-queue production models while elevating data-integrated supply chains.
Self-consolidating concrete formulations are decomposing traditional vibration-based casting workflows. Infrastructure contractors in Germany and the Netherlands are specifying these flowable mixes for densely reinforced bridge segments. The technology is decomposing labor intensity in precast plants while enabling thinner wall sections and reduced material volumes.
REACH chemical authorization requirements are restricting polycarboxylate ether superplasticizer formulations across European precast production. Manufacturers are reformulating admixture suites to maintain workability windows under tightened substance restrictions. Architectural elements with complex surface finishes face the steepest compliance adaptation costs.
Buyers are consolidating specification authority into centralized procurement desks at major infrastructure developers. Traditional distributor networks are losing channel control as direct manufacturer relationships capture volume commitments. This concentration is most visible in Indian smart city authorities and Saudi sovereign project vehicles.
Precast Concrete Market Segmentation
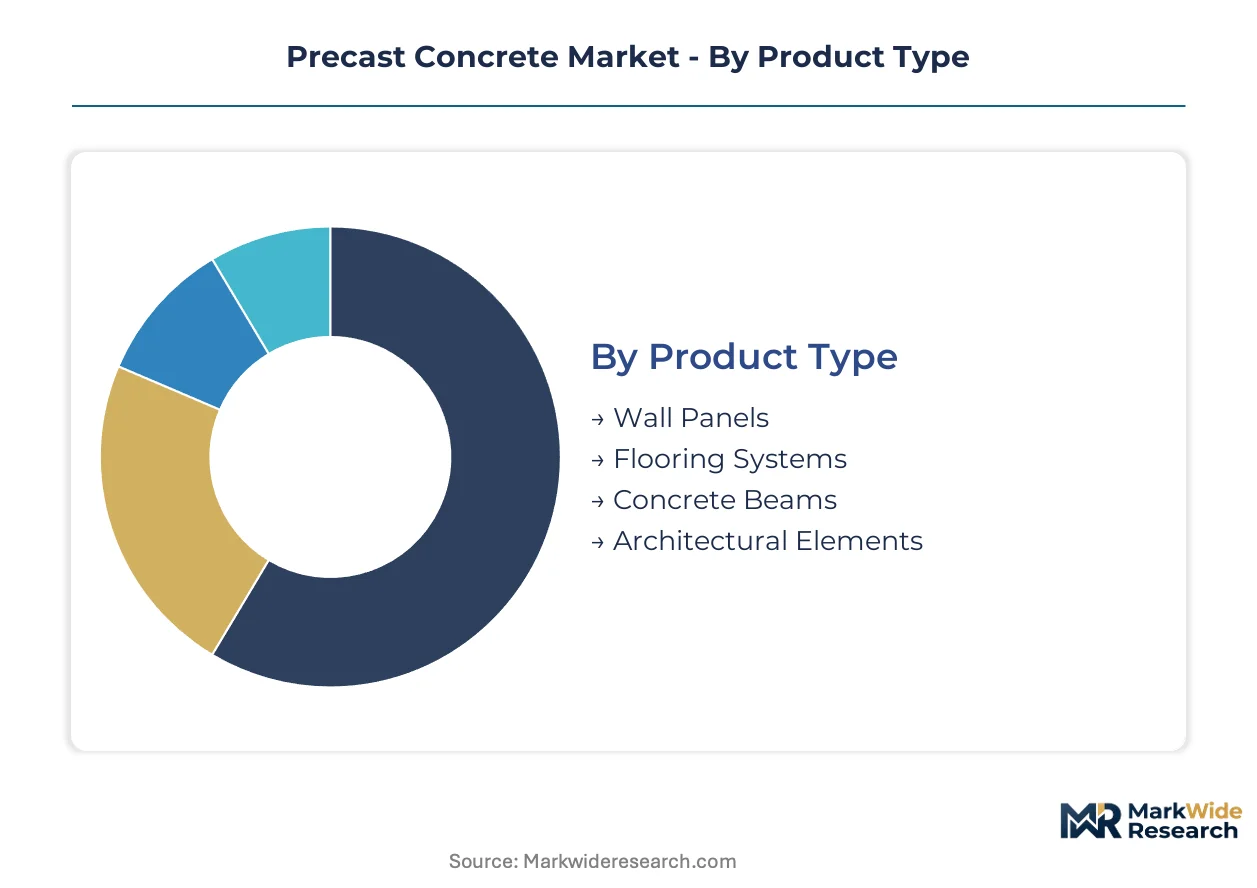
Precast concrete manufacturers configure production lines around segment-specific curing protocols and mold inventories. Product mix decisions determine capital allocation between standardized structural elements and custom architectural components.
Product Type:
Domestic markets absorb repetitive structural elements; export flows concentrate in specification-grade architectural components for premium developments.
- Wall Panels:Sandwich configurations with insulation cores dominate mid-rise residential envelopes. German and Dutch housing cooperatives specify these for thermal performance compliance. Energy code tightening accelerates substitution of site-cast alternatives.
- Flooring Systems:Hollow-core planks and double-tee configurations serve repetitive span requirements in commercial mid-rise construction. Indian smart city authorities specify these for transit-oriented development corridors. Labor scarcity in Middle Eastern urban centers amplifies offsite fabrication demand.
- Concrete Beams:Prestressed I-girders and box girders carry bridge deck loads across highway and rail infrastructure.
- Architectural Elements:Custom facade cladding and ornamental components command specification premiums in Saudi giga-projects and European cultural institutions.
Flooring Systems holds the largest share; momentum sits with Architectural Elements.
End User:
Cost tiers separate commodity structural supply from performance-specified segments with extended qualification cycles.
- Residential Buildings:Mid-rise multifamily and single-family detached segments consume standardized wall and floor elements. Indian affordable housing missions and Middle Eastern worker accommodation projects concentrate volume absorption. Mortgage rate sensitivity compresses speculative development timelines.
- Infrastructure Projects:Bridge decks, tunnel segments, and drainage systems require 50-100 year design life specifications. EU Green Deal embodied carbon thresholds filter contractor eligibility for public procurement. Long replacement cycles insulate demand from cyclical construction volatility.
- Commercial Structures:Office and retail shells utilize repetitive bay modules for speed-to-market delivery.
- Industrial Facilities:Warehouse clear-span requirements and heavy floor loadings drive beam-and-column system specifications.
Infrastructure Projects anchors volume absorption; Residential Buildings is expanding most quickly.
Application:
Application selection dictates mix design complexity and certification requirements across project portfolios.
- Building Construction:Structural frames and envelope systems constitute the core revenue pool. Indian PLI scheme incentives channel domestic capacity toward vertical construction elements. BIM integration accelerates design-to-fabrication handoffs.
- Transportation:Bridge components, rail sleepers, and airport pavement elements face extreme fatigue loading specifications. German and Japanese rail authorities enforce proprietary design standards that fragment supplier eligibility. Carbon fiber reinforcement penetration is highest in coastal exposure zones.
- Heavy Civil Engineering:Dam segments, marine structures, and utility vaults demand specialized curing protocols.
- Pre-Engineered Structures:Factory-built modules for rapid deployment in remote or constrained sites.
Building Construction captures the dominant share; Transportation shows the steepest expansion trajectory.
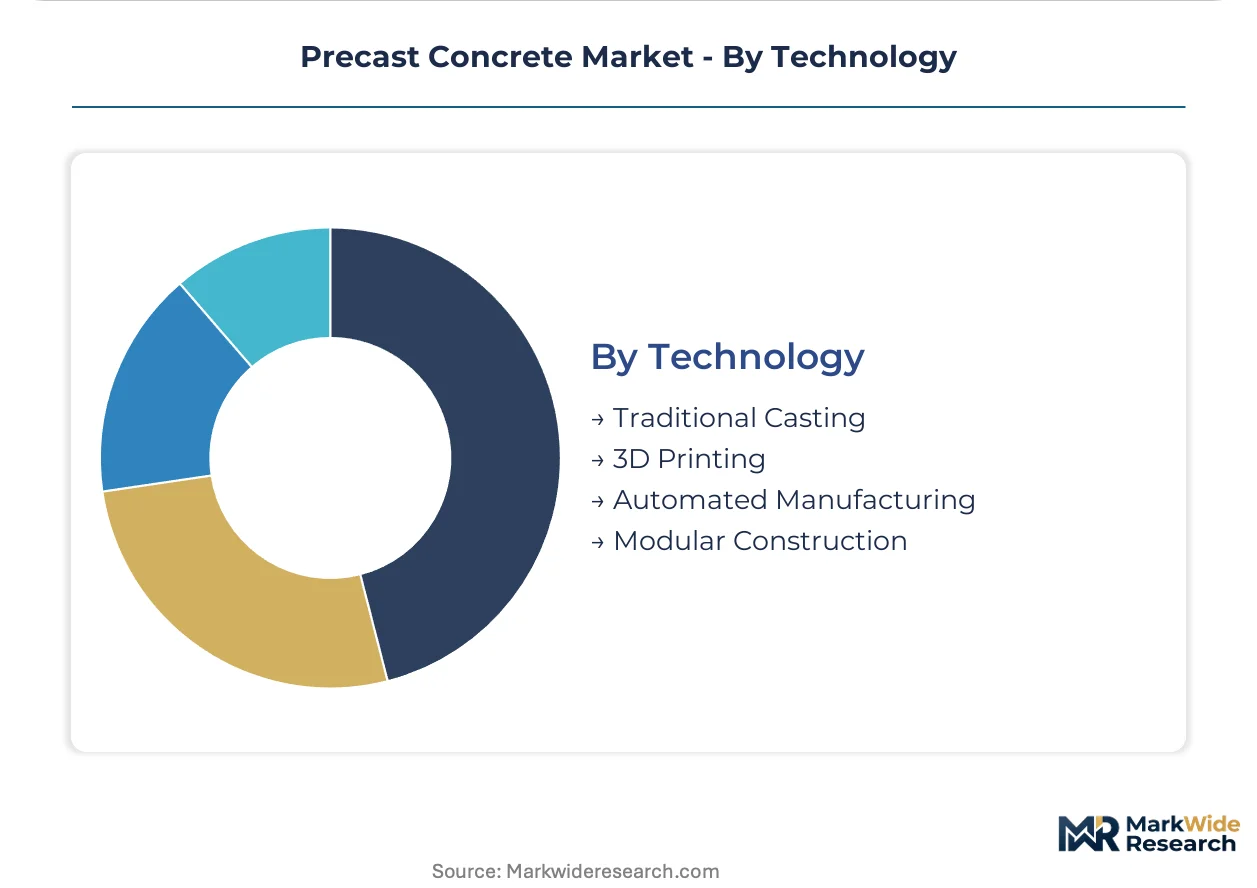
Technology:
Technology maturity curves separate legacy batch operations from capital-intensive automated platforms.
- Modular Construction:Volumetric preassembly of complete room modules compresses site labor requirements. Saudi NEOM and Red Sea developments generate concentrated demand for integrated MEP pre-installation. Factory throughput constraints limit supplier participation to scaled manufacturers.
- Automated Manufacturing:Robotic formwork handling and automated concrete dispensing reduce cycle variability. Dutch and German plants lead implementation density. ISO 9001 certification gates access to specification-grade project pipelines.
- Traditional Casting:Stationary molds with manual vibration and finishing dominate emerging market production.
- 3D Printing:Binder jetting and extrusion-based methods enable complex geometric facade elements without formwork costs.
Traditional Casting retains volume leadership; Modular Construction is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure procurement desks in Germany, India, Saudi Arabia, and the United States concentrate specification authority for structural precast elements. These buyer archetypes channel volume toward certified manufacturers with integrated quality systems and low-carbon mix capabilities.
Germany
Bridge rehabilitation programs and rail corridor upgrades absorb prestressed beam and tunnel segment production. REACH chemical authorization requirements restrict polycarboxylate ether superplasticizer formulations, forcing admixture suite reformulations. The Ruhr industrial cluster hosts automated casting facilities serving Dutch and Belgian cross-border infrastructure contracts.
India
Smart city transit-oriented developments and affordable housing missions drive hollow-core plank and wall panel demand. The PLI scheme for construction-linked manufacturing channels domestic capacity expansion toward structural elements. Gujarat's industrial corridor anchors new precast plants supplying Mumbai-Ahmedabad high-speed rail segments.
Saudi Arabia
NEOM and Red Sea giga-projects generate concentrated demand for architectural cladding and modular room units. The Saudi national regulator enforces embodied carbon disclosure for public infrastructure procurement. The Eastern Province manufacturing zone scales tunnel segment production for Riyadh metro extensions.
United States
EPA construction sector emissions guidelines tighten material sourcing protocols for federal infrastructure awards. State departments of transportation consolidate prestressed girder procurement into multi-year framework agreements. Texas and Florida coastal markets specify corrosion-resistant mix designs for bridge deck replacements.
China
Dual carbon goals and GB standards for green building materials filter import eligibility and domestic mix-design approvals. Yangtze River Delta urban renewal projects absorb prefabricated facade elements for commercial retrofits. Zhejiang province hosts automated plants serving Shanghai's rail and airport expansion programs.
Precast Concrete Market Vendor Landscape
Player mix skews toward vertically integrated cement-to-concrete conglomerates with captive aggregate and reinforcement supply. The supplier base concentrates around three strategic archetypes: multinational building materials groups with specification-grade certification, regional specialists anchored to infrastructure corridors, and technology-forward fabricators with automated casting platforms. Competitive moves center on ISO 9001 quality system accreditation and carbon capture integration at plant level.
Among the multinational tier, Holcim and CEMEX occupy positions defined by upstream control over cement supply and R&D intensity in low-carbon formulations. Gulf Precast anchors the Middle Eastern specialist archetype through manufacturing scale across Saudi and UAE infrastructure corridors. HeidelbergCement represents the European integrated model with emphasis on factory automation and REACH compliance adaptation.
| Leading Market Players |
|---|
| Forterra |
| Holcim |
| Oldcastle Infrastructure |
| CRH |
| HeidelbergCement |
| Tindall Corporation |
| CEMEX |
| Gulf Precast |
| Spancrete |
| Others |
Supply Flow & Price Mechanics
Plant-level scale economies in automated hollow-core plank production concentrate supply among German and Dutch manufacturers with 24-hour curing cycles, compressing price floors for standardized structural elements while elevating premiums for specification-grade architectural components in Saudi giga-projects.
Pricing Analysis
Cost-plus contracts with Portland cement indexation dominate procurement for infrastructure beams and tunnel segments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified manufacturers from uncertified regional suppliers from commodity importers. Pricing pressure stems from energy tariff volatility in steam-curing operations. Residential developers in India exhibit highest price sensitivity; European cultural institutions show lowest.
Supply Chain Analysis
Strategic stockpiling of polycarboxylate ether superplasticizers buffers REACH compliance disruptions in European plants, while just-in-time aggregate delivery prevails in Indian corridor projects. Manufacturing concentrates in Germany, India, and Saudi Arabia. Supply draws from clinker, steel reinforcement, and chemical admixture inputs. Single-source vulnerability sits with Chinese-origin SCMs. Distribution runs through direct manufacturer relationships with consolidated procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU Green Deal, Indian PLI scheme, and Saudi embodied carbon disclosure creates white-space niches for specialized compliance service providers and regional certification specialists.
For Market Incumbents: Compound specification-grade project access through accelerated ISO 9001 accreditation timelines in Gujarat and Eastern Province manufacturing zones. Defend margin position against fiber-reinforced polymer substitution by integrating carbon capture curing systems that monetize CO2 feedstock. Prioritize backward integration into captive SCM supply to buffer REACH chemical authorization volatility.
For New Entrants and Emerging Players: Digital fabrication consulting for BIM-to-CAM workflow integration offers underserved territory where incumbent automation lags. Target Indian smart city transit-oriented developments as the most penetrable segment. Lead with design-to-delivery cycle compression as the go-to-market wedge against legacy batch-and-queue competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated manufacturers with multi-year framework agreements from state transportation departments. Five-to-ten year viability favors plants with integrated carbon capture and low-carbon mix R&D pipelines. Target acquisition archetype: regional specialists with infrastructure corridor anchoring but lacking certification. Watch Saudi giga-project award velocity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Post-combustion systems at precast plants monetize CO2 as concrete curing accelerator feedstock. |
| ISO 9001 Certification Investment | Quality management accreditation gates access to German bridge rehabilitation and Dutch rail contracts. |
| Backward Integration into SCM Supply | Captive supplementary cementitious material production buffers REACH authorization disruptions. |
| BIM-to-CAM Workflow Deployment | Digital fabrication convergence compresses design-to-delivery for complex geometric facade elements. |
| Regional Capacity Expansion | Gujarat and Eastern Province plants capture Indian PLI scheme incentives and Saudi giga-project demand. |
Methodological Framework
The analysis maps flooring systems, wall panels, architectural elements, and beam configurations, each validated through procurement managers at infrastructure developers, plant operations directors, admixture technical sales leads, and smart city authority engineers. Primary interview intelligence triangulates against customs trade data, BIS certification registries, EU Green Deal implementation trackers, and SEC filings from listed building materials groups. Bottom-up plant capacity aggregation cross-checks with top-down construction spend allocation across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across product type, end user, application, and technology segmentation dimensions. CAGRs derive from modeled capacity utilization curves and project pipeline visibility. Forecast inputs incorporate steam curing energy cost trajectories and embodied carbon threshold compliance timelines without year-specific anchoring.
Forecasts assume regulatory continuity in EU Green Deal, Indian PLI scheme, and Saudi national procurement disclosure regimes; material policy shifts would require re-modeling. Revision becomes warranted when Portland cement price volatility or REACH chemical authorization scope crosses thresholds that alter mix-design economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market