
 Gear Grinding Machine Market | 2026-2036
Gear Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Grinding Machine Market Analytics
High-speed steel is restructuring conventional abrasive wheel economics as cubic boron nitride and diamond superabrasives displace legacy alumina bonds in precision gear finishing. Gleason Corporation leverages its vertical integration into cutting tool supply to sustain premium positioning across bevel gear applications. Klingelnberg anchors European demand through its measurement-integrated grinding systems that close the loop between inspection and corrective machining. Reishauer competes on continuous generating grinding throughput, dominating automotive transmission volume production with sub-micron pitch accuracy.
A gear grinding machine removes material from hardened gear tooth flanks to achieve precise geometric tolerances, surface finish requirements typically below Ra 0.4 micrometers, and corrected profiles that compensate for elastic deformation under load. CNC gear grinders lead technology adoption as closed-loop thermal compensation and direct-drive rotary tables displace mechanical indexers in high-value applications. Energy sector demand for large-diameter wind turbine ring gears extends profile grinder order backlogs, while surface grinders retain share in refurbishment and repair operations where capital intensity constraints apply.
ISO standards govern gear accuracy classification and load capacity verification, while EPA and OSHA frameworks in the United States regulate coolant mist exposure and metallic particulate emissions in grinding operations. The EU Machinery Directive and CE marking requirements shape market access for European-built and imported equipment. Stakeholders must monitor how evolving carbon border adjustments and energy efficiency mandates redirect procurement criteria toward machines with regenerative drives and minimum quantity lubrication systems.
Market Dynamics
ISO 6336 load capacity tolerances and AGMA 2001-D04 accuracy standards are forcing automotive OEMs to retire mechanical indexers for closed-loop thermal compensation systems, restructuring capital allocation across precision gear finishing.
Growth Catalysts
- Electric Drivetrain Expansion:Automotive OEMs in Germany, Japan, and China are scaling precision gear production for battery electric vehicle transmissions, pulling demand for sub-micron pitch accuracy equipment.
- Wind Energy Infrastructure:Large-diameter ring gear orders for offshore turbines are extending profile grinder backlogs as energy developers pursue higher torque density drivetrains.
- Superabrasive Material Transition:Cubic boron nitride and diamond bonds are displacing alumina wheels in hardened gear finishing, reducing cycle times and wheel change frequency.
Market Restraints
- Capital Intensity Barriers:CNC gear grinders with direct-drive rotary tables and thermal compensation require substantial upfront investment, constraining adoption among independent job shops.
- Supply Concentration Risk:Precision spindle and linear motor production concentrates in Japanese and German machine tool component networks, exposing lead time vulnerability.
- Technical Limitation on Scale:Continuous generating grinding throughput advantages diminish for batch sizes below fifty units, limiting flexibility in aerospace and medical gear applications.
Strategic Opportunities
- Refurbishment Service Expansion:Surface grinders retain installed base in repair operations where capital constraints prevent new equipment acquisition, creating aftermarket tooling and service revenue.
- Minimum Quantity Lubrication Integration:EU Machinery Directive energy efficiency mandates are redirecting procurement toward machines with regenerative drives and MQL coolant systems.
- Measurement-Integrated Systems:Converging in-process metrology and corrective machining is compressing quality assurance cycles for tier-one automotive supplier networks.
Industry Challenges
- Skilled Operator Scarcity:CNC gear grinder programming and superabrasive wheel dressing require specialized competencies that vocational pipelines in Germany and Japan struggle to replenish.
- Certification Timeline Compression:ISO 1328 accuracy classification verification and CE marking documentation extend delivery schedules for European-built equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Grinding Machine Market |
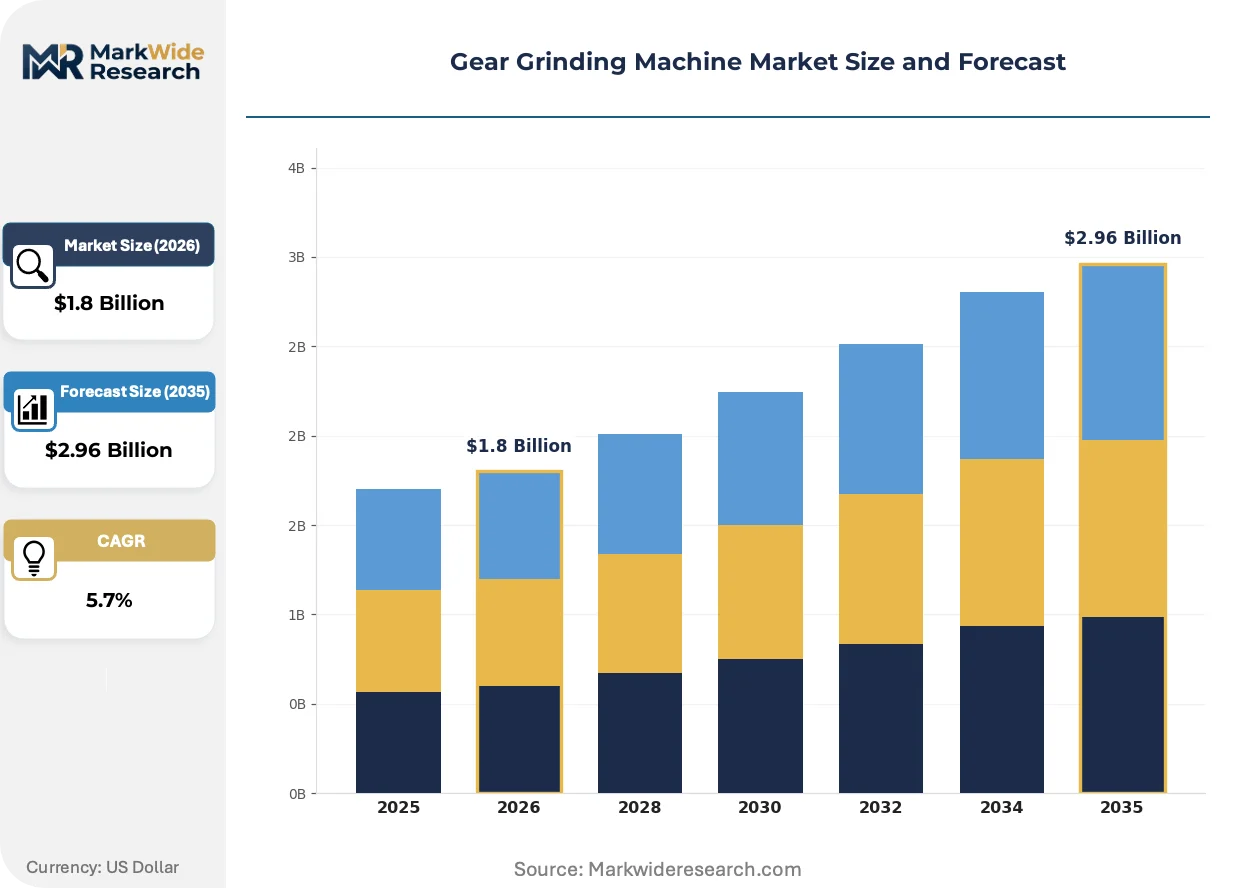
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Gear Grinders, Surface Grinders, Bevel Gear Grinders, Profile Grinders End User: Aerospace, Automotive, Industrial Machinery, Energy Application: Gear Manufacturing, Tool Production, Automotive Components, Heavy Machinery Technology: Conventional, CNC, Abrasive, Erosion |
| Companies Covered | Gleason Corporation, Klingelnberg, Liebherr, Kapp Werkzeugmaschinen, Reishauer, FFG Werke, Samputensili, Qinchuan, Chongqing Machine Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Grinding Machine Market Evolving Landscape
Direct-drive rotary table architecture and in-process measurement loops are converging to compress the inspection-to-correction cycle, while regulatory pressure on coolant emissions and energy consumption is reshaping equipment specification criteria.
Closed-loop thermal compensation systems are electrifying precision gear grinding by eliminating thermal drift during extended production runs. Automotive transmission manufacturers in Germany and Japan are adopting these systems at accelerating rates for high-volume electric drivetrain gear production. This capability is electrifying the competitive separation between premium CNC platforms and legacy mechanical indexers in sub-micron accuracy applications.
REACH chemical restrictions and EPA coolant mist exposure limits are tightening permissible emissions in grinding operations. Machine builders must now engineer minimum quantity lubrication and regenerative drive systems to maintain market access in Europe and North America. Surface grinder and profile grinder categories face divergent compliance timelines, with large-format equipment encountering stricter scrutiny due to higher volumetric coolant throughput.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into componentized offerings for spindle rebuild, software updates, and metrology recalibration. Tier-one automotive suppliers in China are driving this shift by insourcing preventive maintenance while outsourcing specialized repairs. This pattern is most visible in the Yangtze River Delta machine tool cluster, where supplier concentration enables third-party service competition.
Gear Grinding Machine Market Segmentation
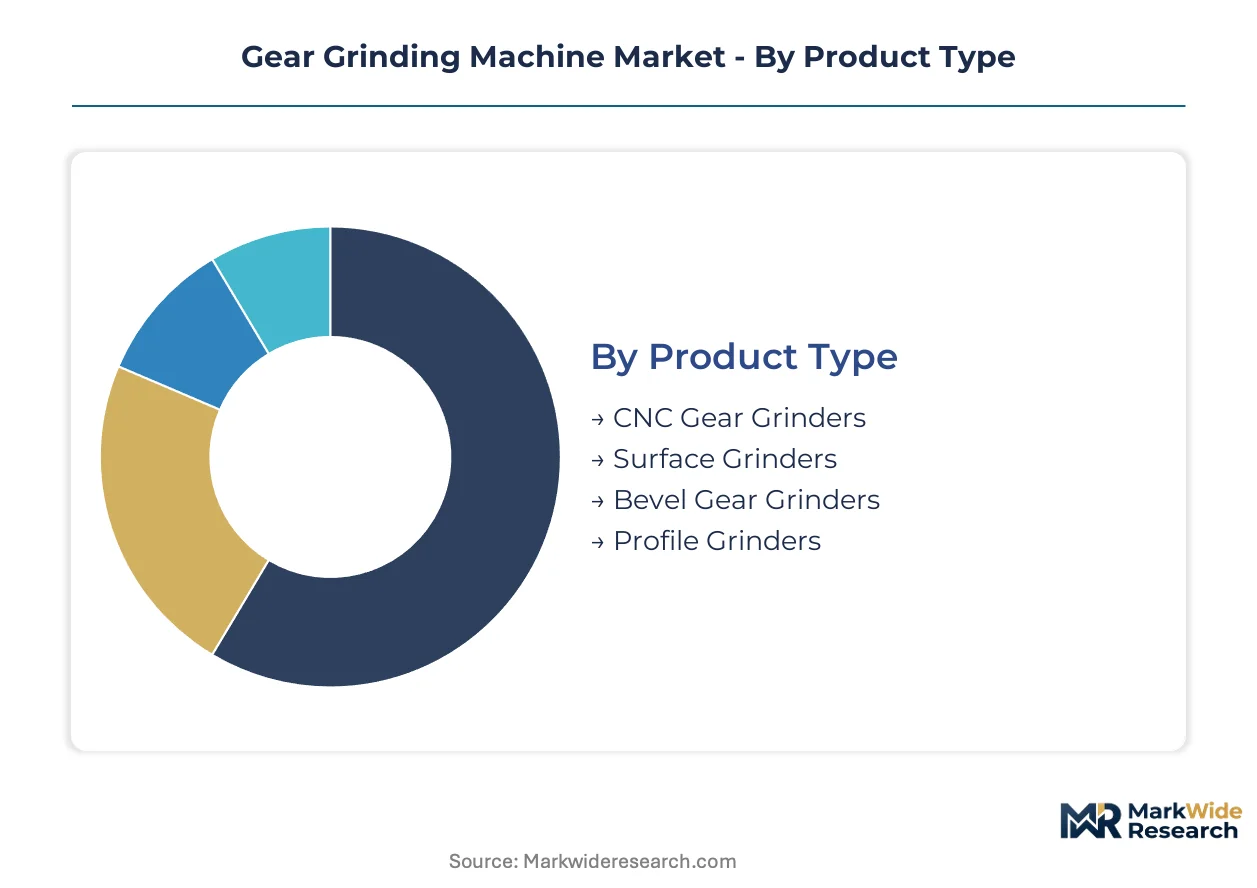
Gear grinding machine procurement patterns diverge sharply across product architectures and end-use requirements. CNC platforms command premium positioning in automotive volume production while conventional systems retain footholds in repair-oriented applications where capital constraints dominate.
Product Type:
Supply concentration in precision spindle and linear motor networks favors integrated platform architectures over modular alternatives.
- CNC Gear Grinders:Closed-loop thermal compensation and direct-drive rotary tables enable sub-micron pitch accuracy for hardened gear finishing. Automotive OEMs in Germany and Japan specify these platforms for electric drivetrain volume production where ISO 6336 tolerances apply.
- Profile Grinders:Large-format configurations accommodate wind turbine ring gears exceeding two meters in diameter. Energy developers in China are extending order backlogs for offshore torque density applications.
- Surface Grinders:Lower capital intensity sustains installed base in refurbishment operations.
- Bevel Gear Grinders:Specialized tooth geometry requirements limit addressable market to transmission and differential applications.
CNC gear grinders absorb the bulk of installed capacity; profile grinders are expanding most quickly.
End User:
Cost tier stratification separates precision-demanding sectors from price-sensitive maintenance operations.
- Automotive:Battery electric vehicle transmission production is pulling demand for continuous generating grinding throughput. Tier-one supplier networks in the Yangtze River Delta and Stuttgart region are consolidating procurement around measurement-integrated systems.
- Energy:Offshore wind infrastructure requires large-diameter ring gears with corrected profiles for elastic deformation compensation. Developers face extended lead times from concentrated German and Japanese machine tool builders.
- Aerospace:Batch sizes below fifty units diminish continuous grinding economics, favoring flexible profile grinder configurations.
- Industrial Machinery:Capital intensity barriers constrain adoption among independent job shops serving general manufacturing.
Automotive end users command the largest share of new equipment investment; energy sector procurement is climbing the fastest.
Application:
Volume concentration in passenger vehicle drivetrains contrasts with fragmented demand across tool production and heavy machinery segments.
- Gear Manufacturing:Hardened tooth flank finishing for electric vehicle reduction gears requires Ra 0.4 micrometer surface specifications. Superabrasive wheel bonds are displacing alumina in high-volume German and Japanese facilities.
- Automotive Components:Transmission and differential gear production integrates in-process metrology to compress quality assurance cycles.
- Tool Production:Cutting tool resharpening applications favor lower-cost surface grinder configurations.
- Heavy Machinery:Mining and construction equipment gears tolerate wider tolerances, limiting premium platform penetration.
Gear manufacturing applications dominate capital deployment; automotive components are gaining share fastest.
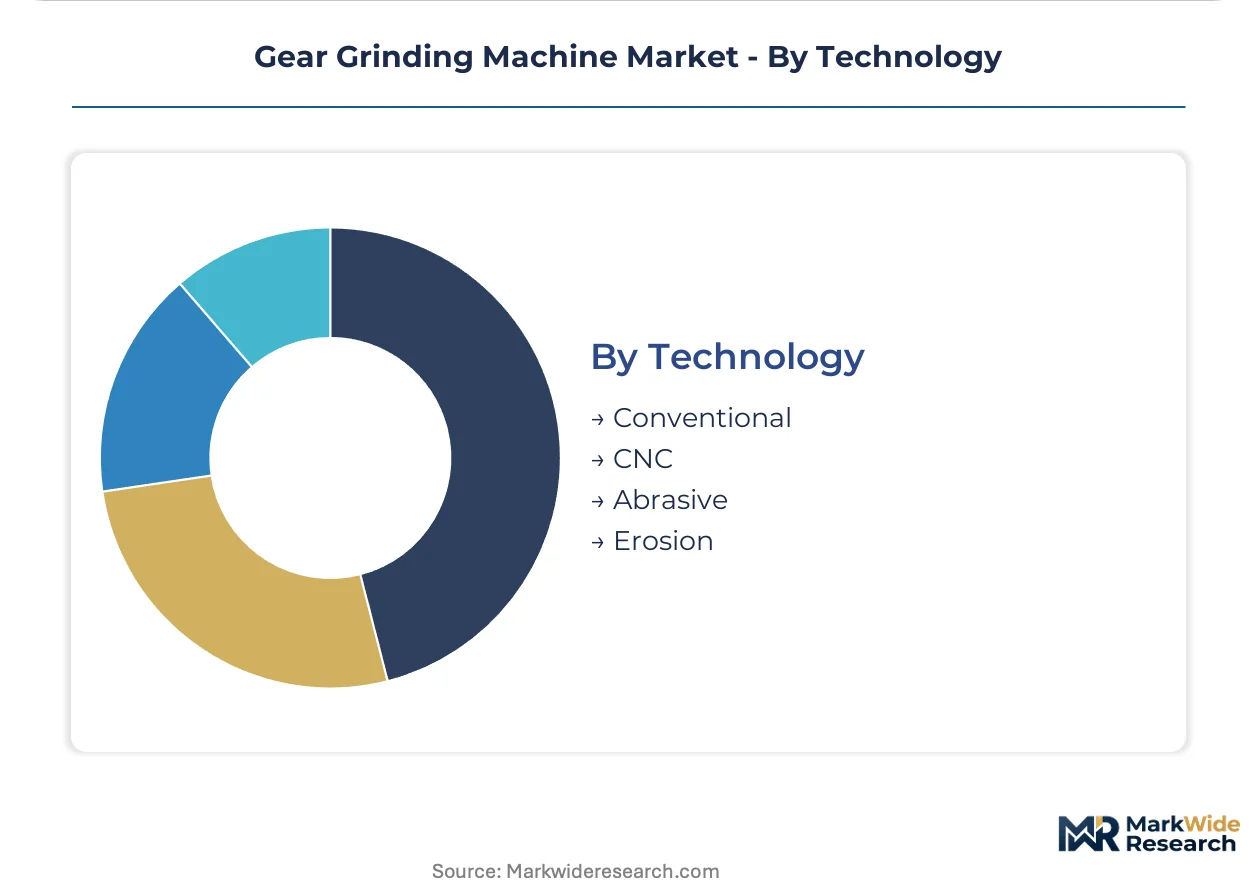
Technology:
Margin compression in conventional abrasive systems is accelerating displacement by superabrasive and electrochemical alternatives.
- CNC:Software-defined motion control enables real-time corrective machining based on in-process measurement feedback. REACH and EPA coolant restrictions are mandating minimum quantity lubrication integration.
- Abrasive:Cubic boron nitride and diamond bonds reduce cycle times and wheel change frequency in hardened steel finishing.
- Conventional:Mechanical indexing systems face retirement pressure from tightening ISO 6336 load capacity standards.
- Erosion:Electrochemical machining alternatives address exotic materials in aerospace gear applications.
CNC technology accounts for the majority of value creation; abrasive technology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine tool clusters and Yangtze River Delta manufacturing zones concentrate precision gear grinding capacity through targeted industrial policy support. Tax-incentive programs in Stuttgart and Shanghai are accelerating capital deployment for electric drivetrain production.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are scaling CNC gear grinder procurement for battery electric vehicle transmission lines. The EU Machinery Directive and CE marking requirements shape equipment specification criteria for domestic builders. Stuttgart anchors European demand through integrated measurement-grinding systems serving tier-one supplier networks.
China
Wind energy developers in the Yangtze River Delta are extending profile grinder order backlogs for offshore turbine ring gears exceeding two meters in diameter. MIIT industrial upgrading programs subsidize superabrasive wheel technology adoption in precision manufacturing. Shanghai and Jiangsu province machine tool clusters are consolidating procurement around measurement-integrated platforms.
Japan
Continuous generating grinding throughput dominates automotive transmission volume production in Aichi and Kanagawa prefectures. METI energy efficiency mandates redirect capital toward machines with regenerative drives and minimum quantity lubrication systems. Nagoya-area precision spindle and linear motor networks expose concentrated supply chain vulnerability.
United States
EPA coolant mist exposure limits and OSHA metallic particulate emissions frameworks regulate grinding operations in Michigan and Ohio automotive corridors. The Inflation Reduction Act electric vehicle tax credits are pulling gear production investment toward domestic supply chains. Detroit-area refurbishment operations retain surface grinder installed base amid capital intensity constraints.
Switzerland
Swissmedic medical device regulations and ISO 1328 accuracy requirements govern gear classification for orthopedic and surgical instrument applications. Precision gear finishing for batch sizes below fifty units favors flexible profile grinder configurations in the Jura Arc watchmaking and medical technology cluster. Geneva and Neuchâtel cantons specialize in sub-micron accuracy equipment for aerospace and medical end uses.
Gear Grinding Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium platform builders commanding automotive volume production while regional fabricators serve refurbishment markets. The vendor base concentrates around integrated measurement-grinding systems and continuous generating grinding throughput technologies. Three archetypes dominate: European measurement-integrated specialists, Japanese high-volume throughput leaders, and Chinese state-supported precision equipment builders. M&A activity targets metrology software capabilities, while capacity expansion concentrates in Yangtze River Delta and Stuttgart industrial zones.
Within the European measurement-integrated tier, Klingelnberg and Reishauer exemplify closed-loop thermal compensation architectures that compress inspection-to-correction cycles. Gleason Corporation occupies a position bridging bevel gear specialization with vertical control over cutting tool supply. Among Chinese state-supported fabricators, Qinchuan and Chongqing Machine Tool sit within capital-intensive expansion trajectories targeting domestic electric vehicle supply chain localization.
| Leading Market Players |
|---|
| Gleason Corporation |
| Klingelnberg |
| Liebherr |
| Kapp Werkzeugmaschinen |
| Reishauer |
| FFG Werke |
| Samputensili |
| Qinchuan |
| Chongqing Machine Tool |
| Others |
Value Network & Pricing Analysis
EU Machinery Directive energy efficiency mandates and REACH chemical restrictions gate qualified supply access and premium-tier pricing power for CNC gear grinding platforms, compressing margins for non-compliant builders while rewarding regenerative drive and minimum quantity lubrication adopters with pricing premiums in German and Japanese automotive supplier networks.
Pricing Analysis
Lead-time-driven pricing stratification separates premium CNC platforms with extended backlogs from discounted spot inventory in conventional surface grinder categories. Three-tier pricing structure across premium measurement-integrated systems, standard CNC configurations, and economy mechanical indexers reflects ISO 6336 certification grade and after-sales service bundling. Pricing pressure stems from capital intensity barriers constraining independent job shop demand. Tier-one automotive suppliers in Germany exhibit lowest price sensitivity; refurbishment operators in US Midwest corridors show highest.
Supply Chain Analysis
CE marking and ISO 1328 accuracy certification requirements gate market access for European-built equipment and imported platforms. Precision spindle and linear motor production concentrates in Japan, Germany, and Taiwan, drawing from specialized steel alloys, ceramic bearings, and direct-drive torque motor components. Single-source vulnerability in Nagoya-area precision motor networks exposes lead time risk. Distribution runs through tier-one supplier procurement consortia in Stuttgart and Yangtze River Delta clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as ISO 6336 and AGMA 2001-D04 standard tightening forces capital-constrained mechanical indexer builders toward exit or acquisition.
For Market Incumbents: Hedge against emerging Chinese state-supported fabricators by deepening captive supply of superabrasive cutting tools and precision spindles. Prioritize measurement-integrated system development to compress inspection-to-correction cycles for automotive transmission volume production. Defend Stuttgart and Aichi prefecture supplier relationships against Yangtze River Delta procurement consolidation. For New Entrants and Emerging Players: Begin with refurbishment service unbundling in US Midwest and Detroit-area industrial corridors where capital intensity barriers prevent new equipment acquisition. Target surface grinder aftermarket tooling and spindle rebuild segments as the most penetrable white space. Pursue third-party metrology recalibration contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Extended profile grinder order backlogs for offshore wind turbine ring gears is the leading indicator that energy sector demand will sustain premium platform pricing. Frame long-term viability around electric drivetrain transmission localization across multiple regional supply chains. Target metrology software capabilities as the priority acquisition archetype. Monitor MIIT industrial upgrading program subsidy disbursement rates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superabrasive Cutting Tools | Gleason Corporation's captive supply of CBN and diamond bonds sustains premium positioning across bevel gear applications. |
| Measurement-Integrated Platform Development | Klingelnberg's closed-loop thermal compensation systems compress quality assurance cycles for Stuttgart tier-one networks. |
| Refurbishment Service Unbundling | Third-party spindle rebuild and software update offerings fragment traditional bundled maintenance contracts in Yangtze River Delta clusters. |
| Minimum Quantity Lubrication Integration | Regenerative drive and MQL coolant systems maintain EU market access under Machinery Directive energy efficiency mandates. |
| Precision Spindle Capacity Expansion | Japanese and German component network concentration creates acquisition targets for supply security in direct-drive rotary table production. |
Research Methodology
Independent corroboration across machine tool OEM technical directors, tier-one automotive supplier procurement leads, and precision component distribution channel partners underwrites the qualitative findings. Secondary validation draws from METI energy efficiency mandate filings, MIIT industrial upgrading program disclosures, EPA coolant emission regulatory dockets, and customs trade data for grinding machine imports. Bottom-up equipment shipment tallies triangulate against top-down capital expenditure surveys from automotive and energy sector end users.
Rate-of-change decomposition across the projection horizon segments volume and value outputs by product architecture, end-use sector, and technology type. Modeled dimensions include CNC platform tier, application specificity, and regional regulatory cluster alignment. CAGRs derive from installed base retirement schedules and new capacity absorption rates. Forecast inputs incorporate electric drivetrain transmission line announcements and offshore wind turbine ring gear diameter specifications.
Supply chain disruption, regulatory timeline compression, and superabrasive material cost volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding standard adoption trajectories and capital availability across buyer segments. A model refresh is warranted upon material change in EU carbon border adjustment implementation schedules or MIIT subsidy program restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Japan Waterjet Cutting Machines Market