
 North America Ceiling Tiles Market | 2026-2036
North America Ceiling Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceiling Tiles Market Intelligence
The traditional two-step distribution channel, from manufacturer to regional distributor, is narrowing as large-scale contractors procure directly from manufacturers. Armstrong World Industries Inc. leverages its extensive manufacturing scale to serve these large direct accounts. USG Corporation sustains its market position through strong brand recognition and a diversified product portfolio. Meanwhile, CertainTeed (Saint-Gobain) competes by offering integrated building material solutions beyond just ceiling systems.
Ceiling tiles are prefabricated panels designed for installation in an interior ceiling grid system. They are typically composed of materials like mineral fiber, which provides specific acoustic absorption, measured by Noise Reduction Coefficient (NRC), and fire-retardant properties. Mineral fiber tiles continue to dominate the product landscape, while metal tiles are gaining share in high-end commercial applications. Within end-user segments, the commercial sector remains the largest source of revenue, with the educational sector showing consistent demand for acoustically optimized products.
Product standards in the North America market are heavily influenced by ASTM International specifications for fire performance and acoustics. Regulations from the U.S. Environmental Protection Agency (EPA) and Health Canada also govern material composition, particularly concerning volatile organic compounds (VOCs) and recycled content. Future material selection and product innovation will be guided by evolving green building certifications and circular economy principles.
Market Dynamics
The central structural force shaping the North America ceiling tiles market is the disintermediation of the distribution channel. Large-scale contractors are increasingly bypassing regional distributors to procure materials directly from manufacturers, altering long-standing supply chain relationships and competitive dynamics.
Growth Catalysts
- Stricter Building Codes:Regulations from bodies like the U.S. Occupational Safety and Health Administration (OSHA) and updated ASTM International fire safety standards mandate higher performance for acoustic control and fire retardancy, driving demand for premium, compliant ceiling tiles in commercial construction.
- Commercial Renovation Cycles:Sustained activity in the renovation and retrofitting of office, retail, and hospitality spaces, particularly in major urban centers across the United States and Canada, provides a consistent source of demand for ceiling system upgrades.
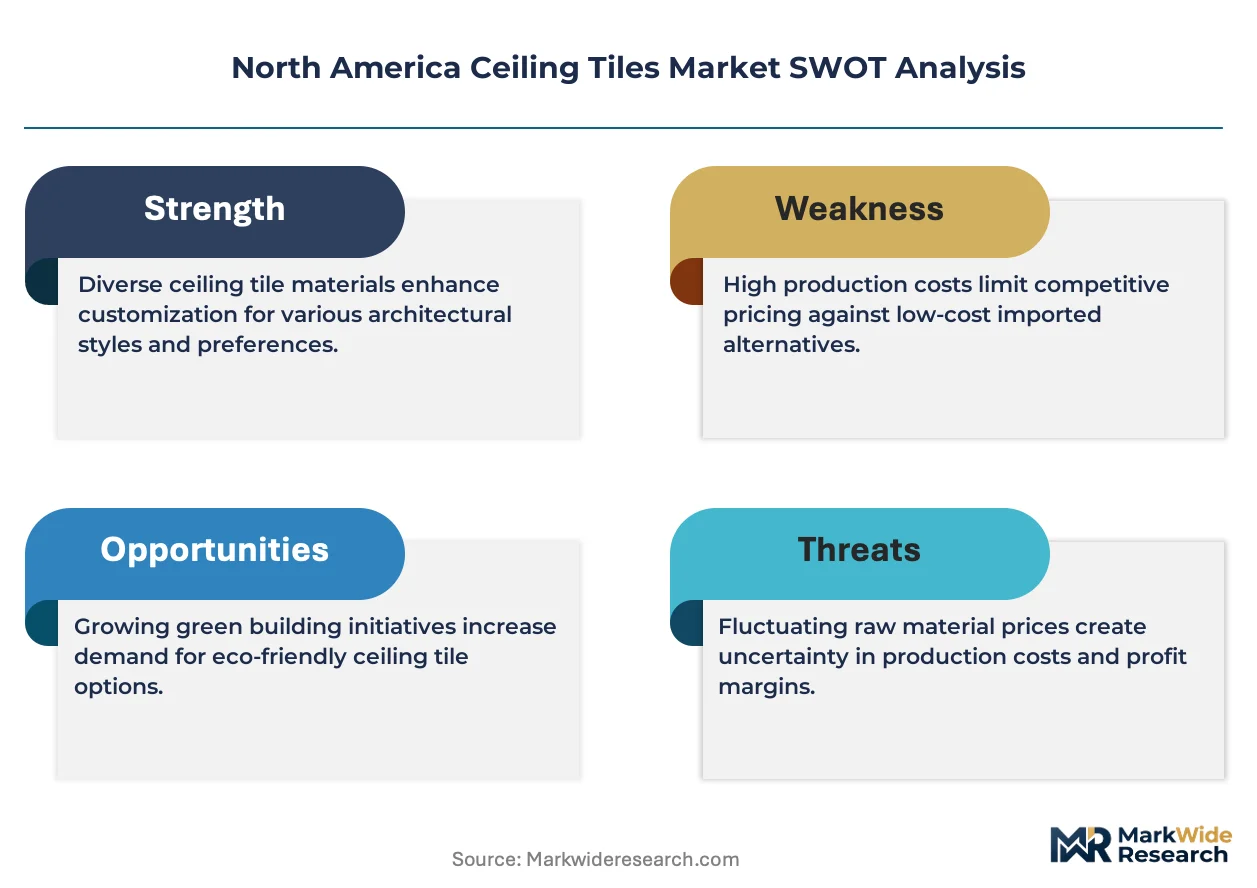
- Green Building Movement:The push for green building certifications like LEED is compelling architects and builders to specify products with high recycled content, low VOC emissions, and transparent environmental product declarations, favoring manufacturers with strong sustainability credentials.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations in key raw materials like mineral fiber and fiberglass, which can compress manufacturer margins and create pricing uncertainty for contractors.
- Substitution from Alternative Designs:A preference for open-plenum ceilings and exposed structural elements in modern office and retail architecture presents a direct substitution threat, reducing the total addressable square footage for suspended ceiling systems.
- Logistical Hurdles:The bulky nature and fragility of ceiling tiles make them expensive and complex to transport over long distances, adding significant logistical costs and risk of damage, particularly for projects in remote locations.
Strategic Opportunities
- Integrated Smart Ceilings:There is a significant opportunity to embed technology, such as LED lighting, sensors, and speakers, directly into ceiling panels, creating value-added systems for smart buildings and the Internet of Things (IoT) ecosystem.
- Healthcare and Education Sector Specialization:Developing specialized tiles with enhanced antimicrobial properties, high cleanability, and superior acoustic performance can capture high-value contracts in the growing healthcare and education facility construction segments.
- Circular Economy Models:Establishing take-back and recycling programs for old ceiling tiles offers a competitive advantage, appealing to corporate clients focused on meeting circular economy principles and reducing construction waste sent to landfills.
Industry Challenges
- Skilled Labor Shortages:A persistent shortage of trained and certified installers for ceiling grid systems across North America can lead to project delays, increased labor costs, and installation quality issues, impacting project timelines and budgets.
- Complex Compliance Landscape:Manufacturers face the challenge of ensuring products meet a patchwork of different regional building codes, fire standards, and environmental regulations across various states and provinces, which complicates product development and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceiling Tiles Market |
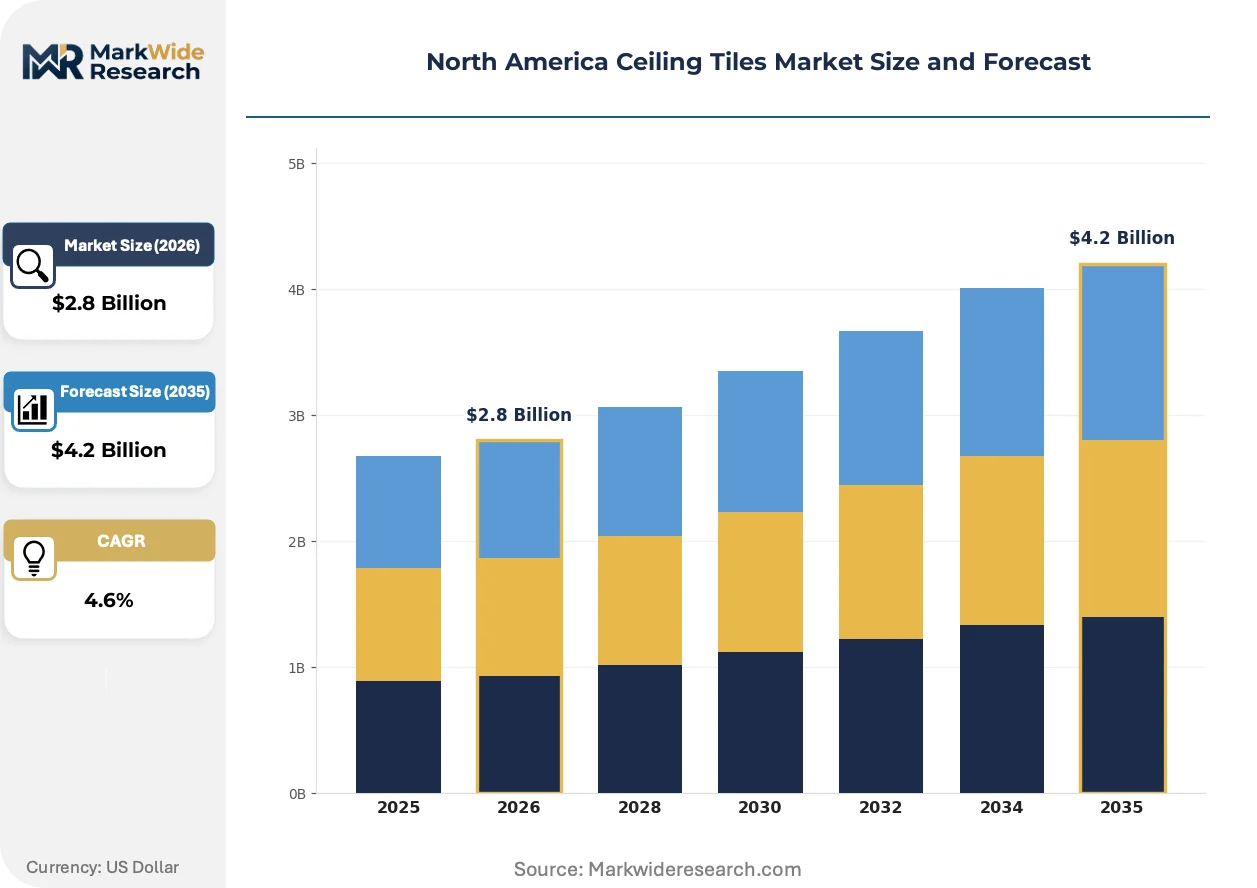
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tile Type: Mineral Fiber, PVC, Metal, Wood Installation Type: Suspended, Direct Attach, Grid System, Acoustic End User: Commercial, Residential, Industrial, Educational Design Style: Contemporary, Traditional, Rustic, Minimalist |
| Companies Covered | Armstrong World Industries Inc., USG Corporation, CertainTeed (Saint-Gobain), Rockfon (ROCKWOOL Group), OWA Ceiling Systems Inc., Hunter Douglas, Gordon Incorporated, SAS International, Ceilume, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceiling Tiles Market Strategic Shifts & Innovations
Product evolution in the North America ceiling tiles market is driven by a convergence of material science and functional building requirements. Innovations focus on enhancing acoustic performance, improving indoor air quality, and simplifying installation, moving tiles from a commodity product to an integrated building system component.
Prefabricated ceiling modules that integrate lighting, air diffusers, and acoustic materials into a single factory-built unit represent a key product evolution. High-end commercial and institutional projects, seeking to accelerate construction timelines, are the primary adopters of these systems. This integrated approach is collapsing the traditional, sequential work of separate electrical, HVAC, and finishing trades into a more streamlined installation process.
Regulatory mandates from the U.S. Environmental Protection Agency (EPA) and Health Canada are tightening restrictions on volatile organic compounds (VOCs) in building materials. This is forcing manufacturers to invest in new water-based binders and low-emission coatings for their mineral fiber and fiberglass tiles. The educational and healthcare sectors are most impacted, as procurement specifications in these segments increasingly require products certified for superior indoor air quality.
Direct purchasing by large construction management firms and general contractors is disrupting established sales channels. This model bypasses the two-step distribution network of regional distributors, especially for large-scale new construction and portfolio-wide renovation projects. The shift is most visible in major metropolitan markets across the U.S. and Canada, where the scale of projects makes direct-from-manufacturer procurement economically and logistically advantageous.
North America Ceiling Tiles Market Segmentation
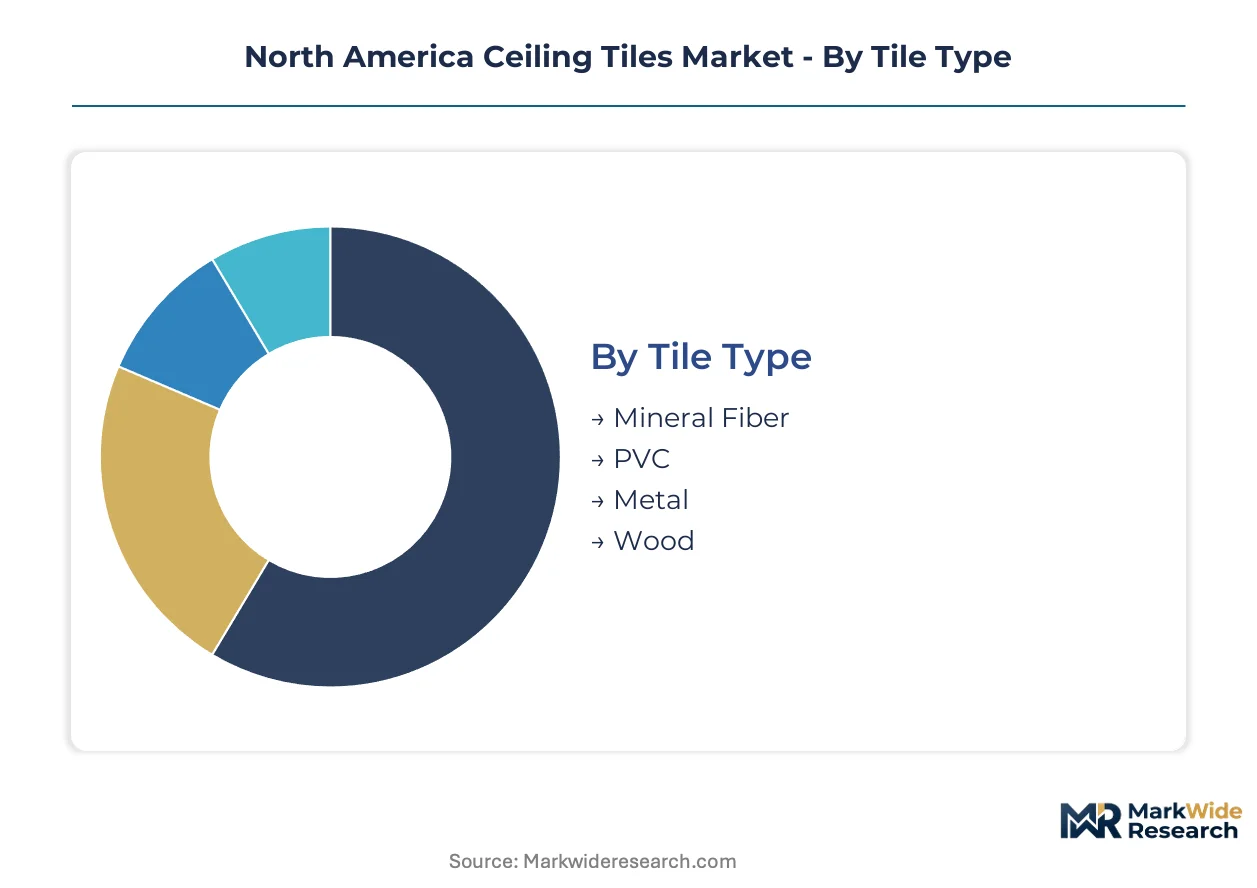
Understanding the distinct segments within the North America ceiling tiles market provides clarity on demand drivers, product innovation pathways, and competitive landscape shifts. Each category reveals specific material preferences, installation methodologies, end-user priorities, and aesthetic considerations influencing procurement decisions across the United States and Canada.
Tile Type:
The market's tile type segmentation reflects a broad use-case spectrum, from foundational acoustic control to aesthetic enhancement in diverse commercial and institutional settings.
- Mineral Fiber:Mineral fiber tiles, composed of inorganic materials, offer excellent acoustic absorption and fire resistance, meeting stringent building codes across the U.S. and Canada. Demand concentrates in commercial office renovations, driven by requirements for Noise Reduction Coefficient (NRC) and fire retardancy.
- Metal:Metal tiles, typically aluminum or steel, provide durability, moisture resistance, and a modern aesthetic, often specified for high-end applications. Their adoption is gaining traction in premium retail and hospitality spaces in major North American urban centers, valued for their sleek appearance and longevity.
- PVC:PVC tiles offer moisture resistance and affordability, often selected for utility areas or environments requiring frequent cleaning.
- Wood:Wood tiles provide natural aesthetics and warmth, appealing to design-conscious projects in boutique commercial settings.
Established volume favors Mineral Fiber; emerging adoption favors Metal.
Installation Type:
Application versatility profoundly influences the choice of installation method for ceiling tiles across North America.
- Suspended:Suspended ceiling systems involve a grid hung from the structural slab, allowing easy access to plenum space for utilities like HVAC and electrical systems. This method dominates new commercial construction projects across the United States, valued for its flexibility and cost-effectiveness.
- Direct Attach:Direct attach installations involve adhering or fastening tiles directly to an existing ceiling surface, offering a clean, low-profile finish without reducing ceiling height. This method sees significant use in smaller office retrofits and specific retail applications in Canadian urban areas seeking simplified installation.
- Grid System:Grid system installations are integral to suspended ceilings, providing the structural framework for tile placement and utility integration.
- Acoustic:Acoustic installations prioritize sound control, often utilizing specialized panels and methods to mitigate noise in educational and healthcare environments.
Widespread deployment characterizes Suspended systems, while specialized needs drive Direct Attach methods.
End User:
Customer type significantly dictates product specifications and performance requirements within the North America ceiling tiles market.
- Commercial:The commercial sector encompasses offices, retail, and hospitality, demanding tiles that balance aesthetics, fire safety, and acoustic performance. Sustained renovation cycles in major U.S. and Canadian metropolitan areas drive consistent demand for high-performance ceiling systems.
- Educational:The educational sector, including schools and universities, prioritizes superior acoustic properties and indoor air quality to enhance learning environments. Stringent procurement specifications in both the U.S. and Canada require low VOC emissions and high NRC ratings for these facilities.
- Residential:Residential applications include basements and home offices, typically favoring easier-to-install and aesthetically pleasing tile options.
- Industrial:Industrial end-users, such as manufacturing plants, require durable, moisture-resistant, and easily cleanable tiles for functional environments.
Volume demand concentrates in the Commercial sector, with specialized requirements defining the Educational segment.
Design Style:
Aesthetic influence plays a critical role in ceiling tile selection, shaping interior environments across North America.
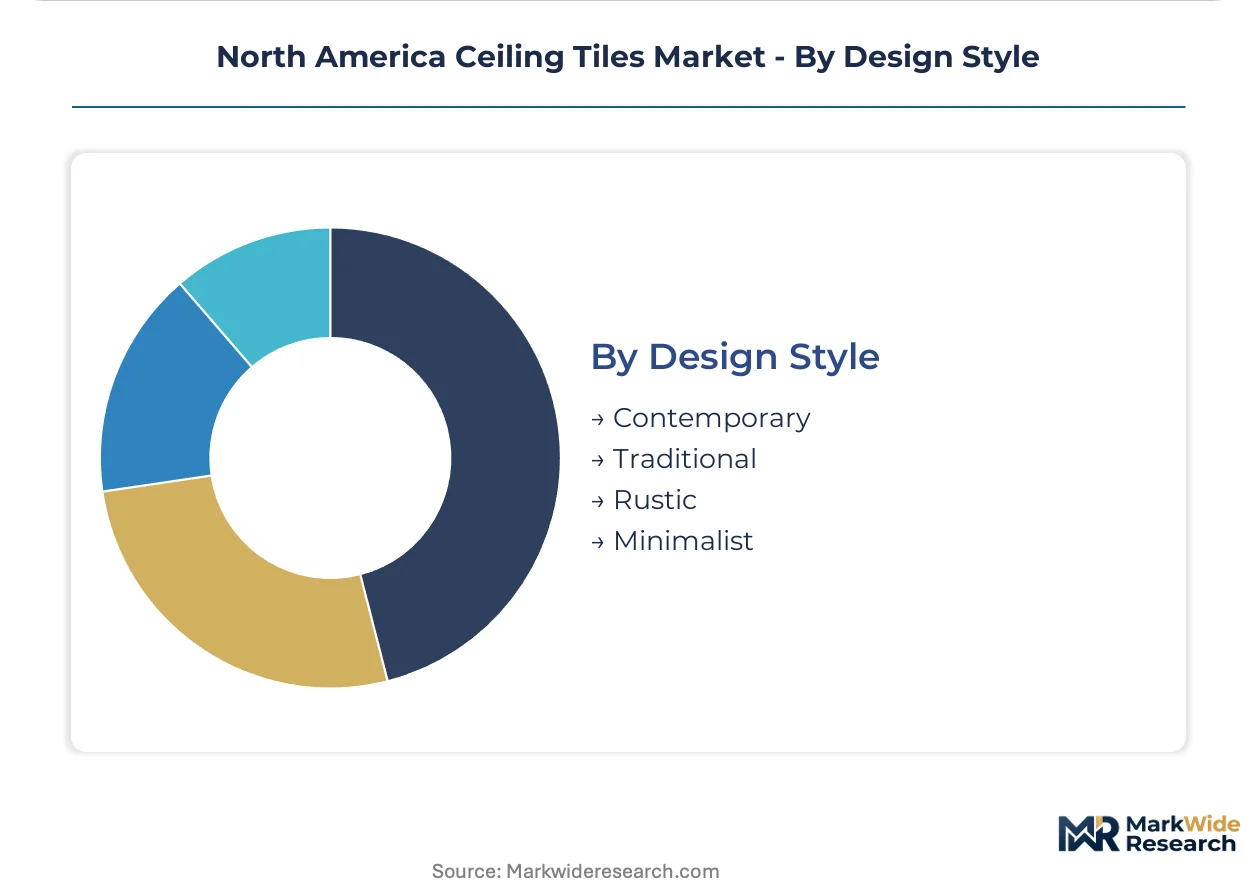
- Contemporary:Contemporary designs feature clean lines, geometric patterns, and often a monochromatic or neutral color palette, aligning with modern architectural trends. This style is highly sought after in new corporate office developments and upscale retail spaces throughout North American cities.
- Minimalist:Minimalist design styles emphasize simplicity, functionality, and uncluttered aesthetics, often utilizing flush-mount or frameless tile systems to create a seamless ceiling plane. Demand for this approach is strong in tech company campuses and modern healthcare facilities in the U.S. and Canada.
- Traditional:Traditional styles incorporate classic patterns and textures, often found in heritage building renovations or hospitality settings seeking a classic ambiance.
- Rustic:Rustic designs mimic natural textures like wood or stone, popular in themed restaurants or hospitality venues aiming for an organic feel.
Dominant aesthetic preferences are reflected in Contemporary designs, with niche appeal found in Rustic styles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for ceiling tiles varies significantly across North America, with the United States often dictating premium specifications due to its large commercial market. Conversely, Mexico's market dynamics emphasize cost-effectiveness and local material sourcing. This regional disparity influences procurement strategies and product availability.
United States
Commercial renovation cycles and green building initiatives consistently drive demand for ceiling tiles across the United States. Regulations from the U.S. Environmental Protection Agency (EPA) mandate low VOC emissions for indoor air quality. Major urban centers like New York City show high project concentration for premium acoustic and fire-rated systems.
Canada
Educational sector demand for acoustically optimized products and office retrofits are prominent drivers in Canada. Health Canada regulations influence material composition, particularly regarding recycled content. Toronto and Vancouver metropolitan areas experience consistent demand for modern, aesthetically pleasing ceiling solutions.
Mexico
Industrial construction expansion and growing hospitality sector projects fuel demand for ceiling tiles in Mexico. Local building standards increasingly emphasize fire safety and durability in commercial applications. Mexico City and Monterrey urban areas are seeing significant activity in new commercial and industrial facility development.
New York Metro
High-end commercial developments and healthcare facility upgrades drive specialized demand in the New York metropolitan area. The stringent NYC Building Code mandates advanced fire performance and acoustic properties for public spaces. Manhattan and Brooklyn see continuous investment in architecturally integrated ceiling systems.
Ontario
Institutional infrastructure projects and corporate office fit-outs generate substantial demand across Ontario. The Ontario Building Code specifies performance requirements for fire resistance and sound attenuation. The Greater Toronto Area remains a hub for large-scale commercial and educational sector ceiling tile procurements.
North America Ceiling Tiles Market Key Industry Players
Established manufacturers and specialized innovators split the North America ceiling tiles market, creating a tiered competitive landscape. The market structure favors large-scale producers capable of extensive distribution networks and broad product diversification. Key strategic archetypes include integrated building solution providers focused on comprehensive offerings and material-specific specialists targeting niche applications. Companies engage in continuous product innovation and strategic partnerships to expand their market reach and adapt to evolving building codes.
At the scale-driven end, Armstrong World Industries Inc. exemplifies extensive manufacturing capabilities and direct procurement channels for large contractors. USG Corporation, a prominent entity, sustains its market position through strong brand recognition and a diversified product portfolio across various segments. CertainTeed (Saint-Gobain) represents the integrated solutions archetype, offering broader building material systems beyond just ceiling tiles. These entities collectively anchor significant portions of the North American market, catering to diverse project requirements and evolving architectural demands. Their strategic positioning addresses both volume-driven and value-added segments, influencing market trends. Their presence underscores the importance of both scale and specialized offerings within the industry.
| Leading Market Players |
|---|
| Armstrong World Industries Inc. |
| USG Corporation |
| CertainTeed (Saint-Gobain) |
| Rockfon (ROCKWOOL Group) |
| OWA Ceiling Systems Inc. |
| Hunter Douglas |
| Gordon Incorporated |
| SAS International |
| Ceilume |
| Others |
Cost & Logistics Intelligence
Major metropolitan areas like New York City, with their high project concentration, influence premium pricing for specialized ceiling tile systems. This regional capacity and demand balance directly impacts local material availability and cost structures.
Pricing Analysis
Configured-to-order ceiling systems command a significant premium over standard, off-the-shelf products in the North America market. Pricing stratifies across premium, standard, and economy tiers, driven by performance specifications like Noise Reduction Coefficient and fire ratings, alongside brand recognition. Cost compression in mineral fiber tiles intensifies due to raw material price volatility, affecting standard product margins. Large commercial contractors, prioritizing compliance and specific performance, exhibit lower price sensitivity compared to smaller residential or utility project buyers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly critical for manufacturers supporting large-scale ceiling tile projects. North American production concentrates heavily within the United States and Canada, drawing from mineral fiber, fiberglass, and metal inputs. Commodity price volatility for these raw materials presents a structural supply chain risk. Distribution runs through direct procurement by large contractors, alongside traditional two-step channels for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ceiling tiles market presents a significant service-attach opportunity, with integrated smart ceiling systems expanding faster than traditional tile hardware sales. This enables recurring revenue streams through software and maintenance contracts.
For Market Incumbents: Build a regulatory compliance moat by investing heavily in R&D for advanced fire performance and acoustic properties. Expand direct-to-contractor channels to counter disintermediation and defend market share against price-focused competition. This proactive approach mitigates the threat of substitution from alternative open-plenum designs. Deepen certification investment for LEED and low VOC standards to maintain leadership.
For New Entrants and Emerging Players: Establish a beachhead in specialized segments like integrated smart ceilings or high-performance healthcare and education tiles. The most penetrable segment lies in mid-sized commercial renovations in secondary urban centers, where large incumbents have less direct control. Offer products with superior sustainability credentials and circular economy models. This approach leverages evolving green building mandates for differentiation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in integrated ceiling systems or advanced material solutions. The market exhibits strong long-term viability over the next 5-10 years, driven by sustained commercial renovation cycles and smart building trends. Target acquisition profiles include innovators with patented low-VOC materials or established IoT integration capabilities. The signal to watch is the accelerating adoption rate of prefabricated ceiling modules in new construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop integrated smart ceiling panels | Embeds IoT technology, creating value-added systems for smart buildings. |
| Expand direct procurement channels for large contractors | Bypasses distributors, streamlining supply and strengthening manufacturer-client relationships. |
| Invest in circular economy take-back programs | Appeals to corporate clients focused on reducing construction waste and meeting sustainability goals. |
| Certify products for enhanced indoor air quality (low VOC) | Addresses stringent regulations from EPA and Health Canada, particularly in educational and healthcare sectors. |
| Partner with HVAC and lighting manufacturers for modular solutions | Accelerates construction timelines by integrating multiple trades into single factory-built units. |
Research Approach
A spread of perspectives from commercial contractors, architects, facility managers, and material scientists converged on the working assumptions for this study. This involved combining insights from primary interviews with extensive secondary validation. Data sources included ASTM International specifications, EPA and Health Canada regulatory documents, company financial filings, and construction industry reports. Both bottom-up and top-down triangulation methods ensured data consistency and accuracy.
Demand-supply balance models underpinned the quantitative projections across the analysis window. Segmentation dimensions included tile type, installation method, end-user sector, design style, and key regional markets. Compound Annual Growth Rates were derived through regression analysis of historical trends and projected market drivers. Key forecast inputs included commercial renovation spending and new construction starts in major urban centers.
Stress conditions across raw material price volatility, building code revisions, and economic downturns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding market dynamics and regulatory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
US Parking Deck Coatings Market