
 Carbon Steel IBC Market | 2026-2036
Carbon Steel IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Steel IBC Market Outlook
Stainless steel is repositioning carbon steel IBC economics in corrosive chemical handling, forcing incumbents to defend value through coating innovations and hybrid designs. Greif, Inc. leverages its integrated steel drum and IBC manufacturing footprint to sustain margin capture across North American chemical corridors. Mauser Packaging Solutions anchors European demand through its closed-loop reconditioning network. Thielmann US LLC specializes in precision-welded stainless vessels, competing on FDA-compliant finishes for food-grade applications.
A carbon steel IBC is a rigid, reusable intermediate bulk container fabricated from carbon steel sheet, typically rated for densities between 1.2 and 1.9 specific gravity, designed for the transport and storage of liquids, semi-solids, and powdered materials in volumes ranging from 180 to 550 gallons. Closed top designs dominate chemical applications where vapor containment and UN-certified hazardous material transport govern procurement specifications. Welded construction commands premium positioning in pharmaceutical and high-purity chemical handling where seam integrity eliminates contamination vectors. Composite variants, combining steel cages with polymer liners, are gaining traction in food and beverage processing where clean-in-place protocols and weight reduction drive operational efficiency.
The EPA's Resource Conservation and Recovery Act governs carbon steel IBC retirement and reconditioning cycles in the United States, directly influencing replacement demand intensity. REACH and the EU Packaging and Packaging Waste Directive impose material traceability and recycling-content thresholds on European manufacturers, reshaping supply chain compliance costs. Stakeholders must monitor evolving UN Dangerous Goods model regulations and regional carbon-border adjustments that will determine competitive positioning between virgin steel and recycled-content IBC offerings.
Market Dynamics
Carbon steel IBC demand pivots on regulatory compression of drum retirement cycles and the corrosion-performance gap that stainless steel exploits in chemical corridors. Buyers now weigh total cost of ownership against upfront capital, reshaping supplier value propositions.
Growth Catalysts
- REACH drum-retirement mandates:European chemical handlers face accelerated replacement schedules for hazardous material containers, driving turnover in the Rhine-Ruhr corridor.
- Texas Gulf Coast petrochemical expansion:Capacity additions at Port Arthur and Baytown clusters generate concentrated demand for UN-certified transport vessels.
- Coating innovation:Epoxy-phenolic and zinc-rich interior linings extend carbon steel service life in mildly corrosive applications, preserving incumbent economics.
Market Restraints
- Hot-rolled coil volatility:Steel input costs swing with scrap availability and energy pricing, compressing fabricator margins unpredictably.
- Stainless steel substitution:Pharmaceutical and high-purity chemical handlers migrate to 316L vessels where seam integrity eliminates contamination risk.
- EPA RCRA compliance burden:Reconditioning documentation and manifesting requirements extend turnaround times and raise operational overhead.
Strategic Opportunities
- India chemical corridor buildout:Gujarat and Maharashtra industrial zones lack mature IBC reconditioning infrastructure, creating first-mover service opportunities.
- Hybrid cage-polymer designs:Composite construction reduces tare weight for food-grade applications where clean-in-place protocols dominate.
- EU Packaging and Packaging Waste Directive recycled-content thresholds:Mandates for traceable recycled steel create premium positioning for circular-economy-certified vessels.
Industry Challenges
- Welder certification scarcity:ASME Section IX and UN-certified vessel fabrication require specialized pressure-vessel welders in short supply across North American fabrication yards.
- Legacy fleet integration:Chemical handlers with mixed drum and IBC inventories face tracking-system harmonization costs when upgrading to RFID-enabled asset management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Steel IBC Market |
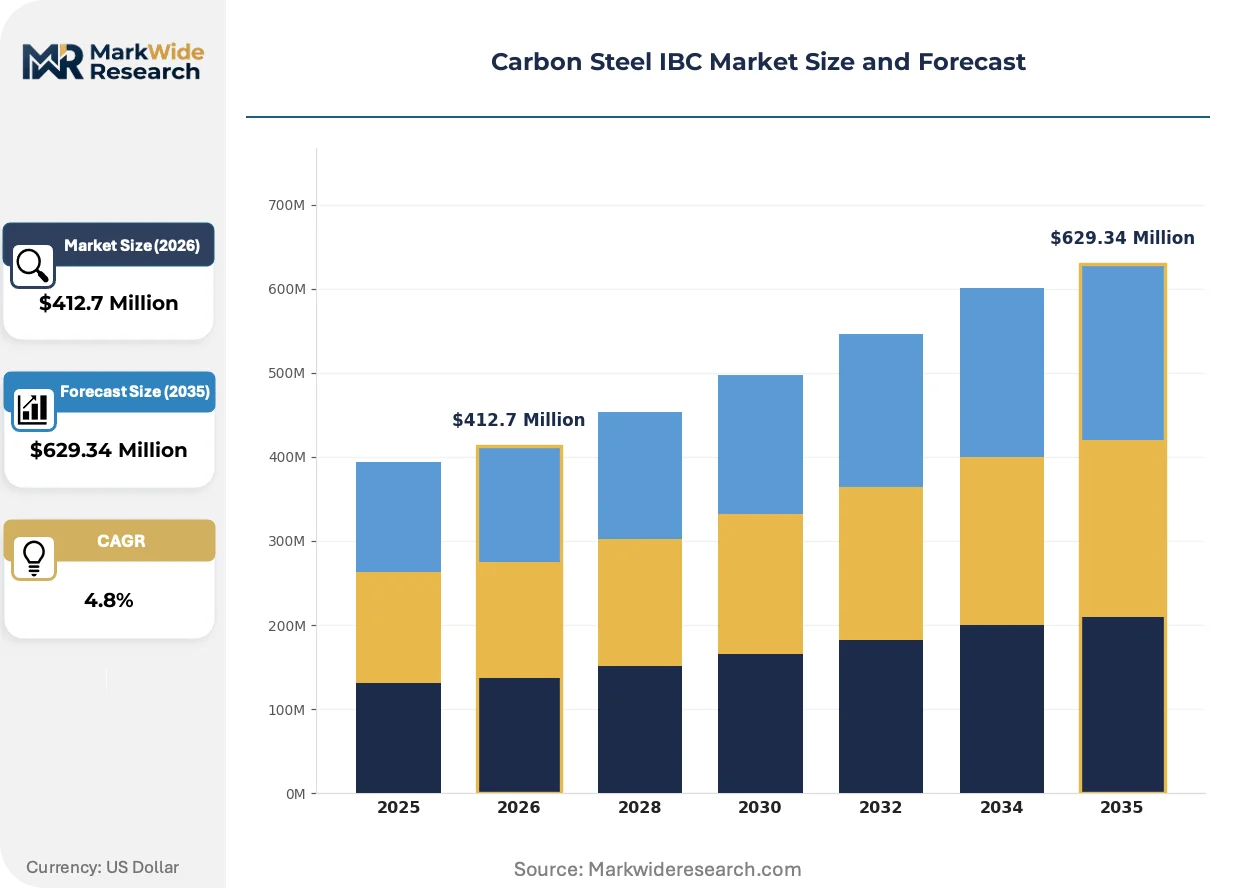
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $629.34 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Top, Closed Top, Welded, Composite Application: Chemicals, Food & Beverage, Pharmaceuticals, Agriculture End User: Manufacturers, Distributors, Retailers, Exporters Distribution Channel: Online, Offline, Direct Sales, Resellers |
| Companies Covered | Hoover Ferguson Group, Schutz Container Systems, Mauser Packaging Solutions, Greif, Inc., Thielmann US LLC, Precision IBC, Inc., Sharpsville Container Corporation, Snyder Industries Inc., Custom Metalcraft Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Steel IBC Market Strategic Shifts
Material substitution and regulatory digitization are compressing traditional carbon steel IBC economics while opening service-model opportunities. Fabricators must now compete on lifecycle data transparency, not just vessel durability.
Laser-hybrid welding is overtaking conventional MIG processes in precision vessel fabrication. Pharmaceutical and food-grade buyers specify FDA-compliant surface finishes that seamless laser joints deliver. This technology is overtaking established methods by eliminating post-weld grinding and reducing contamination vectors in high-purity applications.
REACH Article 33 substance-of-very-high-concern disclosure requirements now extend to packaging materials in European chemical supply chains. Manufacturers must document SVHC content above 0.1% threshold in coatings and gaskets. German chemical handlers are demanding full material passports, forcing suppliers to requalify component sources.
Asset-pooling models are displacing outright purchase in mid-volume chemical handling operations. Third-party fleet managers offer per-use pricing with maintenance and reconditioning bundled, transferring residual-value risk from chemical plants to service providers. This shift concentrates most visibly in Benelux chemical logistics hubs where multi-user container pools reduce capital intensity for specialty chemical SMEs.
Carbon Steel IBC Market Segmentation
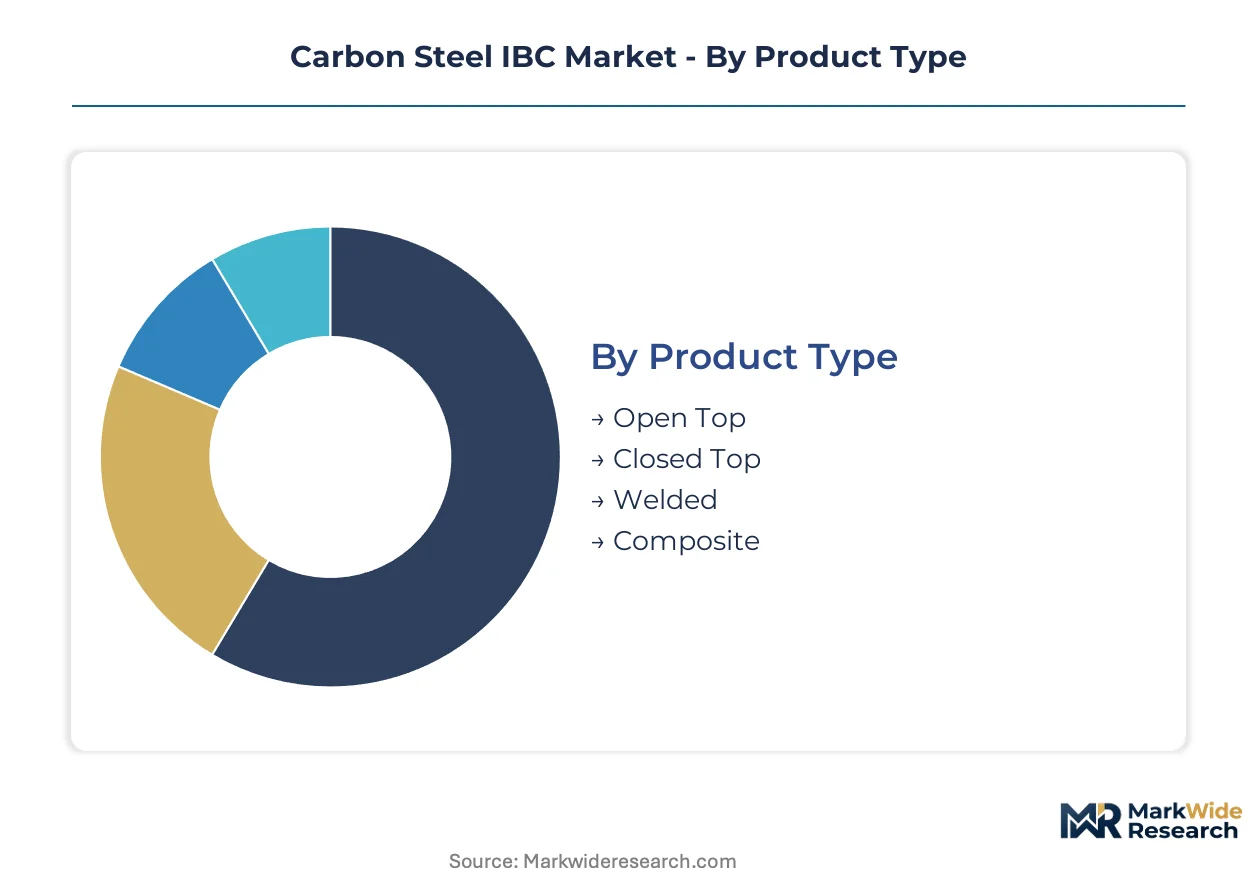
Carbon steel IBC procurement decisions pivot on corrosion resistance requirements, regulatory certification tiers, and total cost of ownership calculations across chemical handling operations. Segment boundaries blur where hybrid designs and coating innovations create overlapping performance envelopes.
Product Type:
Capital intensity escalates sharply with seam complexity and certification rigor, welding automation requirements, and surface finish specifications.
- Closed Top:Vapor-tight construction with UN-certified pressure relief valves dominates hazardous chemical transport. Demand concentrates in Texas Gulf Coast petrochemical clusters where EPA RCRA retirement cycles accelerate replacement schedules.
- Welded:Seamless pressure-vessel fabrication requires ASME Section IX certified welders and precision surface finishing. Pharmaceutical handlers in Germany specify FDA-compliant laser-hybrid welds where contamination vectors must be eliminated entirely.
- Open Top:Lower capital threshold suits non-hazardous solids handling with simplified access for filling and cleaning operations.
- Composite:Steel cage structures with polymer liners reduce tare weight for food-grade clean-in-place protocols.
Closed top designs absorb the bulk of installed capacity; welded construction is expanding most quickly in high-purity applications.
Application:
Margin profiles diverge based on regulatory burden intensity and reconditioning frequency requirements across end-use sectors.
- Chemicals:Corrosive substance handling demands epoxy-phenolic or zinc-rich interior linings to extend carbon steel service life. REACH compliance in the Rhine-Ruhr corridor mandates accelerated container retirement, sustaining replacement demand.
- Pharmaceuticals:316L stainless substitution threatens carbon steel positioning where seam integrity governs contamination risk. Precision-welded vessels with FDA-compliant surface finishes capture residual carbon steel demand in secondary chemical storage.
- Food & Beverage:Clean-in-place compatibility and weight reduction drive composite cage-polymer adoption.
- Agriculture:Fertilizer and pesticide handling tolerates lower-specification open top designs with reduced capital outlay.
Chemical applications anchor revenue concentration; food and beverage composite adoption is climbing the fastest.
End User:
Procurement scale and asset management sophistication determine whether buyers favor outright purchase or third-party pooling arrangements.
- Manufacturers:Integrated chemical producers with captive logistics operations maintain owned fleets and in-house reconditioning capabilities. Capital deployment favors closed top UN-certified vessels for hazardous material compliance.
- Distributors:Mid-volume handlers increasingly adopt asset-pooling models with per-use pricing and bundled maintenance, transferring residual value risk to third-party fleet managers.
- Retailers:Agricultural supply chains purchase open top designs for seasonal fertilizer distribution with minimal reconditioning infrastructure.
- Exporters:Cross-border chemical shipments require harmonized UN certification across multiple regulatory jurisdictions.
Manufacturers command the deepest installed base; distributor pooling arrangements are gaining share fastest.
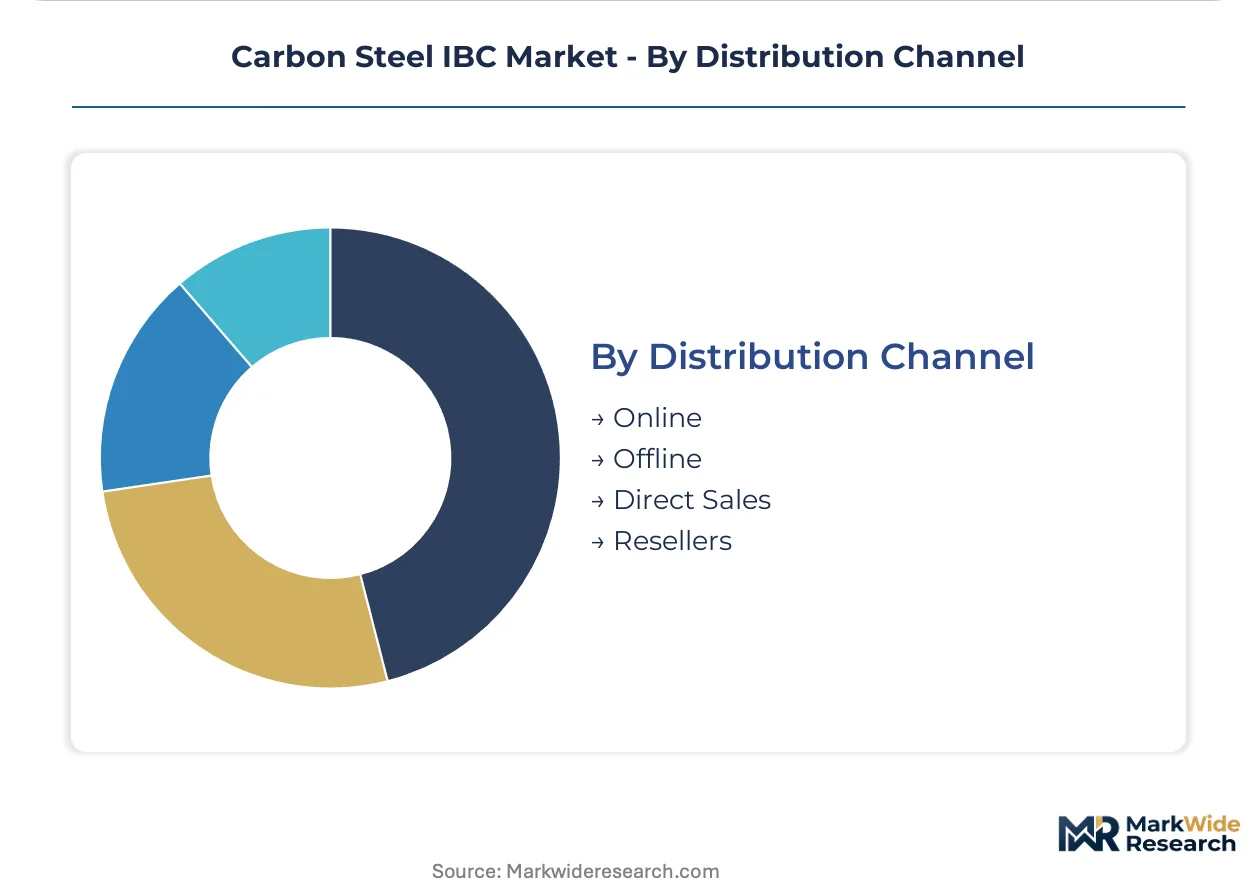
Distribution Channel:
Channel selection reflects buyer technical sophistication and the complexity of certification documentation requirements.
- Direct Sales:Large chemical manufacturers negotiate volume contracts with fabricators for customized vessel specifications and integrated reconditioning services. Technical sales engineering supports UN certification compliance.
- Resellers:Regional distributors stock standard closed top designs for rapid fulfillment of replacement demand in industrial corridors.
- Offline:Traditional industrial supply relationships persist where buyers require physical inspection of weld quality and surface finish.
- Online:Digital procurement platforms penetrate standard specification segments with transparent pricing and documented certification downloads.
Direct sales capture the largest transaction value; online channels are expanding most quickly in standardized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Maharashtra are accelerating chemical infrastructure buildouts that concentrate IBC procurement around new polymer and specialty chemical complexes.
United States
Port Arthur and Baytown petrochemical expansions are generating concentrated demand for UN-certified transport vessels. EPA RCRA retirement cycles are compressing replacement timelines for hazardous material containers. Texas Gulf Coast clusters now represent the densest North American installation base for closed-top carbon steel IBCs.
Germany
Rhine-Ruhr chemical handlers face accelerated container turnover under REACH drum-retirement mandates. ECHA substance-of-very-high-concern disclosure requirements now extend to packaging coatings and gaskets. Leverkusen and Ludwigshafen industrial zones are driving precision-welded vessel specifications for pharmaceutical-grade applications.
India
Gujarat and Maharashtra industrial corridors lack mature reconditioning infrastructure, creating first-mover service opportunities for fleet managers. BIS certification requirements for pressure vessels are tightening fabrication standards. Dahej and Mundra SEZs are anchoring new chemical capacity that will outpace domestic IBC supply capabilities.
China
Yangtze River Delta chemical clusters are expanding specialty material production that demands corrosion-resistant container solutions. MEE environmental compliance inspections are accelerating retirement of legacy drum inventories. Ningbo and Shanghai port zones are standardizing UN-certified vessel specifications for export chemical shipments.
Saudi Arabia
Jubail and Yanbu industrial cities are scaling downstream petrochemical derivatives production requiring bulk liquid handling infrastructure. The country's national industrial development program is localizing packaging supply chains for chemical exports. Eastern Province clusters are importing European fabrication expertise to meet SABIC affiliate specifications.
Carbon Steel IBC Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated drum-IBC fabricators commanding premium positioning in North American chemical corridors while regional reconditioning networks anchor European service intensity. The vendor base concentrates around three strategic archetypes: vertically integrated steel drum specialists with captive IBC fabrication, standalone precision vessel welders targeting FDA-compliant finishes, and third-party fleet managers offering asset-pooling with bundled maintenance. Capacity expansion and coating technology licensing are the dominant competitive moves as fabricators defend carbon steel economics against stainless substitution.
Within the integrated steel packaging tier, Greif, Inc. and Mauser Packaging Solutions exemplify divergent geographic anchoring strategies. Greif leverages its North American drum and IBC manufacturing footprint to capture margin across chemical corridor demand. Mauser anchors European positioning through its closed-loop reconditioning network. Thielmann US LLC occupies the precision-welded specialist position, representing the FDA-compliant finish tier where laser-hybrid welding eliminates contamination vectors.
| Leading Market Players |
|---|
| Hoover Ferguson Group |
| Schutz Container Systems |
| Mauser Packaging Solutions |
| Greif, Inc. |
| Thielmann US LLC |
| Precision IBC, Inc. |
| Sharpsville Container Corporation |
| Snyder Industries Inc. |
| Custom Metalcraft Inc. |
| Others |
Value Chain & Pricing Dynamics
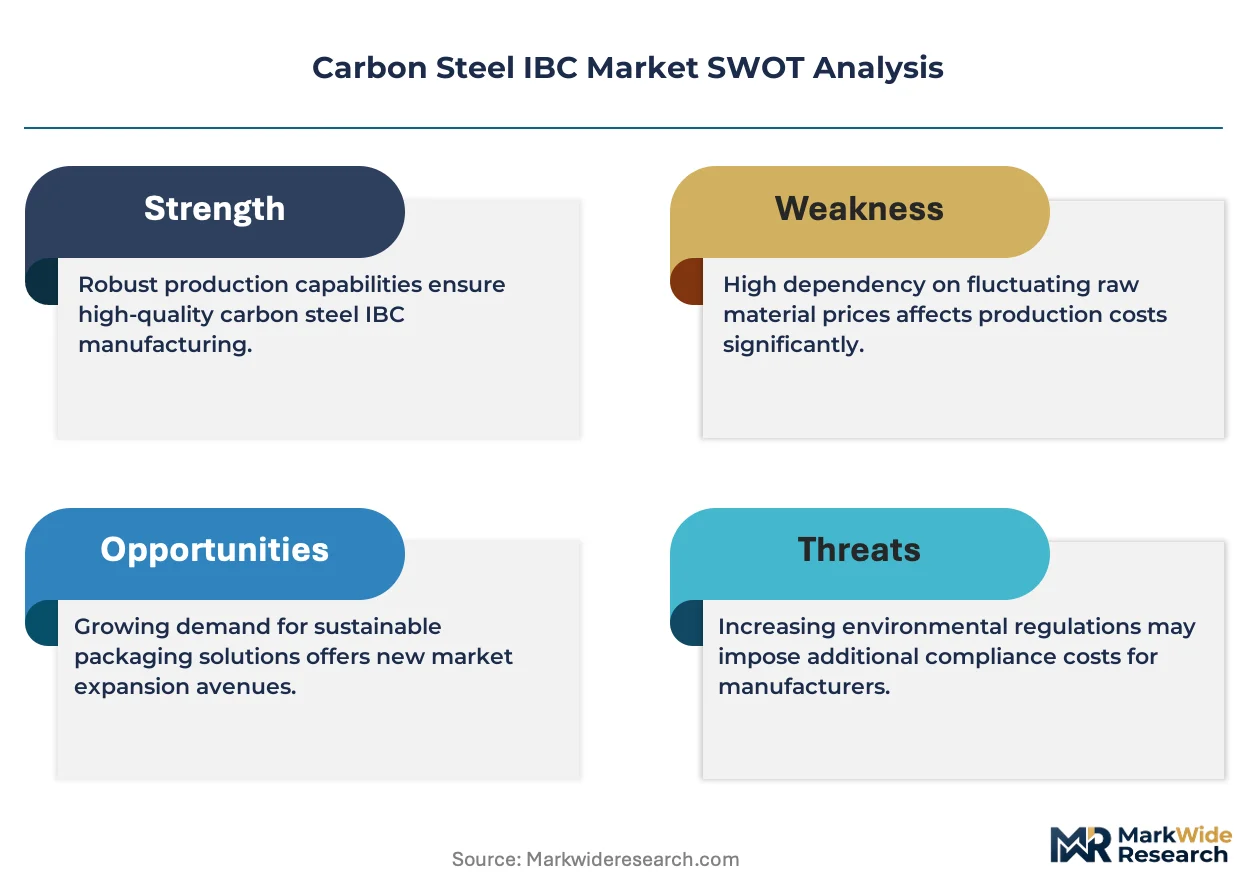
Certification-grade divergence between UN-certified precision vessels and commodity open-top designs splits both pricing power and supply chain configuration across the carbon steel IBC market. Premium welded construction commands 40-60% markups over standard closed-top units, while coating-grade tiers further stratify procurement economics in chemical corridors.
Pricing Analysis
Volume concentration in standard closed-top designs runs on thin commodity margins, while precision-welded pharmaceutical vessels sustain premium capture through FDA-compliant surface finishes. Price differentiation rests on ASME Section IX certification status and laser-hybrid welding capability. Cost compression in commodity tiers is intensifying because hot-rolled coil volatility transfers directly to fabricator quotes. Distributor pooling arrangements prove least price-sensitive; agricultural retailers purchasing seasonal open-top inventory show highest elasticity.
Supply Chain Analysis
Freight cost sensitivity anchors fabrication location decisions, with Texas Gulf Coast and Rhine-Ruhr clusters absorbing capacity to minimize hazardous material transport legs. Raw material flows draw from integrated US steel mills, German cold-rolling specialists, and Indian hot-rolled coil imports. Single-source vulnerability concentrates in epoxy-phenolic coating formulations subject to REACH SVHC disclosure thresholds. Distribution runs through direct sales for large chemical manufacturers and regional reseller networks for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-hybrid welding is displacing conventional MIG fabrication in pharmaceutical and food-grade applications, compressing legacy carbon steel economics while opening service-model opportunities for certified specialists.
For Market Incumbents: Deploy coating innovation as the primary defensive lever against stainless steel substitution in mildly corrosive chemical handling. Extend service life through zinc-rich interior linings in the Texas Gulf Coast cluster. Backward integration into captive hot-rolled coil supply buffers margin volatility from scrap availability swings. For New Entrants and Emerging Players: Enter via reconditioning infrastructure gaps in Gujarat and Maharashtra chemical corridors where BIS certification requirements are tightening fabrication standards. Target food-grade composite cage-polymer designs for clean-in-place protocols. Pursue asset-pooling service models with per-use pricing to bypass capital intensity barriers for mid-volume chemical SMEs. For Investors and Strategic Acquirers: Re-rating potential sits with precision-welded specialists given FDA-compliant finish requirements and laser-hybrid welding capability scarcity. Long-term viability favors fabricators with integrated reconditioning networks over pure manufacturing plays. Watch REACH Article 33 disclosure thresholds as the inflection signal for coating requalification costs and supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Licensing | Epoxy-phenolic formulations extend carbon steel service life against stainless substitution in chemical corridors. |
| Reconditioning Network Expansion | Closed-loop asset management captures recurring revenue from REACH-mandated container retirement cycles. |
| Laser-Hybrid Welding Investment | FDA-compliant seam integrity eliminates contamination vectors in pharmaceutical-grade vessel fabrication. |
| Asset-Pooling Service Launch | Per-use pricing transfers residual-value risk from chemical plants to third-party fleet managers. |
| Backward Integration into Steel Supply | Captive hot-rolled coil sourcing buffers margin compression from scrap availability volatility. |
Study Parameters
SEC 10-K filings, Cefic chemical industry reports, and customs trade data formed the secondary backbone, cross-referenced with primary interviews involving IBC fabricator plant managers, chemical procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors specializing in coating formulations. Bottom-up vessel shipment tallies and top-down chemical production capacity estimates were triangulated to anchor volume assumptions.
Bottom-up modeling tracked individual fabrication facility capacities and utilization rates across the projection horizon, while top-down analysis calibrated against petrochemical expansion announcements in Port Arthur, Baytown, and Dahej SEZs. Segmentation dimensions included certification tier, end-use industry corrosivity grade, coating specification, and regional regulatory cluster. CAGRs were derived from replacement cycle compression under EPA RCRA and REACH mandates, with hot-rolled coil price indices and welder certification scarcity feeding sensitivity bounds.
Revisions become necessary when REACH SVHC disclosure thresholds expand to additional coating chemistries, carbon-border adjustments alter virgin versus recycled steel economics, or UN Dangerous Goods model regulations harmonization accelerates certification requalification cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Bollard Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
North America Siding and Decking Market