
 North Africa Cement Market | 2026-2036
North Africa Cement Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Cement Market Intelligence
Capital-intensity divergence between integrated kiln operators and grinding-only competitors is collapsing as energy costs erase margin buffers for asset-light players. Dangote Cement leverages captive gas and coal supply chains across Nigeria and Senegal to sustain cost leadership. LafargeHolcim Maroc Afrique anchors premium blended cement production through clinker substitution technology. HeidelbergCement AG competes on logistics density, controlling coastal distribution networks that limit inland rivals.
North Africa cement denotes hydraulic binding materials manufactured from calcined limestone, clay, and gypsum at kiln temperatures exceeding 1,450°C, producing clinker that hydrates with water to form hardened stone-like structures essential for load-bearing construction. Portland cement dominates volume throughput across the region, though margin pools are migrating toward blended cement varieties as fly ash and slag substitution reduces clinker ratios and carbon exposure. Infrastructure application is accelerating fastest, driven by trans-Saharan corridor projects and desalination plant construction, while residential remains structurally mature in Egypt and Tunisia.
Egypt's Housing and Building National Research Center enforces compressive-strength grading that excludes substandard imports, while Morocco's adoption of EU-equivalent CE marking protocols under its national standardization body tightens export-access rules for Algerian mills. Algeria's Ministry of Industry applies import licensing that protects domestic clinker capacity. Stakeholders must monitor whether Tunisia's state cement monopoly restructuring unlocks private investment or triggers regional oversupply.
Market Dynamics
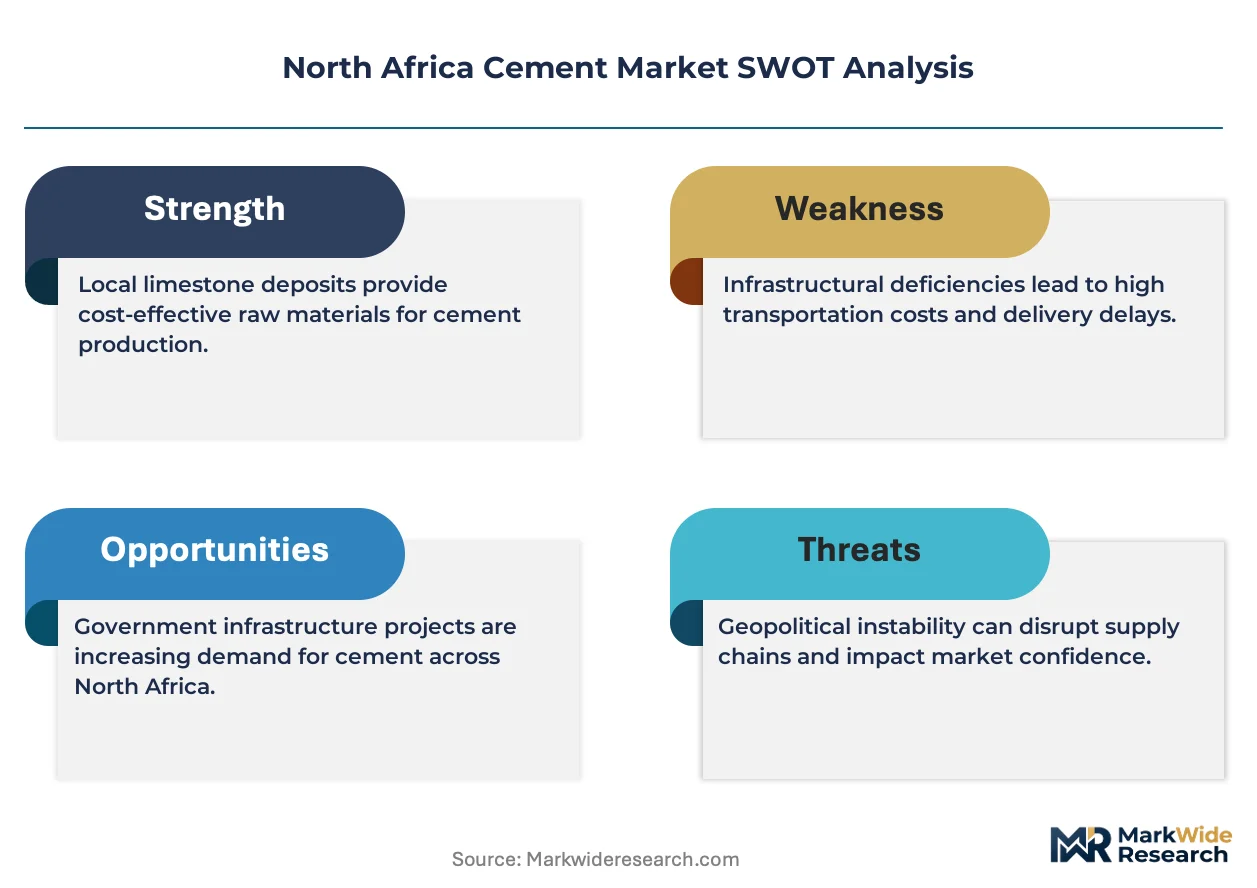
Energy cost asymmetry between integrated kiln operators and grinding-only competitors is collapsing margin buffers across the Maghreb, forcing asset-light players toward consolidation or exit.
Growth Catalysts
- Urban Migration Surge:Algeria's residential construction sector is absorbing record cement volumes as rural-to-urban population flows accelerate infrastructure buildout in secondary cities.
- CE Marking Alignment:Morocco's national standardization body has adopted EU-equivalent protocols, tightening quality benchmarks and filtering substandard imports from regional competitors.
- Clinker Substitution Technology:Fly ash and slag blending processes are reducing carbon exposure while preserving compressive strength, opening margin pools in premium blended cement categories.
Market Restraints
- Natural Gas Price Volatility:Egypt's cement kilns face input cost pressure from fluctuating feedstock pricing, eroding cost advantages for gas-dependent operators.
- Import Licensing Barriers:Algeria's Ministry of Industry applies restrictive permitting that fragments cross-border supply flows and protects inefficient domestic clinker capacity.
- Limestone Reserve Depletion:Tunisia's state monopoly controls access to high-grade calcareous deposits, constraining private kiln expansion.
Strategic Opportunities
- Trans-Saharan Corridor Infrastructure:Road and rail connectivity projects linking Algeria to sub-Saharan markets will generate sustained bulk cement offtake through 2035.
- Desalination Plant Construction:Morocco's Atlantic coastal corridor is deploying reverse osmosis facilities that require specialized sulfate-resistant cement formulations.
- Carbon Border Adjustment Preparation:Egypt's Housing and Building National Research Center is pre-positioning domestic producers for EU-equivalent emissions disclosure standards.
Industry Challenges
- Kiln Operator Skill Shortage:Process engineering expertise for 1,450°C clinker production is concentrated among aging workforces in Tunisia and Egypt.
- Compliance Timeline Compression:Morocco's rapid CE marking adoption is forcing smaller mills to accelerate certification investments or surrender export access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Cement Market |
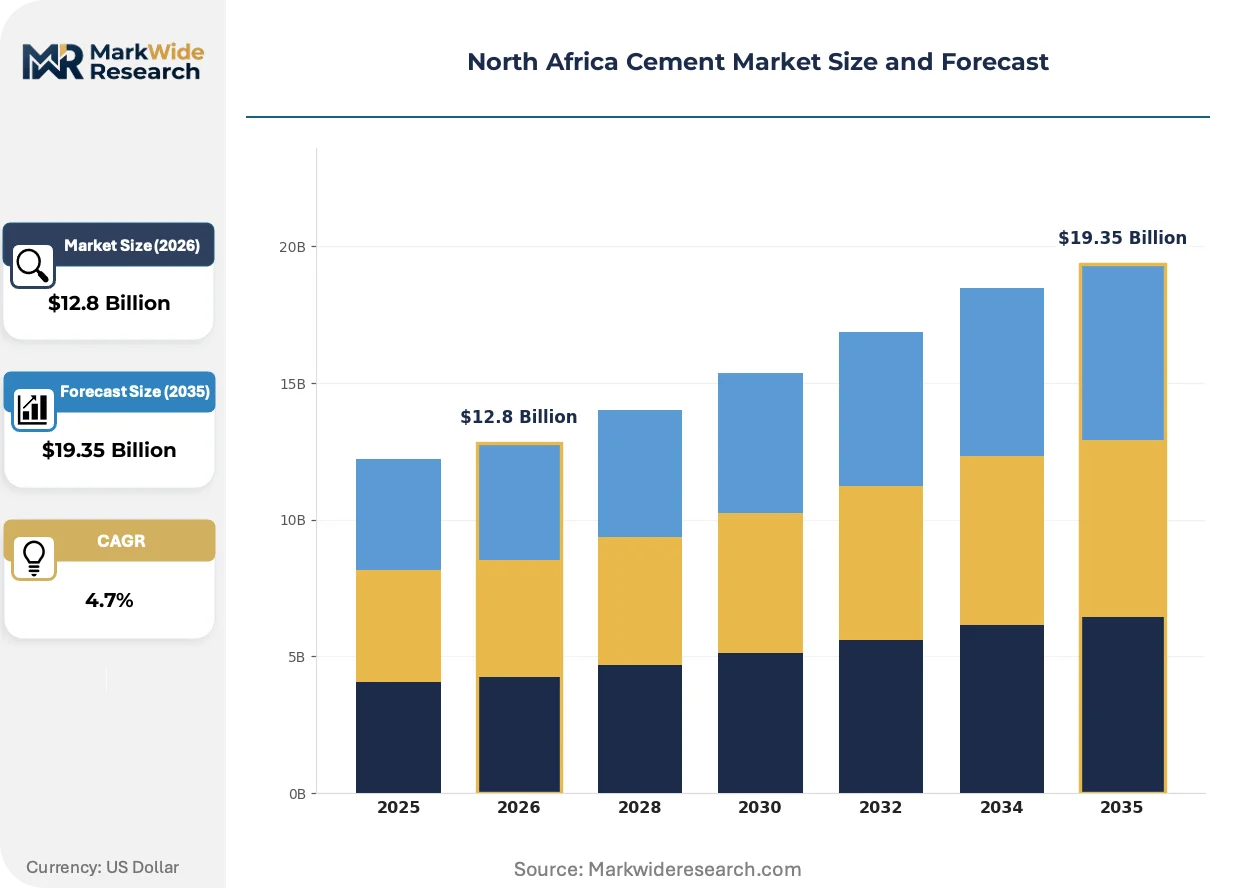
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, White Cement, Blended Cement, Hydraulic Cement Application: Construction, Infrastructure, Residential, Commercial End User: Contractors, Builders, Government, Real Estate Developers Distribution Channel: Direct Sales, Wholesalers, Retail, Online Platforms |
| Companies Covered | Dangote Cement, Ciments du Sahel, LafargeHolcim, Italcementi S.p.A., Vicat S.A., Lafarge Egypt, LafargeHolcim Maroc Afrique, HeidelbergCement AG, El Sewedy Cement, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Cement Market Strategic Shifts & Innovations
Decarbonization pressure and logistics optimization are reshaping competitive positioning across the Maghreb, with technology adoption splitting along asset-intensity lines.
Calcined clay activation is bifurcating the premium cement segment. LC3 (limestone calcined clay cement) formulations reduce clinker ratios by 50% while maintaining early strength performance. Infrastructure contractors in Morocco's industrial port zones are specifying LC3 for marine exposure applications. The technology is bifurcating procurement patterns between coastal projects with specification flexibility and inland residential builds locked into traditional Portland grades.
Egypt's Housing and Building National Research Center has enforced compressive-strength grading protocols that exclude substandard imports from Sudanese and Turkish mills. The regulation compresses price competition at the low end of the market. Domestic producers with captive laboratory certification capabilities are capturing specification-driven tenders in Cairo's new administrative capital construction.
Buyer concentration among state-backed infrastructure consortia is consolidating procurement authority away from fragmented retail distributors. Algeria's public works ministry now aggregates cement demand through centralized tender platforms. Large integrated operators with direct fleet access are displacing traditional merchant intermediaries in bulk contract fulfillment.
North Africa Cement Market Segmentation
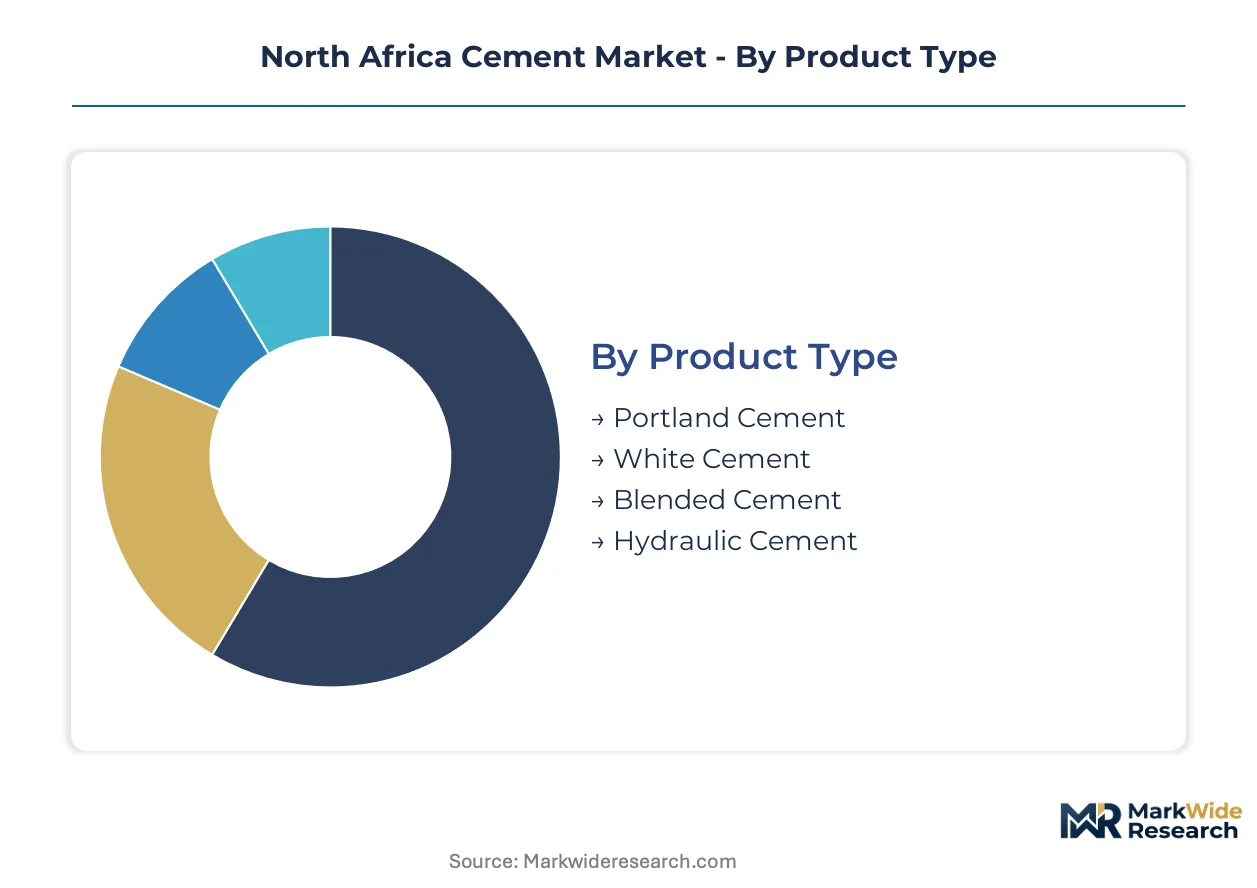
Segmentation in North Africa cement reveals how product specifications, procurement channels, and end-use concentration determine margin capture. Kiln operators align capacity investments to these divides, while grinding-only competitors target channel arbitrage.
Product Type:
Domestic consumption concentrates in standardized bulk grades, while export-accessible segments command specification premiums through certification alignment.
- Portland Cement:Composed of 95% clinker with 5% gypsum addition, achieving compressive strength exceeding 42.5 MPa under EN 197-1 protocols. Demand concentrates in Egypt's new administrative capital construction, where state-backed contractors enforce strict strength grading that excludes non-compliant imports.
- Blended Cement:Incorporates fly ash, slag, or limestone filler to reduce clinker ratios below 65%, cutting carbon exposure while preserving performance. Morocco's Atlantic coastal corridor projects specify blended grades for marine exposure, driven by port-linked industrial zones requiring sulfate resistance.
- White Cement:Manufactured from low-iron raw materials with specialized kiln firing, delivering aesthetic finish properties for architectural applications.
- Hydraulic Cement:Hydrates through chemical reaction with water independent of ambient conditions, enabling underwater and high-moisture construction.
Portland cement commands the established base. The steepest expansion runs through blended cement.
Application:
Volume scale separates commodity bulk flows from specification-driven premium segments, with infrastructure tenders consolidating procurement authority.
- Infrastructure:Trans-Saharan corridor road and rail projects in Algeria generate sustained bulk offtake through centralized public works tenders. Desalination plant construction along Morocco's Atlantic coast demands specialized sulfate-resistant formulations.
- Residential:Algeria's secondary cities absorb record volumes as rural-to-urban migration accelerates, though Egypt and Tunisia show structural maturity with slower growth trajectories.
- Construction:General-purpose building activity spans mixed-use developments requiring standard Portland grades with flexible delivery scheduling.
- Commercial:Office and retail developments concentrate in Cairo and Casablanca financial districts, with quality-sensitive developers specifying certified blended varieties.
Infrastructure commands the established base. Residential is climbing the fastest.
End User:
Buyer concentration determines channel power, with state-backed aggregators displacing fragmented retail procurement.
- Government:Algeria's public works ministry now aggregates cement demand through centralized tender platforms, favoring integrated operators with direct fleet access over merchant intermediaries.
- Contractors:Large infrastructure consortia in Egypt's new administrative capital construction enforce laboratory certification requirements that filter substandard supply.
- Real Estate Developers:Quality-sensitive private developers in Morocco's Atlantic coastal corridor specify LC3 formulations for premium positioning.
- Builders:Small-scale residential builders in Tunisia face constrained access to high-grade limestone reserves controlled by state monopoly restructuring.
Government procurement commands the established base. Contractor consolidation is gaining share fastest.
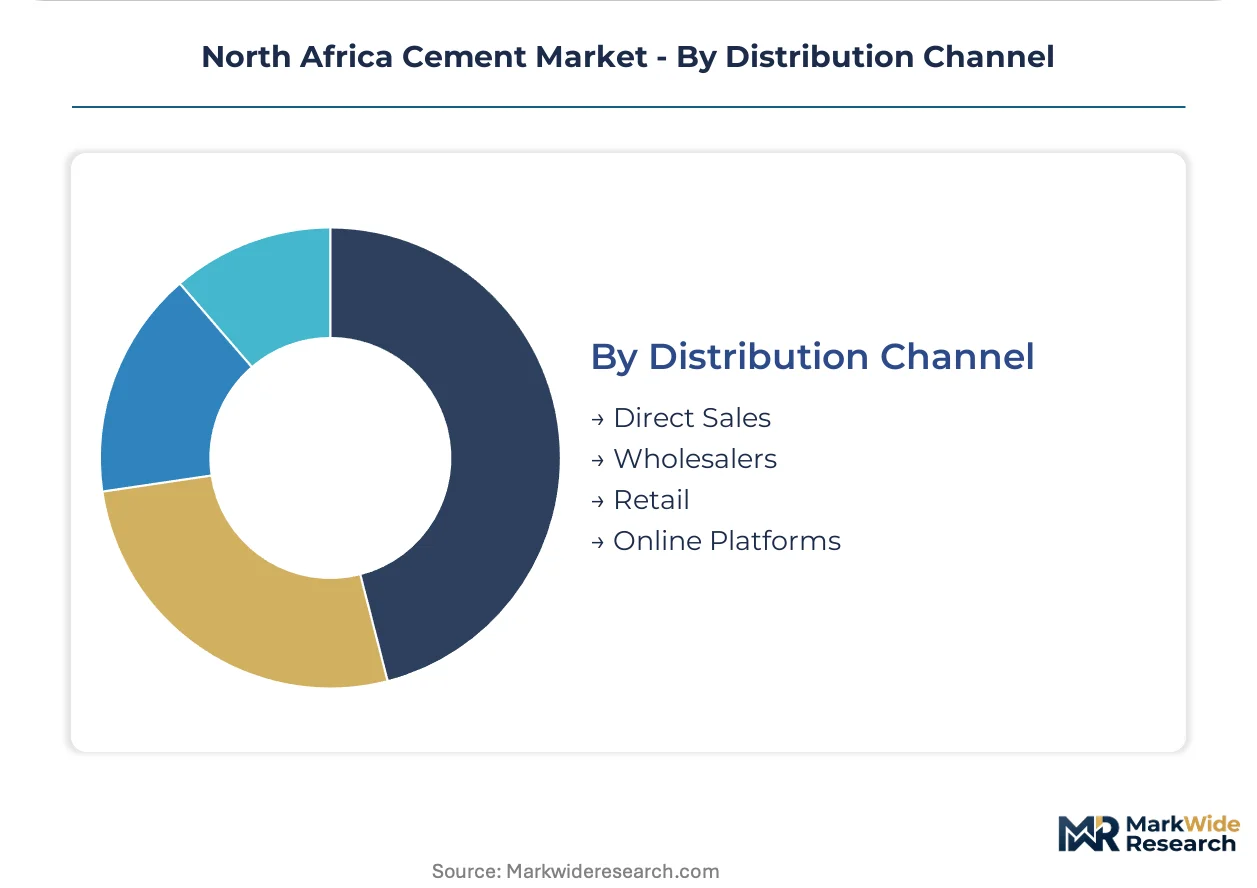
Distribution Channel:
Logistics density separates coastal integrated operators from inland competitors, with fleet ownership determining fulfillment reliability.
- Direct Sales:HeidelbergCement AG and LafargeHolcim Maroc Afrique leverage coastal distribution networks to serve bulk infrastructure contracts with dedicated fleet deployment.
- Wholesalers:Traditional merchant intermediaries retain position in fragmented retail markets but lose share to direct procurement platforms.
- Retail:Small-bag sales through construction material yards serve residential builders in Algeria's secondary cities with flexible quantity scheduling.
- Online Platforms:Emerging digital procurement channels in Egypt's private sector construction offer price transparency but limited bulk fulfillment capability.
Direct sales commands the established base. Online platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt commands pricing power through specification-grade enforcement while Algerian mills absorb cost pressure from import licensing barriers. Morocco's CE marking alignment creates quality arbitrage against regional competitors. Tunisia's state monopoly restructuring remains the wildcard for supply expansion.
Algeria
Secondary cities absorb record cement volumes as rural-to-urban migration accelerates residential construction. The Ministry of Industry applies restrictive import licensing that protects domestic clinker capacity from regional competition. The Atlantic coastal corridor concentrates port-linked industrial zones where procurement geography is reshaping distribution networks.
Egypt
The new administrative capital construction drives specification-grade demand through centralized government tenders. The Housing and Building National Research Center enforces compressive-strength grading that excludes substandard imports from Sudanese and Turkish mills. Cairo's laboratory-certified producers capture infrastructure tenders requiring strict quality protocols.
Morocco
Desalination plant construction along the Atlantic coast demands specialized sulfate-resistant cement formulations for marine exposure. The national standardization body has adopted EU-equivalent CE marking protocols that tighten quality benchmarks for regional competitors. Casablanca's industrial port zones specify LC3 limestone calcined clay cement for premium infrastructure applications.
Tunisia
Structural maturity in residential construction limits volume growth despite steady replacement demand. The state cement monopoly controls access to high-grade limestone reserves, constraining private kiln expansion. Coastal distribution networks face uncertainty as restructuring debates determine whether private investment unlocks capacity or triggers regional oversupply.
Libya
Post-conflict reconstruction generates intermittent bulk cement demand through public works rehabilitation. The central government lacks unified regulatory enforcement, fragmenting procurement across municipal authorities. Coastal terminals near Tripoli and Benghazi concentrate import-dependent supply flows while inland logistics remain disrupted.
North Africa Cement Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Maghreb cement sector. Integrated kiln operators with captive energy supply chains dominate cost-efficient bulk production, while grinding-only competitors face margin compression from volatile natural gas pricing. The market structure splits between multinational conglomerates with coastal logistics density and regional specialists serving protected domestic markets. Consolidation pressure is accelerating as asset-light players exit toward integrated operators or cross-border partnerships.
Within the multinational tier, LafargeHolcim Maroc Afrique and HeidelbergCement AG anchor premium positioning through coastal distribution networks and specification-grade certification capabilities. Dangote Cement exemplifies the integrated cost-leadership archetype with captive fuel supply chains spanning Nigeria and Senegal. These three entities represent the dominant competitive anchors shaping procurement consolidation and technology licensing patterns across North African markets.
| Leading Market Players |
|---|
| Dangote Cement |
| Ciments du Sahel |
| LafargeHolcim |
| Italcementi S.p.A. |
| Vicat S.A. |
| Lafarge Egypt |
| LafargeHolcim Maroc Afrique |
| HeidelbergCement AG |
| El Sewedy Cement |
| Others |
Cost & Logistics Intelligence
Fly ash and slag substitution for clinker is collapsing the traditional cost-plus pricing model while redrawing procurement geography around coastal grinding terminals with bulk import access. Cement buyers now face divergent economics between inland markets tethered to domestic kiln capacity and port-linked zones arbitraging seaborne clinker supply.
Pricing Analysis
The customization-premium spread between specification-grade LC3 formulations and standard Portland bulk separates procurement budgets by application criticality. Three-tier pricing structure across premium blended, standard Portland, and economy bulk levels stratifies around certification grade and volume scale, with Morocco's CE marking alignment compressing margins for uncertified Algerian supply. Pricing pressure stems from natural gas volatility eroding gas-dependent operators' cost positions. Government infrastructure consortia exhibit lowest price sensitivity due to specification mandates, while small residential builders in Algeria's secondary cities face acute budget constraints.
Supply Chain Analysis
Strait of Gibraltar transit underwrites clinker import economics for Morocco's Atlantic coastal corridor, anchoring supply concentration in Egypt, Algeria, and Morocco. Raw material dependencies center on limestone reserves, petroleum coke, and natural gas feedstock. Single-source vulnerability concentrates in Tunisia's state-controlled calcareous deposits. Distribution runs through coastal bulk terminals serving direct sales contracts, with inland markets fragmenting across wholesaler networks and construction material yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process engineering expertise for 1,450°C clinker production has concentrated among aging workforces in Tunisia and Egypt, creating a bottleneck that constrains capacity expansion regardless of capital availability. This capability scarcity favors incumbents with established kiln operations while raising barriers for new entrants lacking technical apprenticeship pipelines.
For Market Incumbents: Consolidate coastal logistics density through dedicated fleet expansion and terminal control to defend against grinding-only competitors arbitraging seaborne clinker. Deepen backward integration into captive fuel supply chains as natural gas volatility threatens gas-dependent operators. Prioritize laboratory certification capabilities to capture specification-driven government tenders excluding substandard imports. For New Entrants and Emerging Players: CE marking fast-track certification opens access to Morocco's Atlantic coastal corridor where port-linked industrial zones specify premium blended grades. Target Algeria's secondary cities with flexible retail bag distribution bypassing centralized government tender platforms. Pursue joint venture structures with existing terminal operators to overcome capital intensity barriers. For Investors and Strategic Acquirers: Tunisia's state monopoly restructuring reshapes the acquisition landscape between privatization opportunity and regional oversupply risk. Long-term viability favors integrated kiln operators with coastal terminal assets and captive energy positions over asset-light grinding competitors. Monitor Algeria's Ministry of Industry import licensing stance as the inflection signal for cross-border supply normalization.| Strategic Initiative | Industry Significance |
|---|---|
| LC3 Technology Licensing | Clinker ratio reduction preserves margins under carbon border adjustment preparation by Egypt's Housing and Building National Research Center. |
| Coastal Terminal Expansion | Port-linked grinding capacity captures Morocco's desalination plant construction requiring sulfate-resistant cement formulations. |
| Captive Fuel Supply Integration | Upstream control over petroleum coke and natural gas hedges against feedstock volatility eroding gas-dependent kiln economics. |
| Laboratory Certification Investment | Compressive-strength grading compliance unlocks Egypt's new administrative capital infrastructure tenders excluding non-compliant imports. |
| Trans-Saharan Logistics Partnership | Road and rail corridor pre-positioning secures bulk offtake from Algeria's public works ministry centralized tender platforms. |
Research Approach
The analysis maps Portland cement, blended cement, white cement, and hydraulic cement segments, each validated through primary interviews with kiln operations directors, public works procurement officers, coastal terminal managers, and construction material distributors. Secondary sources include customs and trade flow databases, national standardization body filings, SEC 10-K disclosures from multinational producers, and infrastructure project development registries. Bottom-up capacity modeling triangulates against top-down consumption estimates from construction activity indices.
Consistency checks validated volume and value outputs against external benchmarks including national cement association statistics and cross-border trade documentation. The analytical framework segments by product type, application, end user, and distribution channel across the projection horizon. CAGRs derive from regression analysis of historical consumption patterns against construction sector growth drivers, incorporating limestone reserve depletion curves and energy cost trajectories as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure spending levels, regulatory enforcement continuity, or energy price stabilization would require recalibration. Forecasts reflect documented assumptions regarding urban migration rates, state monopoly restructuring timelines, and carbon disclosure standard adoption. Practitioners should keep alternative scenarios live as Algeria's import licensing regime, Tunisia's privatization trajectory, and EU-equivalent certification alignment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Concrete Protective Liners Market