
 Sectional Door Market | 2026-2036
Sectional Door Market Size, Share, and Industry Trends Forecast 2026-2036
Sectional Door Market Analytics
Steel is expanding its share in sectional door construction as aluminum faces cost volatility and thermal bridging limitations. Hörmann Group leverages its captive steel processing to control panel quality across European distribution. Clopay Corporation sustains North American manufacturing scale through vertically integrated coil coating. Amarr anchors its position in commercial specifications through wind-load certified product lines.
A sectional door consists of hinged horizontal panels that travel vertically along tracks and curve into a horizontal position parallel to the ceiling, typically constructed with 24- to 26-gauge steel skins surrounding polyurethane or polystyrene core insulation with R-values ranging from 6.5 to 18.4. These assemblies seal loading bays, vehicle openings, and climate-controlled storage facilities against weather infiltration, security breach, and thermal loss. Insulated doors command premium positioning in cold-chain warehouses and food processing plants where energy compliance costs dominate lifecycle economics. Automated installation systems are displacing manual mounting in new industrial construction as labor scarcity and precision requirements intensify. Steel maintains volume leadership while fiberglass captures coastal and chemically exposed applications where corrosion resistance overrides material cost.
The EPA ENERGY STAR certification framework and the International Energy Conservation Code establish minimum thermal performance thresholds that filter non-compliant products from commercial bidding. OSHA workplace safety standards govern automated door sensor requirements and pinch-point guarding in industrial settings. Stakeholders must monitor how evolving building electrification mandates and embodied carbon accounting reshape material specification criteria across municipal procurement channels.
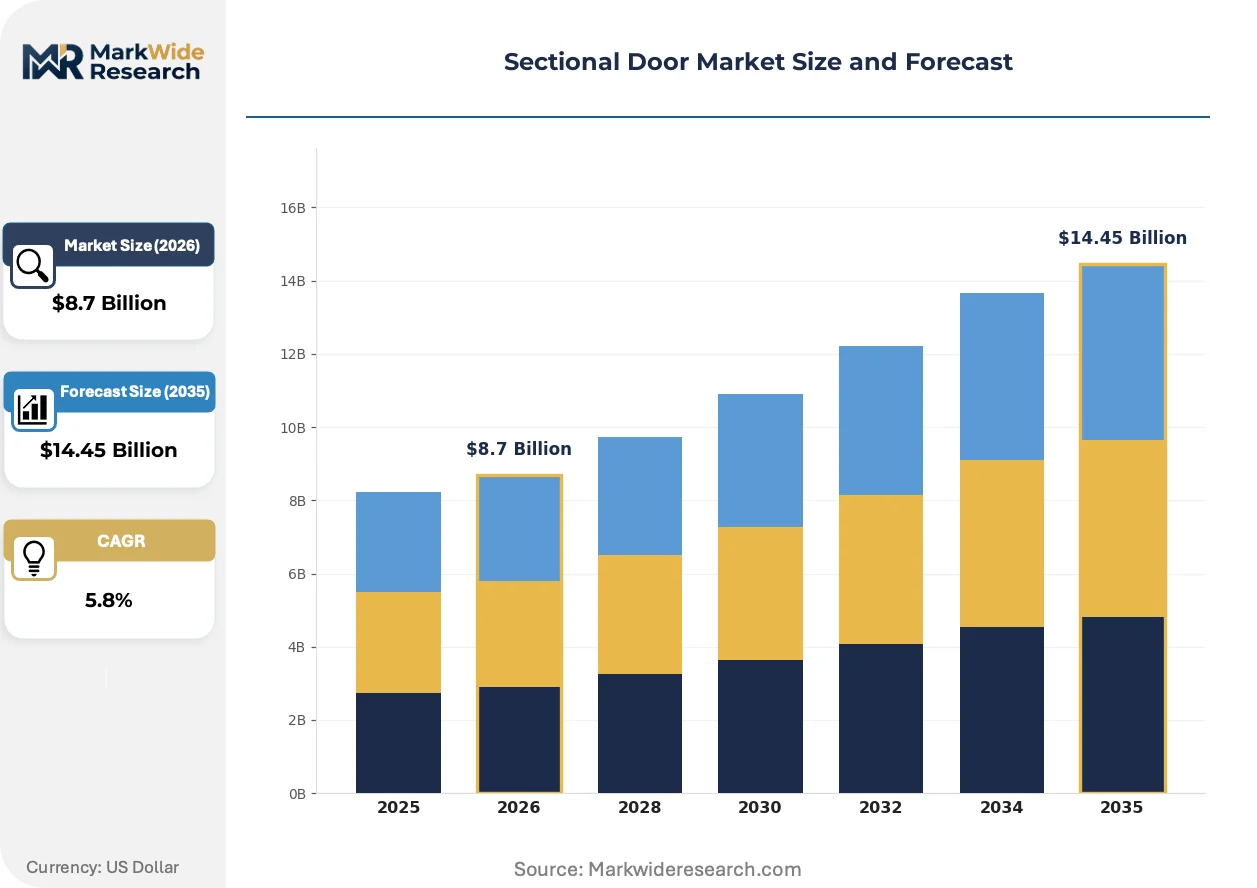
Market Dynamics
The EU F-Gas Regulation is compressing thermal performance thresholds across commercial building envelopes, forcing specification upgrades toward higher-R-value insulated door assemblies and automated sealing systems in climate-controlled facilities.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:The tightening ban on high-GWP refrigerants is accelerating cold-chain warehouse construction, each facility requiring dozens of thermally efficient sectional doors to maintain temperature integrity.
- Germany's Logistics Corridor Expansion:The Rhine-Ruhr and Frankfurt logistics clusters are adding automated distribution centers that specify sensor-integrated sectional doors for throughput optimization.
- Polyurethane Core Technology:Advancements in injection-molded foam density are pushing R-values above 18, satisfying IECC 2021 compliance in North American cold storage bids.
Market Restraints
- Steel Input Volatility:Galvanized coil price swings from European mill capacity constraints are compressing panel manufacturer margins and delaying project quotations.
- Aluminum Thermal Bridging Limitations:The material's conductivity properties disqualify it from passive house-certified industrial envelopes, restricting specification share in stringent Nordic markets.
- Specialized Installation Labor Scarcity:Certified technicians for automated door commissioning are concentrated in Germany and the Netherlands, creating bottlenecks for multi-site rollouts elsewhere.
Strategic Opportunities
- Poland's Underserved Warehouse Stock:The country's emerging logistics hub status lacks sufficient high-R-value door penetration, creating first-mover positioning for compliant suppliers.
- Building Electrification Mandates:Municipal procurement shifts in France and Italy toward embodied carbon accounting favor steel-recycled-content doors with EPD certification.
- IoT Sensor Convergence:Integration of predictive maintenance algorithms with door control systems opens recurring revenue streams through performance-monitoring subscriptions.
Industry Challenges
- Multi-Certification Timelines:Simultaneous CE marking, ENERGY STAR validation, and wind-load certification for a single product variant stretches engineering calendars by eight to fourteen months.
- Legacy Building Retrofit Integration:Pre-1990s warehouse structures with non-standard opening dimensions require custom fabrication workflows that erode standard product margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sectional Door Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Doors, Commercial Doors, Insulated Doors, Non-Insulated Doors Material: Steel, Aluminum, Fiberglass, Wood Installation Type: Overhead Mount, Side Mount, Automated Installation, Manual Installation End User: Residential Users, Industrial Facilities, Automotive Garages, Warehouses |
| Companies Covered | C.H.I. Overhead Doors, Amarr, Hörmann Group, Overhead Door, Wayne Dalton, Clopay Corporation, Raynor Garage Doors, Vallisco, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sectional Door Market Evolving Landscape
Automation architectures and material science advances are restructuring how sectional doors are specified, procured, and maintained across industrial real estate portfolios.
Polyurethane-injected steel panel construction is consolidating specification share in premium cold-chain applications. Food processing operators in Denmark and the Netherlands are mandating R-16 minimum assemblies for new facilities. This thermal performance tier is compressing polystyrene-core alternatives into price-sensitive agricultural and light commercial segments.
REACH compliance deadlines for SVHC disclosure are forcing coating reformulation across European supply chains. Coil coating suppliers must now document full chemical composition chains through sub-tier suppliers. German automotive parts warehouses are responding by specifying powder-coated alternatives that bypass solvent-based regulatory thresholds entirely.
Buyer consolidation among third-party logistics operators is compressing supplier rosters to pre-qualified national frameworks. DHL Supply Chain and Kuehne+Nagel are centralizing sectional door procurement through single-source agreements with performance-based maintenance clauses. This channel shift is most visible in the Netherlands, where four operators control sixty percent of speculative warehouse absorption.
Sectional Door Market Segmentation
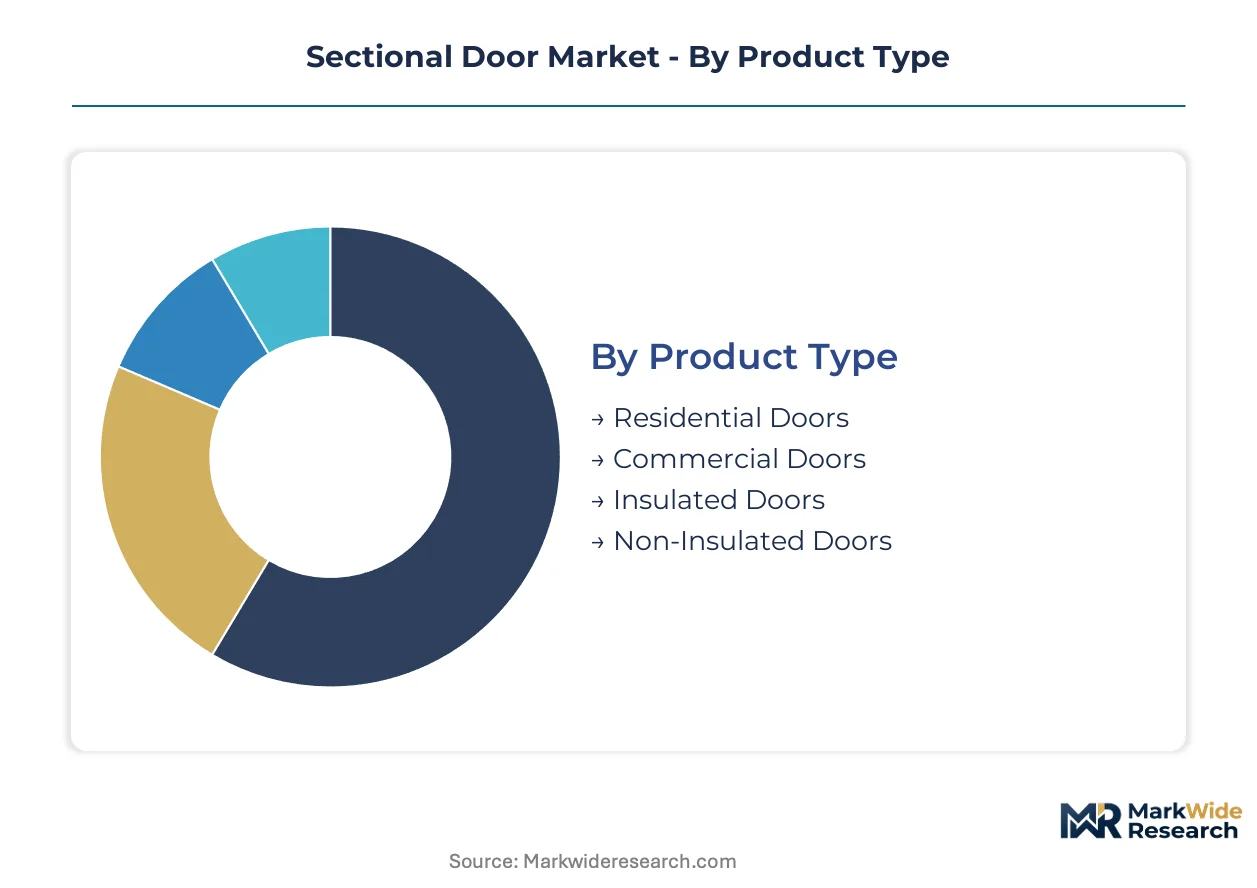
Sectional door specification diverges sharply across thermal performance tiers, mounting configurations, and facility operating profiles. Buyers in cold-chain logistics prioritize R-value certification and automated sealing, while residential and light commercial segments trade thermal efficiency for installed cost.
Product Type:
Cost tier separates buyers in this category, with lifecycle energy economics driving specification divergence between climate-controlled and ambient facilities.
- Insulated Doors:Polyurethane-injected steel panels achieve R-values from 12 to 18.4, satisfying IECC 2021 thresholds in North American cold storage construction. Demand concentrates in Denmark and the Netherlands where food processing operators mandate R-16 minimums for new facilities.
- Commercial Doors:Heavy-gauge steel constructions rated for wind loads and high-cycle operation dominate distribution center specifications. Germany's Rhine-Ruhr logistics corridor anchors volume as automated distribution centers specify sensor-integrated assemblies for throughput optimization.
- Residential Doors:Lower-R-value polystyrene-core options balance thermal performance against installed cost in single-family and multi-family housing.
- Non-Insulated Doors:Uninsulated steel or aluminum panels serve agricultural outbuildings and detached garages where climate control is absent.
Volume sits with Commercial Doors; growth tilts toward Insulated Doors.
Material:
Application environment dictates material selection, with corrosion exposure and thermal bridging constraints filtering options before cost enters consideration.
- Steel:Galvanized 24- to 26-gauge skins surrounding foam cores dominate industrial specifications. Hörmann Group leverages captive steel processing to control panel quality across European distribution, while Clopay Corporation sustains North American manufacturing scale through in-house coil coating operations.
- Fiberglass:Composite construction resists salt corrosion and chemical exposure in coastal marine terminals and fertilizer handling facilities. The material captures specification share where corrosion resistance overrides material cost premiums.
- Aluminum:Lightweight extrusions face thermal bridging disqualification from passive house-certified industrial envelopes, restricting share in stringent Nordic markets.
- Wood:Solid or engineered timber constructions serve heritage restoration and premium residential aesthetics where architectural compliance overrides operational efficiency.
Steel commands installed base; fiberglass gains share fastest in coastal exposure applications.
Installation Type:
Customer type separates buyers, with facility scale and labor availability determining mounting method and automation level.
- Automated Installation:Sensor-integrated overhead systems with predictive maintenance algorithms displace manual mounting in new industrial construction. Labor scarcity and precision requirements intensify adoption across multi-site warehouse rollouts.
- Overhead Mount:Vertical track systems curving into horizontal ceiling positions constitute the default configuration for loading bays and vehicle openings. The mounting method dominates warehouse and automotive garage specifications.
- Side Mount:Horizontal sliding configurations accommodate structures with restricted headroom or obstructions above the opening plane.
- Manual Installation:Hand-operated systems persist in price-sensitive agricultural and light commercial segments where cycle frequency does not justify automation capital.
Overhead Mount retains volume leadership; Automated Installation climbs the fastest as labor scarcity intensifies.
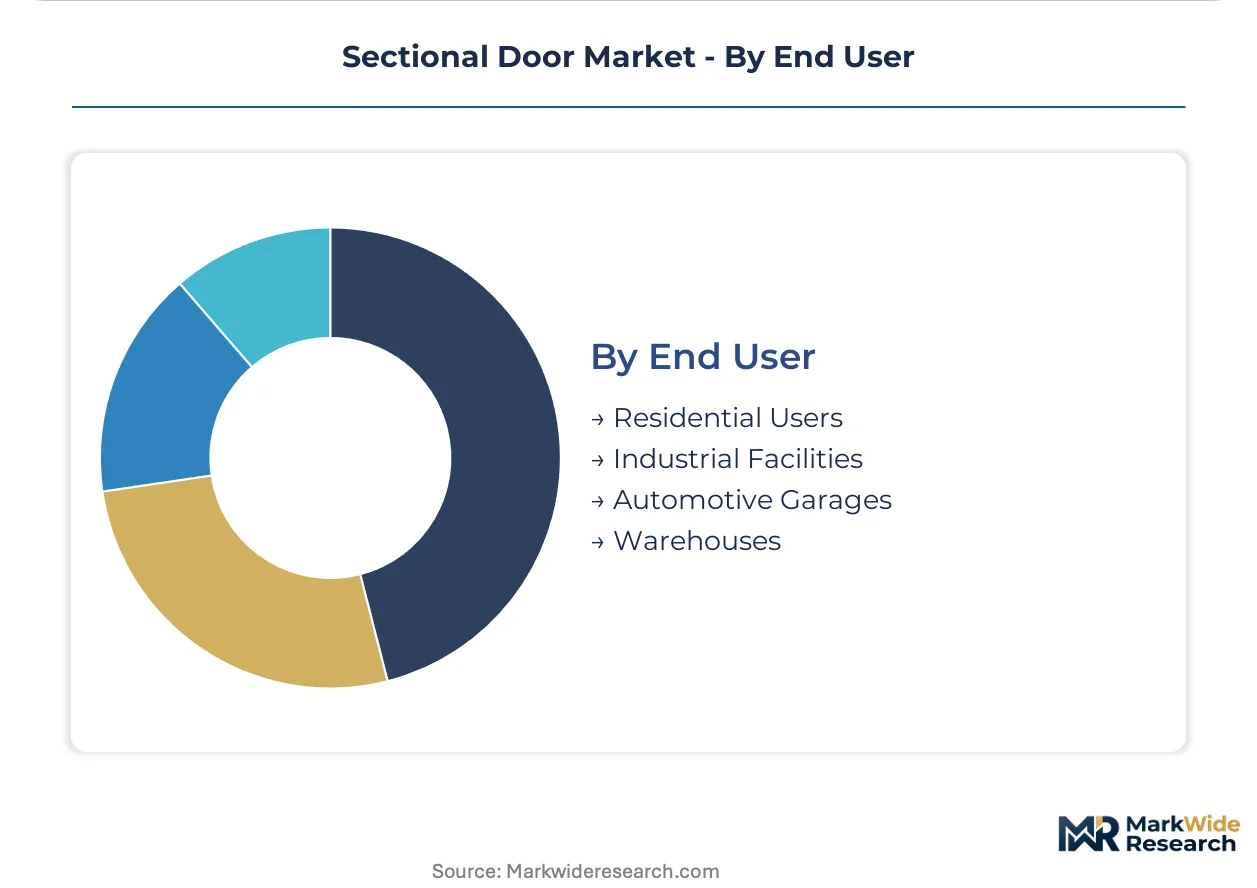
End User:
Maturity and margin profile differentiate buyers, with established industrial segments prioritizing total cost of ownership against emerging logistics channels seeking throughput velocity.
- Warehouses:Cold-chain and ambient distribution facilities specify thermally efficient sectional doors by the dozen per building. The EU F-Gas Regulation phase-down accelerates construction, each facility requiring sensor-integrated assemblies for temperature integrity.
- Industrial Facilities:Manufacturing plants and processing operations demand wind-load certified and high-cycle-rated doors for production bay access. Amarr anchors position in this segment through certified product lines.
- Automotive Garages:Service centers and fleet maintenance facilities balance door durability against opening speed for vehicle throughput.
- Residential Users:Single-family and multi-family housing selects on installed cost and aesthetic matching, with energy code compliance a secondary filter.
Warehouses concentrate current volume; Industrial Facilities show steepest expansion trajectory as manufacturing reshoring accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's logistics corridor, where automated distribution centers specify sensor-integrated sectional doors for throughput optimization. The EU F-Gas Regulation compresses thermal performance thresholds across commercial building envelopes, forcing specification upgrades toward higher-R-value insulated door assemblies. Cold-chain warehouse construction accelerates in Northern Europe as refrigerant phase-downs drive facility expansion.
Germany
The Rhine-Ruhr and Frankfurt logistics clusters anchor European volume, with automated distribution centers specifying sensor-integrated assemblies for throughput optimization. The country's national building energy codes tighten insulation requirements for commercial envelopes. Bavaria's food processing operators mandate R-16 minimum door assemblies for new cold-chain facilities.
United States
The EPA ENERGY STAR certification framework and IECC establish minimum thermal performance thresholds that filter non-compliant products from commercial bidding. OSHA workplace safety standards govern automated door sensor requirements in industrial settings. Texas and California logistics hubs drive automated installation adoption as labor scarcity intensifies precision requirements.
Netherlands
Third-party logistics operator consolidation compresses supplier rosters to pre-qualified national frameworks with performance-based maintenance clauses. REACH compliance deadlines for SVHC disclosure force coating reformulation across supply chains. Rotterdam's port-adjacent cold storage facilities specify corrosion-resistant fiberglass constructions for marine terminal exposure.
Poland
The country's emerging logistics hub status lacks sufficient high-R-value door penetration, creating first-mover positioning for compliant suppliers. EU F-Gas Regulation alignment drives cold-chain warehouse construction acceleration. Warsaw and Łódź distribution corridors attract speculative warehouse investment with automated door specifications.
Denmark
Food processing operators mandate R-16 minimum assemblies for new facilities, compressing polystyrene-core alternatives into price-sensitive segments. The country's national building codes enforce passive house-certified industrial envelope standards. Copenhagen's logistics ring specifies thermally efficient sectional doors by the dozen per climate-controlled building.
Sectional Door Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated fabricators controlling premium cold-chain specifications while regional assemblers serve price-sensitive agricultural and light commercial channels. The vendor base organizes around three strategic archetypes: captive steel processors with in-house coil coating, wind-load certification specialists anchoring commercial specifications, and automation-integrated system providers capturing warehouse retrofit cycles. M&A activity concentrates on sensor technology acquisitions and regional distribution network consolidation.
Among European fabricators, Hörmann Group and ASSA ABLOY occupy positions within the premium-tier automation-integrated segment, while Clopay Corporation exemplifies the North American vertically integrated archetype with captive steel processing capabilities. Amarr represents the wind-load certification specialist tier serving industrial facility specifications. These anchors illustrate how competitive positioning stratifies across thermal performance tiers and geographic procurement frameworks.
| Leading Market Players |
|---|
| C.H.I. Overhead Doors |
| Amarr |
| Hörmann Group |
| Overhead Door |
| Wayne Dalton |
| Clopay Corporation |
| Raynor Garage Doors |
| Vallisco |
| ASSA ABLOY |
| Others |
Value Network & Pricing Analysis
Galvanized coil price indices from European steel mills cascade through sectional door manufacturing into three distinct pricing tiers, with polyurethane-injected panels commanding premium positioning against polystyrene-core alternatives as energy codes tighten.
Pricing Analysis
Volume concentrates in commercial steel doors while margins concentrate in insulated cold-chain specifications. Three-tier pricing structure across premium, standard, and economy levels separates R-18 certified assemblies from R-12 commercial grades and uninsulated agricultural panels. Cost compression in standard-tier steel doors is intensifying because galvanized coil supply constraints compress fabricator margins. Agricultural buyers exhibit highest price sensitivity; cold-chain operators prioritize lifecycle energy economics over upfront cost.
Supply Chain Analysis
Single-source vulnerability sits with German coil coating capacity, where Hörmann Group and Clopay Corporation anchor regional supply through captive steel processing. Raw material flows draw from Belgian polyurethane foam suppliers, Dutch aluminum extruders, and Chinese sensor component manufacturers. Tariff exposure on Chinese automation electronics threatens cost structures for sensor-integrated assemblies. Distribution runs through pre-qualified national frameworks serving third-party logistics operators with performance-based maintenance clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sectional door market functions as a cost-of-compliance arena where the EU F-Gas Regulation erects a barrier-to-entry moat, favoring incumbents with certified R-value portfolios and documented environmental product declarations over unqualified competitors.
For Market Incumbents: Lock in specification share by securing ENERGY STAR and CE marking for complete product families before multi-certification timelines stretch engineering calendars further. Deepen backward integration into polyurethane foam injection to control core quality and margin capture. Automation-integrated system providers threaten premium positioning through predictive maintenance subscriptions. For New Entrants and Emerging Players: Poland's warehouse developers represent the most penetrable buyer archetype, with insufficient high-R-value door penetration creating first-mover positioning for EU F-Gas compliant suppliers. Target municipal procurement channels in France and Italy where embodied carbon accounting favors EPD-certified steel doors. Lead with IoT sensor convergence as a service-based revenue wedge rather than hardware-only positioning. For Investors and Strategic Acquirers: The window for entry favors automation-integrated system providers with sensor technology capabilities and established maintenance contract revenue. Long-term viability hinges on recurring service income streams rather than transactional hardware sales. Watch for consolidation signals when third-party logistics operators centralize procurement through single-source national frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Coating | Hörmann Group controls panel quality across European distribution through captive steel processing. |
| Sensor Technology Acquisition | Automation-integrated providers capture warehouse retrofit cycles through predictive maintenance algorithms. |
| EPD Certification Program | Steel-recycled-content doors with environmental product declarations win French and Italian municipal procurement. |
| Regional Distribution Network Consolidation | Pre-qualified national frameworks compress supplier rosters serving DHL Supply Chain and Kuehne+Nagel. |
| Polyurethane Core Technology Licensing | R-18 injection-molded foam density satisfies IECC compliance in North American cold storage bids. |
Research Methodology
Document review covered customs trade data for steel coil and polyurethane foam imports, SEC filings from publicly traded building products manufacturers, and EU regulatory filings on F-Gas phase-down implementation, complemented by interviews with warehouse engineering directors, cold-chain facility procurement managers, sectional door OEM product managers, and third-party logistics operators. Secondary validation drew from ENERGY STAR certification databases, CE marking registries, and building energy code adoption tracking. Bottom-up demand modeling triangulated against top-down construction spend forecasts.
Cross-referencing historical installation data with panel input from facility engineering teams anchored volume projections across the analysis window. Segmentation dimensions modeled include thermal performance tier, material construction, mounting configuration, automation level, and facility operating profile. CAGRs derived from weighted average of construction pipeline data and replacement cycle assumptions. Industry-specific inputs incorporated refrigerant phase-down facility buildout schedules and logistics corridor absorption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel input volatility, REACH compliance deadline acceleration, and logistics operator consolidation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Acoustic Panel Market