
 Europe Particle Board Market | 2026-2036
Europe Particle Board Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Particle Board Market Foresight
Modular cabinetry kits and pre-cut furniture bundles are repositioning how European buyers specify particle board, shifting volume from commodity sheets to configured solutions. EGGER leverages its integrated resin and substrate operations to control cost position across Central European plants. Swiss Krono Group anchors production scale in Poland and Germany, sustaining supply continuity for large-format retail contracts. Kronospan competes through specialty-grade capacity, dominating fire-retardant and moisture-resistant segments for commercial construction.
Europe Particle Board is an engineered wood product manufactured from compressed wood particles, chips, and flakes bonded with synthetic resin under heat and pressure, typically achieving densities between 600 and 800 kg per cubic meter. Its primary purpose is to provide dimensionally stable, cost-efficient panel substrates for furniture, interior fit-outs, and structural applications where solid timber proves uneconomical. Melamine Faced Particle Board captures the dominant margin pool, as surface-prefinished panels eliminate downstream lamination steps for furniture manufacturers. Standard Particle Board remains volume-heavy but faces substitution pressure from oriented strand board in flooring applications. Distribution through wholesale channels controls the largest throughput, though direct sales to major furniture OEMs are gaining share as procurement consolidates.
ECHA REACH restrictions on formaldehyde emissions and the EU Green Deal carbon-accounting framework shape product formulation and mill-level compliance investments across European production. CE marking under the Construction Products Regulation governs structural applications, while F-Gas Regulation indirectly affects binder chemistry alternatives under development. Stakeholders must monitor evolving bio-based resin pilots and embedded-carbon disclosure rules that will determine which substrate grades retain specification status in public procurement and large-scale residential developments.
Market Dynamics
EU Green Deal carbon-accounting mandates and ECHA REACH formaldehyde emission limits are forcing particle board mills to reformulate binders and retrofit emission controls, compressing margins for non-compliant producers while rewarding early adopters of bio-based resin systems.
Growth Catalysts
- EU Green Deal compliance premiums:Public procurement rules across Germany and Poland now favor low-embedded-carbon substrates, pulling volume toward certified producers.
- Melamine-faced panel substitution:Furniture OEMs in Central Europe are eliminating downstream lamination steps by specifying pre-finished grades.
- Poland manufacturing corridor expansion:Raw material proximity to Baltic timber sources reduces inbound logistics costs for integrated mills.
Market Restraints
- Urea-formaldehyde resin cost volatility:Natural gas price swings directly compress binder economics for standard-grade producers.
- Baltic timber supply concentration:Fiber sourcing clusters in Estonia and Latvia create geographic vulnerability to harvest quota restrictions.
- OSB flooring substitution:Oriented strand board is capturing structural subfloor specifications from commodity particle board in residential construction.
Strategic Opportunities
- Romania and Bulgaria underpenetration:Furniture manufacturing growth in these markets offers first-mover positioning for certified substrate suppliers.
- CE marking structural grade expansion:Load-bearing panel specifications in commercial fit-outs open premium pricing tiers beyond furniture applications.
- Direct OEM procurement platforms:Digital tendering systems are collapsing traditional wholesale markups for large-format buyers.
Industry Challenges
- Bio-resin formulation expertise scarcity:Mill chemists with lignin-based and tannin-modified adhesive experience command premium compensation.
- Continuous press retrofit capex cycles:Tier-2 producers face stranded asset risk without capacity to fund emission-control upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Particle Board Market |
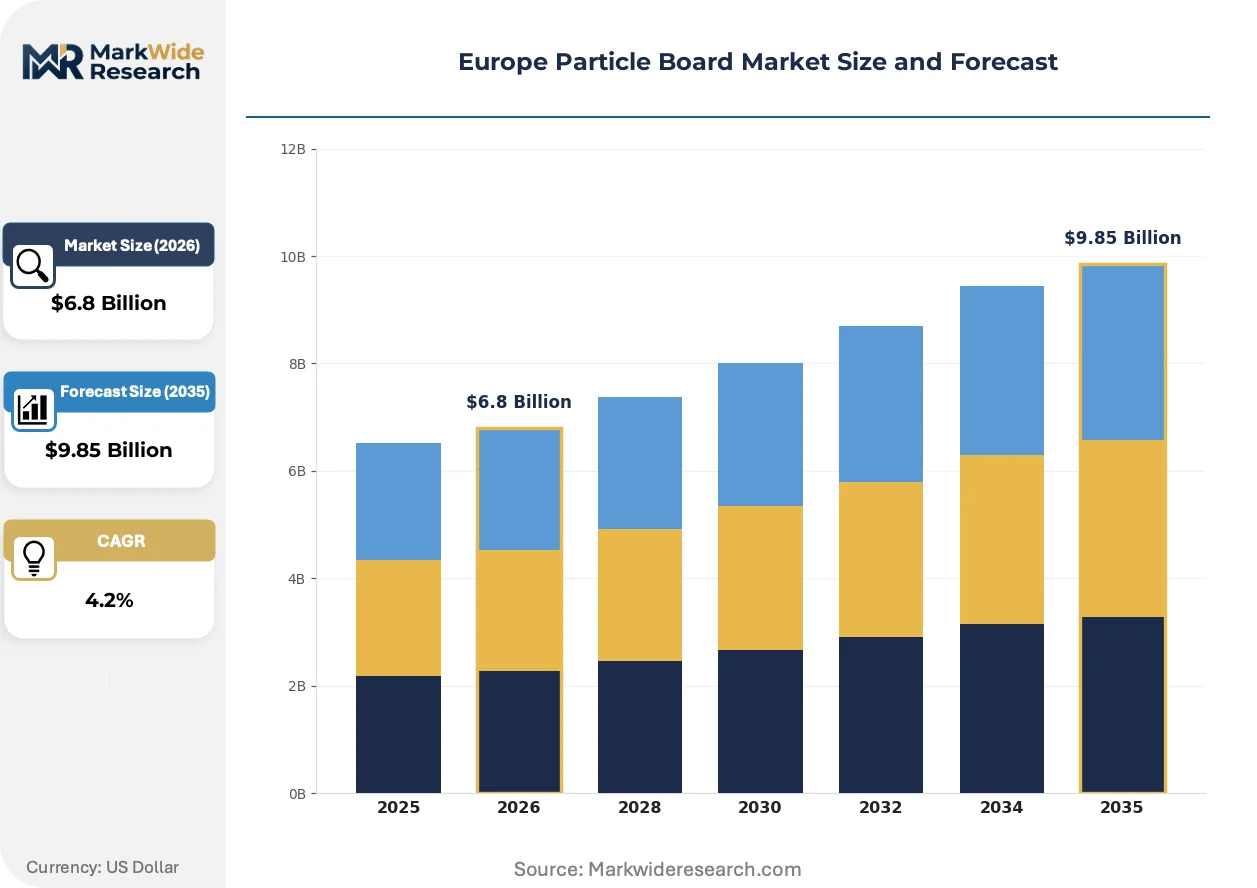
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Particle Board, Melamine Faced Particle Board, Laminated Particle Board, Fire Retardant Particle Board End User: Residential, Commercial Furniture, Construction, Automotive Interiors Application: Flooring, Wall Panels, Furniture Manufacturing, Cabinetry Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | Sonae Arauco, SAUERLAND Spanplatte, EGGER, Peter Benson (Plywood) Limited, Swiss Krono Group, Kronospan, West Fraser Timber, Unilin Division Panels, Kastamonu Entegre, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Particle Board Market Shifts & Advancements
Digital configuration tools and pre-cut furniture bundles are collapsing traditional sheet-good distribution, while binder chemistry pivots toward bio-based alternatives under tightening emission protocols. Three forces are reshaping competitive positioning.
Digital cutting and edgebanding integration is modularizing how particle board enters final assembly. Kitchen and wardrobe manufacturers in Germany now receive dimensionally finished components rather than raw panels, compressing their factory footprint and inventory carrying costs. This shift is modularizing the traditional mill-to-OEM supply relationship into configured-component partnerships.
ECHA REACH formaldehyde emission protocols are tightening test-method tolerances and certification renewal frequencies. Mills must maintain third-party audit trails for resin batch chemistry, raising fixed compliance overhead. The furniture OEM segment bears the highest exposure, as brand retailers demand chain-of-custody documentation that smaller substrate suppliers cannot generate.
Specification behavior is rotating toward embodied-carbon disclosure as a procurement filter. Large residential developers in Poland and the Czech Republic now require Environmental Product Declarations for interior substrates, penalizing high-emission grades regardless of unit price. This preference shift is most visible in multi-family housing projects targeting green building certification.
Europe Particle Board Market Segmentation
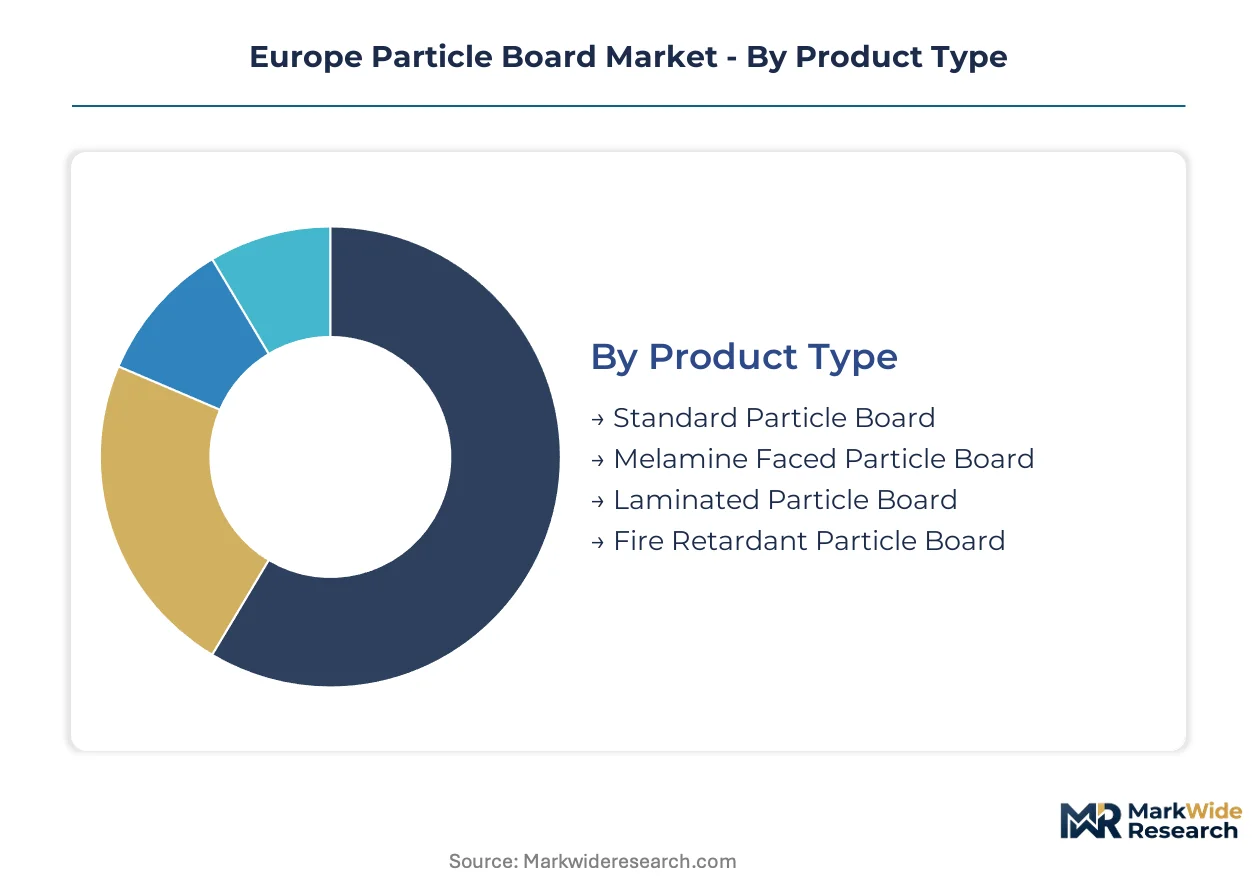
Particle board segmentation in Europe reflects divergent buyer priorities across furniture OEMs, construction contractors, and retail channels. Specification behavior splits between cost-driven commodity procurement and certified-grade premiums for compliance-heavy projects.
Product Type:
Buyers differentiate primarily by surface finish requirements and regulatory certification burdens rather than core substrate density alone.
- Melamine Faced Particle Board:Pre-finished decorative surfaces eliminate downstream lamination steps for furniture manufacturers. Demand concentrates in Germany and Poland where kitchen cabinet OEMs specify direct-from-mill configured components to compress factory footprint and inventory carrying costs.
- Standard Particle Board:Unfinished substrates serve as the volume base for commodity furniture and interior fit-outs where downstream processors control surface treatment. Pricing pressure intensifies as oriented strand board captures structural flooring specifications across residential construction in Central Europe.
- Laminated Particle Board:Post-formed decorative surfaces suit high-wear commercial applications requiring enhanced scratch resistance. Hospitality fit-out contractors in the Czech Republic specify these grades for hotel furniture packages.
- Fire Retardant Particle Board:Additive-treated substrates meet CE marking requirements for load-bearing commercial wall systems. Specification concentrates in public procurement corridors where EU Green Deal carbon-accounting protocols intersect with fire safety mandates.
Volume sits with Standard grades; growth tilts toward Melamine Faced as pre-finished supply chains displace traditional sheet-good distribution.
End User:
Customer procurement scale determines whether supply flows through wholesale intermediaries or direct mill relationships.
- Residential:Multi-family housing developers in Poland and the Czech Republic now require Environmental Product Declarations for interior substrates, penalizing high-emission grades regardless of unit price. This segment absorbs the largest absolute tonnage across Central European manufacturing corridors.
- Commercial Furniture:Large-format retail contracts sustain production scale for integrated mills with continuous press capacity. Swiss and German office furniture manufacturers specify certified chain-of-custody documentation that smaller substrate suppliers cannot generate.
- Construction:Structural load-bearing applications demand CE marking compliance under the Construction Products Regulation. Specification behavior here rotates toward embodied-carbon disclosure as a procurement filter in green building certification projects.
- Automotive Interiors:Lightweight panel applications for vehicle cabins require specialized density control and formaldehyde emission profiles. Tier-1 suppliers source through qualified mill lists audited by German and French OEMs.
Procurement scale concentrates with Commercial Furniture; certification complexity expands fastest in Residential.
Application:
Functional performance requirements dictate resin chemistry selection and density specifications across use cases.
- Furniture Manufacturing:Dimensionally stable substrates support modular cabinetry kits and pre-cut component bundles. German kitchen manufacturers now receive finished parts rather than raw panels, collapsing traditional mill-to-OEM supply relationships into configured-component partnerships.
- Cabinetry:Moisture-resistant grades dominate bathroom and kitchen applications where humidity cycling demands enhanced binder performance. Polish furniture clusters near Baltic timber sources reduce inbound logistics costs for integrated mills serving this segment.
- Wall Panels:Decorative and acoustic-grade specifications serve commercial fit-out contractors. Fire-retardant variants capture premium pricing tiers in public building renovations across Germany.
- Flooring:Structural subfloor applications face substitution pressure from oriented strand board in residential construction. Commodity particle board retains share only in budget-tier renovation projects.
Configured-component supply is reshaping Furniture Manufacturing; Flooring bleeds share to alternative substrates.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and inventory carrying cost tolerance.
- Wholesale:Traditional sheet-good distributors control largest throughput for small-to-mid furniture manufacturers lacking direct mill relationships. Inventory pooling across multiple SKUs justifies markup capture.
- Direct Sales:Major furniture OEMs consolidate procurement through digital tendering platforms that collapse traditional wholesale markups. EGGER and Swiss Krono Group anchor this channel with integrated resin and substrate operations.
- Retail:Big-box home improvement chains serve renovation contractors and DIY segments with pre-cut project bundles. Stocking density favors commodity grades over specialty certifications.
- E-commerce:Configured-component platforms emerge for small-batch custom furniture producers. Digital cutting specifications transmit directly to mill scheduling systems.
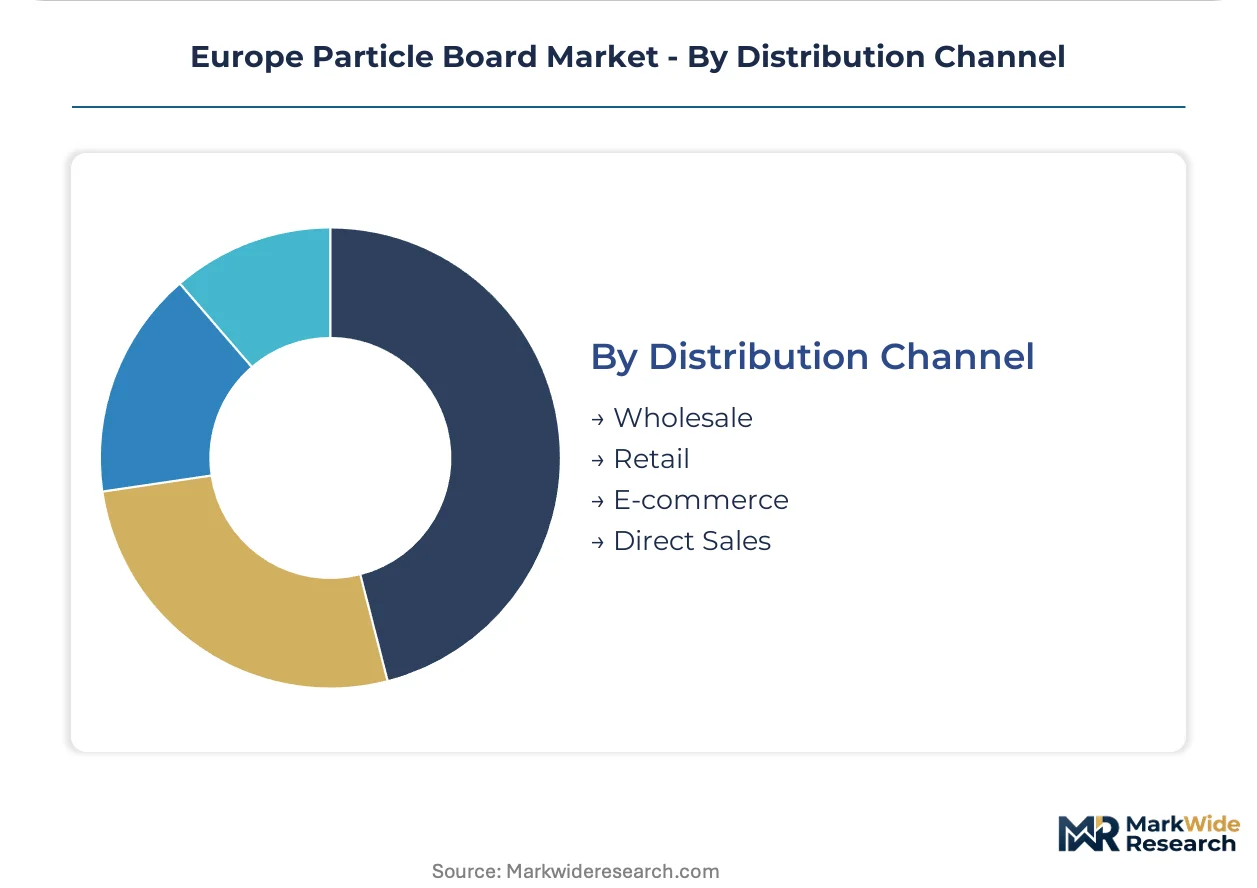
Throughput concentrates in Wholesale; margin capture shifts toward Direct Sales as procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones have concentrated particle board investment near Baltic timber corridors, drawing integrated mills to Pomeranian and Podlaskie voivodeships where raw material proximity compresses logistics costs.
Germany
Kitchen cabinet OEMs in North Rhine-Westphalia and Bavaria specify direct-from-mill configured components, eliminating downstream lamination steps. The EU Green Deal carbon-accounting framework mandates Environmental Product Declarations for public procurement, favoring certified producers. EGGER anchors production scale in Brilon and Wismar, sustaining supply continuity for large-format retail contracts.
Poland
Multi-family housing developers in Warsaw and Kraków now require EPD documentation for interior substrates, penalizing high-emission grades. ECHA REACH formaldehyde protocols tighten test-method tolerances for mills serving furniture clusters. Swiss Krono Group and Kronospan concentrate capacity near Szczecin and Poznań, exploiting fiber sourcing proximity to Baltic timber sources.
Czech Republic
Hospitality fit-out contractors in Prague specify laminated particle board grades for hotel furniture packages demanding enhanced scratch resistance. CE marking under the Construction Products Regulation governs structural panel applications in commercial renovations. Manufacturing corridors near Ostrava and Brno absorb volume from German OEMs seeking cost-competitive configured components.
France
Office furniture manufacturers in Île-de-France and Auvergne-Rhône-Alpes demand certified chain-of-custody documentation that smaller substrate suppliers cannot generate. The F-Gas Regulation indirectly affects binder chemistry alternatives under development. Sonae Arauco positions production near Bordeaux to serve Atlantic-facing distribution channels.
Spain
Renovation contractors in Madrid and Barcelona procure pre-cut project bundles through big-box retail channels favoring commodity grades over specialty certifications. The EU Green Deal compliance premiums pull limited volume toward low-embedded-carbon substrates in public housing projects. Kastamonu Entegre anchors Iberian supply from manufacturing clusters near Valencia.
Europe Particle Board Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's particle board value chain. The vendor base organizes into three tiers: integrated resin-substrate operators commanding direct OEM relationships, regional wholesale-dependent producers, and specialty-grade niche players. Strategic differentiation concentrates on backward integration into resin chemistry, continuous press capacity expansion, and configured-component partnerships that collapse traditional distribution layers.
Within the integrated operator tier, EGGER and Swiss Krono Group exemplify scale-driven positioning through captive supply of synthetic resins and substrate operations across Central European plants. Kronospan occupies a specialist position, representing the archetype of differentiated-grade capacity targeting fire-retardant and moisture-resistant segments. Among regional fabricators, SAUERLAND Spanplatte and Sonae Arauco sit within mid-cap structures serving wholesale channels with standard-grade throughput.
| Leading Market Players |
|---|
| Sonae Arauco |
| SAUERLAND Spanplatte |
| EGGER |
| Peter Benson (Plywood) Limited |
| Swiss Krono Group |
| Kronospan |
| West Fraser Timber |
| Unilin Division Panels |
| Kastamonu Entegre |
| Others |
Supply & Pricing Matrix
The EU Green Deal carbon-accounting framework gates qualified supply and premium-tier pricing access for European particle board mills, forcing non-compliant producers into discount positioning while certified operators capture public procurement premiums across Germany and Poland.
Pricing Analysis
Margin tightening in standard-grade segments reflects urea-formaldehyde resin cost volatility tied to natural gas price swings. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified melamine-faced panels from commodity grades and budget-tier imports. Pricing pressure intensifies in structural flooring as oriented strand board displaces particle board specifications. Residential multi-family developers exhibit highest price sensitivity, while German kitchen cabinet OEMs prioritize certified chain-of-custody documentation over unit cost.
Supply Chain Analysis
Panel returns and edgebanding scrap flows from configured-component partnerships are creating reverse-logistics value pools for specialized recyclers. Raw material sourcing concentrates in Estonia, Latvia, and Poland where Baltic timber corridors feed integrated mills. Binder chemistry rests on synthetic resin supply from petrochemical networks and emerging lignin-based pilot streams. Single-source vulnerability sits with Baltic fiber concentration under harvest quota restrictions. Distribution runs through wholesale intermediaries for small-to-mid furniture manufacturers, though direct mill relationships are consolidating among large-format OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European particle board is becoming a vertical-integration race where captive resin production and configured-component partnerships determine who retains specification access against substitute substrates and import pressure.
For Market Incumbents: Deepen backward integration into bio-based resin chemistry to preempt ECHA REACH formaldehyde emission tightening and capture EU Green Deal compliance premiums. Expand continuous press capacity in Poland's Special Economic Zones to defend against Baltic timber supply concentration risks. Anchor direct OEM procurement platforms that collapse wholesale markups and lock in large-format retail contracts. For New Entrants and Emerging Players: E-commerce configured-component platforms offer the lowest barrier entry path for small-batch custom furniture producers in Romania and Bulgaria. Target hospitality fit-out contractors in the Czech Republic seeking laminated grades with enhanced scratch resistance for hotel furniture packages. Lead with digital tendering systems that transmit cutting specifications directly to mill scheduling, bypassing traditional distribution layers. For Investors and Strategic Acquirers: Bio-resin formulation expertise scarcity is the leading indicator that mills with lignin-based and tannin-modified adhesive capabilities will command acquisition premiums. Long-term viability centers on producers with demonstrated EPD generation capacity and CE marking structural grade expansion. Watch for stranded asset signals among Tier-2 producers unable to fund emission-control retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Resin Chemistry | Captive lignin-based adhesive production insulates against ECHA REACH formaldehyde tightening and natural gas volatility. |
| Continuous Press Capacity Expansion | Poland-based scale additions exploit Baltic timber proximity and serve German OEM configured-component demand. |
| Environmental Product Declaration Certification | EPD documentation unlocks EU Green Deal public procurement premiums across multi-family housing developers. |
| Direct OEM Procurement Platform Development | Digital tendering systems collapse wholesale markups and consolidate supply relationships with large-format furniture manufacturers. |
| CE Marking Structural Grade Investment | Load-bearing panel specifications open premium pricing tiers beyond furniture applications in commercial fit-outs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this European particle board analysis. Primary interviews with mill operations directors, furniture OEM procurement leads, distribution channel partners, and ECHA compliance officers combined with Cefic chemical industry reports, Eurostat construction statistics, and EU Timber Regulation enforcement data. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Data-stream reconciliation across production capacity surveys, resin chemistry cost structures, and end-use demand patterns informed the analytical framework. Segmentation dimensions modeled include product type, end-user industry, application function, and distribution channel across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating Baltic timber supply constraints, ECHA REACH implementation timelines, and EU Green Deal procurement adoption rates.
The model holds under stable regulatory enforcement and continuous Baltic fiber access; deviation in harvest quota restrictions or bio-resin commercialization delays would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Opening Trim Weatherstrips Market