
 Gear Cutting Machines Market | 2026-2036
Gear Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Cutting Machines Market Analytics
Aftermarket service revenue is fragmenting across original equipment builders and third-party refurbishment specialists. Gleason extends its geographic footprint through dedicated service centers in industrial corridors. Mitsubishi Heavy Industries anchors its position via deep integration with shipbuilding and heavy machinery customers. Reishauer specializes in continuous generating grinding technology that commands premium positioning in precision automotive supply chains.
Gear cutting machines are metalworking systems engineered to generate tooth profiles on cylindrical or conical blanks through hobbing, shaping, milling, broaching, or abrasive processes, typically achieving ISO 1328 accuracy grades of 4–7 for automotive and aerospace applications. Their primary purpose is producing precision power transmission components that convert rotational motion with defined speed ratios and torque capacity. CNC Cutting technology leads capital allocation as manufacturers replace mechanical indexing with direct-drive rotary tables and real-time thermal compensation. Hobbing Machines sustain the largest installed base, though Electrical Discharge Machining is gaining share in hardened fine-module gear applications where conventional cutting induces microstructural damage.
ISO standards govern geometric accuracy and surface finish requirements that determine machine specification levels for aerospace and automotive suppliers. EPA fuel-economy regulations and the EU Green Deal's industrial decarbonization targets are redirecting procurement toward energy-efficient machine platforms with regenerative drives and minimum quantity lubrication. China's GB standards and NMPA-equivalent equipment certification create distinct compliance pathways for vendors serving domestic versus export-oriented manufacturers. Stakeholders must monitor how dual carbon mandates in Beijing and Brussels reshape the total cost of ownership calculations for gear production assets.
Market Dynamics
The transition to electric vehicle powertrains is restructuring gear production requirements, as automakers abandon multi-speed transmissions for single-speed reduction units while demanding higher torque density and quieter operation from each component.
Growth Catalysts
- EPA fuel-economy mandates:US automakers must achieve fleet-wide efficiency targets that require precision-machined gears with tighter tolerances, pushing investment into CNC hobbing platforms with in-process measurement capabilities.
- China's dual carbon goals:Beijing's industrial decarbonization targets are redirecting procurement toward energy-efficient machine platforms with regenerative drives and minimum quantity lubrication systems in domestic automotive supply chains.
- Aerospace gear demand:Commercial aviation's recovery and next-generation engine programs are accelerating orders for continuous generating grinding machines capable of ISO 1328 Grade 4 accuracy for turbine power transmission components.
Market Restraints
- Specialized alloy supply concentration:High-speed steel and carbide cutting tool substrates depend on concentrated tungsten and cobalt processing capabilities, creating input cost volatility and geopolitical exposure.
- Technical limitation in hardened fine-module gears:Conventional cutting processes induce microstructural damage in heat-treated components below module 0.5, restricting addressable applications without secondary grinding operations.
- EU machinery certification friction:CE marking requirements under the Machinery Directive impose extended validation timelines for new CNC platforms, delaying commercialization of next-generation control architectures.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for advanced automotive components are attracting greenfield gear production facilities that require complete machine tool ecosystems.
- Wind turbine drivetrain convergence:The merging of planetary and helical gear technologies in multi-megawatt turbine gearboxes creates demand for flexible machining centers capable of both coarse roughing and precision finishing.
- Shipbuilding heavy machinery integration:Marine propulsion systems and deck machinery manufacturers are consolidating supplier relationships, creating captive demand for dedicated large-module gear cutting capacity.
Industry Challenges
- Control systems integration complexity:Retrofitting legacy mechanical indexing machines with direct-drive rotary tables and real-time thermal compensation requires specialized mechatronics expertise that remains scarce in most manufacturing regions.
- ISO 1328 certification timeline compression:Automotive OEMs are demanding documented accuracy validation within weeks rather than months, straining metrology laboratory capacity and third-party verification services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Cutting Machines Market |
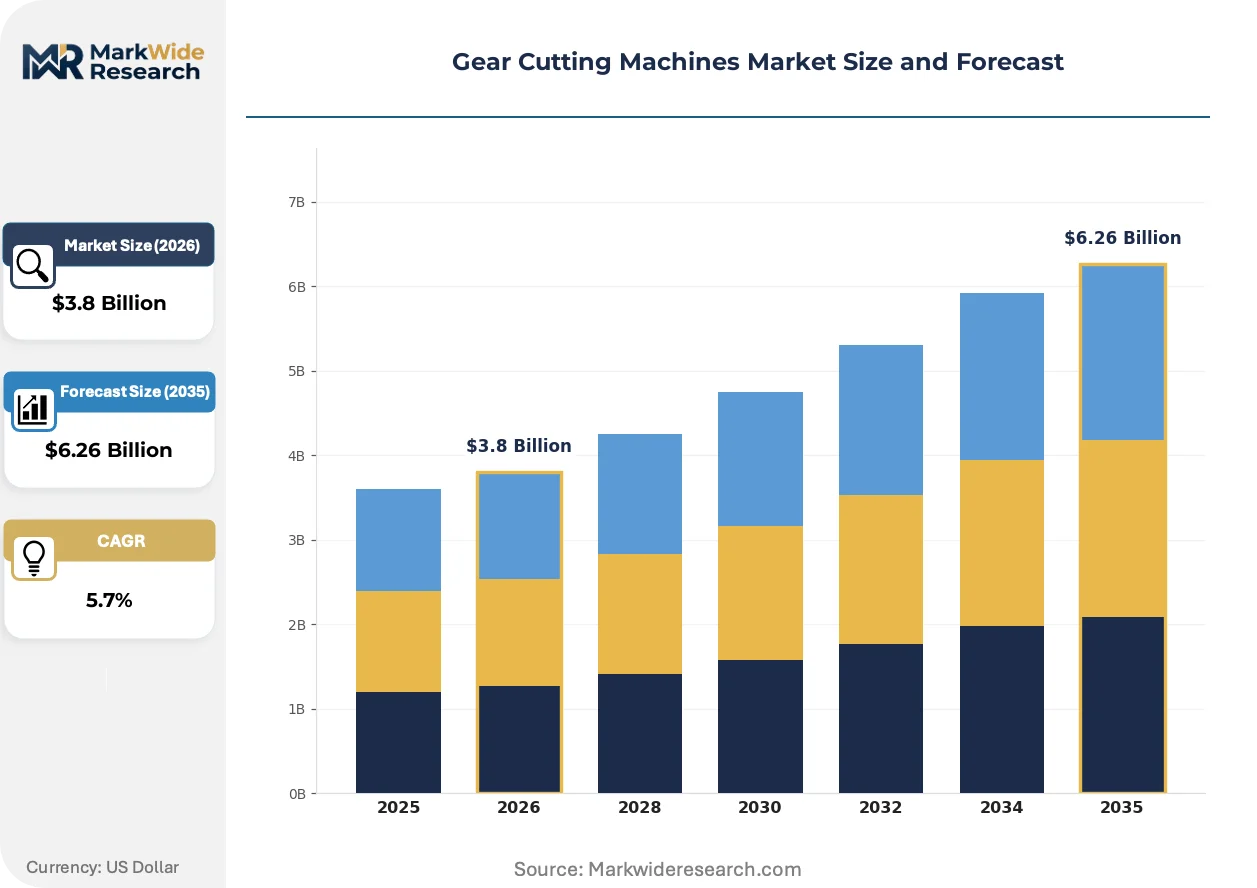
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hobbing Machines, Shaping Machines, Milling Machines, Broaching Machines Technology: Traditional Cutting, CNC Cutting, Electrical Discharge Machining, Laser Cutting End User: Automotive, Aerospace, Marine, Industrial Machinery Application: Precision Gear Manufacturing, Prototype Development, Custom Machining, Mass Production |
| Companies Covered | EMAG Group, Mazak Corporation, Gleason, Reishauer, FFG Werke, Liebherr Group, KLINGELNBERG, Star SU LLC, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Cutting Machines Market Evolving Landscape
Control architecture convergence and process monitoring digitization are redefining competitive differentiation in gear production equipment, moving value capture from mechanical precision to data-enabled productivity guarantees.
Electrical discharge machining is hybridizing with conventional abrasive processes for hardened fine-module gear applications. Medical device and aerospace component manufacturers are adopting these hybrid cells for batch sizes below fifty units. The technology is compressing the traditional process chain by eliminating intermediate heat treatment stress-relief operations.
The EU Green Deal's industrial decarbonization targets are mandating energy consumption disclosures for capital equipment above 50kW rated power. Machine builders must now certify regenerative drive efficiency and lubricant consumption rates to maintain qualification for automotive supplier purchases. German and Italian OEMs are responding with modular platform architectures that isolate energy-intensive subsystems for upgrade.
After-sales service unbundling is fragmenting the traditional bundled maintenance model. Automotive tier-one suppliers are separating predictive maintenance subscriptions from spare parts procurement, creating discrete purchasing decisions for software updates, remote diagnostics, and field service dispatch. This pattern is most visible in the United States, where fleet operators of twenty-plus machines negotiate enterprise-wide service level agreements independent of original equipment purchase contracts.
Gear Cutting Machines Market Segmentation
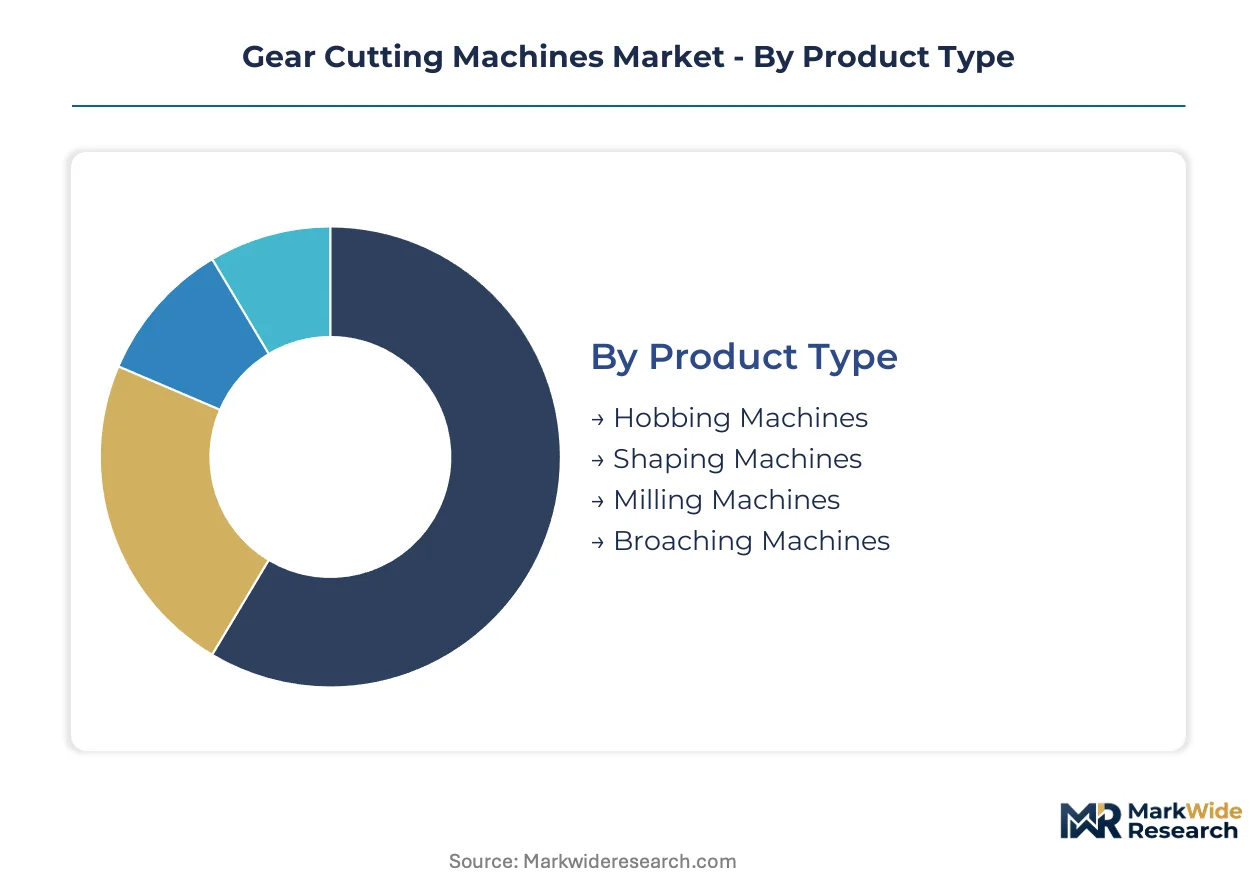
Gear cutting machine procurement patterns diverge sharply across product architectures, control technologies, and end-use precision requirements. Each segmentation axis reveals distinct investment priorities among automotive powertrain engineers, aerospace turbine manufacturers, and industrial machinery builders.
Product Type:
The use-case spectrum spans high-volume automotive transmission lines requiring continuous generating capability through low-volume custom gear shops needing flexible universal platforms.
- Hobbing Machines:These platforms employ rotating hobs to generate external spur and helical gears through continuous generating motion. Demand concentrates in Germany and China where automotive OEMs operate dense clusters of powertrain machining capacity. EPA fuel-economy mandates push these investments toward CNC platforms with in-process measurement.
- Shaping Machines:Reciprocating cutter motion produces internal gears and herringbone configurations inaccessible to hobbing. Aerospace gear demand in the United States favors these systems for turbine power transmission components requiring ISO 1328 Grade 4 accuracy.
- Milling Machines:Multi-axis platforms machine bevel and hypoid gears through face-milling or face-hobbing processes. Wind turbine drivetrain manufacturers specify these for large-module planetary gearboxes.
- Broaching Machines:Linear cutting motion generates splines and internal gear profiles with single-pass efficiency. Heavy machinery manufacturers in Japan deploy these for construction equipment transmission components.
Established volume favors Hobbing Machines; emerging adoption favors Shaping Machines.
Technology:
Capital allocation splits between proven mechanical platforms and digitally native architectures promising thermal stability and real-time compensation.
- CNC Cutting:Direct-drive rotary tables and linear motor axes eliminate mechanical indexing chains. China's dual carbon goals redirect procurement toward these platforms with regenerative drives and minimum quantity lubrication in domestic automotive supply chains.
- Traditional Cutting:Mechanical indexing and cam-driven motion persist in cost-sensitive applications and emerging market installations. India's PLI scheme incentives attract greenfield facilities that balance automation levels against operator skill availability.
- Electrical Discharge Machining:Spark-erosion processing machines hardened fine-module gears below module 0.5 without inducing microstructural damage. Medical device manufacturers in Switzerland adopt these hybrid cells for batch sizes below fifty units.
- Laser Cutting:Directed energy processes prototype gear geometries and cut pre-hardened blanks prior to finishing operations. Aerospace prototyping centers in France experiment with these for rapid iteration of turbine transmission designs.
Installed base concentration favors Traditional Cutting; steepest expansion trajectory belongs to CNC Cutting.
End User:
Customer technical requirements range from automotive torque density optimization through marine large-module durability specifications.
- Automotive:Single-speed EV reduction units demand higher torque density and quieter operation than multi-speed predecessors. OEMs in the United States, Germany, and China dominate order placement for continuous generating grinding capacity.
- Aerospace:Commercial aviation recovery and next-generation engine programs accelerate demand for Grade 4 accuracy capability. FAA certification requirements govern geometric validation protocols for turbine power transmission suppliers.
- Marine:Propulsion systems and deck machinery require large-module gears with decades-long service intervals. Shipbuilders in South Korea and Japan consolidate supplier relationships around dedicated heavy-cutting capacity.
- Industrial Machinery:Construction equipment, mining drivetrains, and general manufacturing span the widest accuracy and module range. Aftermarket refurbishment demand fragments service revenue across third-party specialists in Italy and original equipment builders.
Revenue concentration favors Automotive; margin expansion favors Aerospace.
Application:
Production economics separate high-mix low-volume custom work from dedicated mass production lines with amortized tooling investments.
- Mass Production:Dedicated transfer lines and pallet-based flexible manufacturing systems serve automotive transmission volumes. German and Chinese tier-one suppliers specify platforms with documented OEE guarantees and predictive maintenance integration.
- Precision Gear Manufacturing:ISO 1328 certification requirements compress validation timelines from months to weeks. Metrology laboratory capacity strains under accelerated automotive OEM documentation demands.
- Prototype Development:Rapid geometry iteration and small-batch validation precede production tooling commitment. Laser cutting and EDM hybrid cells serve aerospace and medical device designers in Switzerland and France.
- Custom Machining:One-off and short-run gears for replacement parts and specialized machinery require universal platform flexibility. Indian industrial machinery builders favor locally serviced conventional platforms for this work.
Capital intensity favors Mass Production; technology upgrade frequency favors Prototype Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major manufacturing economies. German and Chinese buyers prioritize CNC platforms with integrated metrology for automotive powertrain validation, while US and Japanese procurement emphasizes aerospace-grade accuracy and marine heavy-module capacity respectively.
United States
EPA fuel-economy mandates drive automaker investment in precision hobbing platforms with in-process measurement. FAA certification requirements govern geometric validation protocols for turbine power transmission suppliers. Aerospace gear demand concentrates in Connecticut and Ohio manufacturing corridors where commercial aviation recovery accelerates orders for continuous generating grinding capacity.
Germany
Automotive OEMs operate dense clusters of powertrain machining capacity demanding ISO 1328 Grade 4 accuracy. CE marking requirements under the Machinery Directive impose extended validation timelines for new CNC platforms. Bavarian and Baden-Württemberg industrial corridors host the densest concentration of machine tool builders serving domestic and export-oriented manufacturers.
China
Dual carbon goals redirect procurement toward energy-efficient platforms with regenerative drives and minimum quantity lubrication. GB standards and NMPA-equivalent equipment certification create distinct compliance pathways for domestic versus export-oriented manufacturers. Yangtze River Delta and Pearl River Delta clusters absorb the bulk of new machine orders as automakers redesign transmission architectures for electric vehicle powertrains.
Japan
Shipbuilding and heavy machinery customers anchor demand for large-module gear cutting capacity with decades-long service intervals. METI industrial policy supports precision manufacturing technology retention in domestic supply chains. Nagoya and Osaka industrial zones concentrate marine propulsion system manufacturers consolidating supplier relationships around dedicated heavy-cutting platforms.
India
PLI scheme incentives for advanced automotive components attract greenfield gear production facilities requiring complete machine tool ecosystems. BIS certification requirements govern equipment qualification for domestic manufacturing investments. Maharashtra and Gujarat industrial corridors emerge as primary destinations for tier-one supplier capacity expansion serving both domestic and export automotive markets.
Gear Cutting Machines Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Premium positioning belongs to specialists in continuous generating grinding and hybrid EDM-abrasive cells, while volume leadership rests with full-line builders offering integrated metrology and predictive maintenance. Strategic archetypes include precision grinding specialists, diversified machine tool conglomerates, and regionally focused service-integrated builders. Dominant competitive moves span geographic expansion through dedicated service centers and vertical integration into cutting tool supply.
Within the precision grinding specialist tier, Reishauer and Gleason exemplify technology leadership anchored in automotive and aerospace supply chain penetration. Among diversified industrial conglomerates, Mitsubishi Heavy Industries occupies a position shaped by deep integration with shipbuilding and heavy machinery end-users. EMAG Group represents the German engineering archetype with modular platform architectures serving high-volume automotive transmission manufacturers.
| Leading Market Players |
|---|
| EMAG Group |
| Mazak Corporation |
| Gleason |
| Reishauer |
| FFG Werke |
| Liebherr Group |
| KLINGELNBERG |
| Star SU LLC |
| Mitsubishi Heavy Industries |
| Others |
Value Network & Pricing Analysis
Tariff exposure between Germany and China for high-speed steel cutting tool substrates determines both pricing tier spreads and supply chain shape in gear cutting machine procurement. OEMs in automotive powertrain manufacturing face compressed margins when tungsten and cobalt processing concentration triggers input cost volatility, forcing tier-one suppliers to renegotiate long-term offtake terms or absorb spot market premiums.
Pricing Analysis
Long-term offtake contracts dominate capital equipment procurement for automotive tier-one suppliers, though spot purchasing persists for refurbishment components and emergency spare parts. Three-tier pricing structure across premium, standard, and economy levels separates continuous generating grinding platforms with ISO 1328 Grade 4 certification from conventional CNC hobbing systems and legacy mechanical indexing machines. Cost compression in the economy tier is intensifying because Indian PLI scheme incentives attract greenfield facilities with aggressive localization requirements. Tier-one automotive suppliers exhibit the highest price sensitivity, while aerospace turbine manufacturers prioritize accuracy certification over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China for control system electronics and linear motor components dominates supply chain risk assessment for CNC platform builders. Manufacturing concentration centers on Germany, Japan, and China for precision gear cutting equipment, with high-speed steel and carbide cutting tool substrates drawing from concentrated tungsten processing capabilities. Single-source vulnerability in direct-drive rotary table supply creates bottlenecks for platforms requiring real-time thermal compensation. Distribution runs through authorized dealer networks for new machine sales, while aftermarket service fragments across third-party refurbishment specialists and original equipment service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gear cutting machine procurement is shifting toward platform-economics dynamics where data-enabled productivity guarantees displace mechanical precision as the primary value capture mechanism. Interoperability between predictive maintenance subscriptions and enterprise-wide service level agreements is restructuring how automotive fleet operators evaluate total cost of ownership.
For Market Incumbents: Build switching-cost moats through captive cutting tool supply and integrated metrology validation services that lock in automotive tier-one suppliers. Backward integration into tungsten carbide substrate processing mitigates input cost volatility from concentrated cobalt supply. Capacity addition in India's Maharashtra and Gujarat industrial corridors captures PLI scheme-driven demand before local competitors establish service footprints. ISO 1328 certification investment compresses validation timelines to match automotive OEM documentation demands. For New Entrants and Emerging Players: Establish a beachhead in electrical discharge machining hybrid cells for medical device and aerospace prototyping applications below fifty-unit batch sizes. White-space targets include hardened fine-module gear applications below module 0.5 where conventional cutting induces microstructural damage. India's emerging gear production facilities present the most penetrable geography given greenfield status and incomplete machine tool ecosystems. Go-to-market leverage rests on flexible leasing models that reduce capital commitment for first-time precision gear manufacturers. For Investors and Strategic Acquirers: Precision grinding specialists with automotive supply chain penetration and documented ISO 1328 Grade 4 capability represent the most defensible acquisition target archetype. Long-term viability hinges on control architecture convergence and software-enabled productivity guarantees rather than mechanical precision differentiation. The signal to watch is unbundling velocity in after-sales service, where separation of predictive maintenance subscriptions from spare parts procurement indicates platform-economics maturation and recurring revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Control Architecture Convergence | Direct-drive rotary tables with real-time thermal compensation displace mechanical indexing in CNC platforms. |
| Backward Integration into Cutting Tools | Captive supply of high-speed steel and carbide substrates reduces exposure to tungsten price volatility. |
| Predictive Maintenance Subscription Unbundling | Automotive fleet operators separate software updates from field service dispatch in enterprise agreements. |
| Hybrid EDM-Abrasive Cell Development | Medical device manufacturers adopt spark-erosion processing for hardened fine-module gears without heat treatment damage. |
| India Greenfield Service Center Expansion | PLI scheme incentives in Maharashtra and Gujarat attract tier-one supplier capacity requiring local support infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive powertrain engineers, aerospace turbine manufacturers, marine propulsion system procurement leads, and aftermarket service heads at third-party refurbishment specialists. Secondary validation drew from customs and trade data for machine tool imports, SEC filings of diversified industrial conglomerates, ISO 1328 certification registry databases, and automotive production statistics from vehicle registration databases. Bottom-up modeling of installed base replacement cycles and top-down triangulation against capital expenditure disclosures from tier-one suppliers ensured cross-verification of demand estimates.
Calibration against historical machine tool order patterns and announced capacity expansions anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, control technology, end-use precision requirements, and application production economics. CAGRs were derived from slope analysis of replacement demand curves and technology displacement trajectories. Industry-specific forecast inputs incorporated EPA fuel-economy mandate compliance timelines and China's dual carbon goals for industrial decarbonization.
Stress conditions across tungsten and cobalt price volatility, CE marking validation timeline extensions, and automotive OEM certification compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EV powertrain gear count reduction and aerospace commercial aviation recovery trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wood Floor Grinding Machine Market
Tools
Edging Tool Market
Tools
Press Machine Market
Tools
Sanding Machine Market
Tools
Concrete Saw Market
Tools
Hydraulic Tools and Equipment Market
Tools
Cordless Multi Rotary Tools Market
Tools
Asia Pacific Power Tools Market
Tools
Orbital Recip Saw Market
Tools
End Mill Holder Market
Tools
Mechanical Hand Tools Market
Tools
Friction Washer Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Screw Fastener Market
Tools
North America Power Tools Market
Tools
Machine Bench Vices Market