
 Point-Of-Care Medical Imaging Market | 2026-2036
Point-Of-Care Medical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Medical Imaging Market Intelligence
Urgent care centers are redrawing procurement priorities away from centralized radiology departments, pulling capital toward compact, bedside-capable systems. GE HealthCare leverages its installed base of portable ultrasound platforms to defend channel relationships with mid-size hospital networks. Siemens Healthineers anchors its position through deep R&D investment in handheld MRI form factors. Philips Healthcare differentiates by integrating AI diagnostic layers directly into wireless imaging hardware, reducing reliance on separate software licensing.
Point-of-care medical imaging encompasses diagnostic modalities engineered for deployment at the patient's location rather than in dedicated radiology suites, typically operating at reduced power footprints, lower magnetic field strengths, or simplified user interfaces compared with conventional equipment. These systems serve the primary commercial purpose of accelerating clinical decision timelines by eliminating patient transport and appointment scheduling bottlenecks. Ultrasound dominates current revenue contribution due to its portability, lower capital threshold, and broad protocol applicability across emergency and primary care settings. AI Diagnostics represents the fastest-expanding technology segment, with algorithm-based image interpretation compressing read times and enabling non-specialist operators to perform scans previously requiring radiologist oversight. Portable Scanners across X-ray and CT categories command premium pricing where emergency departments prioritize trauma triage speed over image resolution granularity.
FDA 510(k) clearance requirements shape hardware design constraints and software validation burdens for US market entrants, while the EU MDR extends conformity assessment timelines and intensifies clinical evidence demands for European commercialization. The country's national pharmaceutical regulator in India, CDSCO, imposes additional import licensing layers that delay product availability for domestic clinic networks. Stakeholders must monitor divergence between FDA's evolving guidance on AI-as-medical-device and EMA's parallel framework development, as regulatory misalignment threatens to fragment product development roadmaps and duplicate validation expenditures.
Market Dynamics
AI-enabled image interpretation is compressing radiologist dependency and redistributing diagnostic authority toward bedside clinicians, fundamentally altering equipment purchasing criteria across emergency and ambulatory networks.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance for algorithm-augmented portable devices reduces validation timelines for US market entrants, encouraging hardware-software integration investments.
- Ambulatory clinic protocol standardization:German outpatient networks are mandating point-of-capability imaging for triage workflows, creating pull-through demand for compact ultrasound and X-ray systems.
- Wireless hardware-software convergence:Direct embedding of diagnostic algorithms into handheld probes eliminates separate licensing friction and accelerates deployment velocity.
Market Restraints
- EU MDR conformity assessment extension:Intensified clinical evidence requirements for European commercialization stretch validation timelines and inflate regulatory expenditure burdens.
- High-purity semiconductor supply concentration:Advanced imaging sensor fabrication depends on concentrated Asian foundry capacity, exposing equipment manufacturers to input availability volatility.
- Resolution-performance tradeoff in portable CT:Reduced power footprints in mobile trauma scanners sacrifice image granularity, limiting applicability in complex diagnostic scenarios.
Strategic Opportunities
- India CDSCO import licensing gaps:Domestic clinic networks face delayed product availability due to layered approval requirements, creating first-mover advantage for local manufacturing partnerships.
- Handheld MRI form factor emergence:Ultra-low-field magnetic systems enable deployment in resource-constrained settings previously excluded from advanced imaging access.
- AI-as-medical-device framework alignment:Divergence between FDA and EMA guidance creates temporary regulatory arbitrage windows for dual-market product architecture.
Industry Challenges
- Non-specialist operator training deficits:Algorithm-assisted scanning requires new competency frameworks for emergency physicians and primary care practitioners unfamiliar with image acquisition protocols.
- Legacy PACS integration friction:Wireless point-of-care systems encounter interoperability barriers with hospital-wide archival infrastructure, complicating enterprise deployment decisions.
- Software update validation cycles:Continuous learning algorithms trigger recurring FDA re-submission requirements, straining post-market surveillance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Medical Imaging Market |
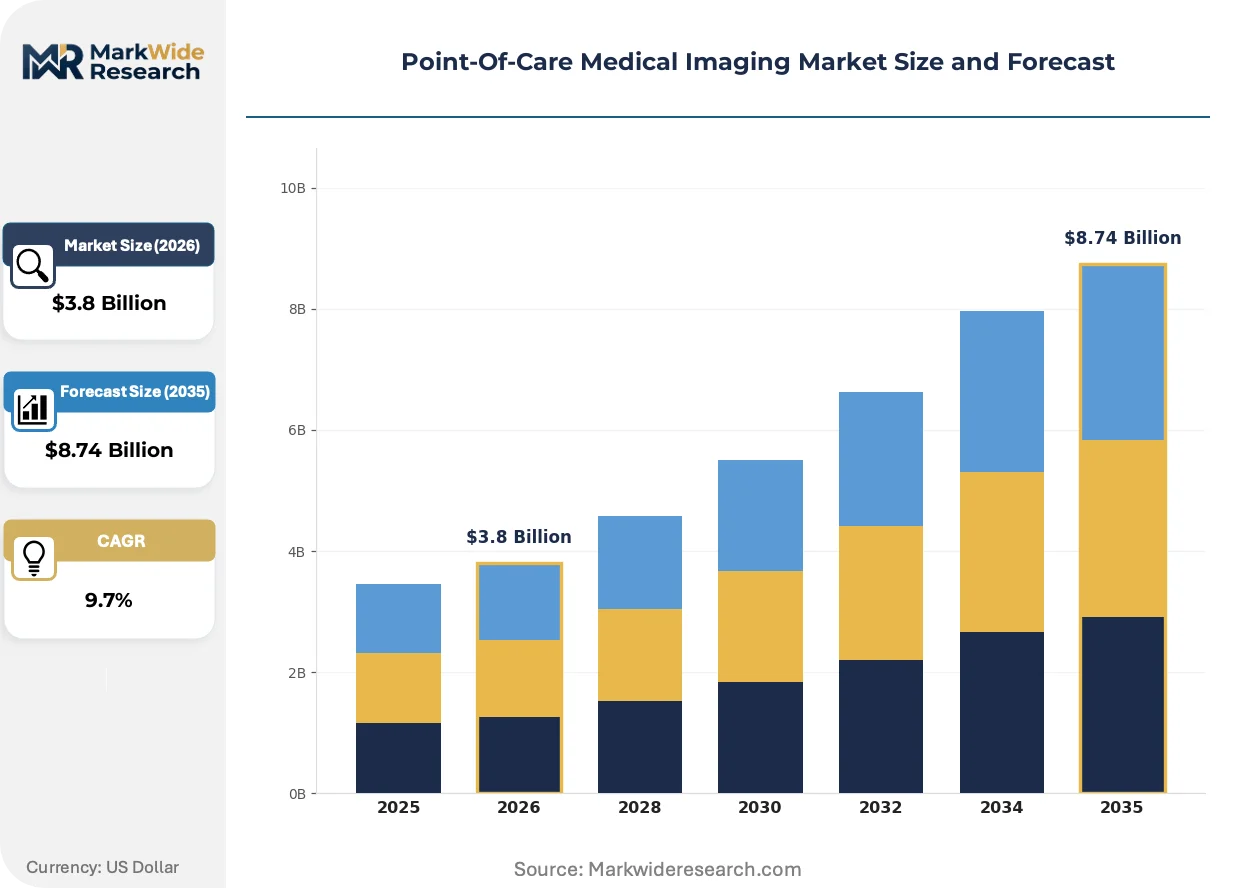
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, X-ray, MRI, CT Scan Application: Emergency Care, Diagnostic Imaging, Primary Care, Chronic Disease Management End User: Clinics, Hospitals, Urgent Care Centers, Home Healthcare Technology: Wireless Imaging, Portable Scanners, Mobile Applications, AI Diagnostics |
| Companies Covered | GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, FUJIFILM Holdings, Samsung NeuroLogica, Xoran Technologies, Carestream Health, Mindray Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Medical Imaging Market Strategic Shifts & Innovations
Edge computing architectures and embedded intelligence are dissolving the traditional separation between image capture and diagnostic interpretation, collapsing workflow steps that previously required distinct equipment and personnel.
Semiconductor miniaturization is decomposing the physical boundaries of conventional imaging suites. Advanced CMOS sensors and specialized ASICs now enable magnetic resonance functionality at fractional field strengths previously considered diagnostically inadequate. Emergency departments in North American hospital systems are piloting these ultra-portable systems for trauma bay deployment. The technology is decomposing capital allocation patterns that historically concentrated imaging investment in centralized radiology departments.
The EU MDR intensifies clinical evidence thresholds for software-enabled devices, extending conformity assessment timelines beyond legacy medical device directive periods. Manufacturers must now generate prospective validation data for algorithm performance across diverse patient populations. European emergency medical services procurement is responding by consolidating vendor relationships toward established players with robust quality management systems.
Hospital capital committees are unbundling imaging procurement from radiology department oversight, shifting budget authority toward emergency medicine and critical care service lines. Traditional equipment financing through centralized health system treasury functions is yielding to departmental leasing arrangements with shorter refresh cycles. This pattern is most pronounced in German and US mid-size hospital networks where service-line profitability metrics drive technology investment decisions.
Point-Of-Care Medical Imaging Market Segmentation
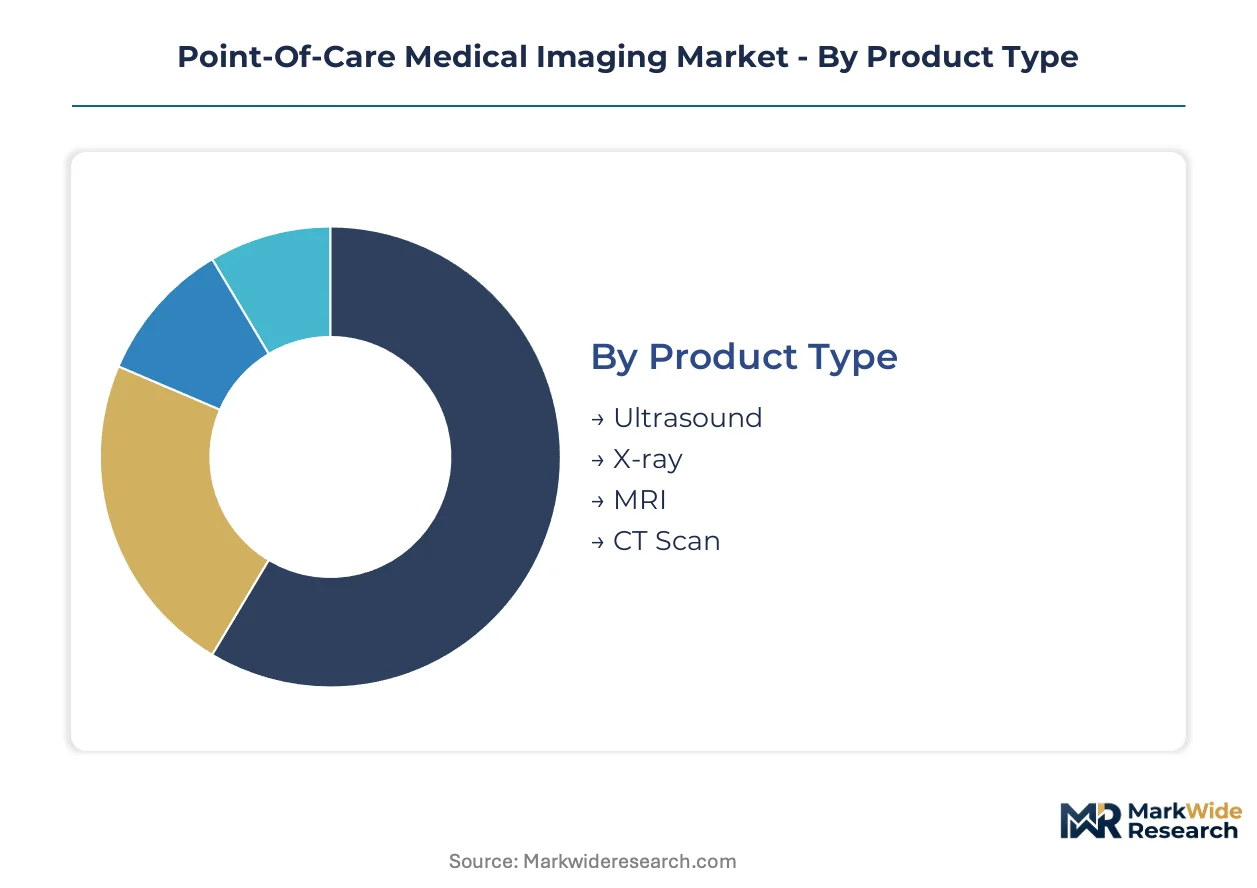
Point-of-care medical imaging segmentation reveals divergent regulatory pathways and capital deployment patterns across hardware modalities and care settings. Each category carries distinct FDA 510(k) validation burdens, EU MDR clinical evidence requirements, and end-user procurement authority structures that reshape competitive positioning.
Product Type:
FDA clearance timelines and EU MDR conformity assessment intensity vary sharply across imaging modalities, with software-enabled systems facing expanded validation protocols under evolving AI-as-medical-device frameworks.
- Ultrasound:Compact transducer arrays and battery-powered consoles dominate current procurement volumes across North American emergency departments and German ambulatory networks. Demand concentrates in bedside trauma triage and primary care screening protocols where transport elimination accelerates clinical decision timelines.
- X-ray:Reduced-power digital radiography systems sacrifice resolution granularity for deployment flexibility in urgent care settings. German outpatient clinic networks standardize these systems for fracture assessment workflows, pulling capital from centralized radiology departments.
- MRI:Ultra-low-field magnetic systems enable deployment in resource-constrained settings previously excluded from advanced imaging access.
- CT Scan:Mobile trauma scanners command premium pricing where emergency departments prioritize triage speed over image resolution.
Established volume favors Ultrasound; emerging adoption favors MRI.
Application:
Procurement authority is migrating from radiology departments toward emergency medicine and primary care service lines, reshaping purchasing criteria across application segments.
- Emergency Care:Trauma bay deployment demands sub-minute image acquisition and wireless transmission to enterprise PACS infrastructure. North American hospital systems accelerate compact system procurement for this application, prioritizing hardware-software integration over standalone device specifications.
- Diagnostic Imaging:Algorithm-assisted interpretation redistributes diagnostic authority toward bedside clinicians, compressing radiologist dependency in time-critical scenarios. FDA 510(k) pathway acceleration for AI-augmented devices reduces validation timelines for this application segment.
- Primary Care:German ambulatory clinic networks mandate point-of-capability imaging for triage workflows, creating standardized demand for compact ultrasound and X-ray systems.
- Chronic Disease Management:Home healthcare settings drive demand for wireless imaging hardware with embedded diagnostic layers.
Service-line budget authority concentrates in Emergency Care; protocol standardization expands fastest in Primary Care.
End User:
Capital allocation patterns diverge across facility types, with departmental leasing arrangements displacing centralized treasury financing in mid-size networks.
- Hospitals:Emergency departments in North American hospital systems anchor procurement volume for compact ultrasound and portable CT systems. Capital committees unbundle imaging procurement from radiology oversight, shifting budget authority toward critical care service lines with shorter refresh cycles.
- Clinics:German ambulatory networks standardize point-of-care imaging protocols, creating pull-through demand for wireless-enabled devices. EU MDR intensified clinical evidence requirements favor established vendors with robust quality management systems in this segment.
- Urgent Care Centers:These facilities redraw procurement priorities away from centralized radiology departments, pulling capital toward bedside-capable systems.
- Home Healthcare:Wireless hardware-software convergence enables deployment in previously excluded settings.
Procurement volume concentrates in Hospitals; deployment velocity accelerates fastest in Home Healthcare.
Technology:
Software validation burdens and hardware design constraints diverge across technology segments, with continuous learning algorithms triggering recurring FDA re-submission requirements.
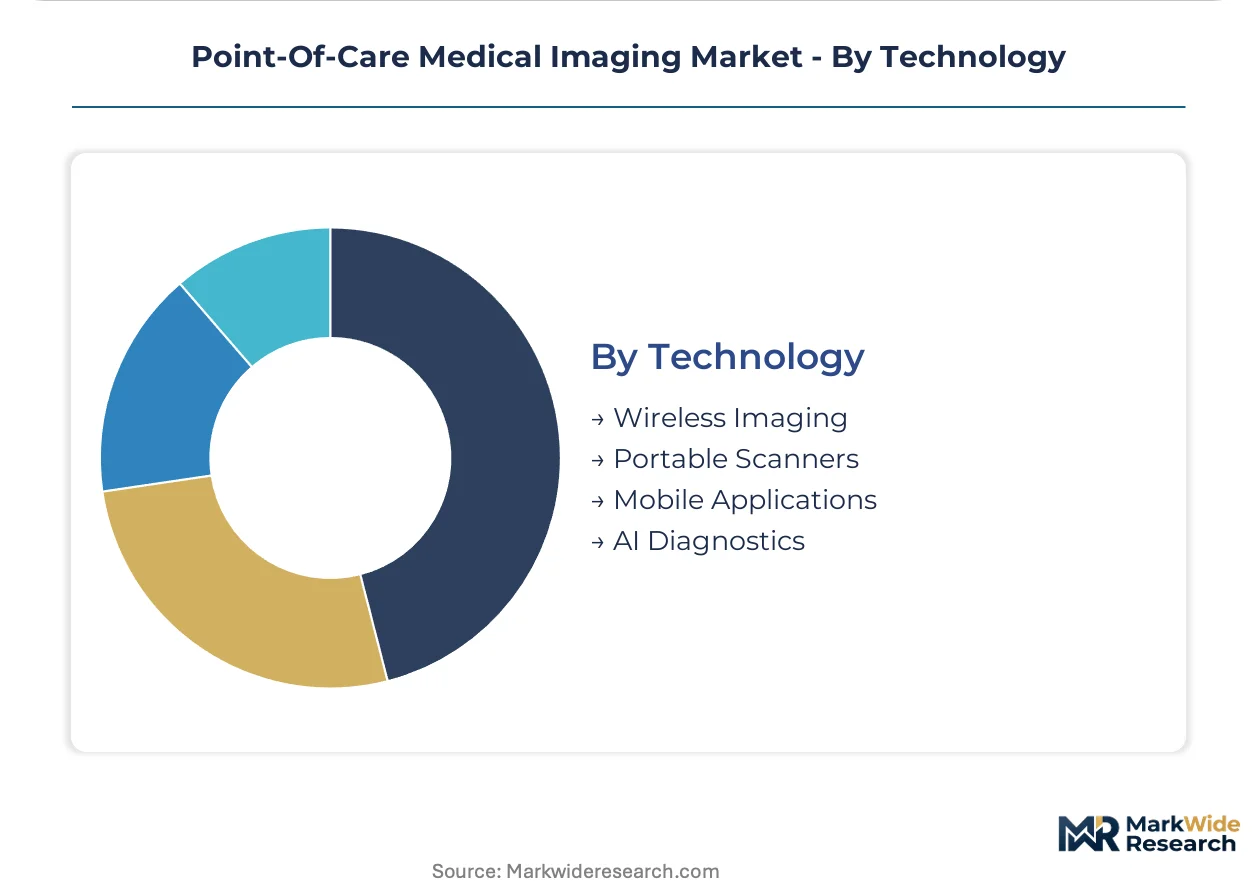
- AI Diagnostics:Algorithm-based image interpretation compresses read times and enables non-specialist operators to perform scans previously requiring radiologist oversight. This segment faces divergence between FDA and EMA guidance frameworks, creating temporary regulatory arbitrage windows for dual-market product architecture.
- Wireless Imaging:Direct embedding of diagnostic algorithms into handheld probes eliminates separate licensing friction and accelerates deployment velocity. EU MDR extends conformity assessment timelines for these software-enabled devices beyond legacy medical device directive periods.
- Portable Scanners:X-ray and CT categories in this technology command premium pricing where emergency departments prioritize trauma triage speed.
- Mobile Applications:These systems encounter legacy PACS integration friction in enterprise deployment scenarios.
Revenue concentration favors Wireless Imaging; capability expansion runs fastest through AI Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for compact imaging hardware, while the transatlantic fiber corridor enables real-time AI diagnostic data flows between German research clusters and US clinical trial networks.
United States
Emergency departments in Texas and Florida hospital systems accelerate procurement of bedside ultrasound systems for trauma bay deployment. FDA 510(k) pathway streamlining reduces validation timelines for algorithm-augmented portable devices. The Boston-Cambridge corridor concentrates venture financing for handheld MRI startups developing ultra-low-field magnetic systems.
Germany
Ambulatory clinic networks in North Rhine-Westphalia mandate point-of-care imaging protocols for standardized triage workflows. EU MDR intensifies clinical evidence requirements, extending conformity assessment timelines beyond legacy medical device directive periods. The Munich medical technology cluster anchors R&D investment for wireless-enabled diagnostic hardware.
India
Domestic clinic networks in Maharashtra and Karnataka face delayed product availability due to CDSCO import licensing layers. The country's national pharmaceutical regulator imposes additional approval requirements that stretch commercialization timelines. Hyderabad's life sciences corridor attracts manufacturing partnerships seeking to bypass import barriers through local production.
Japan
Metropolitan hospital systems in Tokyo and Osaka prioritize compact CT systems for emergency trauma triage. PMDA regulatory frameworks shape hardware design constraints for AI-enabled diagnostic software. The Kansai medical device manufacturing belt concentrates precision sensor fabrication for portable imaging probes.
China
Provincial hospital networks in Guangdong and Jiangsu standardize point-of-care ultrasound for primary care screening expansion. NMPA clearance pathways for software-enabled devices compress domestic market entry timelines. The Yangtze River Delta manufacturing corridor dominates CMOS sensor fabrication for handheld diagnostic hardware.
Point-Of-Care Medical Imaging Market Key Industry Players
Listed leaders compete with private specialists across capital access and R&D velocity dimensions, producing a tiered structure where scale advantages concentrate in diversified health technology conglomerates. The vendor base spans three strategic archetypes: integrated imaging platform providers, component specialists focused on transducer or sensor miniaturization, and AI software layer developers seeking hardware embedding partnerships. Dominant competitive moves include strategic partnerships between semiconductor fabricators and device OEMs, plus geographic expansion through local manufacturing partnerships to bypass import licensing barriers.
Among diversified health technology conglomerates, GE HealthCare, Siemens Healthineers, and Philips Healthcare occupy positions spanning the full hardware-software stack. GE HealthCare exemplifies the installed-base defense archetype through channel relationships with mid-size hospital networks. Siemens Healthineers anchors the deep R&D investment tier with focus on novel form factor development. Philips Healthcare represents the wireless convergence archetype through direct algorithm embedding into handheld hardware.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| FUJIFILM Holdings |
| Samsung NeuroLogica |
| Xoran Technologies |
| Carestream Health |
| Mindray Medical |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance tiers gate both supplier qualification and price differentiation simultaneously, compressing validation timelines for algorithm-augmented devices while segmenting hardware-software bundles across premium, standard, and economy certification grades. German ambulatory clinic networks and North American emergency departments face divergent procurement economics based on whether systems carry full diagnostic AI embedding or modular software licensing.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for compact ultrasound and portable CT systems, with three-tier pricing stratification across FDA-cleared premium bundles, CE-marked standard configurations, and economy-grade hardware without embedded diagnostics. Price differentiation hinges on algorithm validation depth and wireless PACS integration completeness. Cost compression in economy tiers intensifies as Asian OEMs expand foundry-direct distribution. Hospital service lines demonstrate highest price sensitivity; trauma bay deployments show lowest sensitivity due to triage-speed prioritization.
Supply Chain Analysis
Just-in-time inventory strategies prevail for CMOS sensor and ASIC components, though strategic stockpiling of high-purity semiconductor substrates is emerging among tier-one device OEMs. Advanced imaging sensor fabrication draws from concentrated foundry capacity in Taiwan, South Korea, and China. Raw material dependencies span rare-earth magnets for ultra-low-field MRI, specialized epoxy resins for transducer arrays, and high-grade silicon wafers. Single-source vulnerability in CMOS fabrication exposes equipment manufacturers to input availability volatility. Distribution runs through regional medical device distributors with GPO contract access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care medical imaging represents high-growth disruption as FDA 510(k) pathway acceleration for AI-enabled portable devices collapses validation timelines and redraws competitive entry barriers.
For Market Incumbents: Fortify channel control through embedded algorithm partnerships with mid-size hospital networks facing legacy PACS integration friction. Deepen backward integration into CMOS sensor supply through captive foundry agreements or strategic offtakes with Taiwanese fabricators. Priority lever rests on defending installed-base relationships against handheld MRI entrants. For New Entrants and Emerging Players: Differentiate on wireless hardware-software convergence for German ambulatory clinic networks standardizing point-of-care triage protocols. White-space targets include India CDSCO licensing gaps through local manufacturing partnerships and home healthcare settings previously excluded from advanced imaging access. Go-to-market angle emphasizes direct algorithm embedding eliminating separate software licensing friction. For Investors and Strategic Acquirers: FDA AI-as-medical-device framework alignment with EMA guidance reshapes the acquisition landscape, creating temporary regulatory arbitrage windows for dual-market product architecture. Long-term viability centers on platforms spanning hardware miniaturization and continuous learning algorithm validation. Target acquisition archetype: semiconductor-integrated device specialists with robust quality management systems. Signal to watch: divergence between FDA and EMA software validation requirements crossing harmonization thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses time-to-market for algorithm-augmented portable ultrasound systems in emergency departments. |
| EU MDR Conformity Pathway Investment | Extends market access for wireless-enabled devices across German ambulatory clinic networks. |
| Hospital System Partnership Expansion | Secures procurement authority migration from radiology departments toward critical care service lines. |
| Software Companion Development | Enables non-specialist operator deployment through embedded AI diagnostic layers in handheld probes. |
| Reimbursement Strategy Formulation | Aligns point-of-care imaging protocols with CMS and German statutory health insurance coding frameworks. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and emergency medicine clinicians; and secondary validation through FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and CMS reimbursement coding updates. Bottom-up equipment shipment modeling triangulated against top-down health system capital expenditure surveys.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, application, end user, technology, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, ambulatory clinic protocol adoption curves, and AI diagnostic software penetration rates. Industry-specific forecast inputs incorporated semiconductor foundry capacity utilization and CDSCO import licensing timeline patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA pathway streamlining or EU MDR harmonization progress would require recalibration. Forecasts reflect assumptions regarding wireless PACS interoperability resolution and non-specialist training framework deployment. Revision becomes warranted when high-purity semiconductor supply concentration crosses critical disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
United States Mammography Market
Medical Imaging
Teleradiology Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Optical Coherence Tomography Market