
 Magnetic Resonance Imaging (MRI) Equipment Market | 2026-2036
Magnetic Resonance Imaging (MRI) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Resonance Imaging (MRI) Equipment Market Analysis
The gap between superconducting and permanent magnet MRI architectures is narrowing as hybrid designs gain engineering traction. Siemens Healthineers leverages its superconducting coil expertise to sustain leadership in high-field installations across European university hospitals. GE Healthcare anchors its position through backward integration into helium recycling systems that reduce operating costs for customers. United Imaging competes aggressively on portable MRI platforms that serve diagnostic centers with limited capital budgets.
Magnetic Resonance Imaging equipment generates anatomical and functional images by manipulating hydrogen nuclei within strong magnetic fields, typically operating at 1.5 to 3.0 Tesla for clinical diagnostics and up to 7.0 Tesla for neuroscientific research. The technology serves primarily to detect soft-tissue pathologies including brain tumors, spinal disorders, and joint injuries without ionizing radiation. Closed MRI systems dominate installed base value due to superior signal-to-noise ratios, though open MRI configurations occupy a defensible niche in bariatric and pediatric applications where patient anxiety limits throughput. Superconducting technology leads revenue contribution given its established performance ceiling, while portable installation formats represent the fastest-growing demand pool as rural clinics seek to avoid patient transport costs.
FDA 510(k) premarket notification requirements shape product development timelines for manufacturers targeting the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for CE-marked systems sold across Europe. Japan's PMDA enforces unique electromagnetic compatibility testing that adds certification layers for vendors entering that market. Stakeholders must monitor helium supply chain constraints and regulatory convergence around AI-assisted diagnostic software as these forces determine competitive viability.
Market Dynamics
Helium supply chain compression is forcing superconducting MRI manufacturers toward closed-loop cryogenic architectures and alternative magnet technologies, fundamentally restructuring capital deployment patterns across hospital procurement cycles.
Growth Catalysts
- AI-Enhanced Diagnostic Protocols:FDA 510(k) clearance pathways for machine learning-integrated reconstruction software accelerate clinical validation timelines for new imaging sequences in oncology workflows.
- Rural Diagnostic Infrastructure:Portable MRI platforms address transport cost burdens for spinal and neuroimaging cases in underserved counties across the United States and provincial China.
- Helium Recycling Mandates:EU F-Gas Regulation phase-down schedules for fluorinated gases indirectly tighten helium stewardship requirements, rewarding vendors with captive liquefaction recovery systems.
Market Restraints
- Superconducting Magnet Input Concentration:Niobium-titanium wire supply concentrates among three Japanese and European metallurgical suppliers, exposing coil manufacturers to rare earth price volatility.
- Site Preparation Cost Escalation:Quench pipe infrastructure and magnetic fringe field shielding for 3.0 Tesla installations consume 15-25% of total project budgets in retrofit hospital environments.
- Substitution by Advanced CT:Photon-counting computed tomography systems from Siemens and GE displace low-field MRI for certain musculoskeletal indications where bone detail predominates.
Strategic Opportunities
- Underpenetrated Tertiary China:County-level hospitals in Henan and Sichuan provinces lack 1.5 Tesla density, creating whitespace for domestic portable platform vendors with localized service networks.
- Neurodegenerative Research Convergence:7.0 Tesla ultrahigh-field systems combined with multinuclear spectroscopy enable amyloid and tau quantification protocols for Alzheimer's drug trial endpoints.
- Subscription Service Models:Equipment-as-a-service arrangements with per-scan pricing reduce capital barriers for independent diagnostic centers in Germany's ambulatory imaging sector.
Industry Challenges
- Clinical Engineering Talent Scarcity:Cryogenic technician certification programs fail to match installation growth, extending mean time to repair for helium loss events.
- Legacy PACS Integration Friction:AI reconstruction outputs require DICOM standard updates that conflict with decade-old hospital archive systems, forcing middleware expenditures.
- Electromagnetic Compatibility Certification:Japan's PMDA imposes unique RF emission testing protocols that add six to nine months to product registration timelines for foreign entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Resonance Imaging (MRI) Equipment Market |
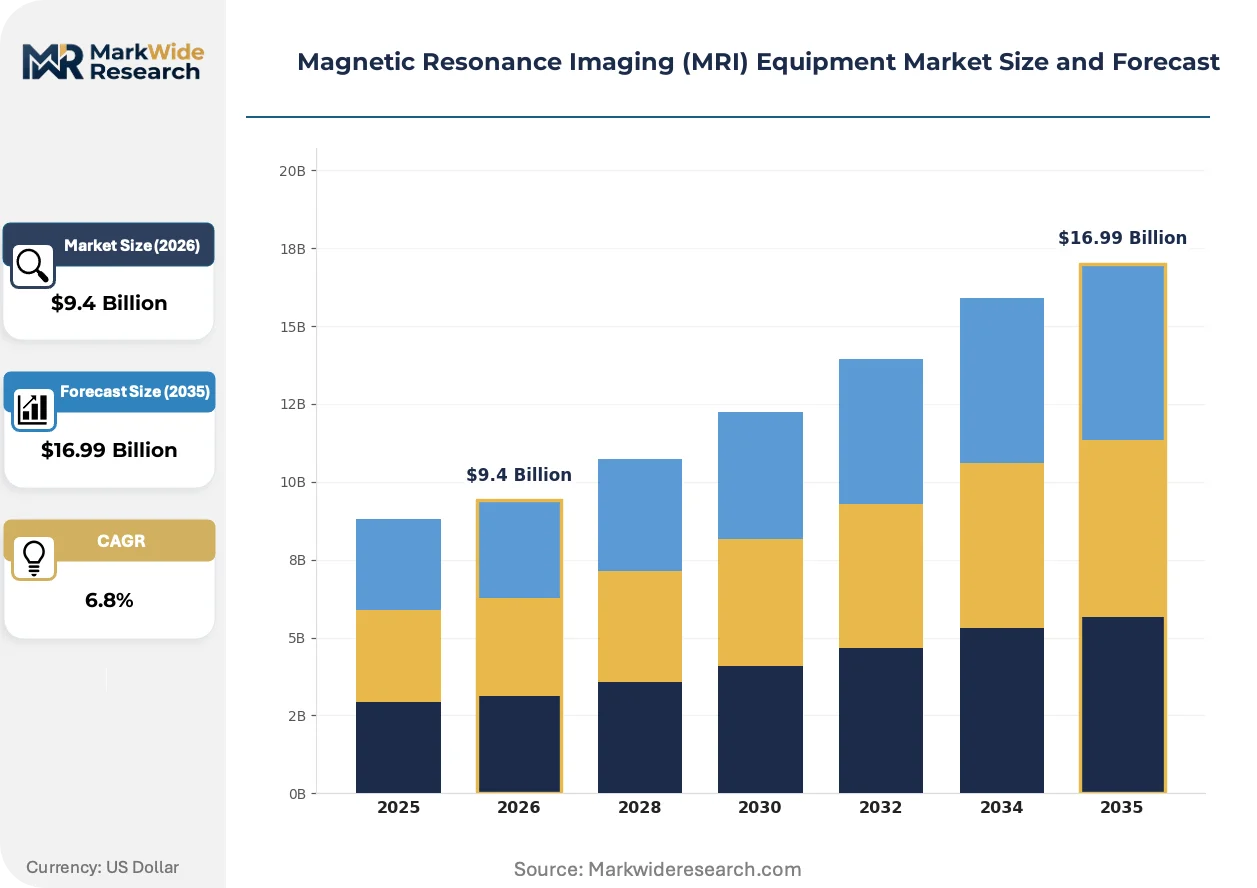
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI Technology: Superconducting, Permanent Magnet, Hybrid, High-Field End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Installation: On-site, Portable, Mobile, Fixed |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, FUJIFILM Holdings Corporation, Canon Medical Systems, ESAOTE, United Imaging Healthcare, FONAR Corporation, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Resonance Imaging (MRI) Equipment Market Emerging Trajectories
Convergence between hardware miniaturization and software-defined reconstruction is collapsing traditional boundaries between hospital-based and point-of-care imaging modalities, compressing the addressable market for conventional fixed-site systems.
Permanent magnet architectures utilizing rare-earth arrays are collapsing the installed footprint and cooling infrastructure requirements for sub-1.0 Tesla diagnostic systems. Community health centers in Brazil and India deploy these platforms for extremity and pediatric neuroimaging where helium logistics prove prohibitive. The structural consequence is collapsing price floors for entry-level MRI, pressuring superconducting vendors to defend high-field positions through software differentiation rather than hardware performance alone.
The EU Medical Device Regulation (MDR) clinical evidence requirements for Class IIb imaging systems tighten post-market surveillance obligations for software-as-medical-device components. Manufacturers must maintain updated clinical evaluation reports across AI algorithm versions, increasing regulatory affairs headcount by 30-40% for European market access. High-field system vendors with established notified body relationships absorb these costs more readily than portable platform entrants, consolidating CE-marking capability among incumbent players.
Hospital purchasing committees now unbundle service contracts from equipment acquisition, negotiating preventive maintenance and software updates through third-party clinical engineering firms. German university hospitals pioneered this disintermediation, pressuring OEM margins on multi-year service attach rates. The behavioral shift is most visible in North American integrated delivery networks, where centralized procurement functions extract 15-20% service contract discounts through competitive rebidding at renewal intervals.
Magnetic Resonance Imaging (MRI) Equipment Market Segmentation
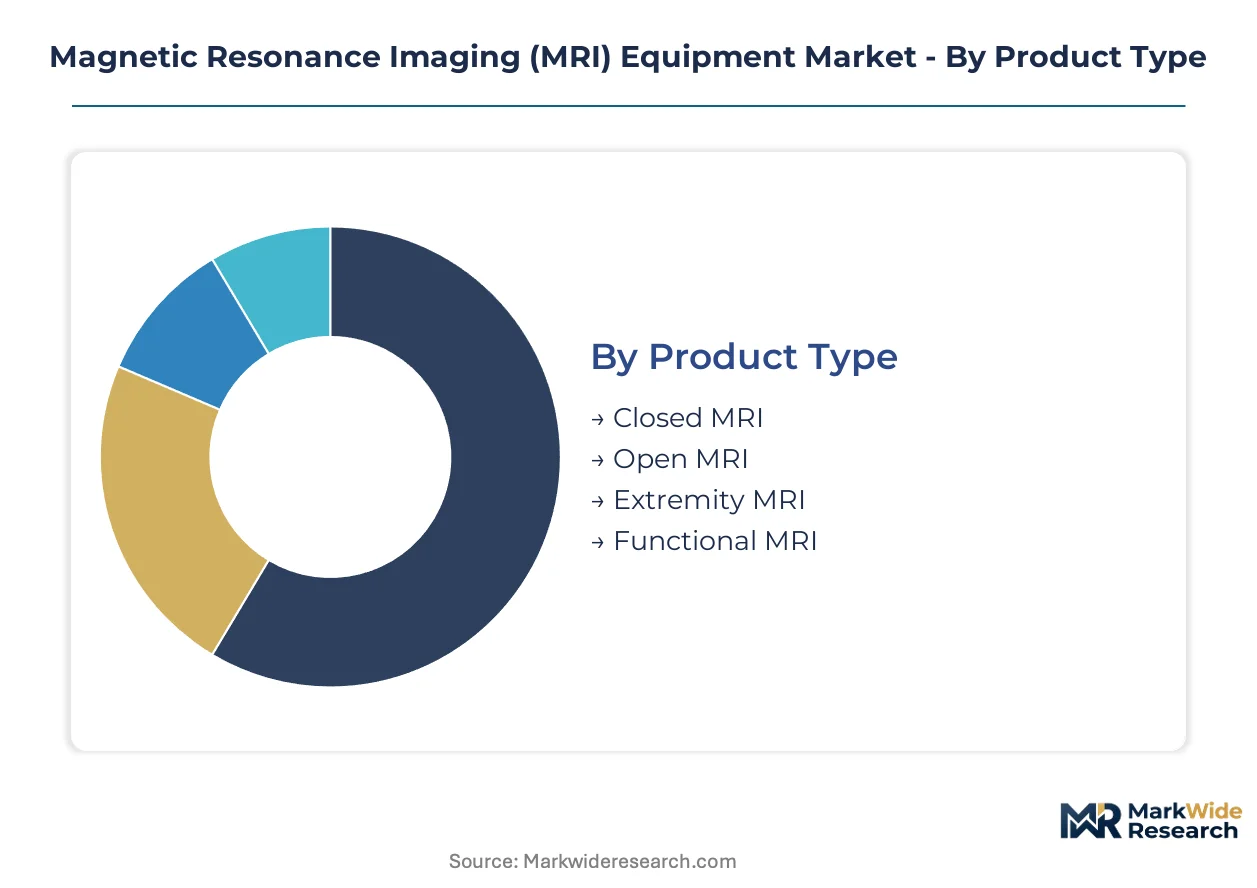
MRI equipment segmentation reveals how clinical requirements, infrastructure constraints, and capital availability fragment procurement patterns across healthcare systems. Understanding these divides illuminates where vendors must tailor specifications versus where scale economies dominate.
Product Type:
Mature closed-bore architectures dominate revenue concentration while emerging configurations address access barriers and patient throughput limitations.
- Closed MRI:Cylindrical superconducting bore designs generate superior signal-to-noise ratios through homogeneous field containment. Tertiary hospitals in Germany and the United States prioritize 3.0 Tesla closed systems for neuro-oncology workflows despite claustrophosis-related throughput losses.
- Open MRI:Vertical or horizontal C-arm magnet geometries eliminate enclosed tunnel constraints. Pediatric departments and bariatric centers in underserved U.S. counties absorb higher per-scan costs to avoid sedation requirements and patient transport delays.
- Extremity MRI:Dedicated limb-only scanners deploy permanent magnet arrays for ankle, wrist, and knee imaging. Sports medicine clinics in Texas and Florida favor these platforms for same-day diagnostic confirmation.
- Functional MRI:Blood-oxygen-level-dependent sequence capabilities enable real-time brain mapping during cognitive tasks. Research consortia in California and Massachusetts deploy these systems for pre-surgical eloquent cortex localization.
Closed MRI retains volume leadership; Open MRI holds the steepest expansion curve.
Technology:
Cost tier stratification separates helium-dependent superconducting platforms from capital-light permanent magnet alternatives.
- Superconducting:Niobium-titanium coils operating at 4 Kelvin deliver field strengths from 1.5 to 7.0 Tesla. University hospitals in China and the United States anchor procurement volume despite quench risks and cryogenic maintenance burdens.
- Permanent Magnet:Rare-earth alloy arrays eliminate helium dependency while capping field strength below 1.0 Tesla. Diagnostic centers in India and Brazil deploy these systems where supply chain fragility threatens superconducting uptime.
- Hybrid:Combined superconducting and permanent magnet architectures optimize field homogeneity against capital cost. European vendors pilot these designs for mid-field clinical research applications.
- High-Field:Systems exceeding 3.0 Tesla enable sub-millimeter resolution for spectroscopic and microstructural analysis. Neurodegenerative research centers in Germany and Japan absorb premium pricing for amyloid quantification protocols.
Superconducting technology commands revenue concentration; Portable-enabled Permanent Magnet platforms are climbing the fastest.
End User:
Customer type determines service contract structures, software integration requirements, and regulatory documentation intensity.
- Hospitals:Integrated delivery networks negotiate enterprise-wide fleet standardization with 10-year total cost of ownership modeling. U.S. health systems increasingly unbundle service contracts from capital purchases.
- Diagnostic Centers:Independent imaging facilities prioritize throughput-per-square-meter and rapid patient turnaround. German ambulatory centers drive subscription-based equipment-as-a-service adoption.
- Research Institutions:Academic medical centers demand multinuclear spectroscopy capability and open software architectures. NIH-funded consortia specify 7.0 Tesla platforms for longitudinal neuroimaging studies.
- Clinics:Single-specialty practices favor extremity-dedicated or portable systems with minimal site preparation. Community health centers in rural China deploy these for spinal screening without patient transport.
Hospitals retain procurement volume leadership; Clinics represent the steepest volume expansion trajectory.
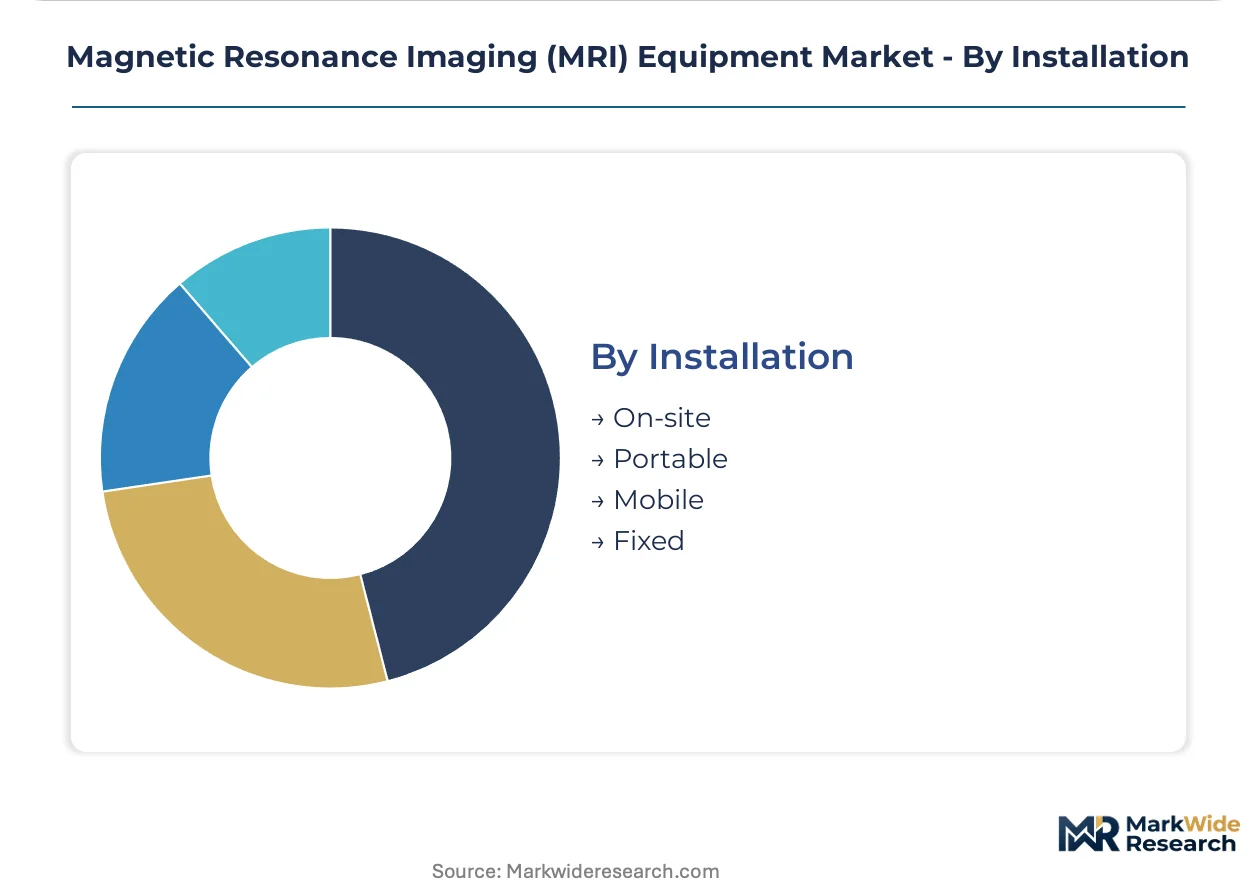
Installation:
Geography shapes infrastructure requirements, with rural access gaps driving format innovation beyond traditional fixed-site models.
- On-site:Permanent magnet or low-field superconducting systems installed within dedicated radiology suites. County hospitals in Henan province deploy these to eliminate referral delays for stroke protocols.
- Portable:Battery-powered or plug-in systems below 1.0 Tesla deployable across multiple clinical settings. U.S. emergency departments pilot these for rapid traumatic brain injury assessment.
- Mobile:Truck-mounted or trailer-based high-field systems rotating across rural service areas. Diagnostic service operators in the American Midwest schedule these for weekly visits to critical access hospitals.
- Fixed:Conventional 1.5 to 3.0 Tesla installations with dedicated RF shielding and quench protection. Tertiary centers in Shanghai and Munich standardize on these for complex cardiac and abdominal imaging.
Fixed installations retain value concentration; Portable formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German superconducting coil exports supply high-field installations across United States university hospitals and Chinese tertiary centers, establishing a transatlantic-Asia trade corridor that shapes procurement patterns in all three markets.
United States
Oncology departments at Cleveland Clinic and Mayo Clinic accelerate 3.0 Tesla scanner procurement for precision radiotherapy planning. FDA 510(k) clearance pathways compress software validation timelines for AI-enhanced reconstruction protocols. The Texas Medical Center cluster anchors demand for portable platforms serving rural stroke networks across the Gulf Coast.
Germany
University hospitals in Munich and Heidelberg drive 7.0 Tesla ultrahigh-field adoption for neurodegenerative research endpoints. EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for CE-marked systems, extending notified body review cycles. The Baden-Württemberg industrial corridor concentrates superconducting magnet engineering talent and cryogenic system suppliers.
China
County-level hospitals in Henan and Sichuan provinces lack 1.5 Tesla density, creating whitespace for domestic portable platform vendors. NMPA regulatory harmonization with international standards accelerates local manufacturer market entry. The Yangtze River Delta cluster around Shanghai hosts assembly operations for both multinational and indigenous equipment producers.
Japan
Neuroscience research institutes in Kanto and Kansai regions absorb premium pricing for multinuclear spectroscopy capability. PMDA enforces unique electromagnetic compatibility testing protocols that add six to nine months to foreign vendor registration timelines. The Tokyo-Osaka corridor maintains installed base leadership in Asia-Pacific for 3.0 Tesla clinical systems.
India
Diagnostic centers in Maharashtra and Karnataka deploy permanent magnet systems where helium logistics threaten superconducting uptime. CDSCO medical device rules tighten post-market surveillance for imported imaging equipment. The Delhi-Mumbai industrial corridor attracts service contract providers targeting independent imaging facilities with subscription pricing models.
Magnetic Resonance Imaging (MRI) Equipment Market Vendor Landscape
On the supply side, the industry is consolidating around superconducting expertise and captive helium stewardship capabilities. Three strategic archetypes dominate: diversified health technology conglomerates with full imaging portfolios, specialized diagnostic imaging pure-plays, and emerging portable platform challengers. Competitive moves center on backward integration into cryogenic supply chains and AI software acquisition to differentiate hardware commoditization.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the integrated-systems archetype through their established superconducting coil expertise and service infrastructure scale. United Imaging Healthcare occupies a position as the portable-platform challenger, representing the capital-light alternative for budget-constrained diagnostic centers. These three anchors illustrate how vendor strategy fragments across high-field performance defense versus accessibility-driven format innovation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| FUJIFILM Holdings Corporation |
| Canon Medical Systems |
| ESAOTE |
| United Imaging Healthcare |
| FONAR Corporation |
| Bruker Corporation |
| Others |
Supply Flow & Price Mechanics
The Baden-Württemberg industrial corridor anchors superconducting coil production capacity for European and Asian OEMs, concentrating upstream pricing power among cryogenic engineering specialists who dictate terms to scanner assemblers in China and the United States.
Pricing Analysis
The 1.5-to-3.0 Tesla versus sub-1.0 Tesla versus 7.0 Tesla pricing gap separates hospital procurement tiers. Three-tier pricing structure across premium high-field, standard mid-field, and economy portable levels stratifies by magnet technology and software bundling intensity. Pricing pressure stems from permanent magnet platforms collapsing entry-level floors in India and Brazil. County hospitals in provincial China exhibit highest price sensitivity; German university hospitals absorb premium positioning for research-grade spectroscopy.
Supply Chain Analysis
Extended payment terms from Japanese niobium-titanium wire suppliers compress working capital for European coil manufacturers. Niobium-titanium wire concentrates in Japan and Germany; rare-earth magnet arrays source primarily from China. Helium liquefaction infrastructure rests on Qatari and Algerian feedstock. Single-source vulnerability in cryogenic compressor assemblies threatens uptime guarantees. Distribution runs through OEM direct sales for hospital systems and third-party clinical engineering firms for independent diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
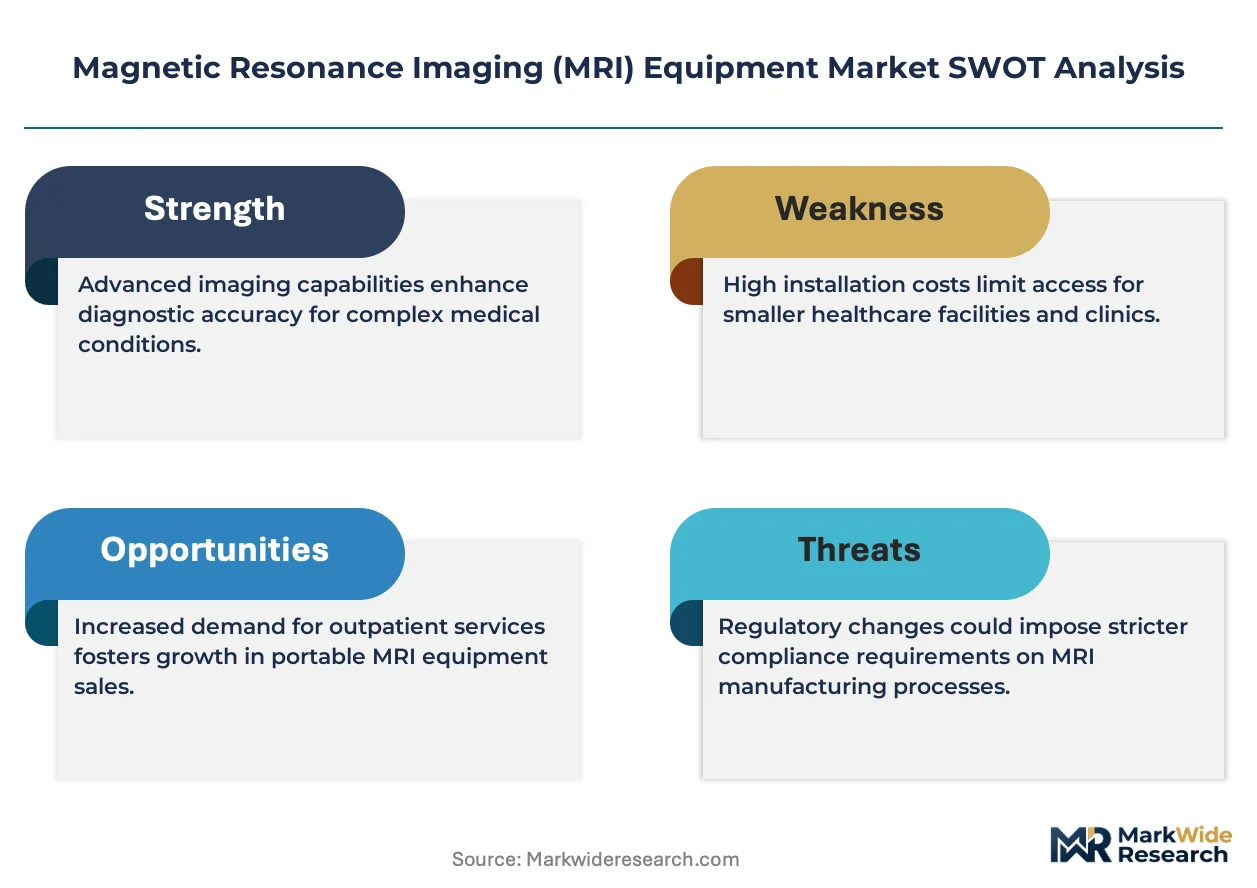
This market functions as a defensive-moat story where regulatory entrenchment around FDA 510(k) and EU MDR certification timelines creates structural barriers that protect incumbent service infrastructure scale.
For Market Incumbents: Pre-empt portable platform challengers by acquiring AI reconstruction software firms before FDA clearance pathways compress their time-to-market advantage. Deepen backward integration into helium recycling systems to neutralize United Imaging's cost position in rural China. Lock in 10-year service contracts with U.S. integrated delivery networks before third-party clinical engineering firms disintermediate attach rates. For New Entrants and Emerging Players: Henan and Sichuan province county hospitals present whitespace where 1.5 Tesla density lags metropolitan benchmarks. Target extremity-dedicated permanent magnet platforms for Texas sports medicine clinics seeking same-day diagnostic confirmation. Pursue subscription-based equipment-as-a-service arrangements with German ambulatory imaging centers to bypass capital purchase committees. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because helium supply chain compression and AI software differentiation are collapsing viable independent hardware vendors into captive OEM divisions. Target mid-tier portable platform specialists with NMPA registrations and localized service networks in China's Yangtze River Delta. Watch FDA 510(k) clearance velocity for AI-enhanced reconstruction protocols as the signal for when software moats overtake hardware performance as the primary value driver.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recycling Infrastructure Investment | Captive liquefaction recovery systems neutralize EU F-Gas Regulation cost pressures for hospital customers. |
| AI Reconstruction Software Acquisition | FDA 510(k) cleared algorithms differentiate superconducting platforms against commoditizing permanent magnet alternatives. |
| County Hospital Service Network Expansion | Localized clinical engineering presence in Henan and Sichuan secures whitespace against domestic portable challengers. |
| Subscription Pricing Model Pilot | Per-scan equipment-as-a-service reduces capital barriers for German ambulatory diagnostic centers. |
| 7.0 Tesla Research Consortium Partnership | NIH-funded neurodegenerative study endpoints anchor premium pricing for ultrahigh-field spectroscopy capability. |
Methodological Framework
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and cryogenic technician certification program administrators anchored the qualitative base. These primary inputs combined with secondary validation from FDA 510(k) clearance databases, NMPA registration filings, hospital procurement contract repositories, and EU MDR notified body decision logs. Bottom-up installation volume tracking across 15 countries triangulated against top-down OEM revenue segmentation.
Scenario-bracketing framed demand projections across the analysis window, modeling technology type, field strength tier, installation format, end-user category, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from logistic diffusion curves fitted to historical replacement cycles and greenfield penetration rates. Helium price volatility indices and AI software regulatory velocity served as industry-specific forecast modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by capital-light portable platform challengers or accelerated FDA AI clearance timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
South America CT Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
South America MRI Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Echocardiography Market
Medical Imaging
Global Image Guided Therapy System Market