
 Nuclear Medicine Software Market | 2026-2036
Nuclear Medicine Software Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Medicine Software Market Insights
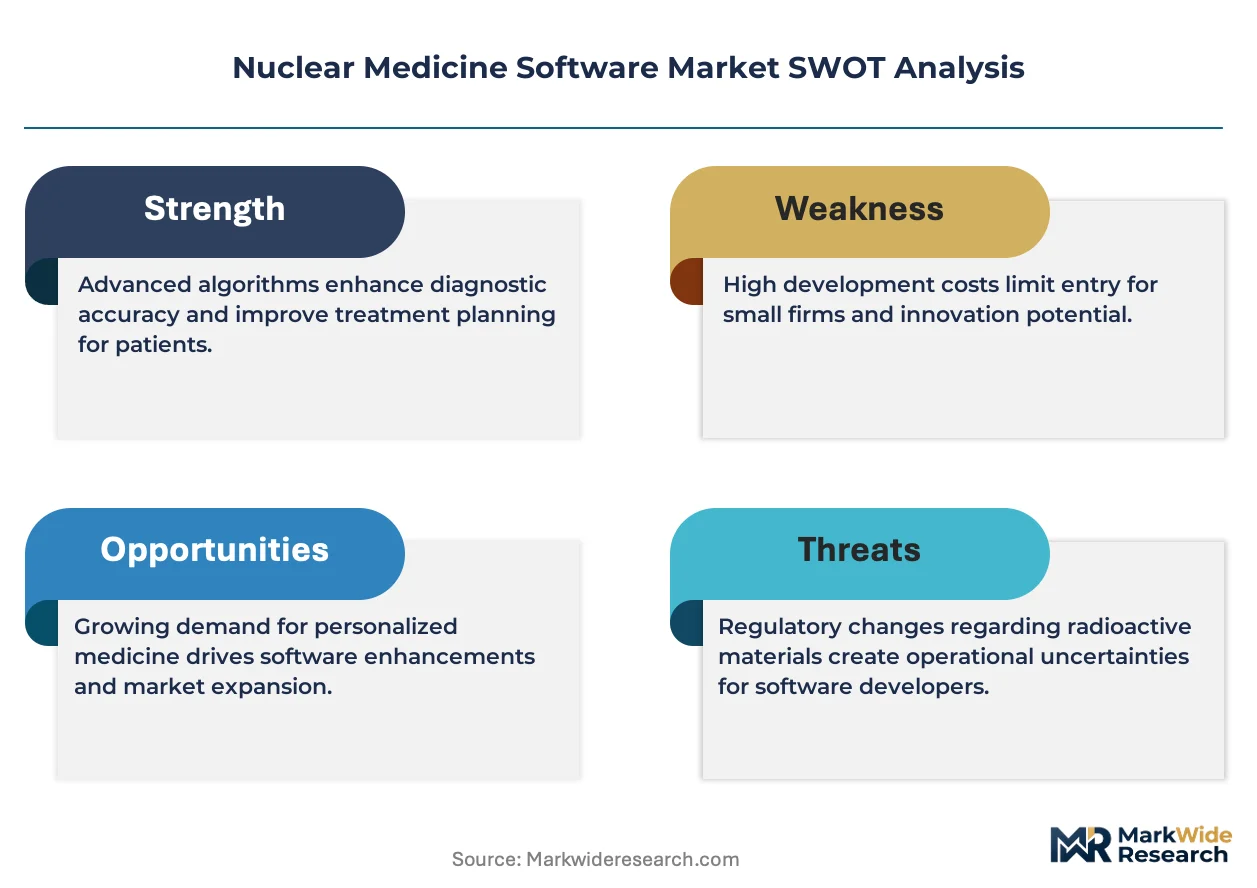
A widening capability gap between cloud-native platforms and legacy on-premise installations is unwinding competitive stability across the vendor landscape. GE HealthCare leverages its embedded hardware-software integration to sustain pricing power in hybrid imaging workflows. Siemens Healthineers anchors its position through deep R&D intensity in AI-augmented reconstruction algorithms. MIM Software Inc. specializes in vendor-neutral quantification tools that compete across heterogeneous scanner fleets.
Nuclear medicine software encompasses computational platforms that process, reconstruct, and quantify functional imaging data from gamma-emitting radiotracers, typically operating with spatial resolutions of 4-10 mm for SPECT and 2-5 mm for PET systems. These tools enable clinicians to calculate standard uptake values, generate time-activity curves, and fuse functional datasets with anatomical CT or MRI references for diagnostic and therapeutic decision-making. Medical imaging software currently occupies the largest revenue pool, while treatment planning systems represent the fastest-expanding segment as theranostic protocols gain clinical traction. Diagnostic tools command premium pricing in cardiology applications where automated perfusion quantification reduces inter-reader variability.
The FDA enforces 21 CFR Part 11 and HIPAA compliance for clinical deployment, while the EMA's MDR framework imposes stricter post-market surveillance obligations on software-as-medical-device classifications in Europe. Japan's PMDA maintains distinct approval pathways for AI-enabled diagnostic functions that lengthen time-to-market but elevate barriers against unvalidated entrants. Stakeholders must monitor evolving reimbursement codes for software-intensive procedures and calibrate R&D portfolios against regulatory divergence across major jurisdictions.
Market Dynamics
The migration from on-premise installations to cloud-native architectures is fragmenting vendor competitive positions as FDA 21 CFR Part 11 validation requirements favor platforms with embedded compliance automation over legacy retrofit approaches.
Growth Catalysts
- Theranostic protocol expansion:Paired diagnostic-therapeutic workflows in oncology departments are accelerating demand for integrated dosimetry calculation modules.
- AI-augmented reconstruction algorithms:Deep learning-based noise reduction and attenuation correction are shortening scan acquisition times while preserving quantitative accuracy.
- Germany's Diagnosis-Related Group refinements:Reimbursement clarity for software-intensive nuclear cardiology procedures is concentrating purchasing authority in academic medical centers.
Market Restraints
- Specialized workforce scarcity:Qualified medical physicists capable of validating quantitative SPECT/CT protocols command premium compensation that constrains site-level adoption.
- Hardware-software bundling:Scanner OEMs leverage embedded software ecosystems to lock purchasing committees into proprietary quantification tools.
- Validation timeline compression:FDA 21 CFR Part 11 documentation requirements extend deployment cycles for cloud-native platforms versus legacy on-premise alternatives.
Strategic Opportunities
- Japan's PMDA AI approval pathway:First-mover advantage awaits vendors achieving software-as-medical-device classification for automated lesion detection functions.
- Vendor-neutral quantification platforms:Heterogeneous scanner fleets in multi-site health systems create demand for cross-manufacturer standardization tools.
- Radiopharmaceutical manufacturing integration:Real-time quality control software linking cyclotron output to imaging workflow represents adjacent revenue capture.
Industry Challenges
- Interoperability architecture complexity:DICOM-RT and HL7 FHIR standard implementation varies across PACS vendors, forcing costly custom integration.
- Cloud security credentialing:HIPAA Business Associate Agreement negotiations with institutional compliance officers delay pilot-to-production transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Medicine Software Market |
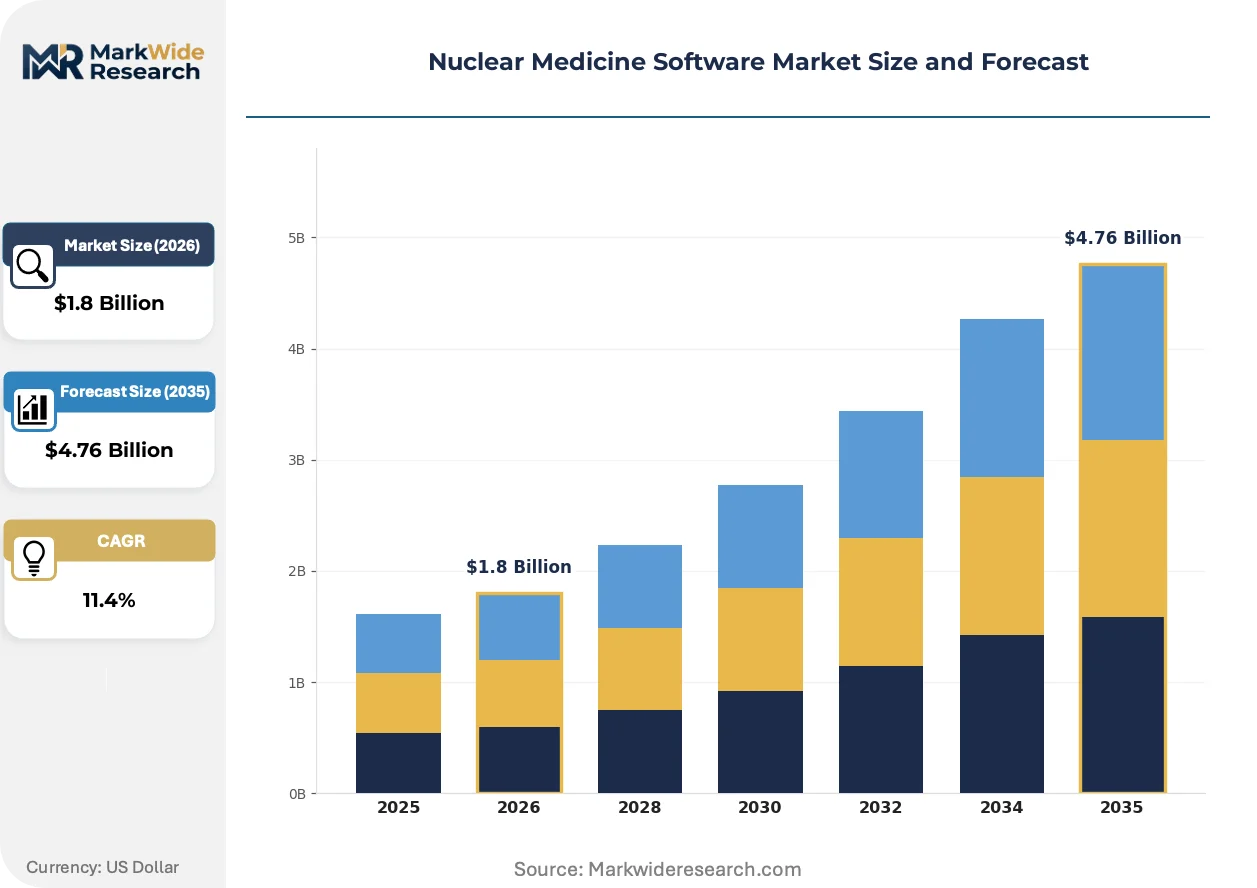
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Medical Imaging Software, Diagnostic Tools, Treatment Planning Systems End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Application: Oncology, Cardiology, Neurology, Pain Management Technology: Gamma Cameras, PET Scanners, SPECT Systems, Hybrid Imaging Devices |
| Companies Covered | Lantheus Holdings, Inc., Hermes Medical Solutions, GE HealthCare, Bracco Group, MIM Software Inc., Siemens Healthineers AG, Mirion Technologies, DOSIsoft SA, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Medicine Software Market Trends and Innovations
Computational reconstruction methods and regulatory automation frameworks are compressing the gap between image acquisition and clinical decision-making, while procurement patterns favor integrated platform economics over point-solution accumulation.
Deep learning-based iterative reconstruction is supplanting filtered back-projection algorithms in SPECT systems. Cardiology departments at high-volume academic centers are adopting these tools to reduce scan times by half while maintaining diagnostic equivalence. The technology is compressing hardware utilization constraints and enabling throughput expansion without capital-intensive scanner additions.
The European Union's Medical Device Regulation imposes stricter post-market surveillance obligations on software-as-medical-device classifications than its predecessor directives. Vendors must now maintain clinical evidence portfolios and vigilance reporting systems that mirror pharmaceutical obligations. European radiopharmaceutical therapy centers are responding by consolidating purchasing around established platforms with proven MDR technical documentation.
Subscription-based licensing models are displacing perpetual license sales in North American hospital procurement. Chief Information Officers favor operational expenditure treatment and embedded cybersecurity maintenance over capital-intensive ownership with fragmented update responsibility. This shift concentrates vendor selection authority in health system headquarters rather than individual department budgets.
Nuclear Medicine Software Market Segmentation
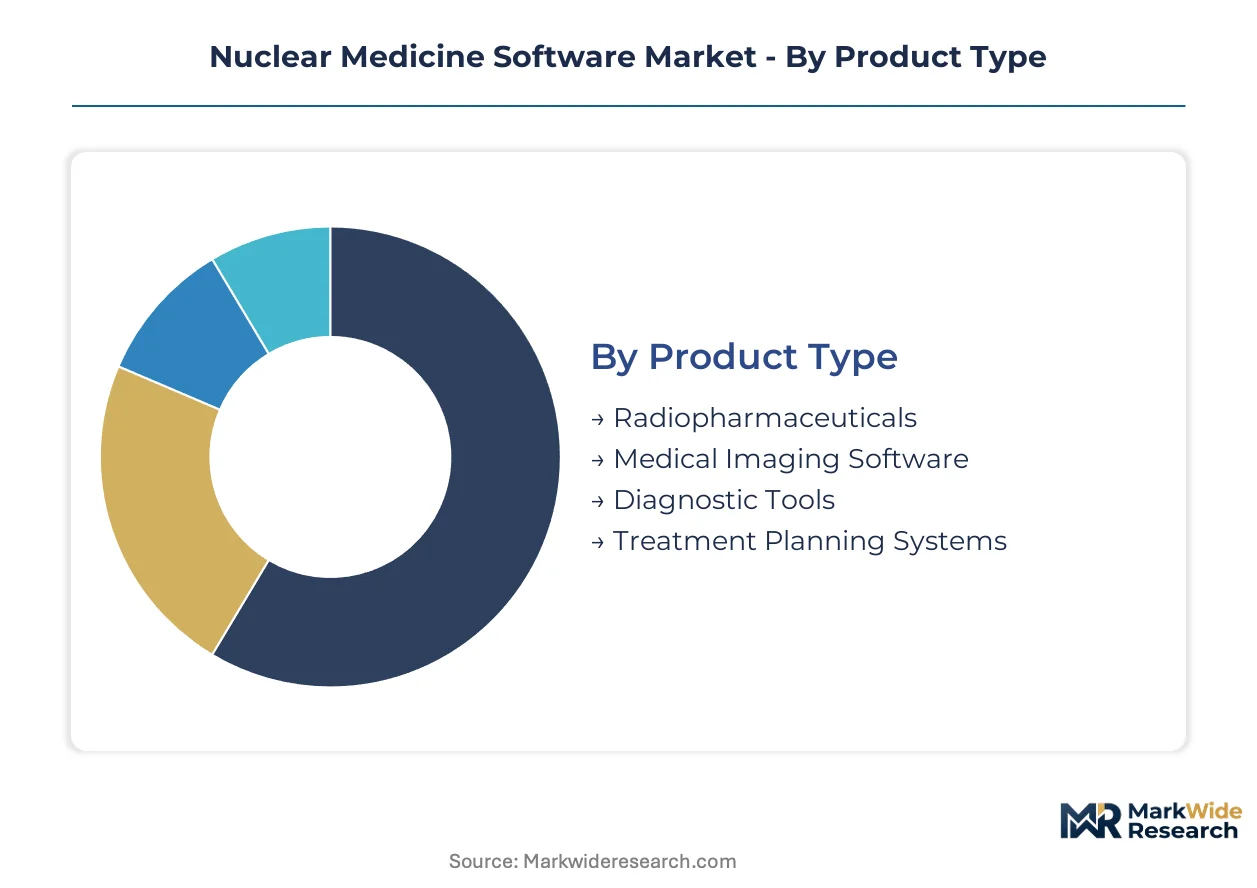
Segmentation in nuclear medicine software reveals distinct procurement patterns across clinical settings, with product architecture and reimbursement pathways determining which configurations reach which end-users. Channel dynamics vary sharply between capital-intensive hybrid imaging platforms and modular quantification tools.
Product Type:
Direct sales dominate capital equipment bundles, while subscription licensing channels favor standalone software modules that integrate across heterogeneous hardware fleets.
- Medical Imaging Software:Computational platforms process functional imaging data from gamma-emitting radiotracers with spatial resolutions of 4-10 mm for SPECT and 2-5 mm for PET systems. United States academic medical centers concentrate purchasing for quantitative SPECT/CT analysis tools as oncology departments expand theranostic protocols. FDA 21 CFR Part 11 validation requirements favor cloud-native architectures with embedded compliance frameworks.
- Treatment Planning Systems:Dosimetry calculation modules enable personalized radiopharmaceutical therapy dosing based on patient-specific pharmacokinetics. Germany's Diagnosis-Related Group refinements create reimbursement clarity that concentrates purchasing authority in academic medical centers for software-intensive nuclear procedures. These systems are gaining share fastest as paired diagnostic-therapeutic workflows mature.
- Radiopharmaceuticals:Companion diagnostic agents require integrated software for tracer kinetic modeling and biodistribution analysis.
- Diagnostic Tools:Automated perfusion quantification packages reduce inter-reader variability in cardiology applications.
The dominant share belongs to Medical Imaging Software, while Treatment Planning Systems are closing the gap fastest.
End User:
Purchasing authority concentrates in health system headquarters under subscription models, while departmental budgets retain control for capital-intensive hardware-software bundles.
- Hospitals:Integrated delivery networks in the United States negotiate enterprise licenses for vendor-neutral quantification tools across multi-site scanner fleets. Chief Information Officers favor operational expenditure treatment with embedded cybersecurity maintenance.
- Diagnostic Centers:Specialized imaging facilities in Japan pursue PMDA software-as-medical-device classification for automated lesion detection functions to differentiate service offerings. These centers are expanding most quickly as outpatient theranostic protocols gain regulatory clarity.
- Research Institutions:Academic medical centers validate quantitative protocols and train specialized medical physicists.
- Outpatient Facilities:Community-based practices adopt streamlined diagnostic tools for routine cardiac and cancer screening.
Hospitals command the installed base, though Diagnostic Centers show the steepest expansion trajectory.
Application:
Reimbursement density determines software investment priority, with cardiology and oncology offering the clearest pathways to procedure-based returns.
- Oncology:Theranostic protocols pair diagnostic imaging with targeted radiopharmaceutical therapy, requiring integrated dosimetry modules. Germany and Japan concentrate demand where reimbursement pathways for paired workflows are most clearly defined. Deep learning-based reconstruction algorithms shorten scan acquisition times while preserving quantitative accuracy for treatment response assessment.
- Cardiology:Automated perfusion quantification commands premium pricing where inter-reader variability reduction justifies software expenditure. United States academic centers adopt deep learning-based iterative reconstruction to halve scan times without diagnostic compromise, compressing hardware utilization constraints.
- Neurology:Amyloid and tau imaging protocols require specialized quantification against normative databases.
- Pain Management:Bone scan analysis tools target metastatic disease detection in oncology crossover applications.
Oncology holds the revenue concentration, yet Cardiology maintains the most mature reimbursement infrastructure.
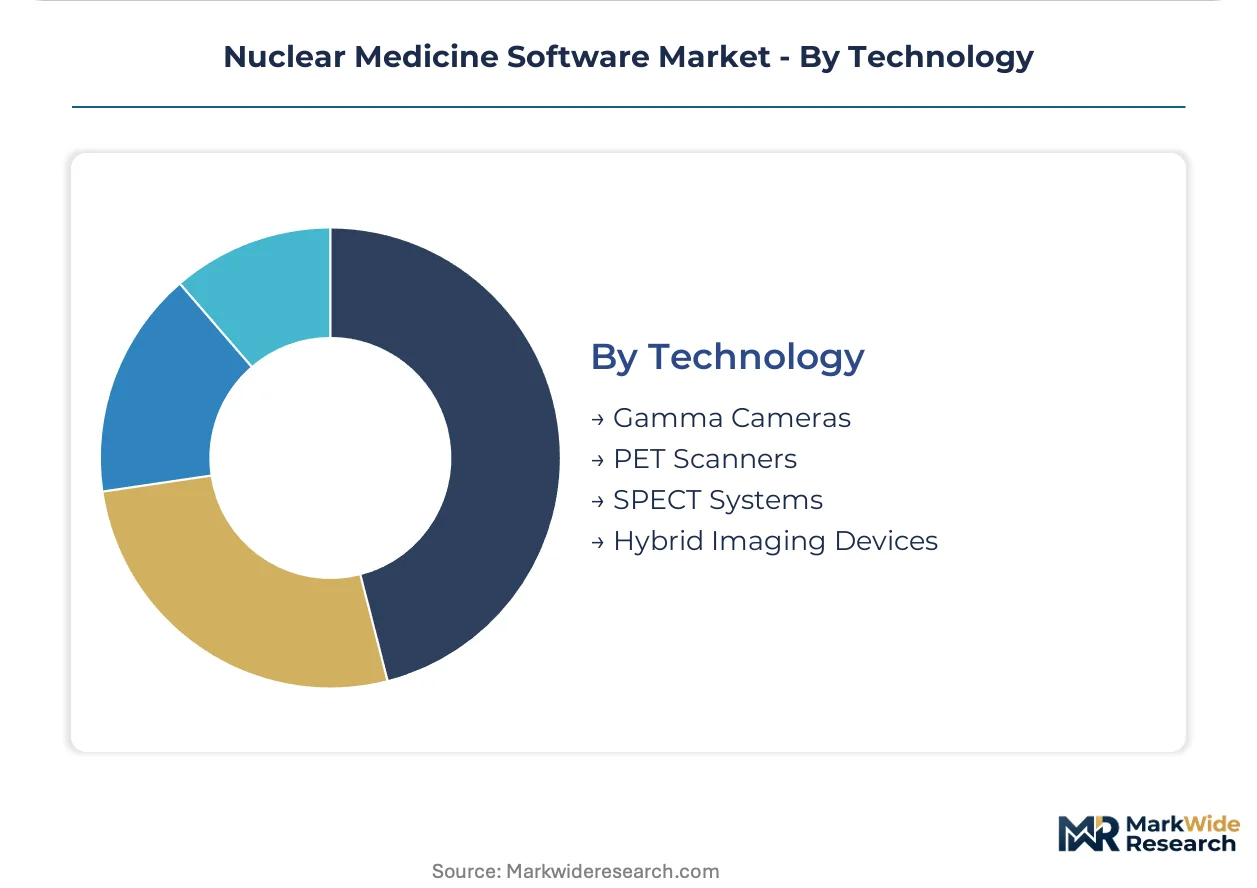
Technology:
Hardware-software bundling by scanner OEMs locks purchasing committees into proprietary ecosystems, creating openings for vendor-neutral platforms at heterogeneous sites.
- Hybrid Imaging Devices:SPECT/CT and PET/CT systems embed proprietary reconstruction and quantification software that sustains OEM pricing power. GE HealthCare leverages hardware-software integration to defend position in United States hospital procurement. Siemens Healthineers anchors share through AI-augmented reconstruction algorithm development.
- SPECT Systems:Gamma camera platforms face substitution pressure as hybrid devices capture cardiac and oncologic volume.
- PET Scanners:Oncology departments prioritize these for metabolic imaging sensitivity in theranostic patient selection.
- Gamma Cameras:Legacy nuclear cardiology workflows persist in cost-constrained outpatient settings.
Hybrid Imaging Devices dominate capital allocation, while PET Scanners climb fastest on theranostic protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys nuclear medicine software predominantly within academic medical centers for theranostic protocols, while Germany and Japan concentrate purchasing in diagnostic centers where reimbursement clarity enables outpatient service expansion. This consumption-mix differential shapes vendor go-to-market strategies across major jurisdictions.
United States
Oncology departments at academic medical centers drive demand for quantitative SPECT/CT analysis tools as paired diagnostic-therapeutic workflows mature. FDA 21 CFR Part 11 validation requirements favor cloud-native platforms with embedded compliance automation over legacy retrofit approaches. Boston and Houston medical clusters concentrate pilot-to-production transitions for AI-augmented reconstruction algorithms.
Germany
Diagnosis-Related Group refinements create reimbursement clarity for software-intensive nuclear cardiology procedures, concentrating purchasing authority in university hospitals. EMA's MDR framework imposes stricter post-market surveillance obligations on software-as-medical-device classifications. The Munich-Düsseldorf corridor anchors adoption of integrated dosimetry calculation modules for radiopharmaceutical therapy.
Japan
Diagnostic centers pursue PMDA software-as-medical-device classification for automated lesion detection functions to differentiate outpatient service offerings. The regulator's distinct approval pathways for AI-enabled diagnostic functions lengthen time-to-market but elevate barriers against unvalidated entrants. Tokyo and Osaka metropolitan areas concentrate theranostic protocol expansion as reimbursement pathways clarify.
United Kingdom
Integrated delivery networks negotiate enterprise licenses for vendor-neutral quantification tools across multi-site scanner fleets. NHS procurement frameworks emphasize operational expenditure treatment with embedded cybersecurity maintenance over capital-intensive ownership. The Oxford-Cambridge-London triangle validates quantitative protocols and trains specialized medical physicists for SPECT/CT standardization.
Switzerland
Research institutions anchor demand for cross-manufacturer standardization tools serving heterogeneous scanner fleets across European multi-site health systems. Swissmedic maintains alignment with EMA MDR requirements while preserving streamlined approval pathways for clinical validation studies. The Basel-Zurich corridor concentrates radiopharmaceutical manufacturing integration with real-time quality control software development.
Nuclear Medicine Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in nuclear medicine software, with hardware-software bundling sustaining pricing power for scanner OEMs against modular challengers. The upper tier leverages embedded reconstruction algorithms and regulatory automation frameworks to defend installed base positions. Specialist archetypes include vendor-neutral quantification platforms, AI-augmented reconstruction developers, and radiopharmaceutical workflow integrators. Competitive moves concentrate on M&A for complementary algorithm portfolios and strategic partnerships for cloud security credentialing.
Within the integrated systems tier, GE HealthCare and Siemens Healthineers occupy positions anchored by hardware-software integration and deep R&D intensity in iterative reconstruction methods. MIM Software Inc. represents the vendor-neutral specialist archetype, competing across heterogeneous scanner fleets with cross-manufacturer standardization tools. Hermes Medical Solutions exemplifies European-based specialists navigating EMA MDR compliance obligations for software-as-medical-device classifications.
| Leading Market Players |
|---|
| Lantheus Holdings, Inc. |
| Hermes Medical Solutions |
| GE HealthCare |
| Bracco Group |
| MIM Software Inc. |
| Siemens Healthineers AG |
| Mirion Technologies |
| DOSIsoft SA |
| Koninklijke Philips N.V. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native architecture substitution for legacy on-premise installations is redrawing procurement geography and pricing economics simultaneously, as FDA 21 CFR Part 11 validation requirements favor embedded compliance automation that fragments vendor competitive positions across United States, Germany, and Japan health systems.
Pricing Analysis
After-sales service and extended validation support contracts drive lifetime value in nuclear medicine software procurement. Subscription-based licensing models now dominate North American hospital procurement, with Chief Information Officers favoring operational expenditure treatment and embedded cybersecurity maintenance over perpetual license ownership. Price differentiation hinges on FDA 21 CFR Part 11 certification tier and after-sales service bundling depth. Cost compression in mid-tier quantification modules is intensifying because scanner OEMs leverage hardware-software bundling to lock purchasing committees into proprietary ecosystems. Community-based outpatient facilities exhibit highest price sensitivity, while academic medical centers prioritize regulatory automation over unit economics.
Supply Chain Analysis
Inbound logistics costs for specialized GPU hardware and cloud infrastructure components face pressure from transpacific container availability constraints and port congestion at Long Beach and Rotterdam. Software development draws from engineering talent pools concentrated in United States, Germany, and Switzerland, with algorithm training dependent on curated clinical datasets from academic medical centers and validated radiopharmaceutical tracer libraries. Single-source vulnerability sits with proprietary reconstruction algorithm IP held by dominant scanner OEMs. Distribution runs through direct enterprise sales for capital-intensive hybrid imaging bundles and subscription-based channel partnerships for modular quantification tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States integrated delivery networks negotiate enterprise licenses across multi-site scanner fleets, fragmenting departmental procurement autonomy that once favored point-solution accumulation.
For Market Incumbents: Consolidate algorithm portfolios through targeted acquisition of AI-augmented reconstruction specialists to defend against vendor-neutral quantification platforms eroding proprietary ecosystem lock-in. Deepen vertical integration into cloud security credentialing services to accelerate pilot-to-production transitions that HIPAA Business Associate Agreement negotiations currently delay. Scanner OEMs must embed compliance automation frameworks that compress FDA 21 CFR Part 11 validation timelines versus cloud-native retrofit approaches.
For New Entrants and Emerging Players: Anchor in Japan's diagnostic center segment where PMDA software-as-medical-device classification creates first-mover advantage for automated lesion detection functions. Target Germany's university hospital corridor where Diagnosis-Related Group reimbursement clarity concentrates purchasing authority for integrated dosimetry modules. Pursue strategic partnerships with radiopharmaceutical manufacturers for real-time quality control software linking cyclotron output to imaging workflow.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vendor-neutral quantification platforms serving heterogeneous scanner fleets across European multi-site health systems. Five-to-ten year viability hinges on MDR technical documentation depth and cloud-native architecture migration completion. Watch for FDA 21 CFR Part 11 validation timeline compression as inflection indicator for competitive repositioning among cloud-native versus legacy platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | FDA 21 CFR Part 11 embedded compliance automation accelerates hospital procurement cycles. |
| AI-Augmented Reconstruction Acquisition | Deep learning algorithm portfolios shorten scan acquisition times while preserving quantitative accuracy. |
| Vendor-Neutral Quantification Development | Cross-manufacturer standardization tools capture heterogeneous scanner fleet demand in multi-site systems. |
| Radiopharmaceutical Workflow Integration | Real-time quality control software links cyclotron output to imaging for adjacent revenue capture. |
| Japan PMDA SaMD Classification Pursuit | Automated lesion detection approval elevates barriers against unvalidated diagnostic entrants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineers, GPO contracts managers, and medical physicists at academic medical centers. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up segmentation modeling triangulated against top-down market sizing from installed base estimates and replacement cycle analysis.
Across the analysis window, forecasts integrated deployment model transitions from perpetual license to subscription SaaS, organization size tiering from community hospitals to integrated delivery networks, and vertical specialization across oncology, cardiology, and neurology applications. CAGRs derived from procedure volume growth, reimbursement code expansion, and scanner fleet replacement dynamics. AI-augmented reconstruction adoption curves and theranostic protocol penetration served as industry-specific demand inputs.
Material uncertainties — regulatory divergence across FDA, EMA, and PMDA jurisdictions, specialized medical physicist workforce scarcity, and cloud security credentialing delays — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement pathway clarity and compliance automation maturation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Medical Holography Market