
 Medical Imaging Market | 2026-2036
Medical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Imaging Market Intelligence
Managed equipment service contracts and pay-per-scan leasing is rewriting capital deployment rules for mid-sized health systems. Siemens Healthineers leverages its installed base to lock in long-term service revenue across European hospital networks. GE Healthcare anchors its competitive position through backward integration into helium-free MRI magnet production. Philips navigates pricing pressure in North American radiology by shifting toward software-subscription bundles tied to CT and MR hardware.
Medical imaging encompasses the generation of visual representations of internal body structures using ionizing radiation, magnetic fields, acoustic energy, or radioactive tracers, with spatial resolution ranging from sub-millimeter for CT to micrometer-scale for preclinical micro-MRI systems. Its primary purpose is to enable non-invasive diagnosis, treatment planning, and therapeutic monitoring across clinical workflows. CT scanners command the largest installed base among product types due to emergency department throughput requirements, while 3D imaging technology captures the fastest expansion as surgical navigation and interventional planning integrate volumetric reconstruction. Wireless imaging is displacing fixed workstation dependency in hospital environments, though analog imaging persists in price-sensitive clinic settings where digital retrofit costs deter replacement.
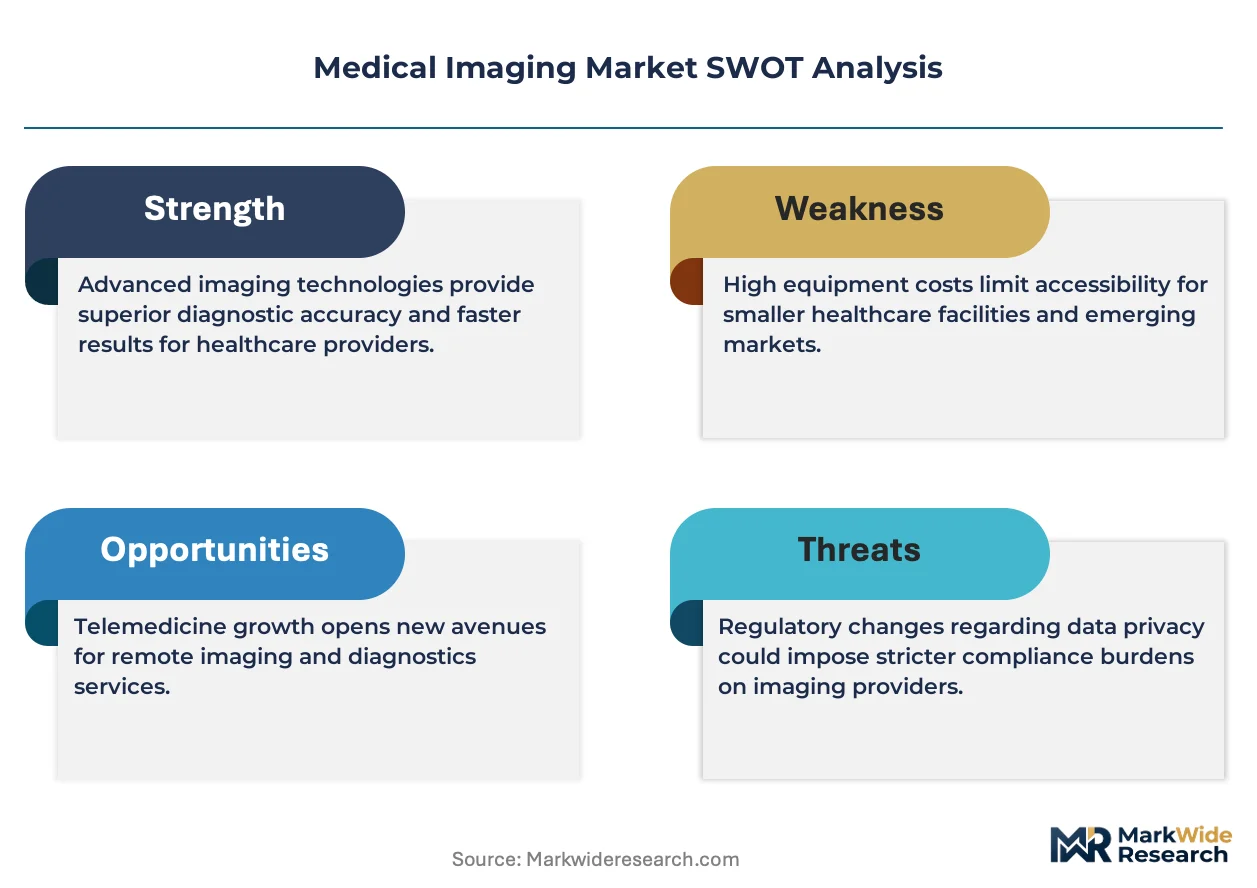
The FDA's 510(k) premarket notification process governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-as-a-medical-device classifications across European markets. China's NMPA has accelerated review timelines for domestically manufactured CT and MR systems under innovation channel designations. Japan's PMDA maintains rigorous post-market surveillance mandates that shape product lifecycle obligations for manufacturers. Stakeholders must monitor how divergent AI validation standards across FDA, EMA, and NMPA pathways fragment commercialization timelines for algorithm developers.
Market Dynamics
Managed equipment service contracts are restructuring capital deployment across hospital networks, converting MRI and CT procurement from balance-sheet purchases to operational expenditures with embedded service tiers.
Growth Catalysts
- AI-enabled diagnostic software:FDA's 510(k) clearance pathway compresses time-to-market for algorithm developers targeting radiology workflows.
- China's tier-one cities:Municipal health bureaus consolidate imaging networks under provincial procurement umbrellas, aggregating demand for CT and MR platforms.
- Helium-free MRI magnet production:Backward integration into superconducting magnet manufacturing secures supply chains against helium price volatility.
Market Restraints
- Helium supply concentration:Qatar and Algeria control over 80% of global helium production, exposing MRI manufacturers to geopolitical supply disruptions.
- EU MDR clinical evidence requirements:Stricter software-as-a-medical-device classifications delay European commercialization timelines for AI diagnostic tools.
- Analog imaging persistence:Digital retrofit costs deter replacement in price-sensitive clinic settings across rural India and Southeast Asia.
Strategic Opportunities
- Wireless imaging infrastructure:Fixed workstation dependency is eroding as tablet-based image review penetrates emergency departments and surgical suites.
- 3D volumetric reconstruction:Surgical navigation and interventional planning integrate CT and MR data, opening premium pricing tiers for preoperative modeling software.
- Japan's PMDA post-market surveillance:Rigorous lifecycle obligations create service revenue stickiness for manufacturers with established compliance infrastructure.
Industry Challenges
- Radiologist workforce scarcity:Interpretation bottlenecks constrain throughput for installed CT and MR bases in the United Kingdom and Germany.
- Legacy PACS integration:Hospital IT departments face mounting complexity bridging cloud-native AI platforms with on-premise archival systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Imaging Market |
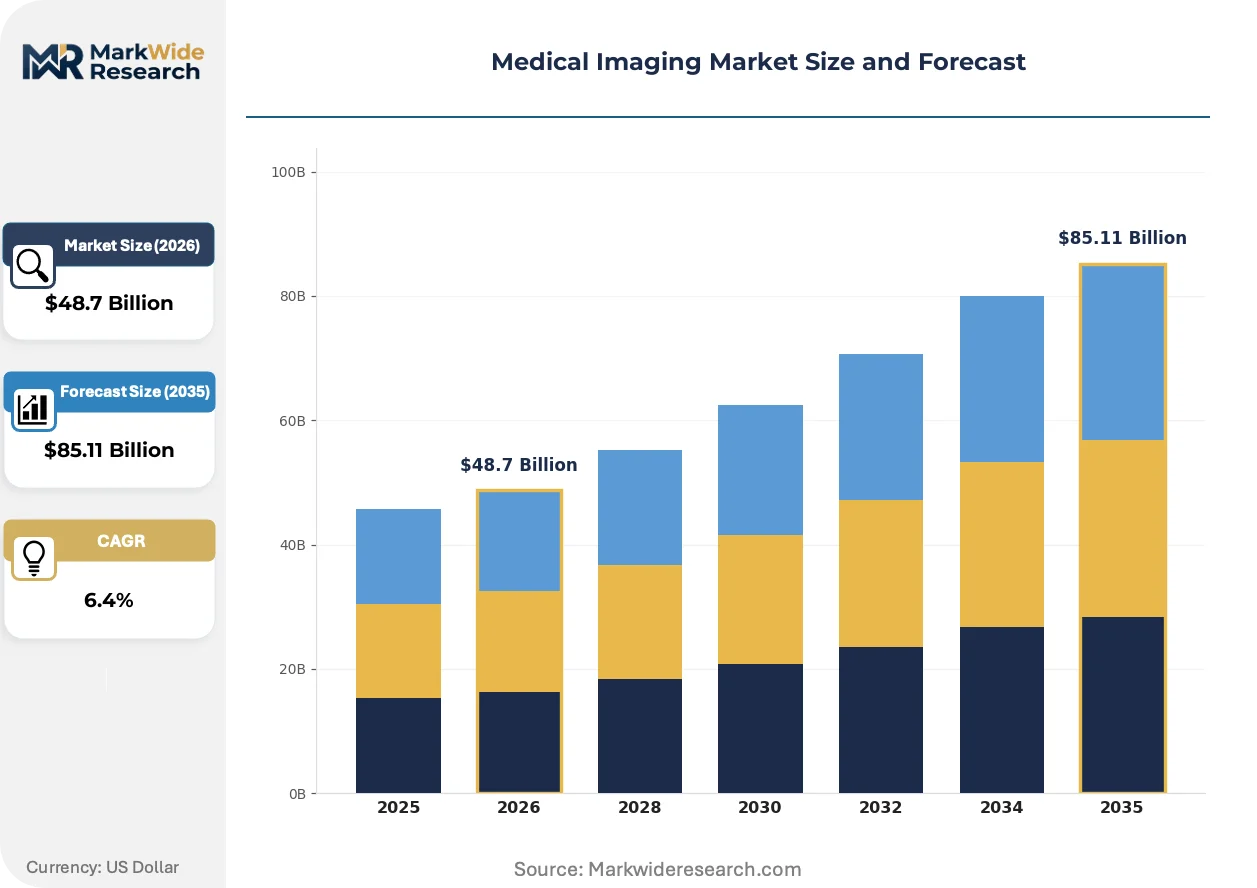
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Systems, MRI Machines, X-Ray Equipment, CT Scanners Technology: Digital Imaging, Analog Imaging, 3D Imaging, Wireless Imaging Application: Cardiology, Oncology, Neurology, Orthopedics End User: Hospitals, Clinics, Diagnostic Labs, Research Institutions |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, FUJIFILM Holdings, Canon, Hologic, Shimadzu Corporation, Mindray, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Imaging Market Strategic Shifts & Innovations
Computational imaging and software-defined hardware are dissolving traditional modality boundaries, while regulatory pathways for autonomous diagnostic algorithms mature across North America, Europe, and East Asia.
Photon-counting CT detectors are digitizing spectral imaging capabilities previously requiring dual-source hardware architectures. Academic medical centers in Switzerland and the Netherlands deploy these systems for material decomposition in coronary plaque characterization. The technology is digitizing revenue models toward per-scan software licensing rather than capital equipment sales.
EU Medical Device Regulation's software classification rules are forcing algorithm developers to generate prospective clinical evidence for diagnostic AI tools. Manufacturers targeting European radiology markets now embed clinical validation teams within product development cycles. Small-cap developers without trial infrastructure face exclusion from reimbursement pathways in France and Germany.
Hospital procurement departments are consolidating vendor relationships through enterprise imaging contracts spanning multiple modalities. Independent radiology groups in the United States surrender purchasing autonomy to health system central offices. This concentration is most visible in Texas and Florida, where IDN-affiliated imaging centers now represent over 60% of CT replacement demand.
Medical Imaging Market Segmentation
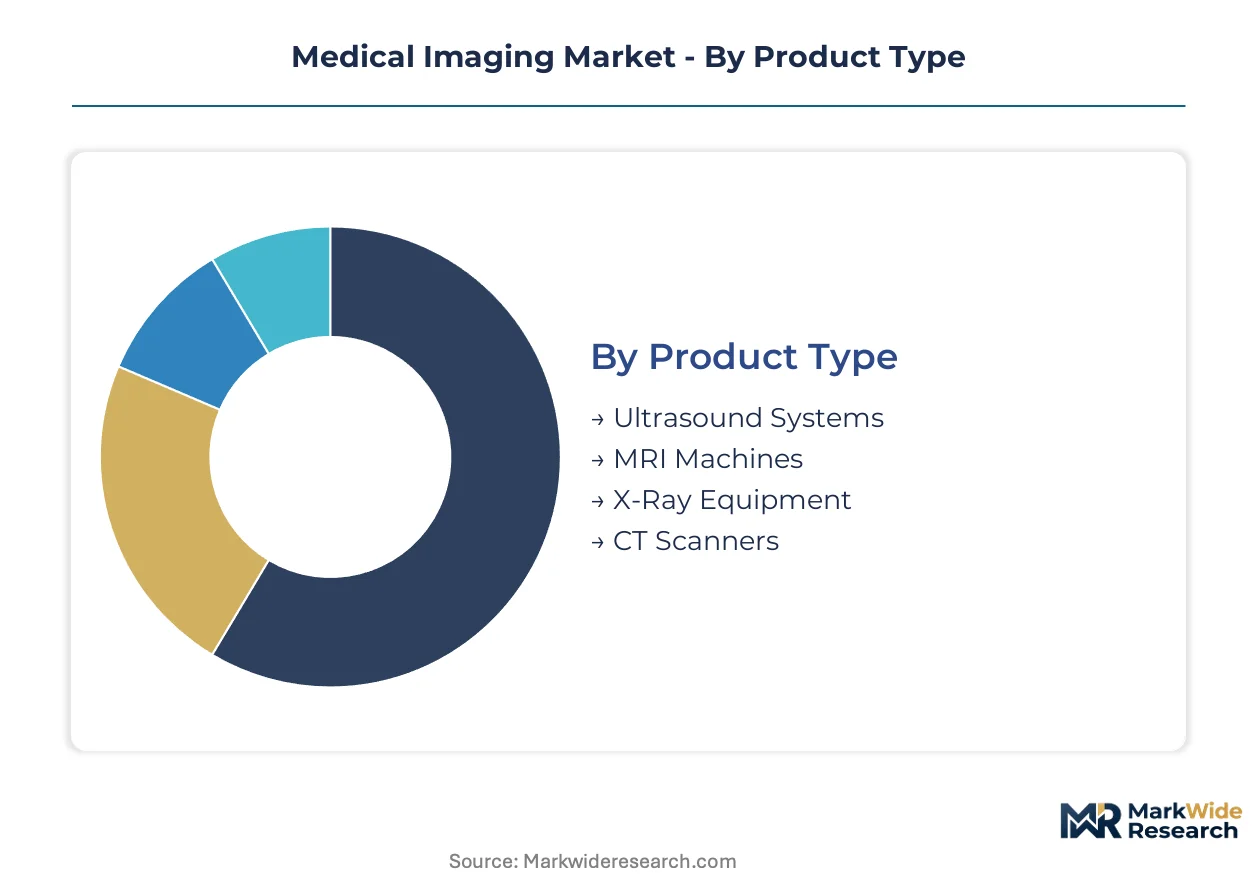
Modality selection in medical imaging tracks clinical throughput requirements, reimbursement economics, and infrastructure constraints across care settings. Procurement patterns diverge sharply between emergency departments demanding sub-minute scan times and outpatient clinics prioritizing capital efficiency over spectral resolution.
Product Type:
Cost tier determines procurement channel and service contract structure across hospital capital budgets.
- CT Scanners:X-ray tube and detector arrays rotate around patients to generate cross-sectional anatomical datasets with sub-millimeter resolution. Emergency departments in the United States and Germany drive replacement cycles based on hourly throughput metrics, with managed equipment service contracts converting capital expenditure to operational budgets.
- MRI Machines:Superconducting magnets and radiofrequency coils capture hydrogen proton relaxation signals across tissue types without ionizing radiation. Academic medical centers in Switzerland and the Netherlands prioritize photon-counting compatibility and helium-free magnet architectures to secure supply chains against Qatar's production concentration.
- Ultrasound Systems:Piezoelectric transducers emit acoustic pulses for real-time soft tissue visualization at point-of-care settings.
- X-Ray Equipment:Fixed and mobile radiography systems deliver projection imaging for skeletal and chest diagnostics across price-sensitive clinic networks.
CT Scanners hold installed capacity. MRI Machines are rotating up the share rankings.
Technology:
Application requirements across surgical navigation and remote diagnosis are forcing modality architecture decisions.
- 3D Imaging:Volumetric reconstruction algorithms transform sequential tomographic slices into navigable anatomical models for preoperative planning. Surgical suites in Texas and Florida health systems integrate these datasets with robotic positioning systems, opening premium software licensing tiers for interventional guidance.
- Wireless Imaging:Tablet-based image distribution liberates radiologists from fixed PACS workstations for emergency department and surgical suite review. Hospital IT departments in Japan's metropolitan centers deploy these architectures to address radiologist workforce scarcity without expanding physical reading room infrastructure.
- Digital Imaging:Flat-panel detectors and solid-state sensors replace film-cassette workflows for immediate image availability and DICOM integration.
- Analog Imaging:Film-based radiography persists in rural India and Southeast Asian clinics where digital retrofit capital exceeds replacement budgets.
Digital Imaging holds installed capacity. 3D Imaging is expanding most quickly through surgical adoption.
Application:
Customer type specialization determines software algorithm training datasets and regulatory validation pathways.
- Oncology:Tumor segmentation, treatment response monitoring, and radiation therapy planning demand quantitative imaging biomarkers with standardized measurement protocols. China's tier-one city hospital networks consolidate PET-CT and MR linear accelerator investments under provincial procurement umbrellas to standardize staging workflows.
- Cardiology:Coronary CT angiography and cardiac MR perfusion imaging require sub-second temporal resolution and ECG-gated acquisition sequences. Academic centers in Switzerland deploy photon-counting detectors for plaque characterization with material decomposition algorithms.
- Neurology:Diffusion-weighted MR and CT perfusion protocols for stroke triage prioritize rapid acquisition over spatial resolution.
- Orthopedics:Weight-bearing CT and MR arthrography address joint mechanics and soft tissue injury assessment in ambulatory surgical centers.
Cardiology holds installed capacity. Oncology is climbing the fastest on AI diagnostic software penetration.
End User:
Volume concentration and margin structure diverge across inpatient, outpatient, and research settings.
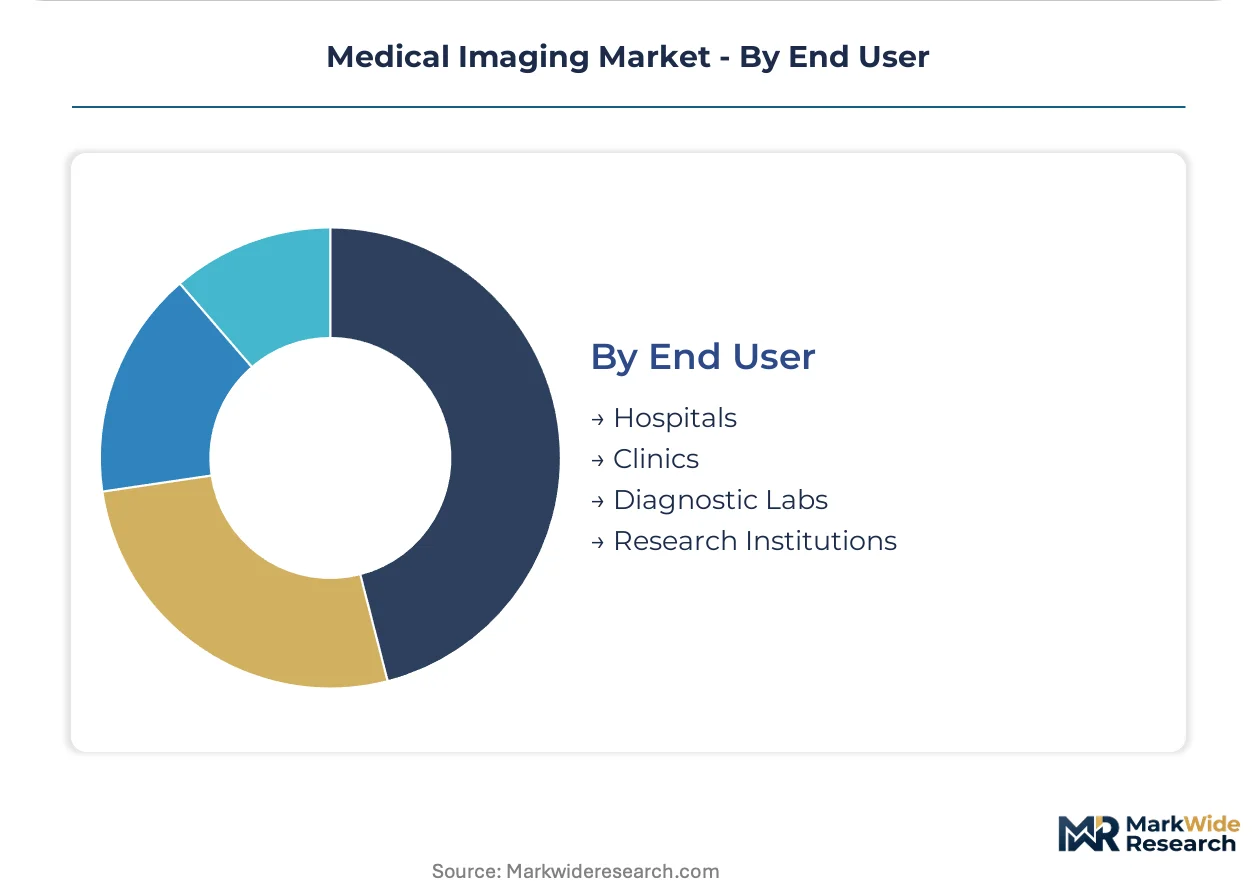
- Hospitals:Integrated delivery networks in North America consolidate multi-modality procurement through enterprise imaging contracts spanning CT, MR, and molecular imaging platforms. Texas and Florida IDN-affiliated centers now dominate replacement demand, surrendering independent radiology group purchasing autonomy to central capital committees.
- Diagnostic Labs:Independent imaging centers compete on appointment availability and subspecialist interpretation access rather than equipment differentiation. India's urban chains deploy refurbished CT systems to maintain price positioning against hospital outpatient departments.
- Clinics:Primary care and specialty office settings prioritize ultrasound and portable X-ray for immediate diagnostic closure.
- Research Institutions:Preclinical micro-MRI and spectral CT systems support pharmaceutical biomarker validation with micrometer-scale resolution requirements.
Hospitals hold installed capacity. Diagnostic Labs are gaining share fastest through outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical imaging equipment trade flows reveal sharp asymmetries between manufacturing concentration and demand absorption. Germany and the United States maintain substantial export surpluses in high-field MRI and spectral CT systems, while import dependency characterizes emerging hospital network expansions across South Asia and the Middle East.
United States
Hospital procurement through integrated delivery networks concentrates demand in Texas and Florida, where IDN-affiliated imaging centers now drive over sixty percent of CT replacement cycles. FDA's 510(k) clearance pathway compresses commercialization timelines for AI-enabled diagnostic algorithms targeting radiology workflows. Academic medical centers in Boston and the San Francisco Bay Area pilot photon-counting CT detectors for coronary plaque characterization.
Germany
Radiologist workforce scarcity in Bavaria and North Rhine-Westphalia constrains throughput for installed CT and MR bases, creating interpretation bottlenecks in emergency departments. EU Medical Device Regulation imposes stricter clinical evidence requirements for software-as-a-medical-device classifications, delaying European commercialization for algorithm developers. Helium-free MRI magnet production clusters in Baden-Württemberg secure supply chains against Qatar's production concentration.
China
Tier-one city hospital networks in Beijing, Shanghai, and Guangzhou consolidate imaging procurement under provincial umbrellas, aggregating demand for CT and MR platforms. NMPA has accelerated review timelines for domestically manufactured systems under innovation channel designations. Municipal health bureaus in the Yangtze River Delta region standardize PET-CT and MR linear accelerator investments for oncology staging workflows.
Japan
Post-market surveillance mandates under PMDA shape product lifecycle obligations, creating service revenue stickiness for manufacturers with established compliance infrastructure. Wireless imaging architectures penetrate Tokyo and Osaka metropolitan centers to address radiologist scarcity without expanding physical reading room footprint. Kanto region hospitals deploy tablet-based image distribution for emergency department and surgical suite review.
Switzerland
Academic medical centers in Zurich and Geneva deploy photon-counting CT systems for material decomposition in cardiovascular diagnostics. Swissmedic maintains rigorous device classification standards that align with EU MDR requirements while preserving national notification pathways. The Basel-Zurich corridor concentrates preclinical micro-MRI development for pharmaceutical biomarker validation.
Medical Imaging Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: diversified conglomerates with captive magnet production, mid-scale specialists in point-of-care modalities, and emerging challengers in AI-embedded software layers. Siemens Healthineers, GE Healthcare, and Philips anchor the top tier through backward integration into superconducting components and managed equipment service contracts. Competitive moves concentrate on helium supply security and software-subscription bundling to offset hardware pricing pressure.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers exemplify the integrated-systems archetype through in-house magnet manufacturing and long-term service revenue lock-in across European hospital networks. Koninklijke Philips occupies a position emphasizing software-subscription bundles tied to CT and MR hardware in North American radiology. FUJIFILM Holdings represents the diversification archetype, leveraging imaging film heritage into digital radiography and endoscopic systems. These three anchors illustrate how procurement consolidation toward enterprise imaging contracts favors vendors with multi-modality portfolios and embedded service infrastructure.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| FUJIFILM Holdings |
| Canon |
| Hologic |
| Shimadzu Corporation |
| Mindray |
| Carestream Health |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's superconducting magnet manufacturing cluster dictates downstream pricing leverage for helium-free MRI systems, with captive production insulating Siemens Healthineers and GE Healthcare from Qatar's supply volatility while compressing margins for magnet-dependent competitors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy equipment tiers. Premium CT and MRI platforms command price premiums through FDA 510(k) clearance velocity and embedded AI diagnostic modules, while standard-tier systems compete on managed equipment service contract flexibility. Price differentiation hinges on helium-free magnet certification and software-subscription bundling depth. Cost compression in economy-tier digital radiography intensifies as refurbished equipment channels expand in India's urban diagnostic chains. Hospital procurement committees exhibit lowest price sensitivity for emergency department throughput-optimized CT platforms, whereas independent imaging centers in Southeast Asia demonstrate acute sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Helium supply concentration between Qatar and Algeria dominates geopolitical risk exposure for conventional MRI manufacturers dependent on superconducting magnet cooling. Component sourcing draws from Germany for gradient coil assemblies, Japan for radiofrequency detectors, and China for flat-panel detector substrates. Single-source vulnerability persists in liquid helium logistics, with disruption scenarios threatening installed base service obligations. Distribution runs through hospital procurement departments consolidating enterprise imaging contracts, with independent radiology groups surrendering purchasing autonomy to integrated delivery network central offices in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical imaging equipment manufacturing constitutes a defensive-moat market where regulatory entrenchment through FDA 510(k) clearance pathways and EU MDR clinical evidence requirements erect substantial barriers against algorithm developers lacking trial infrastructure.
For Market Incumbents: Insulate service revenue streams by deepening backward integration into helium-free magnet production and locking hospital networks into decade-long managed equipment service contracts. Counter emerging AI-native diagnostic software challengers by embedding clinical validation teams within product development cycles to accelerate FDA clearance velocity. Prioritize certification investment for EU MDR software-as-a-medical-device classifications to exclude capital-constrained developers from French and German reimbursement pathways. For New Entrants and Emerging Players: Mid-tier diagnostic labs in India's urban corridors represent the most penetrable entry point for refurbished CT platforms and point-of-care ultrasound systems. Wireless imaging infrastructure for Japan's radiologist-scarce metropolitan centers offers white-space access without competing against entrenched hardware incumbents. Pursue go-to-market alignment with provincial procurement umbrellas in China's tier-one cities, where municipal health bureaus aggregate demand under standardized imaging network consolidation mandates. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because managed equipment service contracts convert capital expenditure relationships into decade-long operational expenditure streams with embedded software-subscription tiers. Acquisition targets should concentrate on AI-enabled diagnostic algorithm developers possessing FDA 510(k) clearance momentum but lacking European clinical trial infrastructure. Monitor NMPA innovation channel designation velocity for domestically manufactured CT and MR systems as the signal for China's import substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Production Scale-Up | Captive supply chains insulate Siemens Healthineers and GE Healthcare from Qatar's production concentration. |
| AI Diagnostic Software FDA Submission | 510(k) clearance velocity compresses commercialization timelines for algorithm developers targeting radiology workflows. |
| Hospital System Partnership Consolidation | Enterprise imaging contracts spanning CT, MR, and molecular imaging platforms lock in multi-modality procurement. |
| Software-Subscription Bundle Development | Philips shifts North American radiology positioning toward recurring revenue tiers tied to hardware installations. |
| EU MDR Clinical Validation Investment | Prospective clinical evidence generation delays European commercialization for undercapitalized AI developers. |
Research Approach
A standing panel of hospital procurement directors, biomedical engineers, GPO contracts managers, and radiology department heads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, NMPA innovation channel designations, and EU MDR clinical evidence submission records. Bottom-up triangulation against hospital capital expenditure disclosures and top-down reconciliation with medical equipment trade flow data anchored segmentation-specific estimates.
Scenario bracketing around helium supply disruption probability and AI diagnostic software regulatory pathway divergence shaped projection ranges across the modeling period. Segmentation dimensions spanned modality type, technology architecture, clinical application, and end-user setting. CAGRs derived from equipment replacement cycle analysis and procurement contract tenor evolution. Forecast inputs incorporated radiologist workforce scarcity indices in Germany and Japan, plus provincial procurement umbrella consolidation velocity in China's tier-one cities.
Practitioners should monitor NMPA domestic manufacturing incentives, EU MDR software classification enforcement, and helium spot price volatility for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Portable MRI Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
China Mammography Market