
 Point of Care Ultrasound Systems Market | 2026-2036
Point of Care Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care Ultrasound Systems Market Insights
The direct-to-hospital sales channel is narrowing as group purchasing organizations consolidate procurement decisions across integrated delivery networks. GE HealthCare leverages its installed base of radiology systems to cross-sell compact point-of-care units into emergency departments. Butterfly Network competes on semiconductor-based single-probe architecture that collapses cost structures for clinic settings. Siemens Healthineers anchors its position through hybrid contracts bundling hardware, software updates, and training subscriptions.
Point of care ultrasound systems are portable diagnostic imaging devices operating at frequencies between 2-15 MHz, designed for real-time anatomical visualization at the patient's bedside without requiring dedicated radiology suite infrastructure. Their primary commercial purpose is to accelerate clinical decision-making in time-sensitive care environments while reducing dependency on centralized imaging departments. Handheld devices are capturing the fastest expansion trajectory as semiconductor miniaturization enables probe-to-smartphone connectivity at sub-console price points. Emergency medicine applications command the deepest current installed base, though critical care segments are widening as intensivist training programs standardize ultrasound competency requirements.
FDA 510(k) premarket notification requirements govern device safety and effectiveness submissions, while the EU MDR imposes stricter clinical evidence standards for class IIa and IIb diagnostic imaging devices entering European markets. ISO 13485 quality management certification has become a baseline qualifier for supplier qualification by major hospital chains, effectively filtering non-compliant manufacturers from procurement shortlists. Stakeholders must monitor how AI diagnostic algorithm classifications shift between software-as-medical-device and embedded hardware regulatory pathways across jurisdictions.
Market Dynamics
Semiconductor miniaturization is collapsing the cost-performance threshold for probe-to-smartphone connectivity, redistributing purchasing power from radiology departments to individual clinicians and ambulatory networks.
Growth Catalysts
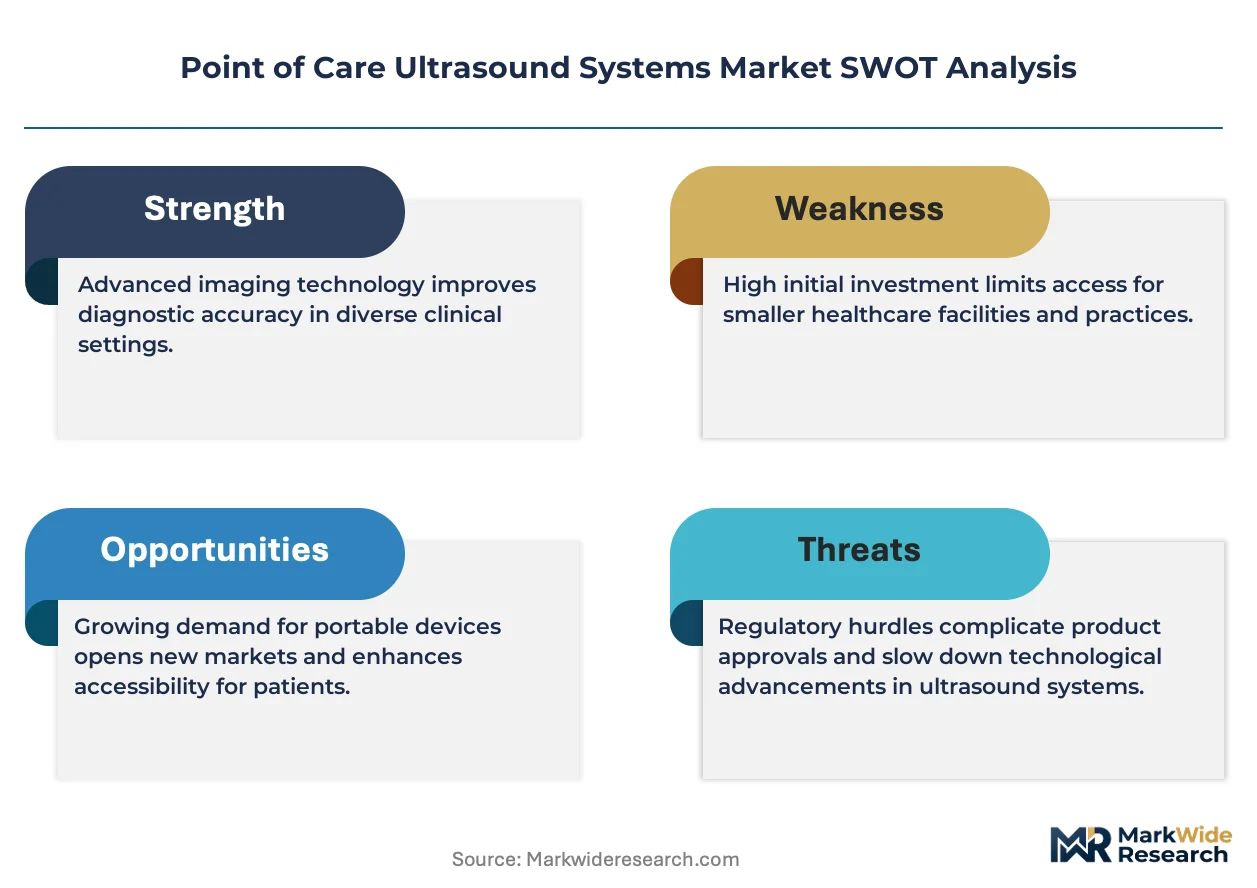
- Emergency medicine protocol standardization:Hospital networks in the United States are mandating point-of-care ultrasound competency for emergency physicians, embedding devices into triage workflows.
- ISO 13485 certification requirements:Major hospital chains now filter supplier shortlists through quality management certification, elevating compliant manufacturers above fragmented competitors.
- AI-enabled diagnostic algorithms:Machine learning integration into handheld probes accelerates image interpretation without requiring radiologist availability at the bedside.
Market Restraints
- CMOS sensor supply concentration:Advanced semiconductor fabrication for ultrasound-on-a-chip architectures depends on a limited supplier base concentrated in East Asian foundries.
- EU MDR clinical evidence requirements:Class IIa and IIb diagnostic imaging devices face extended approval timelines and expanded post-market surveillance obligations.
- CT and MRI substitution pressure:For definitive diagnostic confirmation, centralized imaging modalities retain preference in oncology and neurological applications.
Strategic Opportunities
- Critical care intensivist training expansion:Standardized ultrasound competency requirements in ICU fellowship programs are widening addressable demand beyond emergency medicine.
- Subscription-based training bundling:Hybrid contracts combining hardware, software updates, and education subscriptions capture recurring revenue from integrated delivery networks.
- Group purchasing organization consolidation:Procurement centralization across multi-site hospital systems favors vendors with enterprise-scale service infrastructure.
Industry Challenges
- Probe-to-platform integration complexity:Legacy PACS infrastructure in established hospitals requires costly middleware development for seamless image workflow integration.
- Software-as-medical-device classification uncertainty:AI diagnostic algorithms face jurisdictional variation between embedded hardware and standalone software regulatory pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care Ultrasound Systems Market |
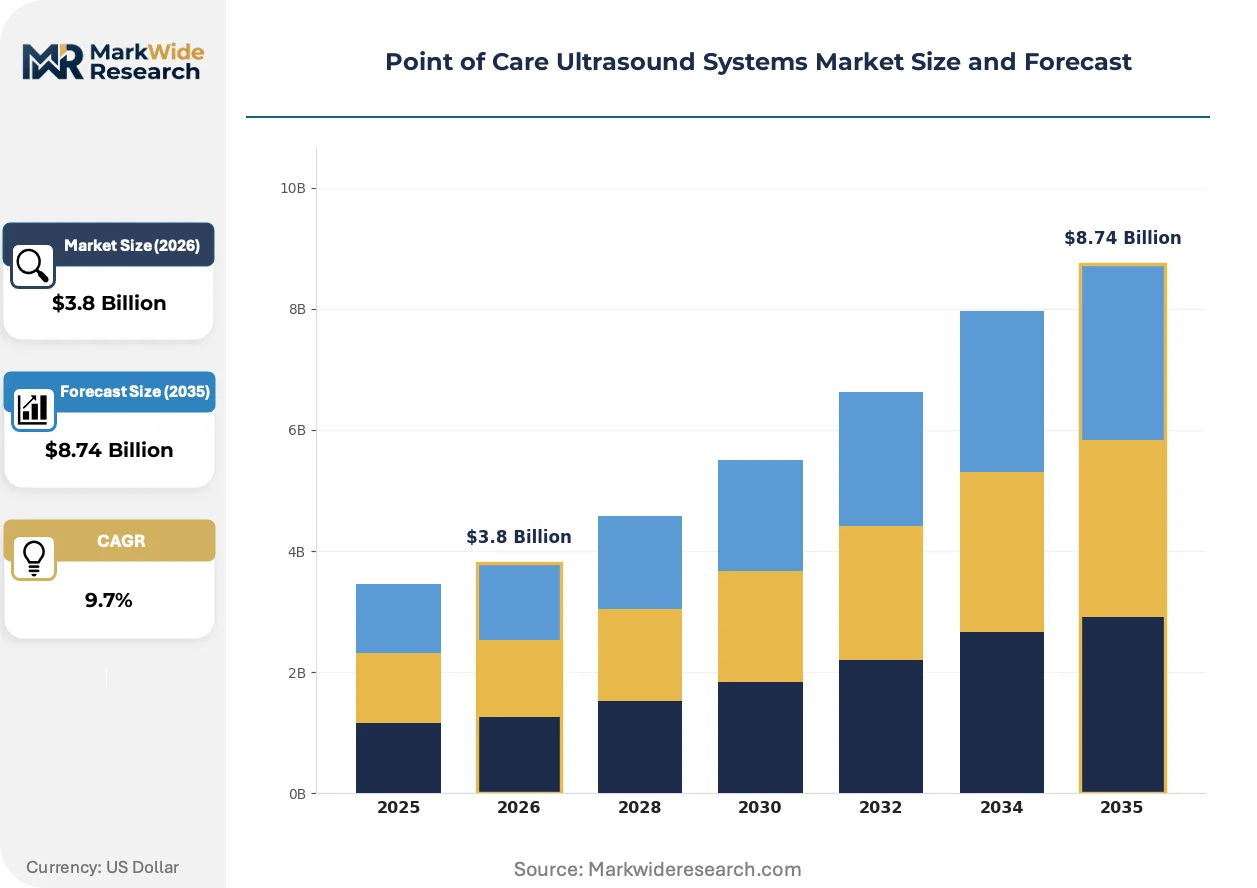
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Systems, Handheld Devices, Mobile Units, Console Systems Delivery Mode: On-Site Testing, Remote Monitoring, In-Hospital Use, Emergency Services End User: Clinics, Hospitals, Urgent Care Centers, Emergency Departments Application: Cardiology, Obstetrics, Emergency Medicine, Critical Care |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, FUJIFILM Sonosite, Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Butterfly Network, Inc., Samsung Medison Co., Ltd., Esaote SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care Ultrasound Systems Market Trends and Innovations
Three intersecting forces are restructuring how point-of-care ultrasound capabilities reach clinical settings: silicon architecture substitution, regulatory pathway bifurcation for AI features, and procurement centralization through buying consortiums.
Single-probe semiconductor architectures are collapsing the historical trade-off between image quality and device portability. CMOS-based beamforming eliminates discrete crystal arrays, enabling full diagnostic functionality at sub-console price points. Emergency departments and rural clinics are adopting these systems for rapid deployment where radiology suite access is impractical.
FDA 510(k) premarket notification refinements for AI-enabled features are compressing product development timelines while elevating algorithm validation requirements. Device manufacturers must now demonstrate clinical equivalence for machine learning components alongside hardware safety. This regulatory evolution most affects handheld system developers targeting rapid bedside diagnostic deployment.
Buying consortiums are consolidating procurement decisions across integrated delivery networks, narrowing direct-to-hospital sales channels. Group purchasing organizations now standardize imaging protocols and vendor selection across multi-site systems, displacing individual department purchasing autonomy. This concentration is most visible in United States health systems pursuing enterprise-scale equipment standardization.
Point of Care Ultrasound Systems Market Segmentation
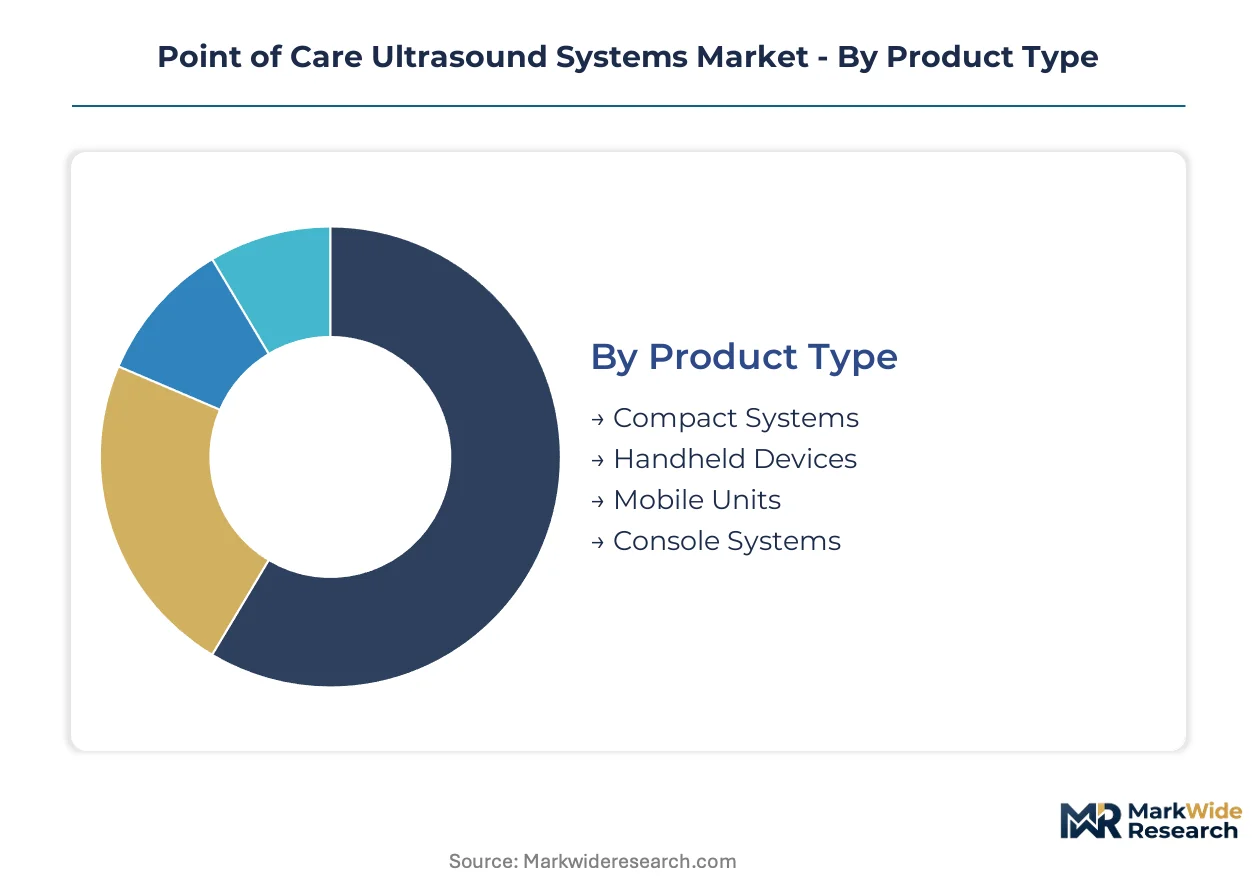
Point of care ultrasound systems fragment across four intersecting dimensions that determine procurement velocity, pricing power, and service attach rates. Product architecture and delivery mode shape capital expenditure cycles, while end user concentration and clinical application dictate training requirements and software subscription potential.
Product Type:
Replacement cycles vary dramatically across form factors, with handheld devices turning over every 3-4 years versus 7-10 year lifespans for console installations.
- Handheld Devices:Semiconductor-based single-probe architectures eliminate discrete crystal arrays, enabling probe-to-smartphone connectivity at price points accessible to individual clinicians. Emergency departments in United States hospital networks are deploying these for rapid triage where radiology suite access creates bottlenecks.
- Compact Systems:Cart-based units with reduced footprint retain full diagnostic functionality for bedside imaging without dedicated suite infrastructure. Critical care units favor these for intensivist-led protocols where image quality requirements exceed handheld capabilities.
- Mobile Units:Battery-powered systems with transportable carts serve multi-bed ICU rounds and intra-hospital transfers.
- Console Systems:Full-featured platforms with advanced Doppler and elastography capabilities anchor radiology department satellite operations.
Console systems anchor the volume base while handheld devices gain share at the steepest rate.
Delivery Mode:
Service contracts and software attach rates diverge sharply between stationary installations and distributed deployment models.
- In-Hospital Use:Fixed installations within dedicated departments command premium service tiers and PACS integration requirements. United States integrated delivery networks standardize these deployments across multi-site imaging protocols.
- Emergency Services:Pre-hospital and ambulance-based deployment demands ruggedized hardware with simplified interfaces for non-specialist operators. FDA 510(k) clearance pathways for these field configurations emphasize rapid startup and automated preset selection.
- On-Site Testing:Point-of-care deployment in outpatient settings prioritizes workflow integration with electronic health record systems.
- Remote Monitoring:Tele-ultrasound applications transmit real-time imaging to centralized specialists, expanding specialist reach into underserved geographies.
In-hospital use generates the recurring revenue base while emergency services deployment expands most quickly.
End User:
Procurement centralization through group purchasing organizations concentrates purchasing power differently across facility types.
- Hospitals:Enterprise-scale health systems negotiate hybrid contracts bundling hardware, software updates, and training subscriptions across standardized vendor portfolios. ISO 13485 certification filters supplier shortlists before RFP consideration.
- Emergency Departments:Standalone purchasing autonomy persists in smaller facilities, though network affiliation increasingly dictates equipment selection. Competency mandates for emergency physicians embed devices into triage workflows.
- Clinics:Ambulatory settings prioritize capital efficiency and rapid depreciation, favoring handheld and compact configurations over console investments.
- Urgent Care Centers:Volume-variable operations demand flexible deployment models with minimal fixed infrastructure commitment.
Hospitals concentrate procurement volume while emergency departments drive standardization fastest.
Application:
Clinical validation requirements and reimbursement pathways create divergent commercial economics across specialties.
- Emergency Medicine:Protocol standardization for FAST exams and vascular access commands the deepest current installed base. Training program accreditation requirements sustain demand for simulator-integrated education packages.
- Critical Care:Intensivist fellowship programs are embedding ultrasound competency into core curricula, widening addressable demand beyond emergency medicine origins. EU MDR clinical evidence requirements for class IIb devices extend approval timelines for new feature introductions.
- Cardiology:Specialized probe requirements and quantitative analysis software elevate price points and service attach rates.
- Obstetrics:Fetal imaging applications face distinct regulatory scrutiny for AI-enabled measurement algorithms.
Emergency medicine anchors the installed base while critical care applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States health systems where group purchasing organizations negotiate enterprise contracts, while European procurement fragments across national reimbursement regimes. Semiconductor supply constraints hit East Asian manufacturing clusters hardest. Regulatory divergence between FDA 510(k) pathways and EU MDR timelines reshapes regional product launch sequencing.
United States
Integrated delivery networks consolidate procurement across multi-site hospital systems, mandating point-of-care ultrasound competency for emergency physicians. FDA 510(k) clearance refinements for AI-enabled features compress development timelines while elevating validation requirements. The Boston-Cambridge corridor anchors semiconductor innovation for probe-to-smartphone architectures.
Germany
University hospital networks drive standardization of intensivist ultrasound training protocols across critical care departments. EU MDR class IIb clinical evidence requirements extend approval timelines for new diagnostic imaging features. The Baden-Württemberg industrial cluster concentrates precision manufacturing for compact system components.
China
Domestic hospital tier expansion accelerates demand for cost-optimized handheld devices in county-level facilities. NMPA regulatory harmonization with international standards streamlines market entry for multinational manufacturers. The Yangtze River Delta manufacturing belt scales CMOS sensor fabrication for ultrasound-on-a-chip production.
Japan
Aging population demographics intensify demand for bedside diagnostic capabilities in long-term care facilities. PMDA streamlined review pathways for software-as-medical-device classifications accelerate AI algorithm deployment. The Kanto region's Tokyo-Osaka corridor concentrates R&D investment in miniaturized probe technologies.
United Kingdom
NHS procurement frameworks centralize equipment standardization across regional hospital trusts. MHRA post-Brexit regulatory autonomy enables tailored pathways for AI diagnostic device registration. The Oxford-Cambridge-London golden triangle anchors digital health innovation clusters for tele-ultrasound applications.
Point of Care Ultrasound Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying semiconductor and sensor modules. The vendor base concentrates around three strategic tiers: diversified medical imaging conglomerates with radiology installed bases, handheld device specialists leveraging semiconductor miniaturization, and regional equipment manufacturers competing on capital efficiency. Dominant competitive moves include hybrid contract bundling of hardware with software subscriptions and cross-selling into emergency department networks.
Within the diversified imaging tier, GE HealthCare, Koninklijke Philips N.V., and Siemens Healthineers exemplify platform integrators leveraging legacy radiology relationships to anchor point-of-care expansion. These Netherlands-based, German, and US corporations occupy positions where installed base density enables bundled service contracts across multi-site health systems. Their scale supports ISO 13485 certification maintenance and enterprise-grade PACS integration capabilities that filter smaller competitors from procurement shortlists.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| FUJIFILM Sonosite, Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Butterfly Network, Inc. |
| Samsung Medison Co., Ltd. |
| Esaote SpA |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in East Asian CMOS foundries is tightening component availability for handheld probe manufacturers while simultaneously elevating pricing leverage for certified suppliers serving United States hospital networks. This utilization squeeze propagates through procurement timelines, compressing margins for non-integrated device assemblers while concentrating premium pricing power with vendors maintaining captive semiconductor supply.
Pricing Analysis
The customization-premium spread separates configured-to-order console systems from standard handheld configurations, with pricing stratifying across premium, standard, and economy tiers based on FDA 510(k) clearance tier and ISO 13485 certification status. Subscription-based bundling of hardware with software updates and training subscriptions commands recurring revenue premiums from integrated delivery networks. Pricing pressure stems from group purchasing organization consolidation across United States health systems, which standardizes vendor selection and compresses per-unit margins. Emergency departments exhibit highest price sensitivity due to volume-variable triage workflows, while critical care units demonstrate lowest sensitivity given intensivist-led protocol requirements.
Supply Chain Analysis
Supplier-financing facilities from East Asian foundries are extending payment terms to sustain fab utilization, though CMOS sensor supply concentration in Taiwan, South Korea, and China creates structural vulnerability. Ultrasound-on-a-chip architectures draw from advanced semiconductor fabrication, discrete crystal arrays, and battery cell modules. Single-source dependency for sub-10nm CMOS nodes exposes manufacturers to tariff exposure from geopolitical trade restrictions. Distribution runs through group purchasing organization networks and direct-to-hospital contracts, with enterprise-scale service infrastructure filtering smaller competitors from procurement shortlists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point of care ultrasound systems market is entering a cyclical recovery phase driven by emergency medicine protocol standardization mandates across United States hospital networks. Capital expenditure normalization following supply chain disruptions is releasing pent-up replacement demand for handheld and compact configurations.
For Market Incumbents: Pre-empt semiconductor supply constraints through backward integration into CMOS sensor fabrication or long-term offtake agreements with Taiwan and South Korean foundries. Defend installed base positions by embedding AI-enabled diagnostic algorithms into firmware updates, creating switching costs for emergency departments already standardized on existing platforms. Channel control through hybrid contracts bundling hardware, software, and training subscriptions filters emerging competitors from group purchasing organization shortlists.
For New Entrants and Emerging Players: Build out tele-ultrasound capabilities targeting rural clinic networks and urgent care centers where radiologist availability constraints create white-space opportunity. County-level hospitals in China's domestic tier expansion represent the most penetrable geography, with cost-optimized handheld devices satisfying capital efficiency requirements. A software-first go-to-market angle emphasizing AI diagnostic algorithm differentiation bypasses hardware scale disadvantages against established radiology equipment conglomerates.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across handheld device manufacturing as semiconductor miniaturization collapses probe-to-smartphone cost structures. The five-to-ten year viability window favors acquisition targets with FDA 510(k) cleared AI algorithms and established group purchasing organization relationships over pure hardware assemblers. The signal to monitor is EU MDR approval timeline compression for class IIb diagnostic imaging devices, which would validate clinical evidence investment strategies and accelerate European market entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Features | Accelerates bedside diagnostic deployment timelines while elevating algorithm validation requirements for handheld systems. |
| Hospital System Partnership | Secures enterprise-scale procurement contracts across multi-site integrated delivery networks with standardized imaging protocols. |
| Software Companion Development | Enables probe-to-smartphone connectivity with automated preset selection for non-specialist operators in emergency services. |
| CE Marking Pathway | Unlocks European critical care segments facing extended EU MDR class IIb clinical evidence approval timelines. |
| Reimbursement Strategy | Aligns point-of-care ultrasound protocols with CMS Medicare coding for intensivist-led procedures in ICU settings. |
Research Methodology
Operator-level perspectives from emergency department physicians, critical care intensivists, hospital purchasing committee chairs, group purchasing organization contract managers, and biomedical engineering directors anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) premarket notification databases, EU MDR submission records, hospital procurement databases, and GPO contract repositories. Bottom-up unit economics modeling triangulated against top-down health system expenditure analysis across the projection horizon.
Scenario-bracketing around semiconductor supply disruption severity and regulatory pathway bifurcation framed the analytical envelope. Segmentation dimensions spanned product architecture, delivery mode, end user concentration, and clinical application intensity. CAGRs derived from installed base turnover rates, replacement cycle compression, and protocol standardization velocity across emergency medicine and critical care fellowship programs. Forecast inputs incorporated AI algorithm classification uncertainty between software-as-medical-device and embedded hardware pathways.
Stress conditions across CMOS foundry utilization rates, EU MDR clinical evidence requirement stringency, and group purchasing organization consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding semiconductor miniaturization trajectories and reimbursement pathway stability. Macroeconomic contraction affecting hospital capital budgets, regulatory reclassification of AI diagnostic algorithms, or supply chain regionalization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Animal Ultrasound Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Global Pupillometer Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Dysphagia Management Market
Medical Devices
C-Arms Devices Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market