
 Handheld Ultrasound Scanners Market | 2026-2036
Handheld Ultrasound Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Ultrasound Scanners Market Outlook
The EU Medical Device Regulation is consolidating procurement standards across European healthcare networks, compelling manufacturers to recertify legacy platforms. GE HealthCare leverages its installed base of premium cart-based systems to cross-sell handheld units into hospital satellite clinics. Butterfly Network anchors its position through proprietary semiconductor fabrication of ultrasound-on-chip architectures.
Handheld ultrasound scanners are battery-powered, probe-sized imaging devices operating at 2-15 MHz frequencies, designed for real-time anatomical visualization at the point of care without fixed infrastructure. Portable and wireless product types command the highest volume as rural health posts and athletic training facilities prioritize mobility over advanced modalities. AI-enhanced technology segments capture disproportionate margin pools as machine learning algorithms automate cardiac ejection fraction calculations and lung B-line quantification.
FDA 510(k) premarket notification, EU MDR conformity assessment, and ISO 13485 quality management standards collectively govern device safety, software validation, and post-market surveillance obligations. These frameworks elevate barriers for entrants lacking clinical evidence libraries while rewarding incumbents with predicate device pathways. Stakeholders must weigh regulatory capital requirements against the strategic imperative of securing national health system tenders before competitor lock-in solidifies.
Market Dynamics
Point-of-care decentralization is compressing diagnostic workflows from radiology suites to bedside examinations, forcing equipment vendors to reengineer imaging hardware for untrained operators and unstructured clinical environments.
Growth Catalysts
- EU MDR recertification waves:Consolidated procurement standards across German, French, and Italian hospital networks are disqualifying non-compliant legacy suppliers, opening tender windows for certified handheld platforms.
- Emergency medicine adoption:Trauma bays in US academic medical centers now mandate portable ultrasound for FAST examinations, creating institutional pull-through into satellite clinics.
- Semiconductor miniaturization:Proprietary ultrasound-on-chip architectures are collapsing probe head dimensions while preserving image fidelity at 5-12 MHz frequencies.
Market Restraints
- CMOS sensor supply concentration:Taiwan-based foundries control critical semiconductor fabrication capacity for ultrasound transducer arrays, exposing OEMs to single-source vulnerability.
- FDA 510(k) predicate device requirements:New entrants lacking established predicate pathways face extended clinical validation timelines and submission costs.
- Cart-based system substitution:Premium hospital systems retain installed bases of wheeled ultrasound platforms with superior Doppler sensitivity for cardiac applications.
Strategic Opportunities
- Rural health post penetration:India's Ayushman Bharat network is equipping 150,000 primary health centers with diagnostic tools, creating volume demand for battery-operated imaging.
- Athletic training facility integration:Professional sports franchises in Germany and the United States are deploying handheld units for on-field musculoskeletal assessment.
- AI Act compliance positioning:EU-based manufacturers embedding machine learning for automated measurements can leverage conformity assessment as a competitive differentiator.
Industry Challenges
- Image interpretation skill gaps:Point-of-care operators in emergency departments require structured training programs to achieve diagnostic competency comparable to credentialed sonographers.
- ISO 13485 quality system maintenance:Continuous software update cycles for AI-enhanced algorithms trigger recurring audit obligations and documentation burdens.
- Legacy PACS integration friction:Hospital information systems demand DICOM compliance and cybersecurity protocols that strain wireless transmission architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Ultrasound Scanners Market |
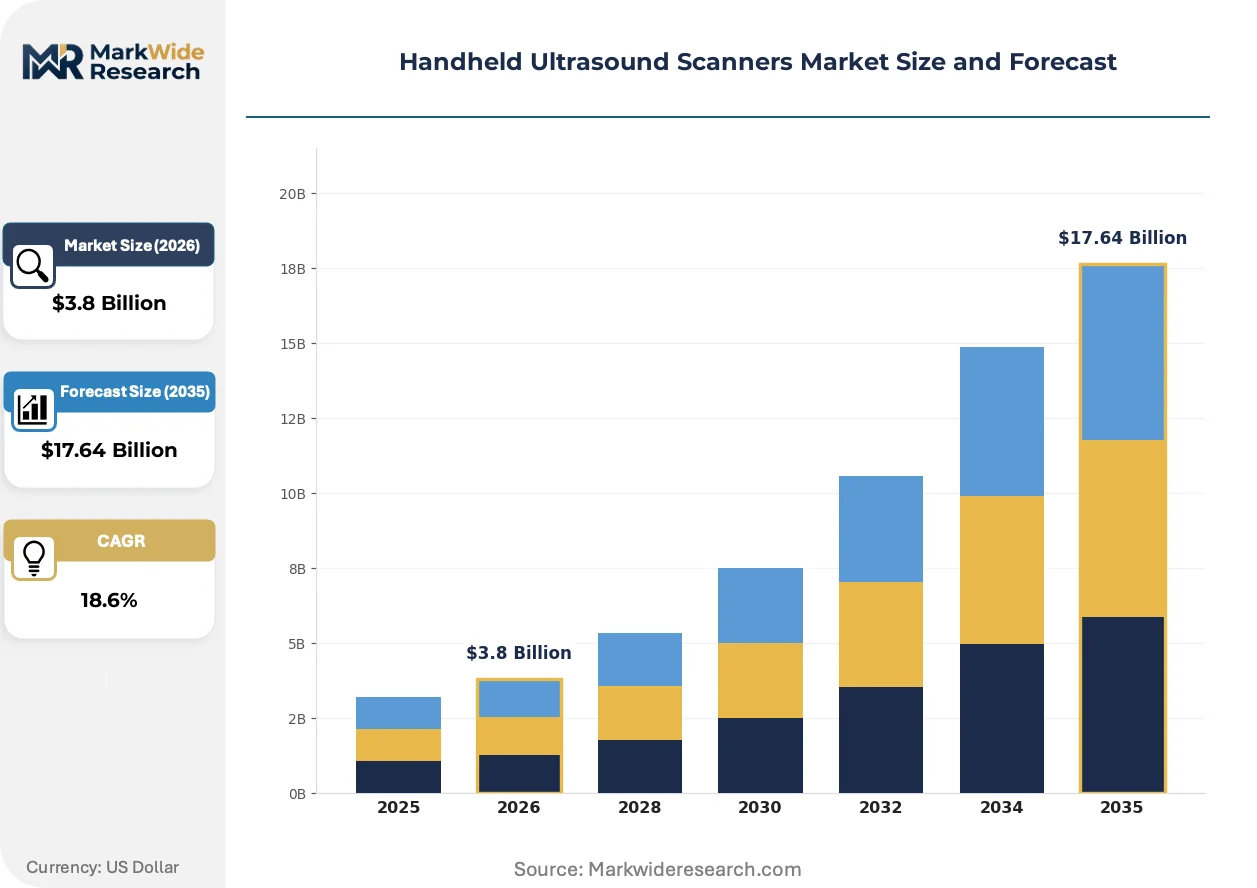
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wireless, Compact, Multifunctional Technology: Digital Imaging, AI-Enhanced, Doppler, 3D Imaging End User: Ambulatory Surgical Centers, Home Care, Urgent Care, Diagnostic Clinics Application: Cardiology, Obstetrics, Emergency Medicine, Musculoskeletal |
| Companies Covered | Clarius Mobile Health, Canon Medical Systems, GE HealthCare, Fujifilm, Siemens Healthineers, Philips, Samsung Medison, Exo, Butterfly Network, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Ultrasound Scanners Market Strategic Shifts
Artificial intelligence is embedding directly into probe hardware, automating anatomical recognition and measurement workflows that previously required specialist interpretation.
Capacitive micromachined ultrasound transducers are expanding into cardiac imaging applications where traditional piezoelectric arrays dominated. Pediatric cardiologists in US children's hospitals are adopting CMUT-enabled probes for neonatal echocardiography without sedation. The technology is expanding into price-sensitive segments previously blocked by transducer cost floors.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data for software-as-medical-device components. This obligation compresses product update cycles and elevates documentation costs. German notified bodies are experiencing backlog delays that extend conformity assessment timelines.
Subscription-based equipment access is displacing capital purchase models in US outpatient clinic chains. Per-procedure pricing aligns costs with utilization, reducing stranded asset risk for low-volume sites. Anesthesia groups in ambulatory surgery centers are driving this shift through equipment-as-a-service arrangements.
Handheld Ultrasound Scanners Market Segmentation
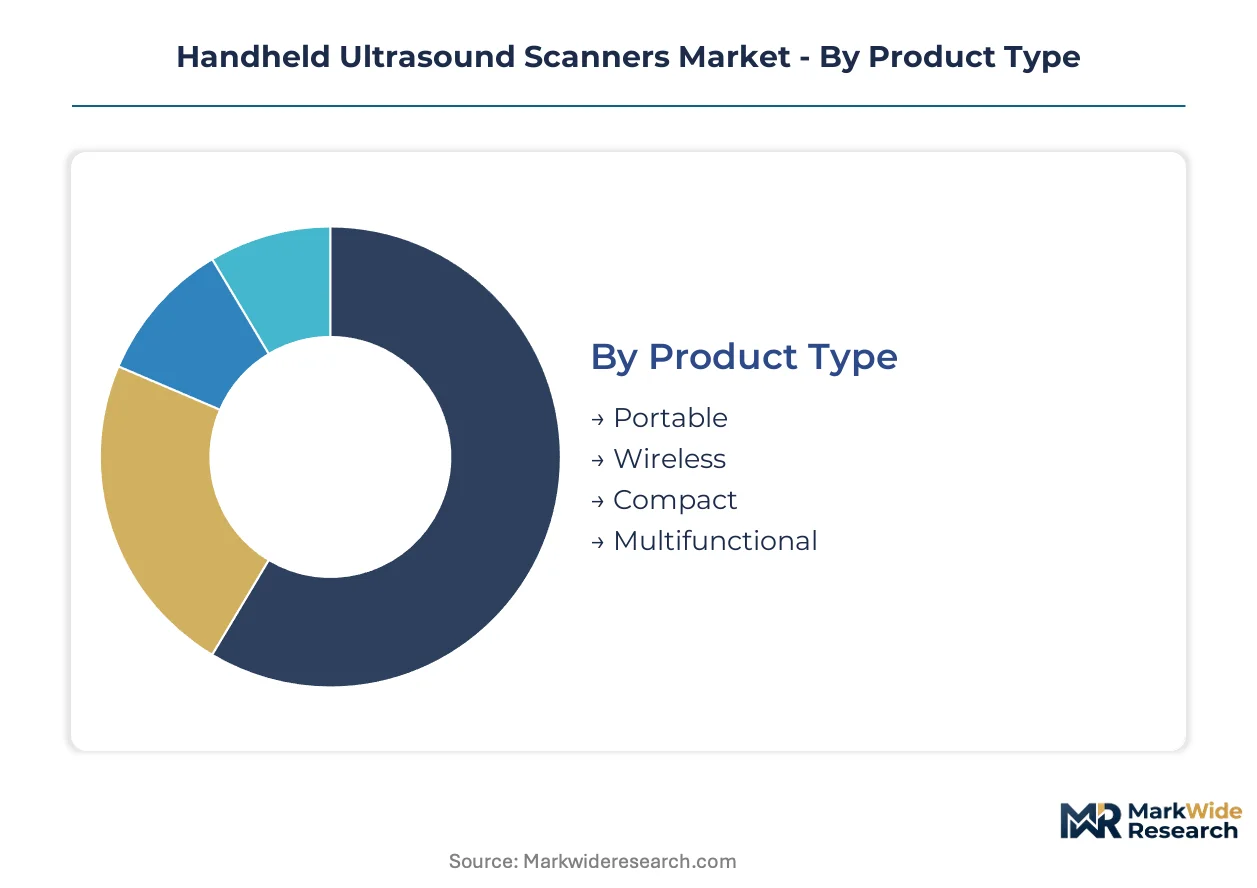
Handheld ultrasound scanner segmentation reveals how hardware configurations, software capabilities, and clinical settings create distinct margin profiles. Manufacturers must align R&D investments with the integration depth each segment demands.
Product Type:
Portable units operate as standalone imaging workstations, while wireless and compact variants embed into broader telemedicine and mobile health ecosystems.
- Portable:Battery-powered devices with integrated displays and onboard storage, typically weighing under 2 kg. Emergency departments in US academic medical centers standardize on these units for FAST examinations, creating procurement pull-through into satellite clinics.
- Wireless:Probe-only hardware transmitting to tablets or smartphones via Bluetooth or Wi-Fi. German outpatient clinic chains favor this architecture for its minimal infrastructure footprint and seamless PACS integration.
- Compact:Stripped-down units with reduced feature sets for price-sensitive deployment. India's Ayushman Bharat primary health centers specify these for basic obstetric screening.
- Multifunctional:Hybrid platforms combining ultrasound with ECG, pulse oximetry, or digital stethoscope capabilities. Athletic training facilities in the United States deploy these for comprehensive sideline assessment.
Volume placements concentrate in Portable; the faster expansion belongs to Wireless.
Technology:
Technology tiers separate commodity imaging from premium diagnostic automation, with AI-enhanced platforms commanding pricing multiples over conventional digital systems.
- Digital Imaging:Conventional beamforming and signal processing without machine learning augmentation. Cost-conscious diagnostic clinics in Germany and France default to this tier for standard anatomical surveys.
- AI-Enhanced:Embedded algorithms automating cardiac ejection fraction calculations, lung B-line quantification, and anatomical landmark detection. FDA 510(k) clearance pathways for these software-as-medical-device components are streamlining product introductions.
- Doppler:Spectral and color flow mapping for vascular and cardiac hemodynamic assessment. Cart-based substitution risk is highest here, as premium hospital systems retain wheeled platforms for superior sensitivity.
- 3D Imaging:Volumetric reconstruction from mechanical or matrix array scanning. Obstetric applications in US maternal-fetal medicine practices drive selective adoption despite computational overhead.
Digital Imaging dominates current installed base; AI-Enhanced is climbing the fastest as FDA and EU MDR frameworks mature for algorithm-based diagnostics.
End User:
End-user segmentation tracks the decentralization of diagnostic capacity from centralized radiology departments to distributed care settings.
- Ambulatory Surgical Centers:Anesthesia groups in US outpatient chains drive equipment-as-a-service arrangements with per-procedure pricing. Subscription models align costs with utilization and reduce stranded asset risk.
- Home Care:Post-acute and hospice settings requiring minimal training for non-specialist operators. Reimbursement fragmentation across US state Medicaid programs constrains penetration.
- Urgent Care:Retail health clinics and freestanding emergency facilities prioritizing rapid triage. Musculoskeletal and soft-tissue applications dominate this channel.
- Diagnostic Clinics:Dedicated imaging centers performing higher-volume, credentialed examinations. ISO 13485 quality system maintenance burdens weigh heaviest here due to continuous software update cycles.
Diagnostic Clinics capture the highest procedure volumes; Urgent Care is expanding most quickly as retail health footprints multiply.
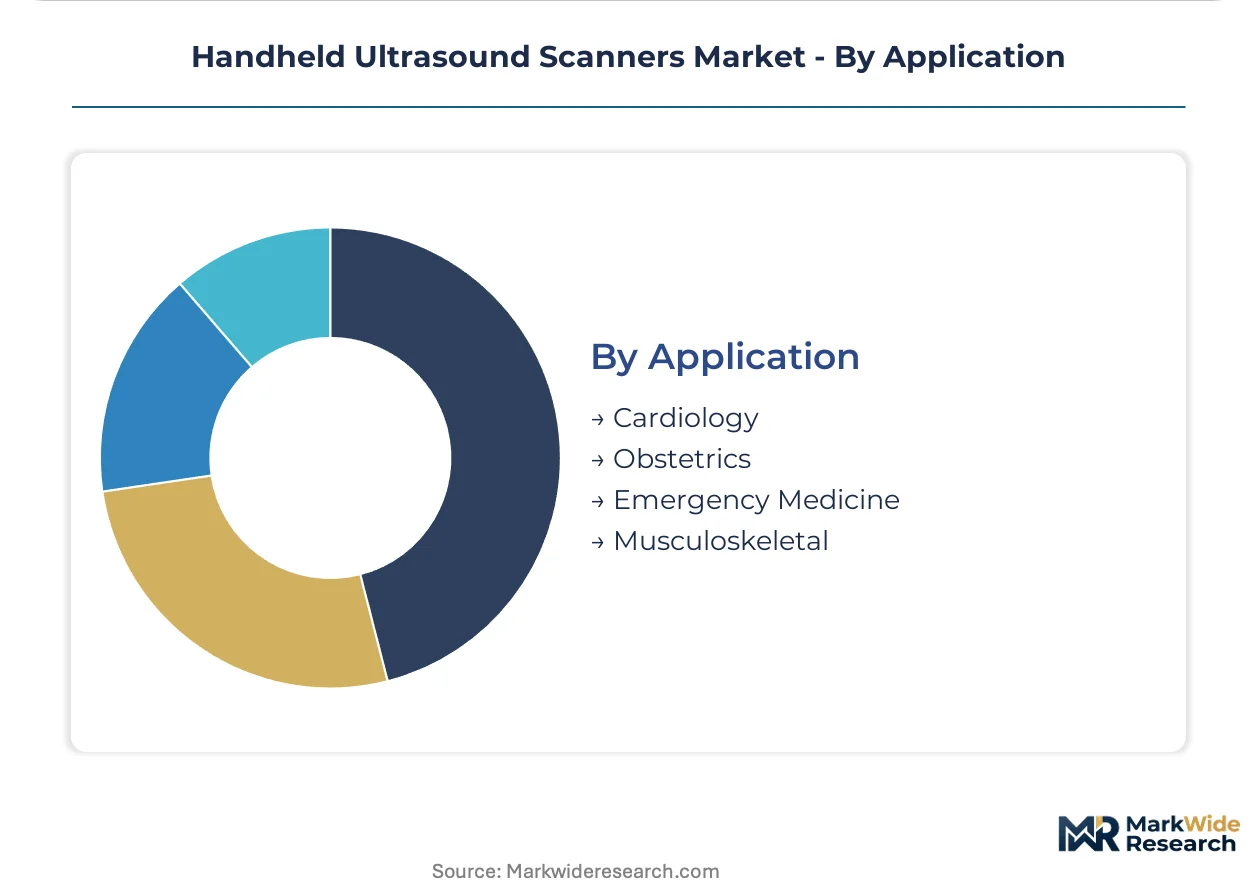
Application:
Application segmentation reflects how handheld hardware must adapt to anatomical depth, motion tolerance, and measurement precision requirements.
- Cardiology:Demands Doppler sensitivity and automated functional measurements. CMUT-enabled probes are penetrating neonatal echocardiography in US children's hospitals where sedation avoidance is paramount.
- Obstetrics:Requires biometric precision for fetal growth monitoring. India's primary health network specifications prioritize this application for maternal screening programs.
- Emergency Medicine:Trauma bay standardization for FAST, lung, and vascular access. US academic medical center mandates are institutionalizing training pathways for untrained operators.
- Musculoskeletal:Superficial imaging with high-frequency transducers. Professional sports franchises in Germany deploy handheld units for on-field tendon and ligament assessment.
Emergency Medicine leads current placements; Cardiology is gaining share fastest as semiconductor miniaturization preserves image fidelity at reduced probe dimensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors semiconductor innovation for ultrasound-on-chip architectures, while FDA clearance pathways in the United States accelerate product introductions ahead of European notified body backlogs.
United States
Emergency medicine departments at Johns Hopkins and Mayo Clinic satellite networks mandate portable ultrasound for FAST examinations, institutionalizing bedside diagnostic workflows. FDA 510(k) premarket notification pathways streamline AI-enhanced imaging clearances for algorithm-based cardiac measurements. The Research Triangle in North Carolina clusters semiconductor fabrication for capacitive micromachined ultrasound transducers.
Germany
Outpatient clinic chains in Bavaria and North Rhine-Westphalia prioritize wireless probe architectures for minimal infrastructure footprints in decentralized care settings. EU MDR Article 10 clinical evaluation requirements compress software update cycles for manufacturers seeking notified body recertification. Berlin-Brandenburg hosts conformity assessment backlog delays extending tender windows for compliant handheld platforms.
China
NMPA regulatory harmonization with international standards accelerates domestic approvals for AI-embedded imaging devices targeting primary health networks. The Yangtze River Delta manufacturing corridor concentrates semiconductor foundry capacity for ultrasound transducer arrays at Taiwan-dependent fabrication nodes. Shenzhen technology zones prototype compact units for rural health post specifications under national decentralization programs.
India
Ayushman Bharat network procurement equips 150,000 primary health centers with battery-operated obstetric screening tools, creating volume demand for stripped-down compact variants. CDSCO medical device registration requirements align with ISO 13485 quality management standards for software validation obligations. Karnataka's Bengaluru medical technology corridor assembles cost-optimized platforms for maternal-fetal medicine applications.
Handheld Ultrasound Scanners Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with installed base leverage over pure-play handheld specialists. Three archetypes dominate: premium cart-based system vendors cross-selling portable units into satellite clinics, semiconductor-integrated probe manufacturers with proprietary fabrication capabilities, and AI-native entrants embedding automated measurement algorithms. Incumbents defend position through predicate device regulatory pathways and national health system tender lock-in, while challengers pursue rural health post penetration and athletic training facility integration.
Within the diversified conglomerate tier, GE HealthCare and Siemens Healthineers occupy positions anchored by legacy premium ultrasound installed bases that enable cross-selling into decentralized care settings. Philips and Canon Medical Systems exemplify portfolio breadth spanning cart-based platforms through wireless probe architectures. Butterfly Network and Clarius Mobile Health represent the semiconductor-integrated and AI-native archetypes respectively, with Exo sitting within the algorithm-automation specialist category targeting point-of-care operators.
| Leading Market Players |
|---|
| Clarius Mobile Health |
| Canon Medical Systems |
| GE HealthCare |
| Fujifilm |
| Siemens Healthineers |
| Philips |
| Samsung Medison |
| Exo |
| Butterfly Network |
| Others |
Value Chain & Pricing Dynamics
Emergency medicine procurement mandates at US academic medical centers are compressing vendor margins as hospitals demand per-procedure subscription models and AI-enhanced software bundles, forcing OEMs to absorb semiconductor cost volatility while repositioning hardware as loss-leading platform entry points.
Pricing Analysis
Value-based pricing anchored to diagnostic throughput and clinical outcome metrics dominates procurement negotiations for AI-enhanced platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared algorithm suites from basic digital imaging and stripped-down compact variants. Pricing pressure stems from India's Ayushman Bharat volume tenders specifying sub-$500 unit costs for primary health center deployment. Diagnostic clinics in Germany exhibit lowest price sensitivity, prioritizing ISO 13485 certification and PACS integration over hardware acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan's Hsinchu Science Park and South Korea's Giheung cluster are elevating CMOS foundry lead times for ultrasound transducer arrays. Semiconductor fabrication draws from Taiwan-based TSMC and Samsung Foundry nodes, with probe assembly concentrating in China's Yangtze River Delta and Mexico's Tijuana medical device corridor. Single-source vulnerability in Taiwan-based foundry capacity exposes OEMs to geopolitical disruption risk. Distribution runs through hospital GPO contracts in the United States, outpatient clinic chains in Germany, and government procurement portals in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification waves and FDA 510(k) predicate pathway consolidation are accelerating competitive exits, rewarding scaled incumbents with compliance infrastructure and clinical evidence libraries while marginalizing undercapitalized challengers.
For Market Incumbents: To counter semiconductor supply concentration and foundry pricing power, secure captive wafer allocation through long-term supply agreements with Taiwan-based foundries. Deepen backward integration into CMUT fabrication through acquisition of MEMS specialists in Greater Boston's Research Triangle corridor. Prioritize EU MDR notified body relationship investment to compress conformity assessment timelines ahead of competitor recertification backlogs. For New Entrants and Emerging Players: Athletic training facility partnerships offer lowest barrier-to-entry channel for algorithm-automation specialists seeking proof-of-concept deployment outside hospital procurement rigor. India's Ayushman Bharat primary health network specifications for compact obstetric screening units present the most penetrable volume opportunity. Pursue CDSCO registration alignment with ISO 13485 standards to qualify for national health system tenders before incumbent lock-in solidifies. For Investors and Strategic Acquirers: The window for entry favors semiconductor-integrated probe manufacturers with proprietary ultrasound-on-chip architectures and established FDA predicate pathways. Long-term viability hinges on regulatory moat depth and national tender penetration across US, German, and Indian health systems. Monitor EU MDR notified body backlog resolution as inflection signal for recertification capacity normalization and competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates AI-enhanced imaging introductions ahead of EU MDR notified body backlogs. |
| CE Marking Pathway | Unlocks German outpatient clinic chain procurement and EU health network tenders. |
| Hospital System Partnership | Institutionalizes bedside ultrasound workflows through emergency medicine department mandates. |
| Software Companion Development | Automates cardiac ejection fraction and lung B-line measurements for untrained operators. |
| Reimbursement Strategy | Aligns per-procedure pricing with US ambulatory surgery center utilization patterns. |
Study Parameters
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data underwrites the qualitative findings in this analysis. Primary interviews with emergency medicine physicians, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) premarket notification filings, EU MDR notified body conformity assessment records, and CDSCO medical device registration databases. Bottom-up unit shipment modeling and top-down health system expenditure triangulation cross-validate segment-level estimates.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix shift effects. Segmentation dimensions modeled include product type, technology tier, end-user setting, clinical application, and regional regulatory cluster. CAGRs derive from logistic adoption curve fitting for AI-enhanced platforms and linear extrapolation for mature digital imaging tiers. Forecast inputs incorporate semiconductor foundry capacity expansion announcements and national health system decentralization program procurement schedules.
Caveats apply where EU MDR notified body backlog resolution, Taiwan foundry geopolitical disruption, or NMPA regulatory harmonization delays could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
South America MRI Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Mammography Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market