
 Global Artificial Intelligence in MRI Market | 2026-2036
Global Artificial Intelligence in MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence in MRI Market Foresight
Deep learning integration into MRI reconstruction pipelines is tilting vendor competition toward real-time inference architectures. Siemens Healthineers anchors its position through proprietary raw-data acquisition protocols that lock in scanner-to-algorithm compatibility. GE Healthcare leverages its installed base of magnetic resonance systems to distribute AI modules through cloud-enabled service contracts. Subtle Medical differentiates via vendor-agnostic deployment, allowing its denoising algorithms to run across multi-manufacturer imaging fleets without hardware retrofit.
Artificial intelligence in MRI encompasses algorithmic systems that process k-space data, reconstructed images, or radiological reports to enhance diagnostic accuracy, compress scan times, or automate clinical workflows. These systems typically employ convolutional neural networks trained on annotated DICOM datasets, with inference latency requirements under thirty seconds for intra-procedural deployment. Deep learning architectures currently dominate commercial deployments, particularly in image reconstruction where they recover signal from undersampled acquisitions. Automated reporting tools represent the fastest-expanding application segment, as natural language processing engines convert structured imaging findings into draft clinical narratives, concentrating margin pools in hospital enterprise contracts. Workflow optimization solutions remain comparatively mature, with most value captured through queue management and protocol selection rather than interpretive assistance.
The FDA's software-as-a-medical-device framework predicates market access on predefined change control plans, while the EU AI Act imposes conformity assessment obligations for clinical decision support tools above minimal risk tiers. China's NMPA maintains separate registration pathways for AI-assisted diagnostic software, requiring multi-center validation studies that extend commercialization timelines. Stakeholders must monitor evolving reimbursement codes for AI-enhanced radiology reads, as payer acceptance will determine whether deployment economics favor point solutions or integrated platform subscriptions.
Market Dynamics
Deep learning architectures are compressing MRI scan durations from forty minutes to under ten minutes, forcing hardware vendors to reconfigure raw-data pipelines for algorithmic compatibility rather than purely signal-to-noise optimization.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The FDA's predefined change control plans accelerate iterative algorithm updates without full resubmission, reducing commercialization friction for reconstruction software developers.
- Convolutional Neural Network Maturation:Training datasets exceeding 100,000 annotated DICOM studies now enable diagnostic-grade performance in automated lesion detection, pulling hospital capital allocation toward AI-enhanced radiology suites.
- German Reimbursement Pathways:Germany's EBM billing codes for computer-assisted image interpretation create direct revenue attribution for AI deployment, accelerating procurement decisions in tertiary care networks.
Market Restraints
- GPU Compute Cost Volatility:NVIDIA A100 and H100 chip shortages inflate inference infrastructure costs for cloud-hosted AI platforms, compressing margins for vendors without captive silicon supply.
- EU AI Act Conformity Assessment:Clinical decision support tools above minimal risk tiers face notified body evaluation timelines exceeding eighteen months, delaying European commercialization for reconstruction algorithms.
- Legacy PACS Integration Friction:DICOM router incompatibility with modern AI inference architectures forces middleware expenditures that erode two-year ROI projections for hospital procurement committees.
Strategic Opportunities
- India's Diagnostic Imaging Expansion:India's PLI scheme for medical device manufacturing attracts MRI scanner assembly, creating localized demand for AI modules that address tuberculosis and neurodegenerative disease prevalence patterns.
- Natural Language Processing Convergence:Integration of radiology-specific NLP engines with structured reporting templates automates clinical narrative generation, opening enterprise software contracts beyond hardware bundling.
- China NMPA Registration Pathways:Multi-center validation requirements, once cleared, confer exclusivity periods that reward first-movers in liver fibrosis quantification and cardiac function assessment algorithms.
Industry Challenges
- Radiologist-AI Workflow Redesign:Clinical validation of human-in-the-loop protocols demands six-to-twelve-month pilot programs that strain hospital IT resources and delay scale deployment decisions.
- Interoperability Certification Complexity:IHE profiles for AI result transmission lack universal adoption, forcing vendor-specific integration engineering that fragments implementation timelines across health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence in MRI Market |
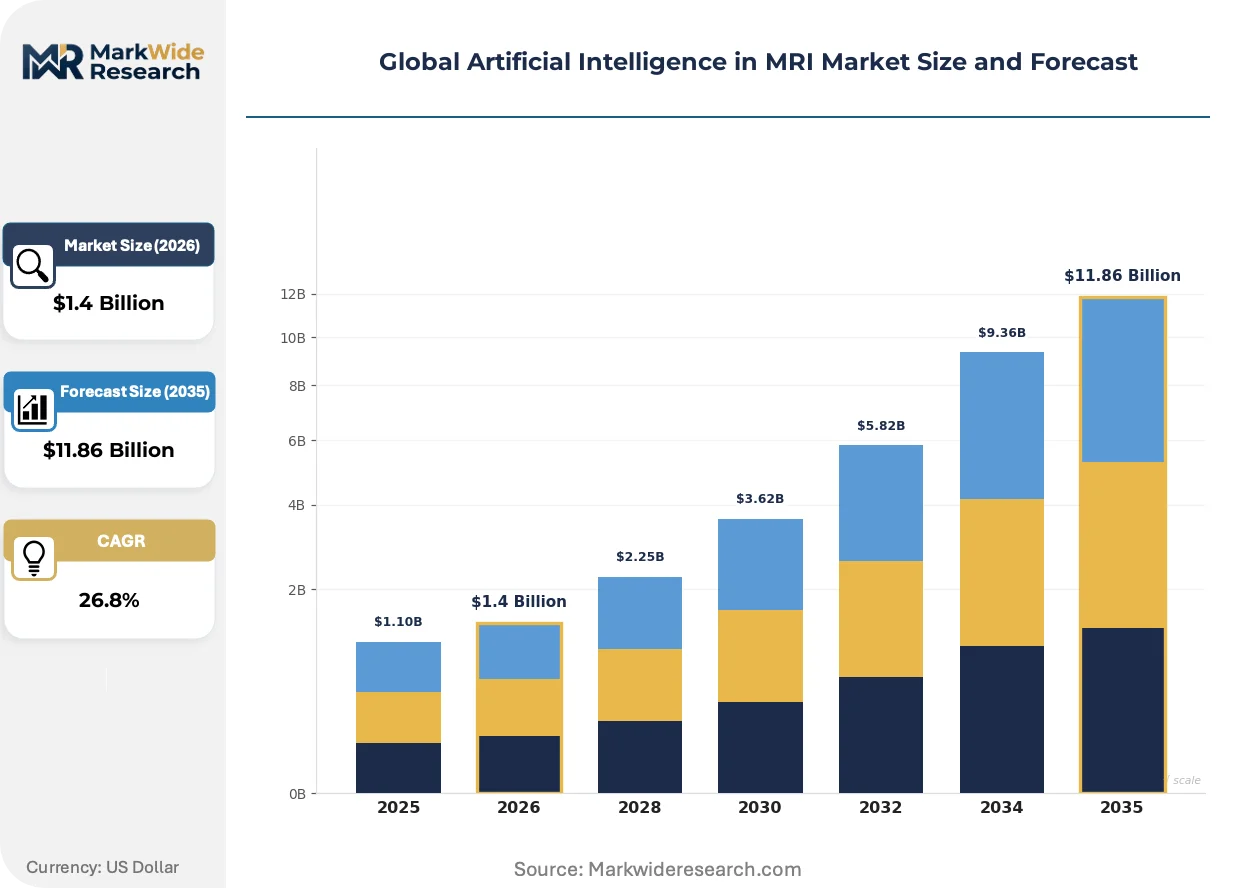
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Image Reconstruction, Automated Reporting, Image Segmentation, Workflow Optimization, Predictive Analysis Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision, Reinforcement Learning Application: Neurological Imaging, Musculoskeletal Imaging, Cardiovascular Imaging, Oncological Imaging, Pediatric Imaging End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics, Academic Centers |
| Companies Covered | Canon Medical Systems Corp, Blackford Analysis, Siemens Healthineers AG, Subtle Medical, Inc., FUJIFILM Holdings Corp, GE Healthcare, Aidoc, Shanghai United Imaging Healthcare Co., Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence in MRI Market Shifts & Advancements
Algorithmic reconstruction is displacing hardware-centric signal acquisition as the primary locus of competitive differentiation, compressing vendor R&D allocation toward software architectures and away from magnet engineering.
Deep learning-based k-space completion is virtualizing the trade-off between scan speed and diagnostic quality. Academic medical centers in the United States and Germany are deploying these algorithms for intraoperative MRI guidance where motion artifact suppression determines surgical outcome. The technology is virtualizing the traditional hardware upgrade cycle, allowing decade-old scanners to produce diagnostic-grade images through computational recovery rather than magnet replacement.
The EU AI Act's risk classification system for clinical decision support tools is reconfiguring vendor regulatory strategies. High-risk algorithm categories now require quality management systems audited by notified bodies, adding €200,000-€400,000 in compliance costs per product line. European hospital procurement committees are prioritizing vendors with established CE marking under the Medical Device Regulation to de-risk long-term service continuity.
Subscription-based AI module licensing is displacing perpetual software licenses in North American hospital contracts. Health systems in the United States are consolidating vendor relationships around platform ecosystems that bundle reconstruction, workflow optimization, and reporting tools under single enterprise agreements. This consolidation concentrates purchasing authority within radiology department chairs and hospital IT procurement officers, reducing point-solution vendor access.
Global Artificial Intelligence in MRI Market Segmentation
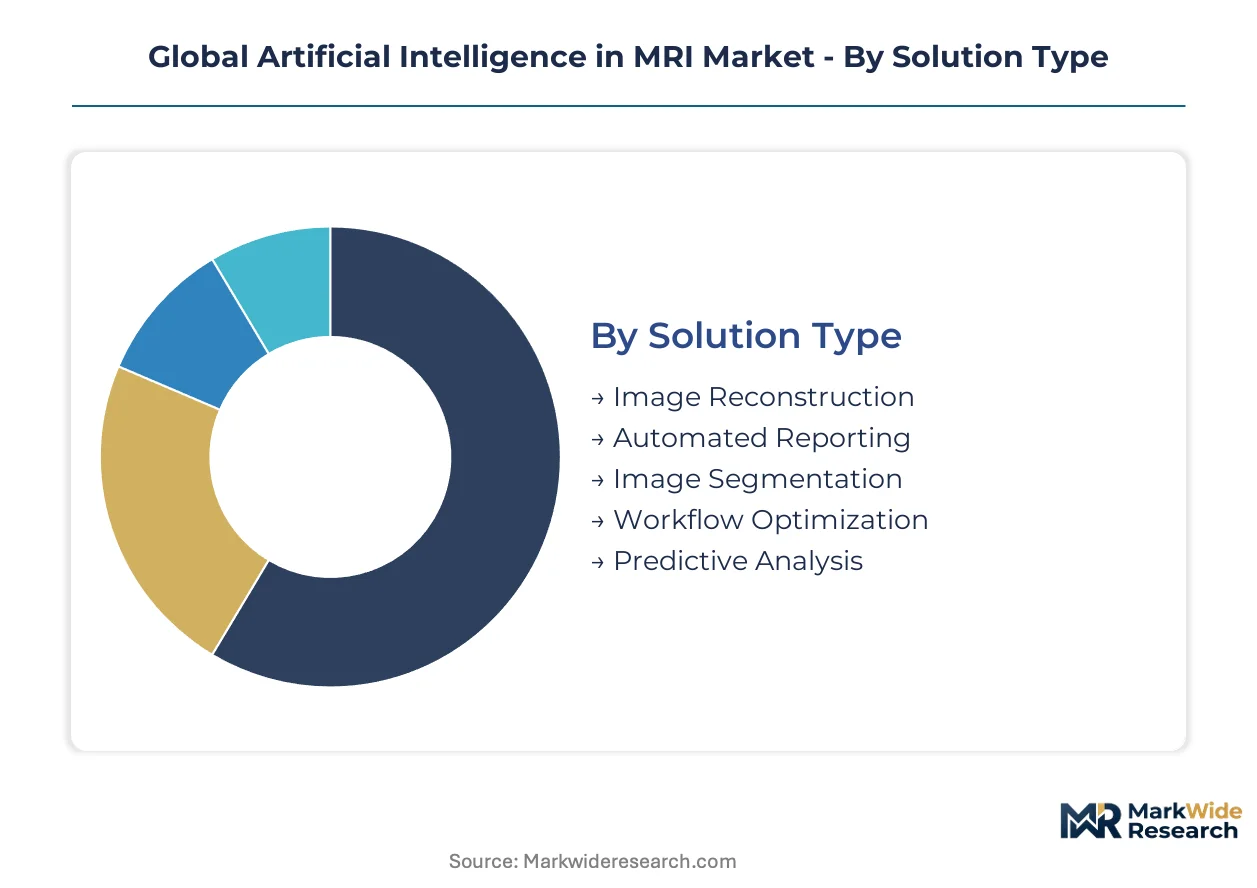
Segmentation reveals how AI value pools concentrate across distinct technical architectures and clinical deployment contexts. Solution types differentiate by latency requirements and regulatory pathway complexity. Technology segments separate by training data intensity and inference infrastructure demands.
Solution Type:
Cost tiers separate algorithmic solutions by development capital intensity and reimbursement eligibility.
- Image Reconstruction:Deep learning architectures recover diagnostic-grade images from undersampled k-space acquisitions, eliminating motion artifacts in cardiac and abdominal protocols. Siemens Healthineers and GE Healthcare embed these algorithms at the scanner level, while Subtle Medical deploys vendor-agnostic cloud inference. Demand concentrates in United States academic medical centers where compressed scan times justify premium pricing against throughput constraints.
- Automated Reporting:Natural language processing engines convert structured DICOM findings into draft clinical narratives, reducing radiologist documentation burden. Germany's EBM billing codes for computer-assisted interpretation create direct revenue attribution, accelerating procurement in tertiary networks. The segment captures the steepest expansion trajectory as health systems consolidate vendor relationships around platform ecosystems.
- Image Segmentation:Convolutional neural networks delineate anatomical structures and pathological regions for volumetric quantification.
- Workflow Optimization:Queue management and protocol selection algorithms prioritize examination scheduling based on clinical urgency and scanner availability.
- Predictive Analysis:Prognostic models forecast disease progression from longitudinal imaging biomarkers.
Image Reconstruction commands the established base. The steepest expansion runs through Automated Reporting.
Technology:
Application maturity determines which architectures dominate commercial deployment versus experimental implementation.
- Deep Learning:Convolutional and transformer architectures trained on annotated DICOM datasets exceeding 100,000 studies enable diagnostic-grade performance in lesion detection and image synthesis. FDA software-as-a-medical-device frameworks accommodate iterative updates without full resubmission, reducing commercialization friction. United States hospitals allocate capital toward suites embedding these capabilities.
- Natural Language Processing:Radiology-specific language models parse unstructured reports and generate structured findings, integrating with electronic health record systems. EU AI Act conformity assessments for clinical decision support tools extend European commercialization timelines, favoring vendors with established quality management systems. The technology climbs fastest as enterprise software contracts displace hardware bundling.
- Machine Learning:Traditional statistical learning methods persist in quality assurance and protocol optimization.
- Computer Vision:Specialized architectures for medical image analysis support registration and multi-modal fusion.
- Reinforcement Learning:Adaptive acquisition strategies optimize scan parameters in real-time based on intermediate image quality.
Deep Learning anchors current revenue. Natural Language Processing is gaining share fastest.
Application:
Clinical volume and reimbursement density differentiate addressable market opportunity across anatomical domains.
- Neurological Imaging:AI algorithms detect acute ischemic stroke, quantify white matter lesion burden, and differentiate tumor recurrence from radiation necrosis. China's NMPA registration pathways for neurodegenerative disease algorithms confer exclusivity periods rewarding first-mover validation investments. Demand concentrates in United States and German stroke centers where treatment windows mandate rapid interpretation.
- Oncological Imaging:Response assessment algorithms measure tumor burden change across serial examinations, standardizing criteria for clinical trial endpoints. India's diagnostic imaging expansion under PLI scheme incentives creates localized demand for tuberculosis and cancer screening modules. The segment expands most quickly as immuno-oncology protocols require frequent monitoring.
- Cardiovascular Imaging:Automated function quantification and plaque characterization support risk stratification.
- Musculoskeletal Imaging:Fracture detection and arthropathy scoring algorithms address high-volume emergency and rheumatology workflows.
- Pediatric Imaging:Motion-robust reconstruction and sedation-sparing protocols address specialized clinical requirements.
Neurological Imaging commands the established base. Oncological Imaging shows the steepest expansion trajectory.
End User:
Procurement authority and integration complexity separate customer segments by contract structure and sales cycle duration.
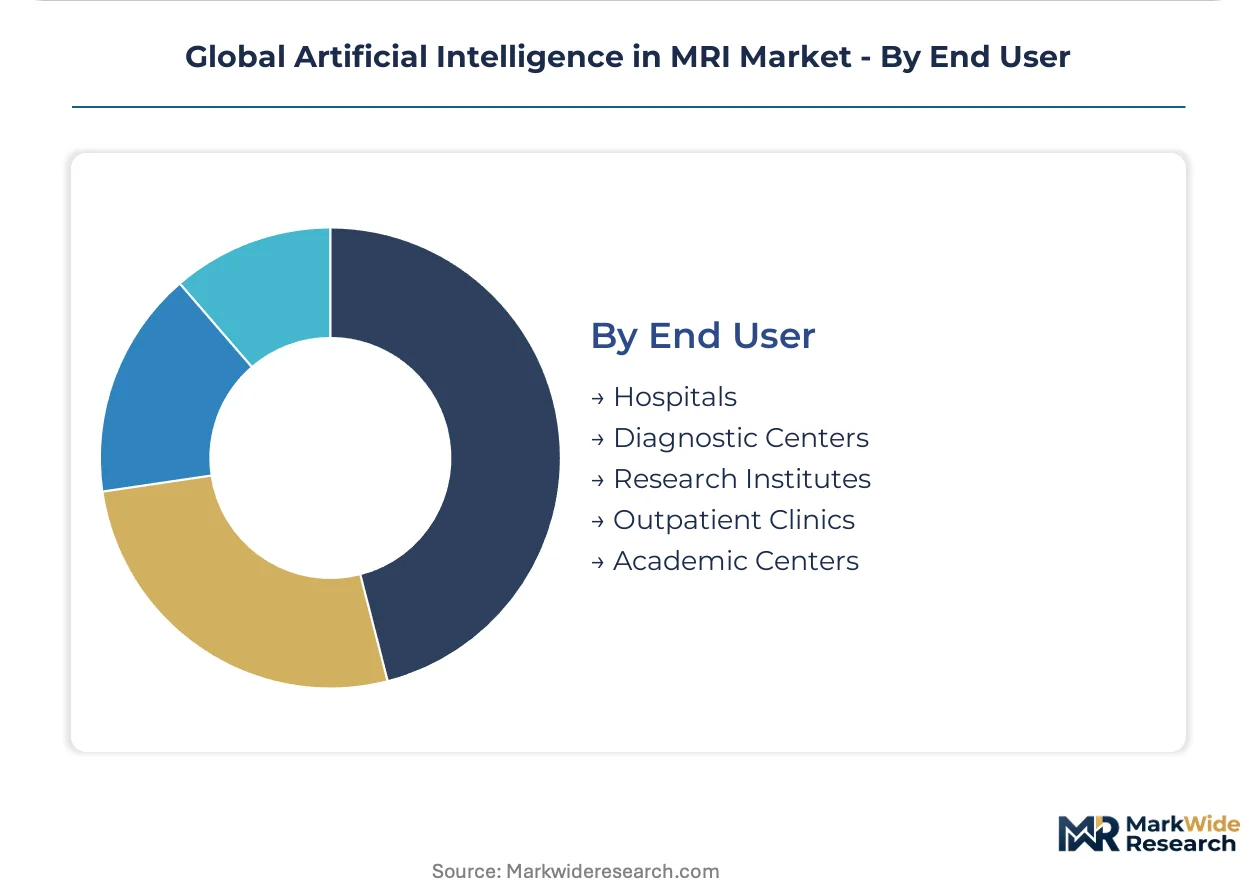
- Hospitals:Integrated delivery networks in the United States consolidate purchasing authority within radiology department chairs and IT procurement officers, favoring platform ecosystems bundling reconstruction, workflow, and reporting tools. Germany's tertiary care networks accelerate procurement where EBM codes enable direct revenue attribution. Legacy PACS integration friction forces middleware expenditures that erode ROI projections.
- Diagnostic Centers:Independent imaging facilities prioritize vendor-agnostic deployment allowing algorithm operation across multi-manufacturer fleets without hardware retrofit. India's diagnostic imaging expansion attracts localized AI module development for prevalent disease patterns. The segment is climbing fastest as outpatient volume shifts from hospital-based settings.
- Research Institutes:Academic medical centers deploy intraoperative MRI guidance algorithms where motion artifact suppression determines surgical outcome.
- Outpatient Clinics:Limited capital budgets favor subscription-based licensing over perpetual software purchases.
- Academic Centers:Training dataset generation and clinical validation partnerships shape technology development roadmaps.
Hospitals command the established base. Diagnostic Centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and China concentrate purchasing authority for AI-assisted MRI platforms, with reimbursement pathway maturity determining deployment velocity in each jurisdiction.
United States
Academic medical centers in Boston and Stanford drive intraoperative MRI guidance adoption where motion artifact suppression determines surgical outcomes. The FDA's software-as-a-medical-device framework accelerates iterative algorithm updates without full resubmission. Integrated delivery networks in the Midwest consolidate vendor relationships around platform ecosystems bundling reconstruction and reporting tools.
Germany
Tertiary care networks in Bavaria and North Rhine-Westphalia accelerate procurement where EBM billing codes enable direct revenue attribution for computer-assisted interpretation. The EU AI Act's conformity assessment obligations extend commercialization timelines for high-risk clinical decision support tools. Siemens Healthineers anchors its position through proprietary raw-data acquisition protocols in Erlangen.
China
Stroke centers in Beijing and Shanghai concentrate demand for neurodegenerative disease algorithms where NMPA registration pathways confer exclusivity periods. Multi-center validation studies extend commercialization timelines but reward first-movers in liver fibrosis quantification. Shanghai United Imaging Healthcare leverages localized assembly under medical device manufacturing incentives.
India
Diagnostic imaging expansion in Maharashtra and Karnataka under the PLI scheme attracts MRI scanner assembly, creating localized demand for tuberculosis and cancer screening modules. The country's national pharmaceutical regulator maintains separate approval pathways for AI-assisted diagnostic software. Independent imaging facilities in Delhi-NCR prioritize vendor-agnostic deployment across multi-manufacturer fleets.
United Kingdom
Radiology departments in London and the Southeast consolidate purchasing authority within NHS trust procurement frameworks. CE marking under the Medical Device Regulation de-risks long-term service continuity for hospital committees. Cloud-enabled AI module distribution penetrates fastest where legacy PACS integration friction forces middleware expenditures.
Global Artificial Intelligence in MRI Market Competitive Landscape
Channel-controlling players compete with product-specialist players across scanner-embedded, cloud-hosted, and vendor-agnostic deployment architectures. The market structure tilts toward platform ecosystems bundling reconstruction, workflow, and reporting tools under single enterprise agreements. Strategic archetypes include hardware-integrated incumbents, vendor-agnostic software specialists, and cloud-native inference providers. Dominant competitive moves encompass strategic partnerships for PACS integration and portfolio diversification into automated reporting.
Among hardware-integrated incumbents, Siemens Healthineers AG and GE Healthcare exemplify scanner-to-algorithm compatibility strategies. Subtle Medical, Inc. occupies a position within the vendor-agnostic specialist tier. These three entities represent the primary competitive anchors: German and US-based integrated health technology corporations against a US-based software-focused limited company.
| Leading Market Players |
|---|
| Canon Medical Systems Corp |
| Blackford Analysis |
| Siemens Healthineers AG |
| Subtle Medical, Inc. |
| FUJIFILM Holdings Corp |
| GE Healthcare |
| Aidoc |
| Shanghai United Imaging Healthcare Co. |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
NVIDIA GPU fabrication concentration in Taiwan and South Korea feeds directly into margin compression for cloud-hosted AI inference providers lacking captive silicon supply. AI-assisted MRI platforms face pricing pressure from upstream compute cost volatility, while scanner-embedded algorithms capture premium positioning through hardware bundling.
Pricing Analysis
Cost-plus contracts with NVIDIA A100 and H100 chip indexation dominate infrastructure procurement for cloud-hosted AI platforms. Pricing stratifies across premium scanner-embedded modules, standard cloud inference subscriptions, and economy-tier workflow optimization tools. Price erosion runs through cloud-hosted tiers as GPU shortages inflate inference costs. Independent diagnostic centers exhibit highest price sensitivity, while United States academic medical centers accept premium positioning for intraoperative guidance capabilities.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for MRI scanner components and GPU accelerator hardware. Taiwan, South Korea, and the United States concentrate semiconductor fabrication for AI inference chips. Raw material dependencies span rare earth magnets for scanner assembly, high-purity helium for cryogenic cooling, and advanced packaging substrates for GPU modules. Distribution runs through original equipment manufacturer service contracts in hospital networks and vendor-agnostic cloud platforms for independent imaging facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Artificial Intelligence in MRI Market represents an early-cycle expansion story, with FDA software-as-a-medical-device frameworks accelerating algorithm iteration velocity beyond traditional medical device commercialization timelines.
For Market Incumbents: Pre-empt vendor-agnostic software specialists by embedding proprietary raw-data acquisition protocols deeper into scanner architectures. Siemens Healthineers and GE Healthcare should accelerate cloud-enabled service contract bundling to lock in hospital procurement committees. Vertical integration into GPU inference infrastructure offers margin defense against NVIDIA supply constraints.
For New Entrants and Emerging Players: Pursue India's diagnostic imaging expansion under PLI scheme incentives, where localized tuberculosis and cancer screening modules face limited incumbent penetration. Germany's EBM billing codes for computer-assisted interpretation create direct revenue attribution that accelerates procurement decisions. Target hospital system partnerships in Bavaria and North Rhine-Westphalia with vendor-agnostic deployment propositions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed radiology informatics platforms seeking platform consolidation. Five-to-ten year viability hinges on reimbursement pathway maturation across United States, German, and Chinese jurisdictions. Monitor FDA predefined change control plan approvals as inflection indicators for algorithm update velocity and competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Predefined change control plans accelerate iterative algorithm updates without full resubmission cycles. |
| CE Marking Pathway Under EU AI Act | Conformity assessment investments de-risk European commercialization for high-risk clinical decision support tiers. |
| Hospital System Partnership | Integrated delivery network consolidation favors platform ecosystems bundling reconstruction and reporting tools. |
| Software Companion Development | Natural language processing integration opens enterprise contracts beyond hardware-centric revenue pools. |
| Reimbursement Strategy | German EBM codes and United States payer acceptance determine deployment economics for AI-enhanced radiology. |
Research Methodology
A standing panel of radiology department chairs, hospital IT procurement officers, biomedical engineers, and GPO contracts managers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU notified body conformity assessment registers. Bottom-up algorithm deployment counts and top-down health system capital expenditure patterns underwent cross-triangulation to anchor market sizing.
Scenario-bracketing around GPU supply volatility, reimbursement pathway maturation velocity, and EU AI Act implementation timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass solution type, technology architecture, clinical application, and end-user procurement authority. CAGRs derived from algorithm adoption curves weighted by scanner installed base and health system contract renewal cycles. Industry-specific inputs included FDA software-as-a-medical-device approval trajectories and German EBM billing code expansion patterns.
Sensitivities concentrate around NVIDIA chip availability, payer acceptance timelines for AI-enhanced radiology reads, and EU notified body capacity for high-risk algorithm conformity assessments. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and hospital capital allocation priorities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Radiology Services Market