
 Teleradiology Market | 2026-2036
Teleradiology Market Size, Share, and Industry Trends Forecast 2026-2036
Teleradiology Market Intelligence
Subscription-based access to AI-assisted diagnostic platforms is recalibrating how imaging centers and hospitals procure interpretation services. This model shifts capital expenditure on software to operational spending, favoring providers with scalable cloud infrastructure. Siemens Healthineers leverages its extensive installed base of imaging hardware to promote its integrated digital health services. In contrast, vRad specializes in providing high-volume remote reading services, competing on turnaround time and subspecialty expertise access for its clients.
Teleradiology involves the electronic transmission of radiological patient images, including X-rays, CTs, and MRIs, from one location to another. These systems use the DICOM (Digital Imaging and Communications in Medicine) standard over secure, high-speed networks to enable remote interpretation by qualified radiologists. Within service types, Night Hawk Reporting remains a foundational segment addressing after-hours and emergency caseloads. Cardiac Imaging and Neurology Imaging represent high-value application areas due to the specialized expertise demanded for accurate diagnoses.
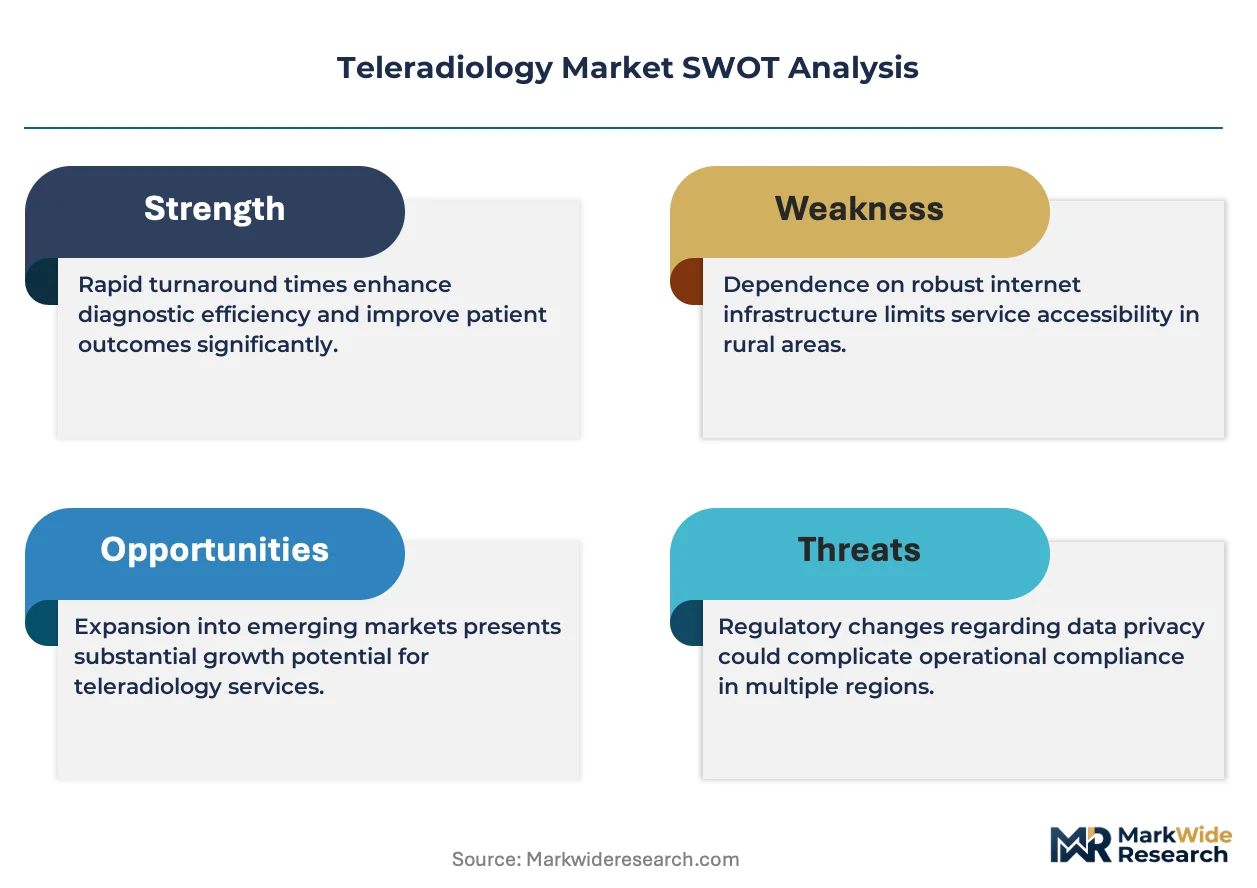
Regulatory frameworks establish stringent requirements for data security and patient privacy, directly influencing platform architecture and operational protocols. Compliance with the Health Insurance Portability and Accountability Act (HIPAA) in the United States and the General Data Protection Regulation (GDPR) in Europe is mandatory for market participants. Service providers must decide whether to develop proprietary AI diagnostic tools or partner with specialized technology vendors to maintain a competitive edge in interpretation accuracy and speed.
Market Dynamics
The fundamental market structure is shaped by a persistent shortage of specialized radiologists, particularly in developed nations, which directly fuels the demand for remote interpretation services. This supply-demand imbalance is amplified by the increasing volume of advanced medical imaging procedures.
Growth Catalysts
- Radiologist Shortages:Persistent deficits in on-site subspecialty radiologists, especially in outpatient clinics and rural hospitals within countries like the United States and Australia, necessitate external interpretation support.
- Enabling Regulations:Mature data security frameworks like HIPAA in the U.S. and GDPR in Europe provide clear legal and technical guidelines for the secure transmission of patient imaging data, reducing compliance risks for providers.
- Infrastructure Advancement:The widespread availability of high-speed broadband internet and scalable cloud computing infrastructure lowers the barrier to entry and enables the reliable transfer of large DICOM image files.
Market Restraints
- Interoperability Hurdles:A lack of standardization among legacy Picture Archiving and Communication Systems (PACS) and hospital information systems creates significant technical barriers and costs when integrating third-party teleradiology platforms.
- Restrictive Licensing:State-level and national medical licensing requirements create significant administrative friction, preventing radiologists from seamlessly providing interpretation services across different jurisdictions without obtaining multiple licenses.
- Data Localization Laws:National policies in certain geographies mandate that patient health information must be stored and processed within the country's borders, complicating the operating models of global teleradiology providers.
Strategic Opportunities
- Clinical Trial Imaging:Centralizing radiological interpretations for multi-site clinical trials offers a significant opportunity, ensuring consistency and quality control in imaging endpoints for pharmaceutical and biotech research.
- Emerging Market Expansion:Healthcare systems in parts of Latin America and Southeast Asia are rapidly digitizing their imaging capabilities, creating new demand for remote reading services where local specialist expertise is scarce.
- Preventive Screening Programs:Large-scale public health initiatives, such as national lung cancer screening programs, generate massive volumes of images that are well-suited for high-throughput analysis by specialized teleradiology services.
Industry Challenges
- Cybersecurity Threats:The high value of protected health information makes teleradiology platforms a prime target for cyberattacks, requiring continuous and costly investment in advanced security protocols and threat monitoring.
- AI Validation and Liability:Determining the legal liability for diagnostic errors when using AI-assisted tools presents a complex challenge, slowing adoption as providers, vendors, and insurers navigate unresolved indemnity issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teleradiology Market |
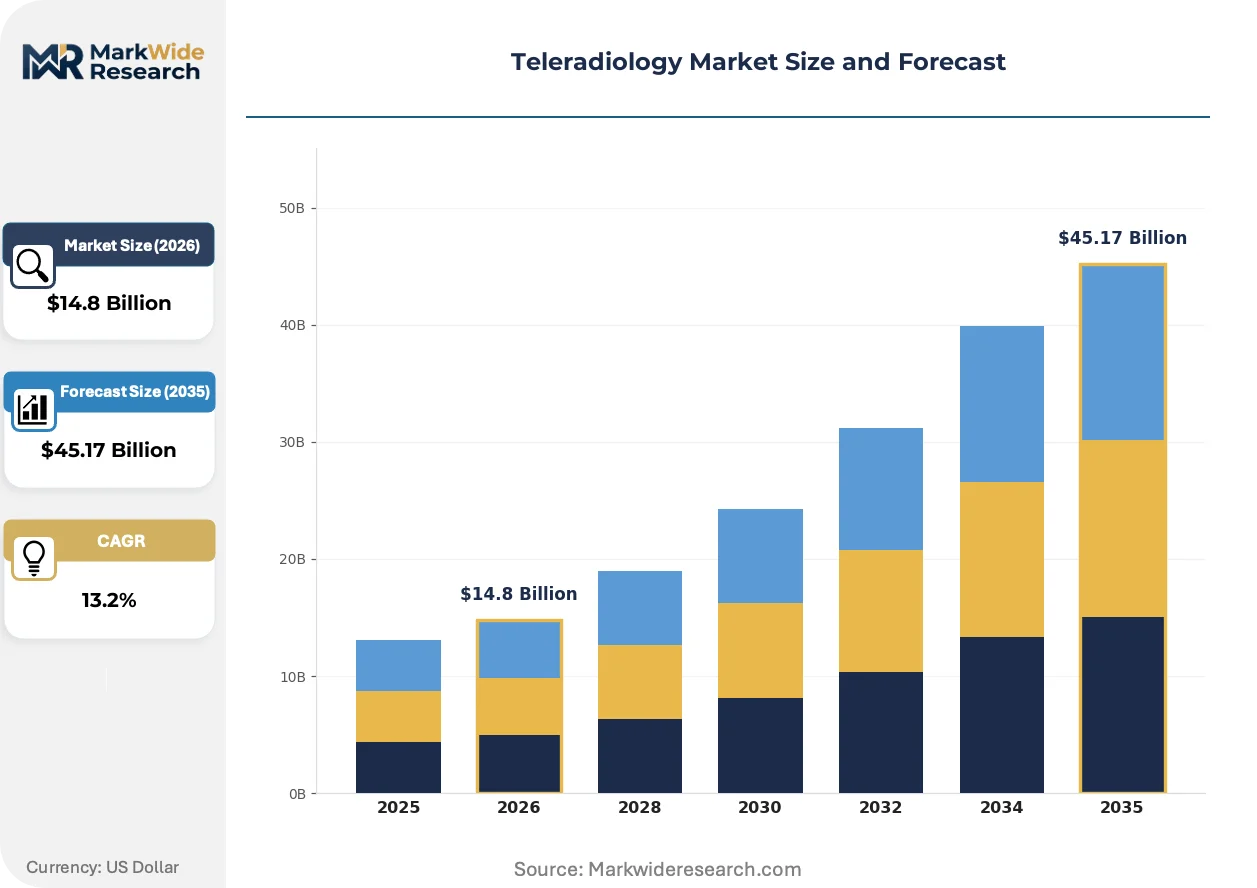
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $45.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand Reading, Routine Reading, Second Opinion, Night Hawk Reporting, Emergency Reporting Technology: PACS Integration, Cloud-Based Platforms, AI-Assisted Diagnostics, Mobile Reporting, Web-Based Solutions End User: Diagnostic Imaging Centers, Outpatient Clinics, Remote Hospitals, Telehealth Providers, Research Institutes Application: Neurology Imaging, Cardiac Imaging, Musculoskeletal Imaging, Chest Radiography, Pediatric Imaging |
| Companies Covered | vRad, Carestream Health, GE Healthcare, FUJIFILM Holdings Corporation, McKesson Corporation, Siemens Healthineers, Agfa Healthcare, ONRAD, Radiology Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teleradiology Market Strategic Shifts & Innovations
The industrialization of diagnostic imaging is the core theme, with technology and new service models transforming radiological interpretation from a local practice into a distributed, on-demand service. This shift prioritizes efficiency, scalability, and access to subspecialty expertise.
AI-powered computer-aided detection software is a foundational technology that analyzes images to flag potential abnormalities for radiologist review. High-volume imaging centers and emergency departments are rapidly adopting these tools to triage critical cases and improve diagnostic consistency. This technology is electrifying the entire workflow, automating mundane tasks and allowing radiologists to focus on complex diagnostic challenges, thereby compressing report turnaround times.
New regulations like the EU AI Act are establishing a risk-based framework for artificial intelligence systems in healthcare. This legislation compels developers of diagnostic AI to provide extensive documentation on data provenance, algorithmic performance, and post-market surveillance. The high-risk medical device segment is most affected, facing increased compliance costs and longer development cycles to achieve CE marking for market access in Europe.
Subscription-based platform access is displacing traditional per-scan fee-for-service models for acquiring interpretation services. This change disrupts the business of individual radiologists and small groups who compete on transactional pricing, favoring larger providers with integrated software and reading capacity. The shift toward predictable operational spending is most pronounced in large hospital networks across the United States and Germany.
Teleradiology Market Segmentation
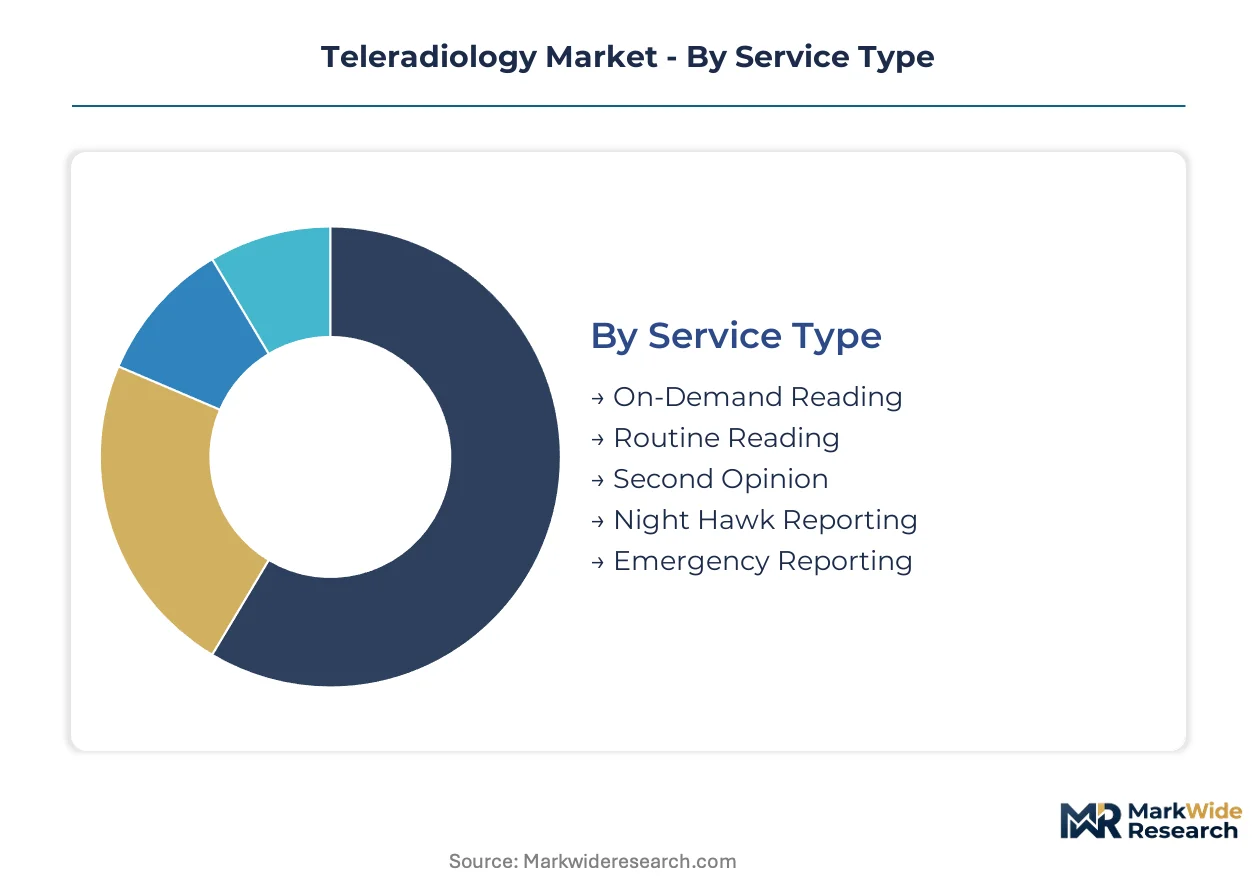
The Teleradiology Market segmentation reveals how specialized services and advanced technologies address diverse healthcare needs. Different service models cater to varying urgency levels, while specific technological platforms enable efficient and secure image interpretation. Understanding these distinctions clarifies the evolving demand patterns across healthcare providers.
Service Type:
Buyers of teleradiology services are differentiated by their immediate need for interpretation and the specialized nature of the diagnostic request.
- Night Hawk Reporting:This service specializes in providing urgent radiological interpretations during off-hours, ensuring continuous patient care when on-site radiologists are unavailable. Hospitals and emergency departments in developed healthcare systems like the United States rely heavily on Night Hawk services to manage critical after-hours caseloads.
- Emergency Reporting:Emergency reporting focuses on rapid interpretation of critical imaging studies, typically within minutes, for patients presenting with acute conditions. This segment is crucial for trauma centers and large hospital networks, where quick diagnoses directly impact patient outcomes and treatment pathways.
- On-Demand Reading:This service provides interpretations for non-critical cases as needed, offering flexibility for facilities without full-time radiology staff.
- Routine Reading:Routine reading covers scheduled imaging studies, offering consistent interpretation for general diagnostic purposes.
- Second Opinion:Second opinion services provide an additional expert review of complex or ambiguous cases, enhancing diagnostic accuracy for patients and referring physicians.
Volume sits with Night Hawk Reporting; growth tilts toward Emergency Reporting.
Technology:
The technological infrastructure supporting teleradiology services varies significantly in deployment model and diagnostic capabilities.
- AI-Assisted Diagnostics:This technology integrates artificial intelligence algorithms to aid radiologists in identifying abnormalities, prioritizing critical cases, and improving diagnostic efficiency. Demand is accelerating in high-volume imaging centers and large hospital networks across Europe, driven by the need to compress report turnaround times.
- Cloud-Based Platforms:Cloud-based solutions offer scalable, secure, and accessible infrastructure for image storage, transmission, and interpretation, reducing capital expenditure for healthcare providers. Hospitals and outpatient clinics in the United States are increasingly adopting these platforms due to their flexibility and ease of integration.
- PACS Integration:This involves seamless connectivity with existing Picture Archiving and Communication Systems, ensuring smooth workflow and data exchange.
- Mobile Reporting:Mobile reporting tools enable radiologists to review and report on images from portable devices, enhancing flexibility for on-call situations.
- Web-Based Solutions:Web-based platforms provide browser-accessible interfaces for remote interpretation, offering flexibility and broad accessibility for radiologists.
The core of teleradiology operations relies on PACS Integration, with AI-Assisted Diagnostics expanding most quickly.
End User:
Different end-user segments leverage teleradiology to address specific challenges related to radiologist availability and specialized expertise.
- Remote Hospitals:These facilities, often located in rural or underserved areas, depend on teleradiology to access specialized interpretations and cover after-hours needs. The persistent shortage of on-site radiologists in countries like Australia fuels the demand for remote hospital services.
- Diagnostic Imaging Centers:These centers utilize teleradiology to manage high imaging volumes, provide subspecialty interpretations, and optimize workflow efficiency. Large diagnostic networks in Germany are integrating teleradiology to streamline operations and enhance service offerings.
- Outpatient Clinics:Outpatient clinics use teleradiology to provide timely diagnostic interpretations for their patients, avoiding delays associated with local radiologist shortages.
- Telehealth Providers:Telehealth platforms integrate teleradiology to offer comprehensive remote diagnostic services, expanding access to specialist care.
- Research Institutes:Research institutes employ teleradiology for consistent and centralized interpretation of imaging data in clinical trials, ensuring data quality and standardization.
Diagnostic Imaging Centers represent the largest consumer base, while Remote Hospitals are gaining share fastest.
Application:
The specific medical application of teleradiology dictates the required subspecialty expertise and the complexity of image interpretation.
- Cardiac Imaging:This application involves the remote interpretation of highly specialized cardiac MRI, CT, and echocardiography studies, requiring specific subspecialty expertise. The demand for accurate cardiac diagnoses drives this segment in developed healthcare systems like the United States.
- Neurology Imaging:Neurology imaging focuses on interpreting complex brain and spine scans, such as MRI and CT, often for time-sensitive conditions like stroke. This segment is critical for providing specialized diagnostic support in hospitals and stroke centers across Europe.
- Musculoskeletal Imaging:Musculoskeletal imaging involves the remote analysis of X-rays, CTs, and MRIs of bones, joints, and soft tissues for orthopedic conditions.
- Chest Radiography:Chest radiography focuses on interpreting standard chest X-rays for conditions like pneumonia or lung cancer, representing a high-volume application.
- Pediatric Imaging:Pediatric imaging requires specialized expertise for interpreting images of children, accounting for developmental differences and specific pathologies.
Chest Radiography constitutes a significant portion of imaging volume, with Neurology Imaging showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global teleradiology market exhibits a significant divide between regions with established healthcare infrastructure driving demand and emerging economies rapidly adopting digital solutions. Developed nations primarily consume remote interpretation services to address radiologist shortages and specialized expertise gaps. Developing markets are building out foundational imaging capabilities, creating new opportunities for service providers.
United States
Demand for teleradiology services in the United States stems from persistent radiologist shortages, particularly in rural hospitals and outpatient clinics. Compliance with HIPAA regulations is mandatory for secure patient data transmission, influencing platform architecture. Major hospital networks across the Northeast and Midwest are adopting subscription-based platforms for predictable operational spending.
Germany
Germany's teleradiology demand is driven by the need for efficient workflow and specialized interpretation within its large diagnostic networks. The EU AI Act is establishing a risk-based framework for diagnostic AI systems, impacting market access. Large hospital groups in Bavaria and North Rhine-Westphalia are integrating teleradiology to streamline operations and enhance service offerings.
Australia
Australia faces persistent deficits in on-site subspecialty radiologists, fueling the demand for external interpretation support, especially in remote hospitals. The country's national health regulations emphasize secure data handling for patient imaging. Regional health authorities in Queensland and Western Australia are investing in remote reading services to improve access to specialist care.
Brazil
Digitization of imaging capabilities in Brazil creates new demand for remote reading services where local specialist expertise is scarce. The national health regulatory agency, ANVISA, sets standards for medical device and service approval. Healthcare providers in São Paulo and Rio de Janeiro are increasingly exploring teleradiology to expand diagnostic access.
India
India's rapidly digitizing healthcare system drives demand for remote interpretation services to overcome geographical barriers and radiologist scarcity. The country's medical device regulations and data privacy norms influence platform development and deployment. Major diagnostic chains in Karnataka and Maharashtra are adopting teleradiology to manage high imaging volumes.
Teleradiology Market Key Industry Players
Capital-heavy imaging hardware manufacturers compete with asset-light teleradiology service providers in this market. The market structure features a tiered landscape, with large integrated healthcare technology conglomerates alongside specialized remote reading firms. Strategic archetypes include hardware-centric integrators, pure-play service bureaus, and AI-driven diagnostic platform developers. Dominant competitive moves involve strategic partnerships to expand service reach and continuous investment in AI-assisted diagnostic tools.
Specialists in high-volume remote reading services include vRad, which exemplifies a pure-play teleradiology service model focused on efficiency and subspecialty access. Siemens Healthineers, a Germany-based corporation, represents the integrated hardware-and-software approach, leveraging its extensive installed base of imaging equipment. Radiology Partners, a US-based firm, anchors the large-scale practice management archetype, consolidating radiologist networks and expanding service offerings across various healthcare settings. These companies collectively illustrate the diverse strategies employed to capture market share and address evolving customer needs.
| Leading Market Players |
|---|
| vRad |
| Carestream Health |
| GE Healthcare |
| FUJIFILM Holdings Corporation |
| McKesson Corporation |
| Siemens Healthineers |
| Agfa Healthcare |
| ONRAD |
| Radiology Partners |
Cost & Logistics Intelligence
Vertical integration into software and service platforms anchors both the supply position and pricing power for teleradiology providers. This strategic choice allows companies to control service delivery and optimize cost structures.
Pricing Analysis
Cost compression in high-volume, general reporting services intensifies as subscription-based models displace traditional per-scan fees. Pricing stratifies across premium, standard, and economy tiers based on subspecialty expertise and guaranteed turnaround times. AI-assisted diagnostic platforms offer differentiation, but also introduce new cost structures. Small outpatient clinics and remote hospitals exhibit higher price sensitivity compared to large integrated hospital networks prioritizing comprehensive solutions.
Supply Chain Analysis
Reverse logistics for teleradiology primarily involve secure data transmission and archival infrastructure, rather than physical goods. Supply of subspecialty radiologists concentrates in developed healthcare systems like the United States and Germany. The service delivery depends on robust high-speed internet and scalable cloud computing infrastructure. Restrictive medical licensing across state and national borders creates a significant structural risk. Distribution runs through specialized service bureaus and integrated digital health platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The teleradiology market is characterized by a vertical-integration race, as players pursue control over both imaging hardware and AI-assisted diagnostic software. This strategy aims to create comprehensive, end-to-end service offerings.
For Market Incumbents: Deepen integration of AI-assisted diagnostic tools into existing platforms to enhance efficiency and diagnostic consistency. Expand subspecialty radiologist networks globally to counter the persistent radiologist shortage. Invest in robust cybersecurity protocols to mitigate risks from cyberattacks, a significant threat to protected health information. Compliance with evolving regulations like the EU AI Act necessitates continuous platform updates.
For New Entrants and Emerging Players: HIPAA in the United States opens a window for secure, compliant cloud-based teleradiology platforms. Target remote hospitals in underserved areas, particularly in parts of Latin America and Southeast Asia, where local specialist expertise is scarce. Offer subscription-based access models to reduce capital expenditure for smaller facilities. Focus on specialized applications like clinical trial imaging, ensuring consistency across multi-site studies.
For Investors and Strategic Acquirers: Exit pathways concentrate in pure-play teleradiology service bureaus with proprietary AI diagnostic tools. The market offers sustained long-term viability over the next 5-10 years due to persistent radiologist shortages and increasing imaging volumes. Acquisition targets include regional specialists with established networks or technology firms focused on interoperability solutions. Monitor regulatory clarity on AI validation and liability as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-Assisted Diagnostics | Siemens Healthineers can leverage AI to compress report turnaround times for high-volume imaging centers. |
| Expand Subspecialty Networks | vRad can offer specialized expertise access to remote hospitals addressing critical diagnostic needs. |
| Develop Cloud-Based Platforms | Healthcare providers in the United States reduce capital expenditure with scalable and secure cloud infrastructure. |
| Pursue Regulatory Compliance (EU AI Act) | Developers of diagnostic AI face increased compliance costs to achieve CE marking for market access in Europe. |
| Partner for PACS Integration | Seamless connectivity with existing Picture Archiving and Communication Systems ensures smooth workflow for diagnostic imaging centers. |
Research Approach
Medical journals, government health reports, and industry association publications formed the secondary backbone of this study. Primary interviews with radiologists, hospital administrators, IT procurement officers, and teleradiology service executives provided critical qualitative insights. This approach combined bottom-up data collection with top-down market validation. Triangulation across these sources ensured robust data integrity.
Bottom-up analysis of individual market segments was reconciled with top-down macroeconomic factors across the analysis window. The model segmented the market by service type, technology, end user, application, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and projected demand drivers. Key inputs included global imaging procedure volumes and regional radiologist availability.
The model assumes a particular technology adoption path; alternative pathways for AI integration would alter the outlook. Forecasts reflect current regulatory frameworks and market dynamics. Practitioners should monitor new data privacy laws and AI liability precedents for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Digital Radiology Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Pre-Clinical Imaging System Market