
 Nuclear Medicine Market | 2026-2036
Nuclear Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Medicine Market Analysis
Buyer concentration among hospital networks and integrated delivery systems is restructuring procurement patterns for radiopharmaceuticals. Cardinal Health leverages its nationwide distribution network to secure long-term supply agreements with major health systems. GE Healthcare anchors its position through cyclotron manufacturing and PET tracer production capabilities. Novartis differentiates via its vertically integrated radioligand therapy platform spanning development through commercial supply.
Nuclear medicine encompasses the clinical use of radioactive substances for both diagnostic imaging and targeted therapy, requiring isotopes with precisely calibrated half-lives measured in hours to days and radiochemical purity exceeding 95 percent for patient administration. Its primary purpose centers on visualizing physiological function at the molecular level and delivering cytotoxic radiation directly to diseased cells while sparing healthy tissue. Among product types, therapeutic isotopes command attention as the fastest-expanding category due to expanding indications in prostate and neuroendocrine malignancies. Within applications, oncology dominates current value generation while cardiology retains stable demand for myocardial perfusion assessment. PET technology leads the imaging modality landscape, though hybrid imaging systems combining PET with CT or MRI are capturing incremental placement growth.
The FDA governs radiopharmaceutical approval through its Office of Radiological Health while the EMA coordinates centralized assessment across European member states under its radiopharmaceuticals guideline, with both agencies tightening manufacturing quality standards that elevate barriers for new entrants. The Nuclear Regulatory Commission and corresponding national atomic energy authorities in Germany and Japan enforce isotope handling, transport, and waste disposal protocols that directly constrain site licensing and operational scale. Stakeholders must monitor cyclotron and reactor supply reliability alongside evolving reimbursement determinations for therapeutic radiopharmaceuticals to calibrate capacity investments and pipeline prioritization.
Market Dynamics
Therapeutic radiopharmaceuticals are displacing conventional external beam radiation for metastatic cancers, forcing cyclotron networks to retool from diagnostic tracer production toward alpha-emitter and beta-emitter manufacturing capabilities.
Growth Catalysts
- Targeted Alpha Therapy:Ac-225 and Pb-212 isotopes demonstrate superior DNA double-strand break induction in micrometastases. Academic medical centers in Germany and Japan are expanding production partnerships to secure supply.
- FDG-PET Reimbursement:CMS coverage determinations for oncologic PET imaging in the United States have stabilized payment rates, incentivizing hospital networks to replace aging SPECT systems with hybrid PET-CT platforms.
- EMA Centralized Pathway:The European Medicines Agency's radiopharmaceuticals guideline harmonizes manufacturing standards across member states, reducing duplicate facility inspections and accelerating multi-country trial enrollment.
Market Restraints
- Mo-99 Supply Concentration:Over ninety percent of global molybdenum-99 production depends on aging research reactors in the Netherlands, Belgium, and South Africa, creating single-point vulnerability for Tc-99m generators.
- Reactor Decommissioning:Canada's NRU reactor closure eliminated a major North American supply source, forcing the United States to increase HEU-free Mo-99 imports from European conversion facilities.
- Radiochemical Purity Thresholds:FDA and EMA specifications exceeding ninety-five percent purity require multi-stage purification systems that extend batch release timelines and constrain batch sizes.
Strategic Opportunities
- India Diagnostic Penetration:India's CDSCO has streamlined import licensing for PET tracers, creating entry pathways for cyclotron operators to serve oncology departments in Mumbai, Delhi, and Bangalore.
- theranostics Pairing:Ga-68 imaging agents matched to Lu-177 therapies enable patient selection and response monitoring within unified treatment protocols, expanding addressable populations beyond current biomarker-defined segments.
- Decentralized Cyclotron Siting:Compact 11 MeV cyclotrons allow hospital-based F-18 production, reducing reliance on centralized radiopharmacies and enabling same-day scheduling for time-sensitive cardiac viability studies.
Industry Challenges
- Radiopharmacist Shortage:Specialized training programs for sterile radiochemistry and dose calibration remain limited to fewer than fifteen accredited centers in the United States, constraining site expansion timelines.
- Waste Disposal Logistics:Generator return programs and decay storage requirements vary across Japanese prefectures, forcing multi-site operators to maintain heterogeneous compliance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Medicine Market |
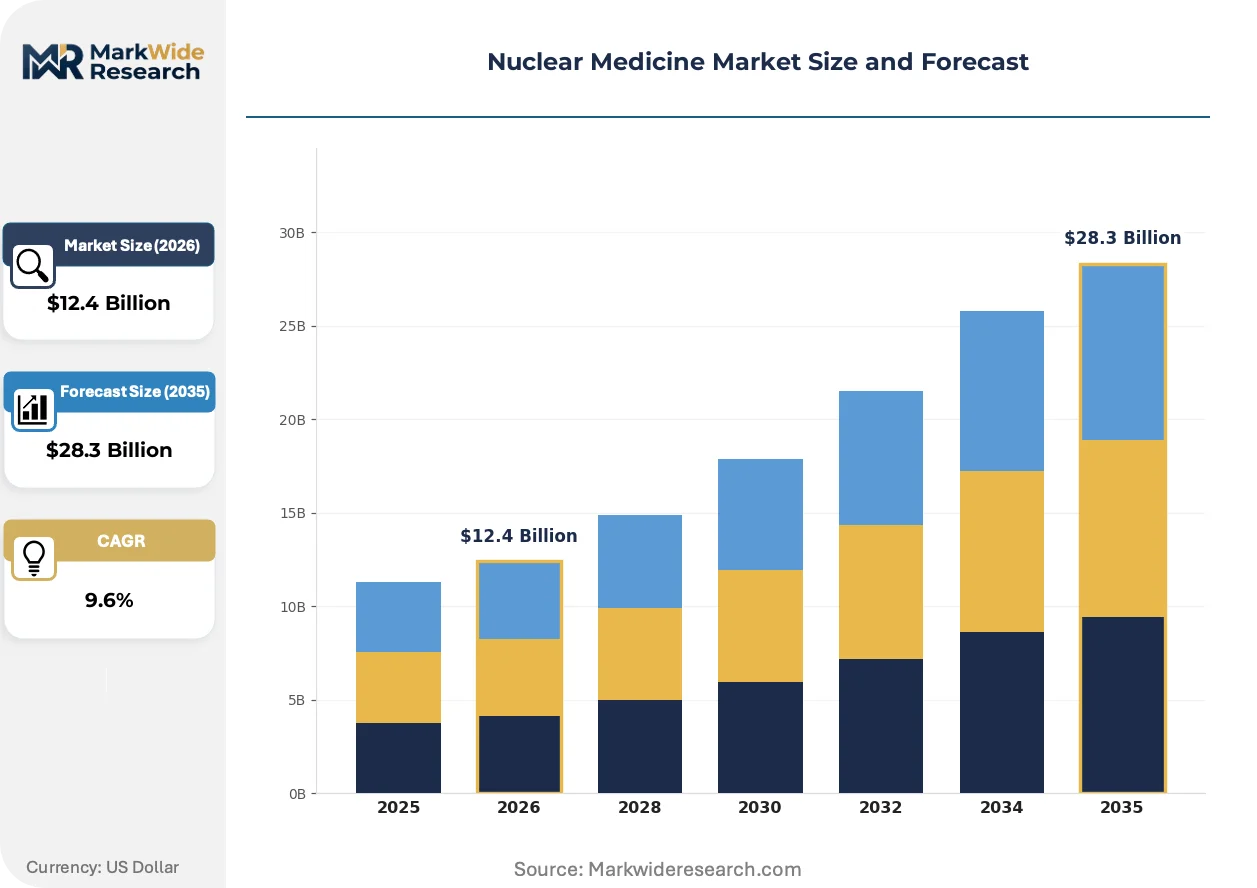
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.3 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Imaging Agents, Therapeutic Isotopes, Diagnostic Agents Application: Oncology, Cardiology, Neurology, Thyroid Disease Technology: Single Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging, Molecular Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics |
| Companies Covered | Cardinal Health, Novartis, Lantheus Holdings, GE Healthcare, Curium Pharma, Jubilant Pharma, Siemens Healthineers, Eckert & Ziegler, NorthStar Medical Radioisotopes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Medicine Market Emerging Trajectories
Alpha-emitter manufacturing is forcing infrastructure reinvestment across isotope supply chains, while diagnostic-procedural convergence compresses the interval between molecular imaging and therapeutic intervention.
Microfluidic radiochemistry platforms are modularizing tracer synthesis workflows. Cyclotron facilities at university hospitals in Heidelberg and Boston are adopting cartridge-based systems that reduce synthesis time from four hours to ninety minutes. This compression is modularizing batch economics and enabling same-day patient scheduling for time-critical neuroendocrine tumor imaging.
EMA's revised GMP Annex 1 for sterile medicinal products imposes environmental monitoring requirements on radiopharmaceutical cleanrooms. Manufacturing sites across France and Germany are retrofitting isolator technology and continuous particle monitoring systems. The directive most affects PET tracer producers, who are consolidating batch testing into centralized quality control laboratories to maintain release timelines.
Hospital procurement departments are unbundling radiopharmaceutical supply from imaging equipment service contracts. Integrated delivery networks in the United States now negotiate tracer pricing separately from cyclotron maintenance agreements, forcing radiopharmacies to disclose cost-plus pricing structures. This disaggregation is most advanced in California and Texas, where multi-hospital systems operate captive specialty pharmacies.
Nuclear Medicine Market Segmentation
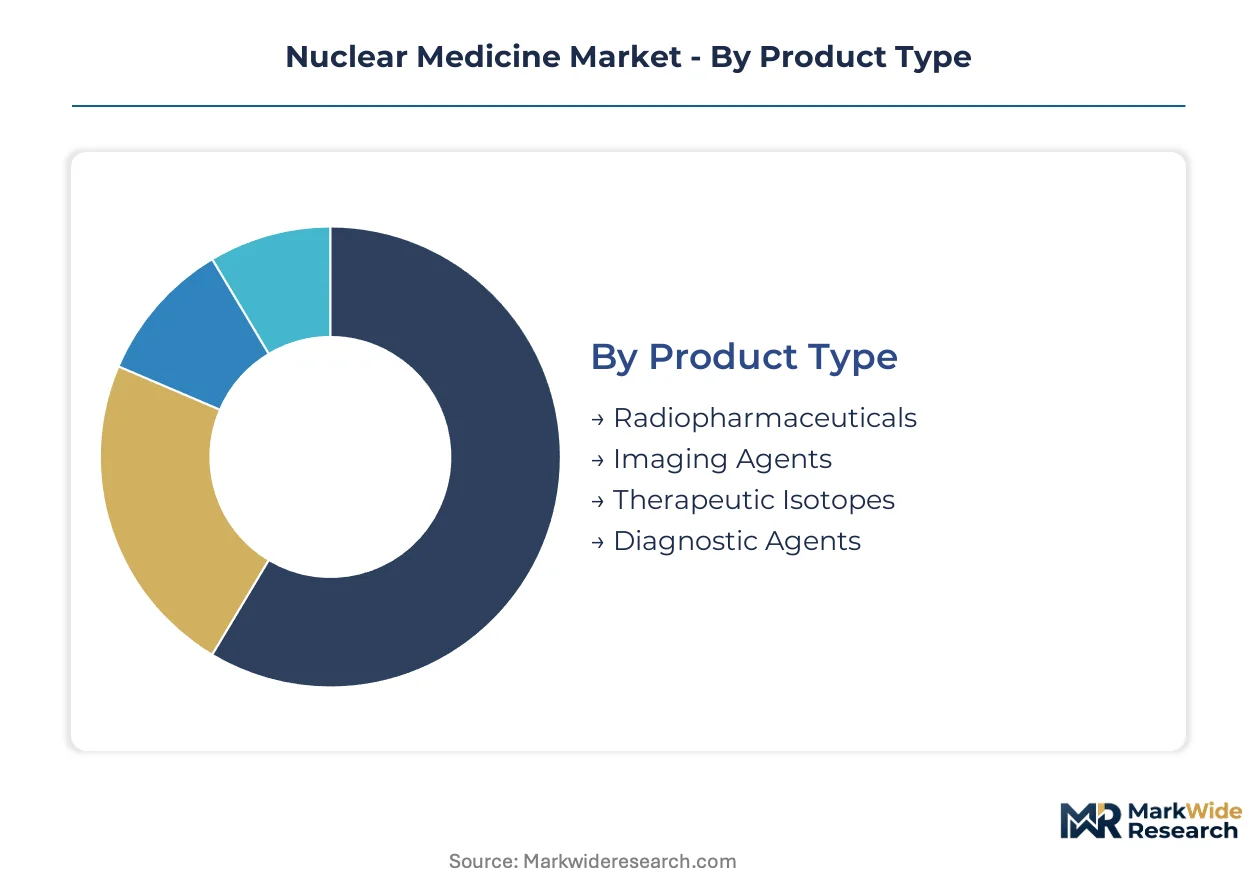
Segmentation in nuclear medicine reveals how clinical utility, infrastructure requirements, and reimbursement pathways fragment commercial opportunity. Understanding these divides enables manufacturers to calibrate production scale and regulatory investment against addressable patient populations.
Product Type:
Volume concentrates in diagnostic agents while premium economics accrue to therapeutic isotopes with targeted delivery mechanisms.
- Radiopharmaceuticals:Encompass both diagnostic and therapeutic radioactive compounds requiring cyclotron or reactor production. Demand clusters in the United States and Germany where hospital networks operate captive radiopharmacies to secure supply chain control.
- Imaging Agents:FDG and other PET tracers dominate procedural volumes, with F-18 fluorodeoxyglucose representing the workhorse for oncologic staging. CMS reimbursement stability in the United States sustains replacement demand for aging SPECT systems with hybrid PET-CT platforms.
- Therapeutic Isotopes:Lu-177 and Ac-225 are expanding indications in prostate and neuroendocrine malignancies. Academic medical centers in Heidelberg and Boston are securing alpha-emitter production partnerships to guarantee supply for radioligand therapy programs.
- Diagnostic Agents:Tc-99m generators remain the volume foundation despite Mo-99 supply vulnerabilities. European conversion facilities are capturing incremental share following Canada's NRU reactor closure.
Today's leader: Imaging Agents. Tomorrow's challenger: Therapeutic Isotopes.
Application:
Oncology commands capital deployment while cardiology offers defensive revenue stability against reimbursement volatility.
- Oncology:PET-CT staging and radioligand therapy drive the majority of value creation. FDG-PET reimbursement from CMS and parallel EMA pathways for radiopharmaceutical approval are streamlining market access for novel agents targeting solid tumors.
- Cardiology:Myocardial perfusion imaging with Tc-99m sestamibi maintains steady procedural volumes. Hospital networks in Japan favor cardiac viability studies using same-day F-18 production from compact cyclotrons to reduce patient scheduling friction.
- Neurology:Amyloid PET imaging for Alzheimer's disease evaluation is penetrating academic memory centers. FDA approval pathways for tau-targeting tracers are expanding addressable populations beyond current biomarker-defined segments.
- Thyroid Disease:I-131 therapy for hyperthyroidism and differentiated thyroid cancer represents mature, price-sensitive demand. Reimbursement compression in this segment is forcing radiopharmacies to consolidate batch production for cost efficiency.
Oncology absorbs the steepest expansion trajectory; cardiology provides the most predictable cash flows.
Technology:
Hybrid platforms capture placement growth as standalone modalities face obsolescence risk from diagnostic-procedural convergence.
- Single Photon Emission Computed Tomography:Legacy Tc-99m-based systems face replacement pressure from PET-CT hybrids. Aging installed bases in community hospitals sustain aftermarket service revenue despite declining new unit demand.
- Positron Emission Tomography:FDG-PET dominates oncologic staging with established reimbursement codes. GE Healthcare and Siemens Healthineers anchor manufacturing capacity to serve hospital network procurement cycles in the United States and Germany.
- Hybrid Imaging:PET-CT and PET-MRI fusion systems are capturing incremental placement growth. EMA's radiopharmaceuticals guideline harmonizes manufacturing standards that accelerate multi-country trial enrollment for tracer developers.
- Molecular Imaging:Theranostics pairing of Ga-68 imaging with Lu-177 therapy enables unified treatment protocols. Academic centers in Japan are expanding production partnerships to secure alpha-emitter supply for micrometastasis targeting.
Standalone SPECT is ceding share fastest; hybrid platforms are absorbing capital allocation.
End User:
Hospital networks concentrate procurement power while diagnostic centers compete on scheduling velocity and geographic convenience.
- Hospitals:Academic medical centers anchor radiopharmaceutical program expansion with integrated cyclotron infrastructure. Cardinal Health secures long-term supply agreements through nationwide distribution networks serving multi-hospital systems.
- Diagnostic Centers:Independent imaging facilities compete on patient throughput and same-day scheduling. Compact 11 MeV cyclotrons are enabling hospital-based F-18 production that reduces reliance on centralized radiopharmacies.
- Research Institutions:University hospitals in Boston and Heidelberg pilot microfluidic radiochemistry platforms. Cartridge-based synthesis systems are compressing tracer production from four hours to ninety minutes for neuroendocrine tumor imaging.
- Imaging Clinics:Outpatient facilities face margin pressure from unbundled procurement practices. Integrated delivery networks in California and Texas now negotiate tracer pricing separately from equipment service contracts.
Hospitals dominate contract value; diagnostic centers are gaining share in patient volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains cyclotron density unmatched elsewhere, while Germany concentrates alpha-emitter production partnerships that Japan now emulates for radioligand therapy expansion.
United States
Hospital networks in Texas and California operate captive radiopharmacies to secure FDG supply chain control. CMS reimbursement stability for oncologic PET imaging sustains hybrid PET-CT replacement cycles. The Nuclear Regulatory Commission enforces isotope handling protocols that constrain site licensing timelines across multi-hospital systems.
Germany
Academic medical centers in Heidelberg anchor European alpha-emitter production for Ac-225 radioligand therapy programs. EMA centralized assessment pathways harmonize manufacturing standards across member states. Bavaria and Baden-Württemberg concentrate cyclotron infrastructure serving cross-border tracer demand from Switzerland and Austria.
Japan
Compact 11 MeV cyclotrons enable same-day F-18 production for cardiac viability studies in Tokyo and Osaka metropolitan areas. METI coordinates atomic energy authority protocols that vary across prefectures for waste disposal logistics. Kansai region hospitals are expanding Ga-68 imaging capacity to pair with Lu-177 therapeutic protocols.
India
CDSCO streamlined import licensing for PET tracers has opened entry pathways for cyclotron operators in Mumbai, Delhi, and Bangalore. Oncology departments at private hospital chains are expanding molecular imaging programs. Maharashtra and Karnataka concentrate diagnostic infrastructure investment from domestic and multinational radiopharmacy operators.
Canada
HEU-free Mo-99 import dependence intensified following NRU reactor closure, redirecting supply relationships toward European conversion facilities. Health Canada regulates isotope handling under the Nuclear Safety and Control Act. Ontario and Quebec hospital networks are evaluating cyclotron-based Tc-99m alternatives to reduce generator supply vulnerability.
Nuclear Medicine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates procurement power among integrated hospital networks. Three archetypes dominate: diversified health technology conglomerates with cyclotron manufacturing capabilities, vertically integrated radiopharmaceutical developers with therapy platforms, and specialized radiopharmacy distributors with nationwide logistics networks. Competitive moves center on securing long-term supply agreements with multi-hospital systems and expanding alpha-emitter production partnerships with academic medical centers.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers exemplify archetypes combining imaging equipment manufacturing with tracer production capabilities. Cardinal Health occupies a position representing specialized distribution scale, while Novartis sits within the vertically integrated therapy developer tier. Curium Pharma and Lantheus Holdings exemplify focused radiopharmaceutical specialists. Eckert & Ziegler and NorthStar Medical Radioisotopes represent isotope production technology providers, with Jubilant Pharma anchoring contract manufacturing and radiopharmacy services.
| Leading Market Players |
|---|
| Cardinal Health |
| Novartis |
| Lantheus Holdings |
| GE Healthcare |
| Curium Pharma |
| Jubilant Pharma |
| Siemens Healthineers |
| Eckert & Ziegler |
| NorthStar Medical Radioisotopes |
| Others |
Supply Flow & Price Mechanics
Ac-225 and Pb-212 isotope production costs cascade through radioligand therapy pricing tiers, with alpha-emitter scarcity in Germany and Japan sustaining premium positioning for academic medical centers while diagnostic tracer commoditization compresses FDG margins across centralized radiopharmacies.
Pricing Analysis
Capacity additions in the United States and Germany are reshaping price floors for F-18 diagnostic tracers as compact 11 MeV cyclotrons enable hospital-based production. Three-tier pricing structure across premium, standard, and economy levels separates alpha-emitter radioligand therapies from FDG-PET staging agents and generic Tc-99m perfusion studies. Cost compression in diagnostic tracers is intensifying because unbundled procurement practices force radiopharmacies to disclose cost-plus structures to integrated delivery networks. Community hospital networks exhibit highest price sensitivity for SPECT replacement cycles, while academic medical centers show lowest sensitivity for alpha-emitter supply security.
Supply Chain Analysis
Dual-sourcing requirements from the Nuclear Regulatory Commission and EMA compel radiopharmacies to qualify multiple Mo-99 conversion facilities across the Netherlands, Belgium, and South Africa. Isotope supply draws from aging research reactors, compact cyclotron networks, and emerging accelerator-based production systems. Single-source vulnerability concentrates in Mo-99 generator supply following Canada's NRU reactor closure. Distribution runs through Cardinal Health's nationwide radiopharmacy network and captive hospital-based production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India where CDSCO streamlining meets cyclotron infrastructure gaps, contrasting with saturated reimbursement environments in the United States and Germany.
For Market Incumbents: Deploy backward integration into alpha-emitter production partnerships to secure Ac-225 supply against emerging reactor-to-accelerator transitions. Consolidate diagnostic tracer manufacturing into centralized quality control laboratories to maintain release timelines under EMA GMP Annex 1 pressure. Defensive positioning requires unbundling imaging equipment service contracts from tracer supply agreements before integrated delivery networks force disclosure. For New Entrants and Emerging Players: Begin with Ga-68 imaging agent production in Mumbai and Bangalore where CDSCO import licensing reforms create immediate addressable demand. India's oncology department expansion at private hospital chains represents the most penetrable geography. A theranostics pairing go-to-market angle—matching diagnostic imaging to Lu-177 therapy protocols—differentiates against commoditized FDG suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where radiopharmacist training scarcity constrains site expansion timelines to fewer than fifteen accredited United States centers. Long-term viability favors vertically integrated platforms spanning cyclotron manufacturing through commercial radioligand therapy supply. Watch EMA and FDA manufacturing quality standard tightening as the inflection signal for accelerated M&A among undercapitalized PET tracer producers.| Strategic Initiative | Industry Significance |
|---|---|
| Alpha-Emitter Production Partnership | Academic medical centers in Heidelberg and Boston secure captive Ac-225 supply for radioligand therapy expansion. |
| Microfluidic Radiochemistry Platform Adoption | University hospitals compress tracer synthesis from four hours to ninety minutes for same-day neuroendocrine tumor scheduling. |
| Reimbursement Strategy Alignment | CMS coverage determinations for oncologic PET imaging stabilize payment rates for hybrid PET-CT replacement cycles. |
| Decentralized Cyclotron Siting | Compact 11 MeV systems enable hospital-based F-18 production reducing reliance on centralized radiopharmacies. |
| Regulatory Approval Pathway Navigation | EMA centralized assessment harmonizes manufacturing standards accelerating multi-country trial enrollment for novel agents. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window combining primary discussions with nuclear medicine department heads, radiopharmacists, cyclotron facility managers, GPO contracts managers, and regulatory affairs specialists at FDA and EMA with secondary validation from CMS reimbursement determinations, EMA radiopharmaceuticals guidelines, Nuclear Regulatory Commission licensing databases, and hospital procurement records. Bottom-up isotope demand modeling and top-down market sizing triangulated against cyclotron installation databases and radiopharmaceutical production capacity disclosures.
Segment-weighting approaches calibrated product type splits against procedural volume data from PET-CT and SPECT installed bases, application shares against reimbursement code utilization, and technology mixes against equipment replacement cycle timing. CAGRs derived from regression analysis of historical cyclotron deployment, isotope production capacity expansion, and radioligand therapy patient population modeling across the projection horizon. Forecast inputs incorporated EMA GMP Annex 1 implementation timelines and CMS coverage determination stability assumptions.
Several conditions sit outside the modeled scope, including unannounced research reactor decommissioning schedules, breakthrough alpha-emitter indications beyond prostate and neuroendocrine malignancies, and disruptive accelerator-based Mo-99 production commercialization. Deviation in Mo-99 supply reliability or therapeutic radiopharmaceutical reimbursement determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Teleradiology Services Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Italy Mammography Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Medical Hyperspectral Imaging Market