
 Remanufactured Medical Imaging Devices Market | 2026-2036
Remanufactured Medical Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Remanufactured Medical Imaging Devices Market Intelligence
A shift in customer concentration, where large hospital networks consolidate purchasing power while independent diagnostic centers proliferate, is expanding the addressable market for remanufactured devices. Major OEMs like Siemens Healthineers leverage their established service networks to offer certified remanufactured systems with full warranties. Koninklijke Philips N.V. differentiates through its 'Circular Edition' portfolio, emphasizing sustainability and performance. Independent service organizations such as Block Imaging compete by offering multi-vendor solutions and flexible service contracts to smaller clinics.
Remanufactured medical imaging devices are used systems that undergo complete disassembly, component replacement, and recalibration to meet original equipment manufacturer specifications. This process, distinct from simple refurbishment, includes software updates and rigorous performance testing to ensure clinical equivalency to new machines. Computed Tomography scanners and Magnetic Resonance Imaging systems represent the largest product segments due to their high replacement cost and long service life. Within end-users, diagnostic centers and specialty clinics drive volume, seeking to manage capital expenditures.
Market access is governed by stringent quality and safety standards, such as the FDA's Quality System Regulation in the United States and the Medical Device Regulation in the European Union. Regulators in Japan, like the PMDA, also enforce specific guidelines for used medical equipment. These frameworks mandate documentation of the remanufacturing process and traceability of critical components. Vendor selection will increasingly hinge on demonstrated compliance and the ability to provide robust cybersecurity for networked devices.
Market Dynamics
The market's primary structural force is the increasing pressure on healthcare providers to expand diagnostic imaging capacity while managing severe capital expenditure constraints. This dynamic creates a distinct value proposition for certified remanufactured systems that offer performance equivalent to new equipment at a substantially lower cost.
Growth Catalysts
- Circular Economy Mandates:Policy frameworks, including the EU Green Deal, promote resource efficiency and waste reduction. These initiatives encourage public and private healthcare systems to adopt remanufactured assets as part of their sustainability and procurement strategies.
- Emerging Market Demand:Cost-sensitive healthcare systems in countries like Brazil, India, and Mexico are expanding diagnostic services. Remanufactured devices provide a financially viable pathway to acquire advanced imaging technology like MRI and CT scanners.
- High-Cost Core Equipment:The significant initial investment and long operational life of complex systems such as Computed Tomography and Magnetic Resonance Imaging scanners make remanufacturing an economically attractive alternative to purchasing new units.
Market Restraints
- Stringent Regulatory Hurdles:Compliance with standards like the FDA's Quality System Regulation and the EU's Medical Device Regulation requires significant investment in documentation and process validation, creating barriers for smaller operators.
- Perception of Obsolescence:End-users, particularly in top-tier research hospitals, may harbor concerns about the technological and clinical equivalence of remanufactured systems compared to the latest new models, impacting adoption in some segments.
- Core Unit Scarcity:The availability of high-quality, late-model used systems for remanufacturing is dependent on the replacement cycles of large hospitals. A limited supply of these "cores" can constrain production and increase input costs.
Strategic Opportunities
- Service-Based Models:Developing subscription or fee-per-scan models for remanufactured equipment can appeal to smaller clinics and diagnostic centers by converting large capital outlays into predictable operational expenses.
- Cybersecurity Integration:Embedding advanced cybersecurity features and ongoing support for networked devices presents an opportunity to differentiate products and address a critical concern for hospital IT departments.
- Targeted Geographic Expansion:Establishing certified sales and service centers in high-growth regions like Latin America and Southeast Asia can capture demand from healthcare providers seeking to expand imaging capabilities affordably.
Industry Challenges
- Specialized Talent Shortages:The remanufacturing process demands highly skilled engineers and technicians proficient in multi-vendor hardware and software. A scarcity of this specialized expertise can limit a firm's capacity and quality.
- Software Licensing Complexity:Securing the rights to use and update proprietary OEM software on remanufactured systems is a persistent legal and operational challenge that can affect device functionality and compliance.
- International Standards Harmonization:Navigating the divergent and evolving regulatory requirements for used medical devices across jurisdictions, such as those from the FDA, PMDA, and EU authorities, adds complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remanufactured Medical Imaging Devices Market |
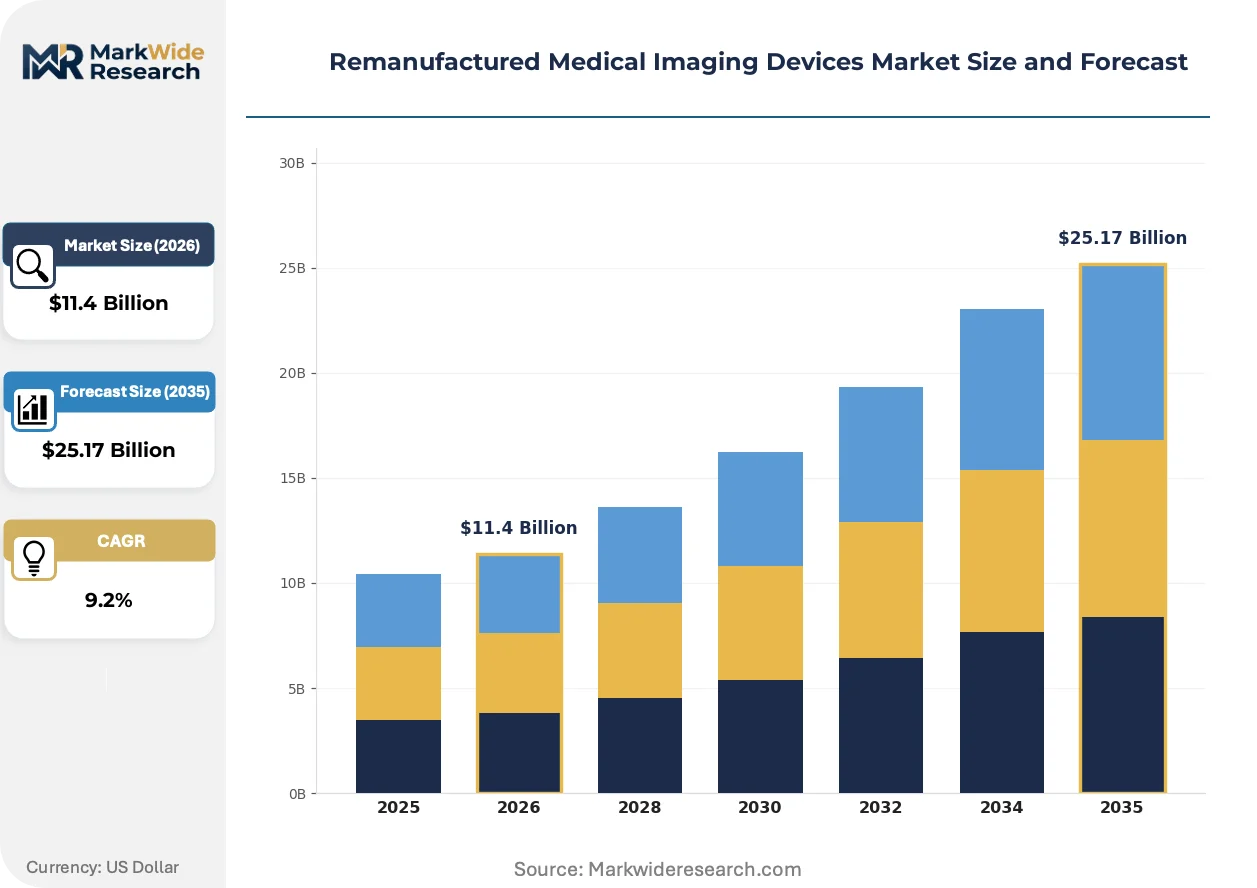
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $25.17 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, Ultrasound Machines, Magnetic Resonance Imaging, Computed Tomography Scanners, Nuclear Imaging Devices Technology: Digital Radiography, Analog Radiography, 3D Imaging, Fluoroscopy, Tomosynthesis Application: Cardiology, Orthopedics, Neurology, Oncology, Pulmonology End User: Diagnostic Centers, Specialty Clinics, Ambulatory Surgical Centers, Medical Research Institutes, Outpatient Facilities |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Hitachi Healthcare Systems, Block Imaging, Soma Technology, Agito Medical A/S, FUJIFILM Healthcare Americas Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remanufactured Medical Imaging Devices Market Strategic Shifts & Innovations
The market is undergoing a significant maturation, shifting from a price-driven secondary channel to a quality-assured, professionalized industry. This evolution is defined by the integration of advanced software, adherence to rigorous global regulations, and new circular procurement behaviors among healthcare providers.
Artificial intelligence and advanced visualization software are being retrofitted onto older hardware platforms. These software-defined upgrades enhance image quality and provide new diagnostic capabilities, such as automated lesion detection. This trend **is integrating** sophisticated analytical tools into remanufactured systems, extending their clinical utility and allowing smaller facilities to access cutting-edge technology without purchasing entirely new machines.
The European Union's Medical Device Regulation (MDR) is setting a higher global bar for quality and safety. It classifies remanufacturers as device manufacturers, mandating comprehensive quality management systems and post-market surveillance. Remanufacturers targeting the EU market are now required to provide extensive technical documentation and traceability, a standard that is influencing practices in other regions.
A notable behavioral change is the adoption of total cost of ownership (TCO) as a primary procurement metric. Healthcare financial administrators are moving beyond initial purchase price to evaluate long-term service, upgrade, and energy costs. This shift benefits certified remanufactured systems, which often present a superior TCO profile, particularly within the budget-conscious diagnostic center and specialty clinic segments.
Remanufactured Medical Imaging Devices Market Segmentation
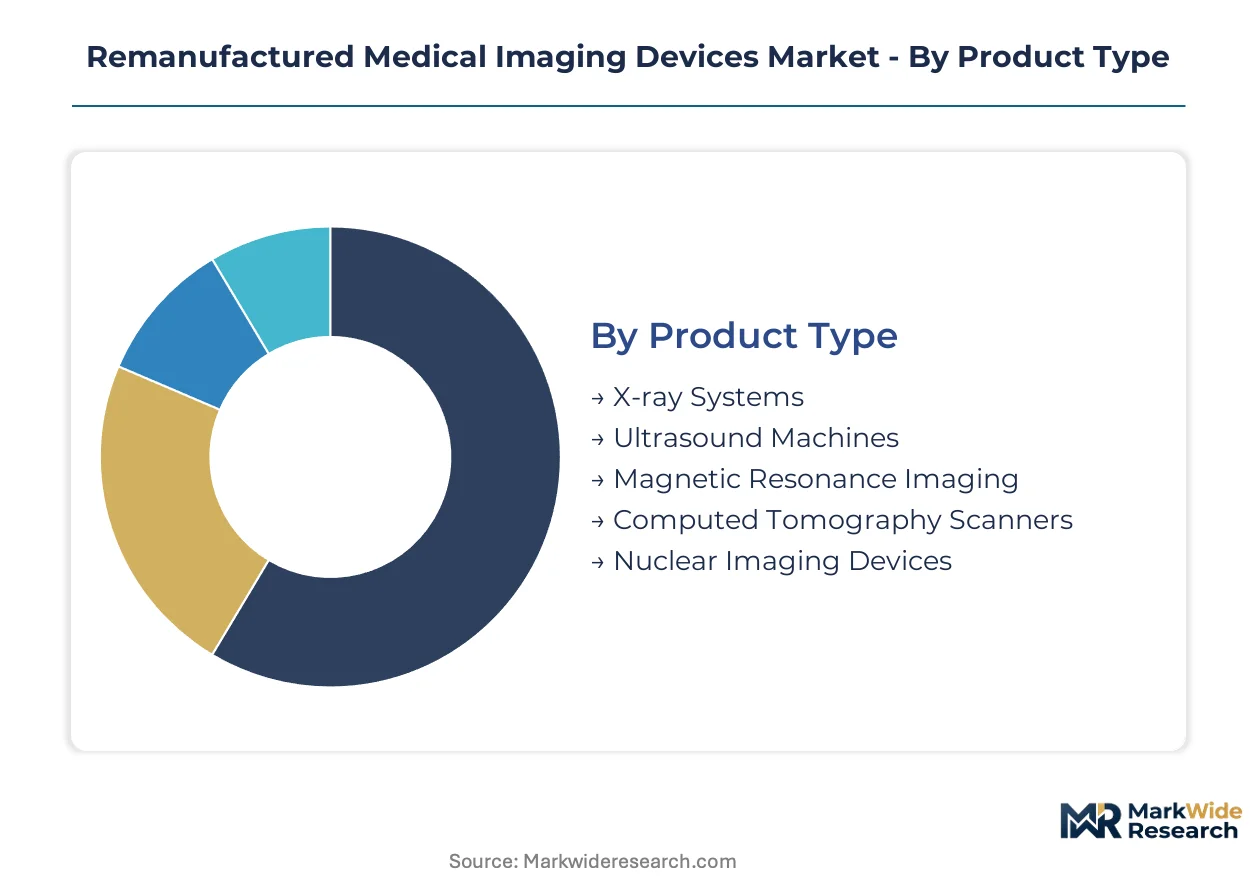
The Remanufactured Medical Imaging Devices Market segments across product type, technology, application, and end-user, illustrating how cost-effectiveness and advanced diagnostic capabilities intersect. Understanding these distinctions allows stakeholders to identify optimal entry points and target specific healthcare provider needs. Each segment reflects unique operational demands and technological requirements within the broader healthcare ecosystem.
Product Type:
The product type segmentation highlights the balance between high-value, complex systems and more ubiquitous imaging modalities, influencing procurement strategies. High-cost core equipment like MRI and CT scanners dominate the premium end of the remanufactured market.
- Magnetic Resonance Imaging:These systems utilize powerful magnetic fields and radio waves to generate detailed images of organs and soft tissues, crucial for neurology and oncology diagnostics. Demand concentrates in advanced diagnostic centers seeking high-resolution imaging without the full investment of new units.
- Computed Tomography Scanners:CT scanners combine multiple X-ray images from different angles to produce cross-sectional views of the body, essential for trauma, vascular, and cancer screening. Specialty clinics and emergency departments in emerging economies drive volume, prioritizing rapid diagnostic throughput.
- X-ray Systems:These foundational imaging devices produce two-dimensional images of bones and dense tissues, widely used for basic diagnostics in various clinical settings.
- Ultrasound Machines:Ultrasound technology uses high-frequency sound waves to visualize internal body structures, offering real-time imaging capabilities particularly valuable in obstetrics and cardiology.
- Nuclear Imaging Devices:These systems detect radiation emitted from radiopharmaceuticals administered to patients, providing functional rather than anatomical information, critical for assessing organ function and disease progression.
Today's leader: Magnetic Resonance Imaging. Tomorrow's challenger: Computed Tomography Scanners.
Technology:
The underlying technological sophistication defines both clinical utility and remanufacturing complexity, with digital solutions increasingly displacing older analog systems. Modern remanufacturing processes integrate software upgrades to enhance functionality across diverse platforms.
- Digital Radiography:This technology converts X-ray energy directly into digital images, offering immediate viewing, enhanced image quality, and easier storage compared to traditional film-based systems. Diagnostic centers prioritize these systems for improved workflow efficiency and reduced environmental impact.
- 3D Imaging:This advanced capability reconstructs two-dimensional images into three-dimensional models, providing greater anatomical detail and aiding in complex surgical planning and diagnosis. Specialty clinics in urban areas leverage these technologies to offer advanced patient care.
- Analog Radiography:Traditional X-ray systems rely on film for image capture, representing a legacy technology with lower initial costs but higher operational expenses.
- Fluoroscopy:This imaging technique provides real-time moving images of internal structures, often used for guiding medical procedures like catheter insertions and orthopedic surgeries.
- Tomosynthesis:A specialized X-ray imaging method creating 3D images of the breast, significantly improving cancer detection rates compared to standard mammography.
The rapid evolution of Digital Radiography technology pushes continuous upgrades across the installed base.
Application:
Clinical applications for remanufactured imaging devices reflect diverse patient needs and diagnostic priorities, with high-prevalence diseases driving significant demand. Specialized areas require specific imaging modalities for accurate diagnosis and treatment planning.
- Oncology:Diagnostic imaging plays a critical role in cancer detection, staging, and monitoring treatment efficacy, requiring high-resolution MRI and CT scans. Cancer treatment centers prioritize remanufactured systems to manage capital costs while maintaining diagnostic precision for a growing patient population.
- Cardiology:Imaging is essential for diagnosing heart conditions, assessing cardiac function, and guiding interventional procedures, with ultrasound and MRI being key modalities. Hospitals and cardiac clinics utilize these devices for non-invasive assessment of cardiovascular health.
- Orthopedics:This application focuses on musculoskeletal conditions, primarily using X-ray and MRI for diagnosing fractures, joint diseases, and soft tissue injuries.
- Neurology:Imaging of the brain and nervous system is crucial for diagnosing strokes, tumors, and degenerative diseases, heavily relying on MRI and CT technologies.
- Pulmonology:Lung imaging, often through CT scans and X-rays, is vital for diagnosing respiratory conditions, infections, and lung cancer.
The expanding scope of Oncology diagnostics drives demand for specialized imaging solutions.
End User:
End-user segments differentiate by their operational models and capital expenditure priorities, with smaller facilities showing significant uptake of remanufactured equipment. Cost-sensitive environments often find remanufactured devices to be a strategic investment.
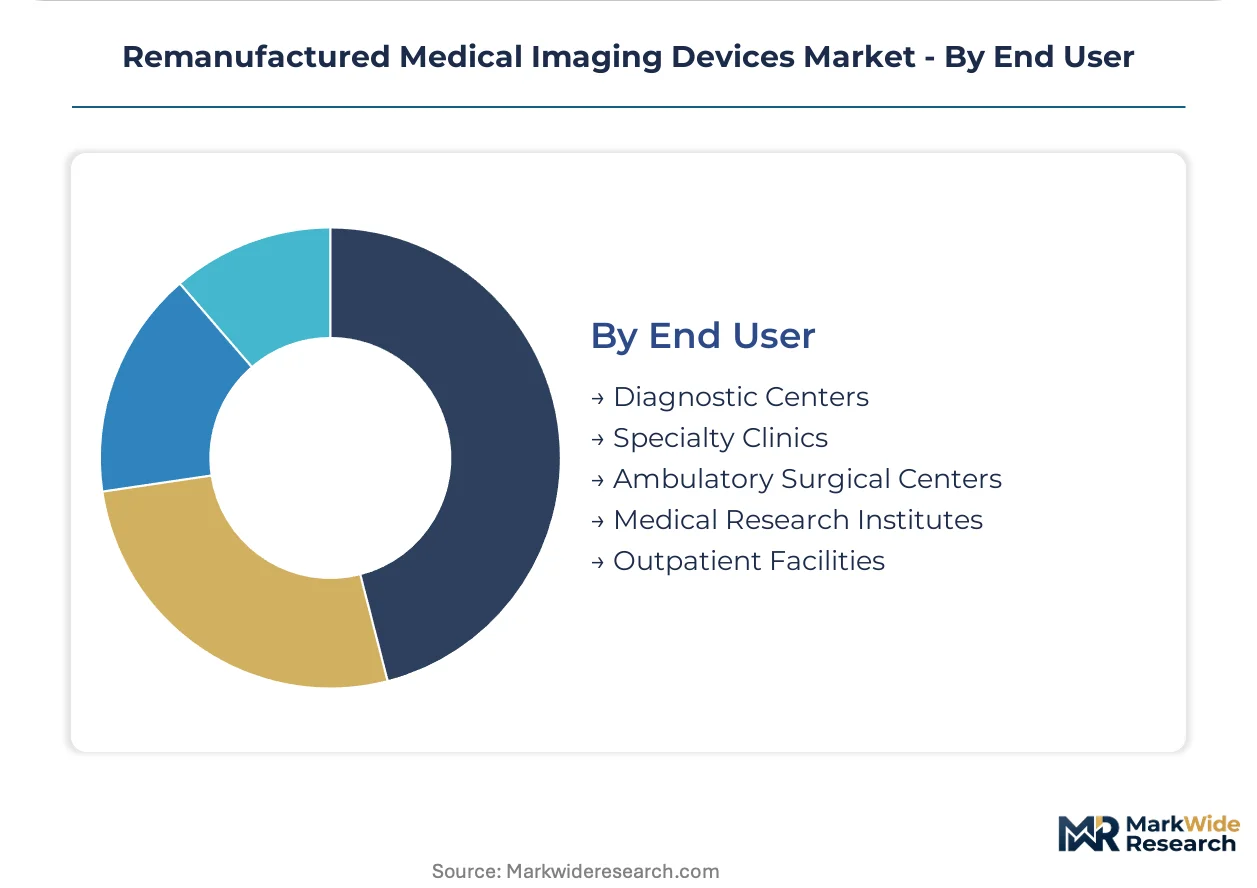
- Diagnostic Centers:These specialized facilities focus solely on providing imaging services, requiring a broad range of modalities to serve diverse patient needs. They represent a primary volume driver for remanufactured systems, seeking to offer advanced diagnostics affordably.
- Specialty Clinics:Clinics focusing on specific medical areas, such as orthopedics or women's health, require targeted imaging equipment to support their specialized services. These clinics value remanufactured devices for their ability to acquire high-performance technology within budget constraints.
- Ambulatory Surgical Centers:ASCs perform outpatient surgical procedures, utilizing imaging equipment for pre-operative assessments and intra-operative guidance.
- Medical Research Institutes:These institutions use imaging devices for clinical trials and scientific studies, often requiring advanced capabilities but with budget limitations for new equipment.
- Outpatient Facilities:General outpatient clinics provide primary care services and often require basic imaging capabilities like X-ray and ultrasound for initial patient assessments.
The continued expansion of Diagnostic Centers highlights the need for cost-effective imaging solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's demand for cost-effective advanced imaging contrasts sharply with Germany's focus on circular economy mandates for medical devices. Both countries, however, recognize the value of extending equipment lifecycles. This global trend underscores the growing acceptance of remanufactured systems.
United States
Demand for remanufactured systems stems from ambulatory surgical centers managing capital expenditures. The FDA's Quality System Regulation ensures device safety and performance. Major OEMs in the Boston area integrate remanufacturing into their service portfolios.
Germany
Circular economy mandates, particularly the EU Green Deal, promote the adoption of remanufactured medical assets. The Medical Device Regulation (MDR) sets stringent quality and safety standards for these systems. Siemens Healthineers in Erlangen develops certified remanufactured systems.
India
Expanding diagnostic services in cost-sensitive healthcare systems drives the acquisition of advanced remanufactured imaging technology. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, including used equipment. Mumbai's healthcare providers seek affordable MRI and CT scanners.
Brazil
Healthcare providers seek financially viable pathways to acquire advanced imaging technology like MRI and CT scanners. ANVISA, the national health surveillance agency, oversees medical device regulations. São Paulo's private clinics prioritize remanufactured equipment for expanded diagnostic capacity.
Mexico
The need to expand diagnostic imaging capacity while managing capital expenditure constraints fuels demand for remanufactured systems. COFEPRIS, the federal commission for protection against health risks, regulates medical devices. Mexico City's diagnostic centers benefit from lower acquisition costs.
Remanufactured Medical Imaging Devices Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the remanufactured medical imaging devices market. The market structure exhibits a tiered approach, with major original equipment manufacturers (OEMs) at the premium end and independent service organizations providing cost-effective alternatives. Strategic archetypes include OEM-certified remanufacturers, multi-vendor solution providers, and regional specialists. Dominant competitive moves involve leveraging established service networks and offering flexible service contracts.
Within the OEM-certified remanufacturing segment, Germany-based Siemens Healthineers and Netherlands-based Koninklijke Philips N.V. exemplify companies that integrate remanufactured systems into their established sales channels. These players emphasize full warranties and sustainability initiatives like Philips' 'Circular Edition' portfolio. Independent service organizations such as Block Imaging occupy a position offering multi-vendor solutions and tailored service contracts to smaller clinics, catering to a different segment of the market.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Hitachi Healthcare Systems |
| Block Imaging |
| Soma Technology |
| Agito Medical A/S |
| FUJIFILM Healthcare Americas Corporation |
| Others |
Cost & Logistics Intelligence
Specialized component costs, such as high-value sensors and proprietary software licenses, directly influence pricing for remanufactured medical imaging devices. These upstream inputs flow through certified remanufacturing processes to reach diagnostic centers and specialty clinics.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for entry-level remanufactured CT and X-ray systems. The dominant pricing structure is per-unit transactional, often bundled with multi-year service contracts. Price differentiation stems from the certification level, distinguishing OEM-certified offerings from independent service organization solutions, and the extent of after-sales service. Pricing softness reflects the increasing availability of lower-cost alternatives in emerging markets, where diagnostic centers exhibit the highest price sensitivity compared to research hospitals prioritizing advanced features.
Supply Chain Analysis
Direct-to-clinic distribution channels, supported by regional service hubs, are prevalent for remanufactured medical imaging devices. Geographic supply concentration for high-value core units originates primarily from the United States and Germany. Component dependencies include specialized X-ray tubes, MRI magnets, and proprietary software licenses. A structural supply chain risk involves the limited availability of high-quality, late-model core units, which can constrain production and increase input costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a geographic-arbitrage play, as lower labor costs in emerging markets like India allow for more cost-effective remanufacturing of complex medical imaging systems. This differential enables broader access to advanced diagnostics.
For Market Incumbents: Anticipate increased competition from independent service organizations by deepening vertical integration into proprietary software updates. Consolidate market share through strategic acquisitions of smaller, regional remanufacturers, particularly in Latin America. The threat of regulatory fragmentation across various jurisdictions necessitates investment in harmonized certification processes. Leverage established service networks to offer comprehensive after-sales support and full warranties, a key lever against emerging entrants.
For New Entrants and Emerging Players: Capture white-space demand in underserved rural clinics by offering flexible, fee-per-scan models for remanufactured ultrasound systems. Target the orthopedic specialty clinic segment in Southeast Asia, which presents a highly penetrable market due to rising musculoskeletal conditions. A go-to-market angle should emphasize multi-vendor compatibility and robust cybersecurity features for networked devices. Develop partnerships with local healthcare providers to build trust and tailor solutions.
For Investors and Strategic Acquirers: Roll-up economics work for specialized remanufacturing firms because regulatory compliance costs favor scale and operational efficiencies. The long-term viability of this market is strong, driven by persistent capital expenditure constraints in healthcare globally. Target independent service organizations with established multi-vendor expertise and strong regional service footprints as acquisition candidates. The signal to watch is the increasing adoption of circular economy mandates in new geographies, indicating expanding addressable markets.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM-Certified Remanufacturing Program Expansion | Siemens Healthineers and Philips can leverage their brand reputation to capture premium segments seeking guaranteed performance. |
| Subscription-Based Service Model Launch | Smaller diagnostic centers in Brazil and Mexico gain access to advanced CT scanners without large upfront capital outlays. |
| Cybersecurity Feature Integration | Hospital IT departments prioritize networked medical devices with robust protection against data breaches and operational disruptions. |
| Multi-Vendor Service Network Development | Independent service organizations like Block Imaging can provide comprehensive maintenance for diverse equipment portfolios, enhancing customer loyalty. |
| Targeted Emerging Market Entry | Healthcare providers in India can affordably expand diagnostic imaging capacity, addressing critical public health needs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary research included discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and remanufacturing facility operators. Secondary data sources encompassed FDA and EU MDR filings, industry association reports, and academic literature. Bottom-up data aggregation and top-down market sizing were triangulated for comprehensive accuracy.
Historical performance data from comparable periods anchored the forecast window, establishing baseline growth trajectories. The analytical framework modeled market segments by product type, technology, application, end-user, and certification level. CAGRs were derived through regression analysis of historical trends and projected adoption rates. Key forecast inputs included capital expenditure budgets of diagnostic centers and evolving regulatory mandates.
Regulatory shifts, core unit scarcity, and technological obsolescence are the dominant revision risks for market forecasts. All projections reflect assumptions about healthcare spending and remanufacturing process advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Brazil Mammography Market