
 Magnetic Resonance Analyzer Market | 2026-2036
Magnetic Resonance Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Resonance Analyzer Market Outlook
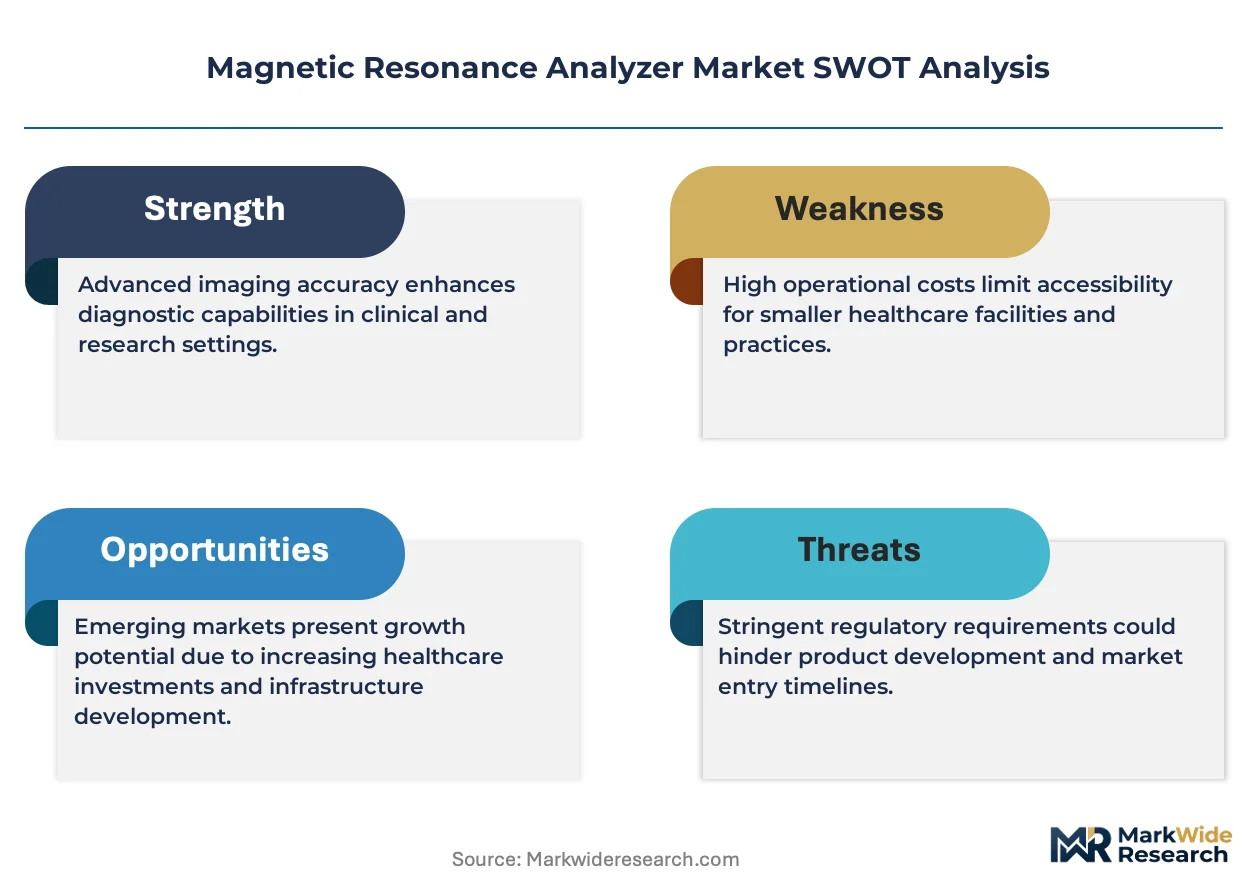
EU MDR is recalibrating the cost-of-entry calculus for magnetic resonance analyzer manufacturers seeking CE marking in European markets. Siemens Healthineers leverages its established regulatory affairs infrastructure to navigate expanded clinical evidence requirements. GE Healthcare anchors its competitive stance through deep integration with hospital capital procurement cycles. Koninklijke Philips N.V. differentiates via specialized open-bore configurations that address bariatric and claustrophobic patient populations.
A magnetic resonance analyzer is an electromagnetic diagnostic instrument that applies superconducting magnets generating field strengths from 0.2 to 7.0 Tesla, paired with radiofrequency coils and gradient systems, to produce tomographic images of soft tissue and metabolic spectra for clinical diagnosis and biomedical research. Closed-bore systems dominate installed base value due to superior signal-to-noise ratios, while open-bore configurations capture growing share in interventional suites and pediatric settings where patient access and comfort constrain conventional geometry. Functional MRI technology leads research institution procurement, though diffusion MRI applications in acute stroke protocols drive replacement demand across hospital radiology departments.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape product development timelines and commercial launch sequencing for manufacturers. China's NMPA has tightened electromagnetic compatibility testing standards for imported imaging equipment, extending registration cycles for multinational suppliers. Japan's PMDA maintains distinct software-as-medical-device classifications that affect AI-enabled reconstruction algorithms. Stakeholders must monitor evolving reimbursement coding for spectroscopic applications to anticipate capital allocation shifts across diagnostic center networks.
Market Dynamics
EU MDR recertification timelines are compressing product launch windows for high-field magnetic resonance analyzers, forcing manufacturers to front-load clinical evidence generation and restructure regulatory affairs teams before legacy certificates expire.
Growth Catalysts
- Diffusion-weighted imaging protocols:Stroke centers in the United States are mandating rapid MRI triage capabilities, accelerating replacement cycles for aging 1.5 Tesla installations in hospital emergency departments.
- Japan's PMDA software-as-medical-device pathway:AI-enabled reconstruction algorithms now qualify for expedited review, stimulating vendor investment in machine learning-based scan acceleration tools for research institutions.
- Helium conservation technologies:Closed-loop cryogenic systems are reducing dependency on volatile helium supply chains, enabling stable operational economics for diagnostic imaging networks in helium-constrained markets.
Market Restraints
- Superconducting wire supply concentration:Niobium-titanium filament production concentrates among a limited set of specialized metallurgical suppliers, exposing manufacturers to input cost volatility and allocation constraints.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations and notified body capacity bottlenecks are extending CE marking timelines by eighteen to thirty-six months for new high-field system submissions.
- CT angiography substitution:Emergency departments facing capital constraints are defaulting to computed tomography for acute vascular imaging, constraining MRI penetration in time-critical diagnostic pathways.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of high-value diagnostic equipment are attracting component localization investments from multinational imaging vendors.
- Interventional MRI suites:Real-time intraoperative imaging for neurosurgical and cardiac ablation procedures represents an underdeveloped application segment with premium pricing potential and limited installed base competition.
- Cloud-native reconstruction pipelines:Edge-to-cloud architectures are enabling diagnostic centers to decouple acquisition hardware from computational infrastructure, opening subscription-based service models for capital-constrained purchasers.
Industry Challenges
- Clinical application specialist scarcity:Radiologists with dual competency in advanced MRI sequences and quantitative biomarker interpretation command premium compensation, constraining workforce scalability for new site deployments.
- Legacy PACS integration complexity:Hospital IT departments face protracted vendor negotiation cycles when connecting modern MRI systems to aging picture archiving infrastructure, delaying operational revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Resonance Analyzer Market |
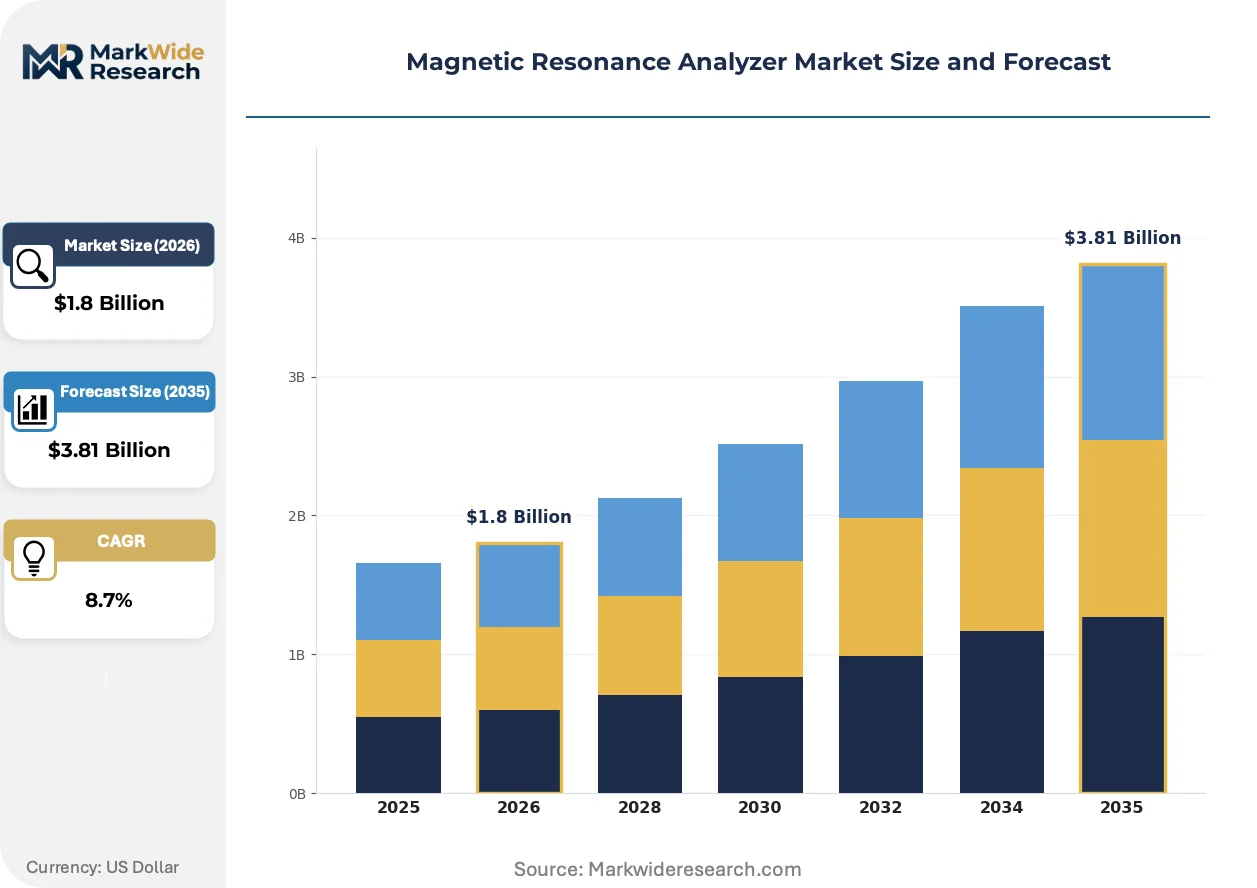
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-Bore Systems, Open-Bore Systems, High-Field Systems, Low-Field Systems End User: Hospitals, Diagnostic Centers, Research Institutions, Academic Laboratories Application: Oncology, Neurology, Cardiovascular, Musculoskeletal Technology: Functional MRI, Diffusion MRI, Spectroscopic MRI, Magnetic Resonance Spectroscopy |
| Companies Covered | Shenzhen Bowei Technology Co. Ltd, Guangzhou San Hong Tech Co. Ltd, Guangzhou EHM Group Limited, Jiangsu TONGREN Medical Electronic Technology Co. Ltd, Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., FUJIFILM, Canon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Resonance Analyzer Market Strategic Shifts
Artificial intelligence is penetrating every layer of magnetic resonance workflow, from acquisition acceleration through automated quality assurance, compressing scan durations and expanding throughput economics for fixed-capital installations.
Compressed sensing reconstruction algorithms are overtaking conventional Nyquist-sampled acquisitions in research hospital procurement specifications. Neuroradiology departments at academic medical centers are specifying AI-accelerated protocols as mandatory bid requirements. This compression of acquisition time is enabling higher patient throughput without magnet field strength upgrades, reshaping replacement cycle economics for mid-field systems.
REACH restrictions on per- and polyfluoroalkyl substances are compelling magnet manufacturers to reformulate electrical insulation and cooling system components. Industrial chemical substitution programs are absorbing engineering resources and extending prototype validation timelines. European OEMs are responding by accelerating in-house materials science capabilities and qualifying alternative fluoropolymer suppliers from Asian markets.
Diagnostic networks are unbundling equipment procurement from service contracts, fragmenting vendor revenue streams and compressing margin capture. Independent service organizations are capturing multi-vendor maintenance contracts previously held by original equipment manufacturers. This disintermediation is most advanced in the United States, where third-party parts sourcing and remote monitoring capabilities have matured sufficiently to satisfy hospital risk management frameworks.
Magnetic Resonance Analyzer Market Segmentation
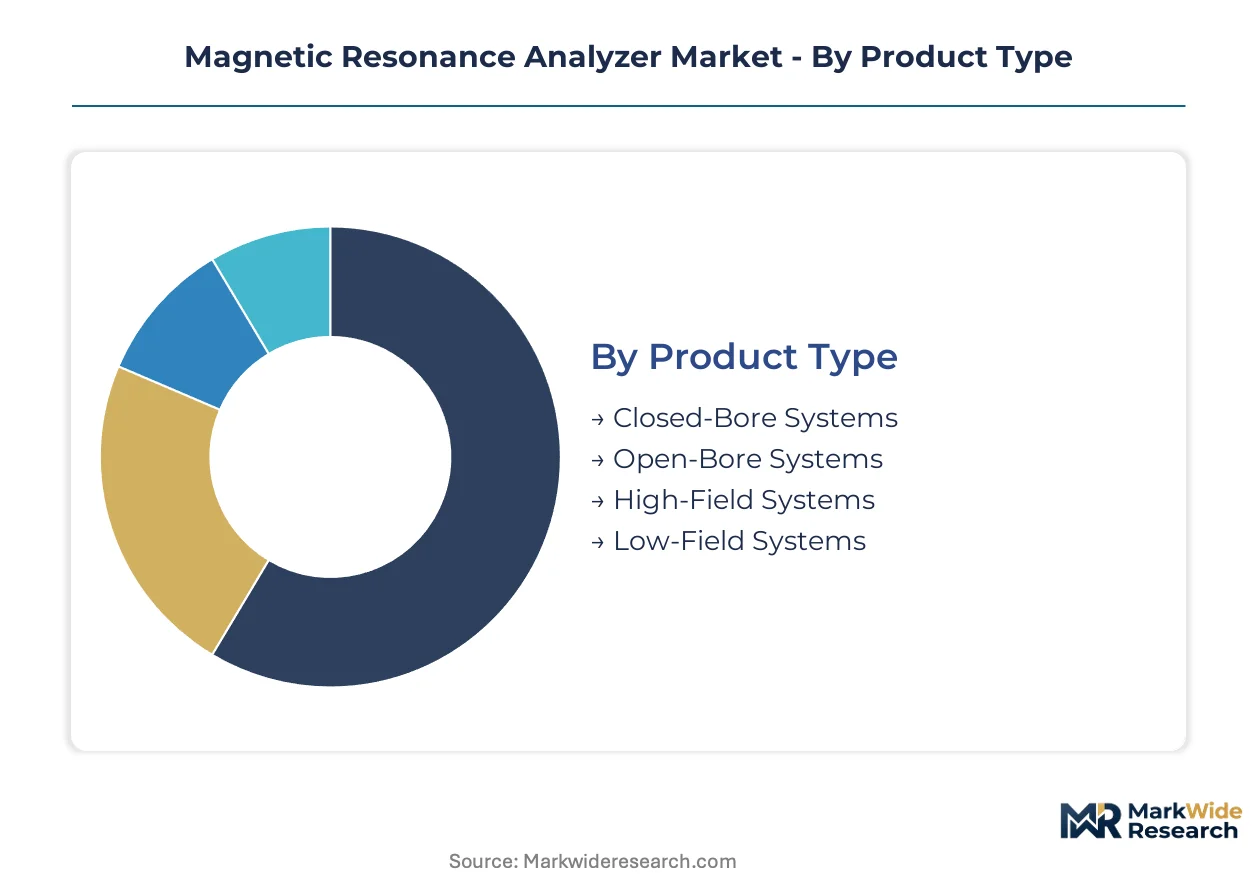
Magnetic resonance analyzer segmentation reveals divergent margin structures across hardware configurations and sharply differentiated procurement patterns between clinical and research buyers. Understanding these fault lines enables targeted positioning for capital equipment vendors navigating compressed replacement cycles.
Product Type:
Closed-bore systems command premium installed base value through superior signal fidelity, while open-bore configurations address accessibility constraints that limit conventional geometry adoption.
- Closed-Bore Systems:Superconducting magnets with cylindrical patient enclosures generate field strengths from 1.5 to 7.0 Tesla, delivering optimal signal-to-noise ratios for diagnostic precision. Hospital radiology departments in the United States concentrate procurement here, driven by Medicare reimbursement differentials favoring high-field diagnostic accuracy.
- Open-Bore Systems:Vertical or C-shaped magnet architectures accommodate bariatric patients and claustrophobic populations excluded from conventional scanners. Pediatric hospitals and interventional suites are expanding adoption fastest, as real-time procedural guidance requirements override signal fidelity trade-offs.
- High-Field Systems:Research institutions and specialized neuroimaging centers specify 3.0 Tesla and above for functional and spectroscopic applications requiring maximal spatial resolution.
- Low-Field Systems:Point-of-care deployments and veterinary diagnostics favor sub-1.0 Tesla permanent magnet designs for operational simplicity and helium independence.
Today's leader: Closed-Bore Systems. Tomorrow's challenger: Open-Bore Systems.
End User:
Procurement authority concentrates in integrated health networks with centralized capital allocation committees, fragmenting vendor access for standalone purchasers.
- Hospitals:Emergency stroke protocols and surgical planning requirements anchor replacement demand. Academic medical centers in Germany and the United States are specifying AI-accelerated sequences as mandatory bid criteria.
- Diagnostic Centers:Independent imaging networks prioritize throughput economics and multi-modality site certification for payer contract eligibility. India's diagnostic chains are expanding fastest under PLI scheme incentives for domestic equipment manufacturing.
- Research Institutions:Functional MRI and spectroscopic applications drive procurement with distinct technical specifications and extended validation timelines.
- Academic Laboratories:Preclinical and materials science applications favor small-bore systems with specialized radiofrequency coils for ex vivo tissue analysis.
Hospitals retain volume dominance. Diagnostic centers are climbing the fastest as outpatient migration accelerates.
Application:
Oncology and neurology applications command premium pricing through specialized coil arrays and contrast-enhanced protocols that justify higher reimbursement coding.
- Oncology:Multiparametric imaging for tumor characterization and treatment response monitoring requires advanced diffusion and perfusion sequences. Comprehensive cancer centers in the United States and Japan are standardizing 3.0 Tesla platforms for radiation therapy planning integration.
- Neurology:Functional MRI for preoperative mapping and diffusion tensor imaging for white matter tractography anchor academic medical center procurement. FDA 510(k) clearances for AI-enabled lesion detection are accelerating replacement cycles.
- Cardiovascular:Stress perfusion and late gadolinium enhancement protocols compete with CT angiography for ischemic evaluation, constraining penetration in emergency settings.
- Musculoskeletal:Dedicated extremity coils and high-resolution sequences for cartilage and ligament assessment serve orthopedic specialty practices and sports medicine clinics.
Neurology leads research investment. Oncology drives the steepest expansion trajectory through precision medicine alignment.
Technology:
Reconstruction algorithm sophistication now differentiates competitive positioning more than magnet field strength alone.
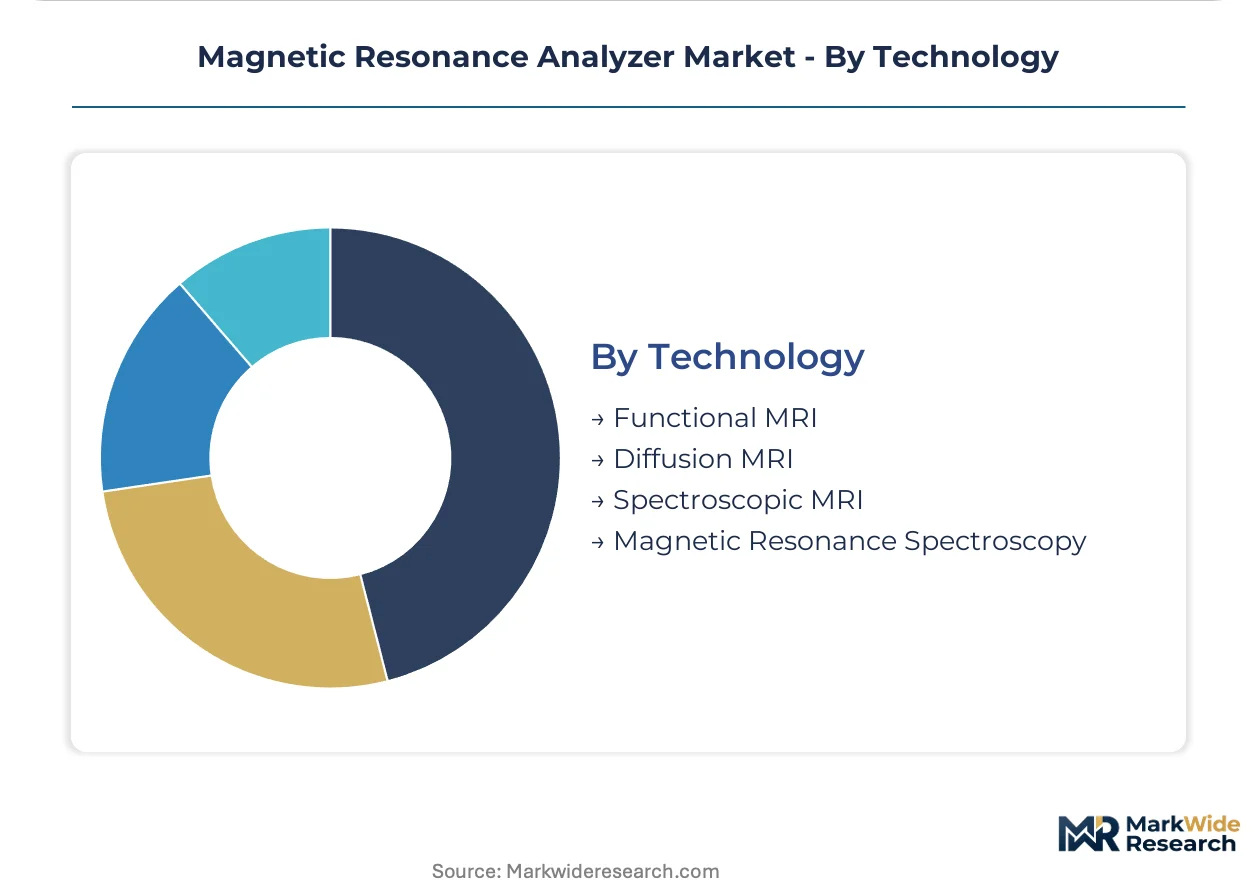
- Functional MRI:Blood-oxygen-level-dependent signal detection for neural activation mapping requires specialized gradient systems and real-time motion correction. Japan's PMDA software-as-medical-device pathway is accelerating vendor investment in machine learning-based analysis tools.
- Diffusion MRI:Apparent diffusion coefficient mapping for acute ischemia detection has become mandatory for stroke center certification in the United States, forcing emergency department capability upgrades.
- Spectroscopic MRI:Metabolite quantification for tumor grading and neurodegenerative assessment remains limited by reimbursement coding gaps and specialized interpreter scarcity.
- Magnetic Resonance Spectroscopy:Standalone spectroscopic systems for research and pharmaceutical metabolism studies occupy a niche with dedicated hardware requirements distinct from imaging platforms.
Diffusion MRI dominates clinical urgency. Functional MRI commands the premium research position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologists with dual competency in advanced MRI sequences and quantitative biomarker interpretation concentrate in the United States, Germany, and Japan, anchoring regional demand patterns for high-field diagnostic installations.
United States
Stroke center certification mandates and Medicare reimbursement differentials for high-field diagnostic accuracy drive hospital radiology department procurement. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking commercial launch sequencing. Academic medical centers in Boston and Houston specify AI-accelerated sequences as mandatory bid criteria.
Germany
Comprehensive cancer centers standardize 3.0 Tesla platforms for radiation therapy planning integration, anchoring replacement demand. EU MDR recertification timelines compress product launch windows, forcing manufacturers to front-load clinical evidence generation. The Rhine-Ruhr metropolitan region hosts concentrated diagnostic imaging networks undergoing capability upgrades.
China
Diagnostic center chains expand fastest under domestic manufacturing incentives for high-value medical electronics. NMPA has tightened electromagnetic compatibility testing standards for imported imaging equipment, extending registration cycles for multinational suppliers. Shanghai and Beijing clusters concentrate procurement authority for centralized capital allocation committees.
Japan
Research institutions drive functional MRI procurement with distinct technical specifications and extended validation timelines. PMDA software-as-medical-device classifications affect AI-enabled reconstruction algorithms, stimulating vendor investment in machine learning-based scan acceleration tools. The Kanto region around Tokyo anchors neuroimaging center density.
India
Independent imaging networks prioritize throughput economics and multi-modality site certification for payer contract eligibility. PLI scheme incentives for domestic manufacturing of high-value diagnostic equipment attract component localization investments from multinational vendors. Maharashtra and Karnataka diagnostic chains expand fastest under production-linked incentive structures.
Magnetic Resonance Analyzer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between scale-driven original equipment manufacturers and agile component suppliers. Three archetypes dominate: integrated health technology conglomerates with established regulatory affairs infrastructure, specialized imaging equipment fabricators with regional manufacturing footprints, and emerging domestic champions leveraging local incentive schemes. Competitive moves concentrate on regulatory pre-positioning ahead of EU MDR certificate expirations and cloud-native service model development for capital-constrained purchasers.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify scale-driven archetypes with deep hospital capital procurement integration. Koninklijke Philips N.V. occupies a differentiated position through specialized hardware configurations. Chinese limited liability companies including Shenzhen Bowei Technology Co. Ltd, Guangzhou San Hong Tech Co. Ltd, and Jiangsu TONGREN Medical Electronic Technology Co. Ltd represent the domestic champion tier serving price-sensitive procurement segments.
| Leading Market Players |
|---|
| Shenzhen Bowei Technology Co. Ltd |
| Guangzhou San Hong Tech Co. Ltd |
| Guangzhou EHM Group Limited |
| Jiangsu TONGREN Medical Electronic Technology Co. Ltd |
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| FUJIFILM |
| Canon |
| Others |
Value Chain & Pricing Dynamics
Helium spot price volatility cascades through magnetic resonance analyzer manufacturing tiers, compressing margins on mid-field systems while reinforcing premium positioning for closed-loop cryogenic platforms in hospital procurement cycles.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning across procurement segments. Three-tier pricing structure across premium, standard, and economy levels reflects field strength gradations, with 3.0 Tesla and above commanding substantial premiums for stroke center certification compliance. Price differentiation rests on AI-accelerated sequence availability and EU MDR certificate status. Cost compression in economy-tier permanent magnet systems is intensifying because domestic Chinese vendors exploit PLI scheme subsidies. Independent diagnostic centers exhibit highest price sensitivity, while academic medical centers prioritize technical specifications over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for superconducting wire now appear in procurement specifications from German and Japanese hospital networks. Niobium-titanium filament production concentrates in the United States, Japan, and Germany, with limited qualified metallurgical suppliers constraining manufacturer flexibility. Component dependencies extend to radiofrequency coil arrays, gradient power electronics, and liquid helium cryogenic systems. Single-source vulnerability in niobium mining and refining exposes OEMs to input allocation constraints. Distribution runs through integrated health network capital committees in developed markets and third-party imaging equipment distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetic resonance analyzer market functions as a stable compounder anchored by irreplaceable clinical utility in acute stroke protocols and oncology staging across developed healthcare systems.
For Market Incumbents: Anticipate margin compression from independent service organizations capturing multi-vendor maintenance contracts previously held by original equipment manufacturers. Siemens Healthineers and GE Healthcare should deepen backward integration into superconducting wire supply through captive metallurgical partnerships or long-term offtake agreements with Japanese and German suppliers. Certification investment in EU MDR clinical evidence generation represents the critical defensive lever ahead of legacy certificate expirations.
For New Entrants and Emerging Players: India's PLI scheme for medical electronics opens a window for component localization plays targeting price-sensitive diagnostic center chains in Maharashtra and Karnataka. White-space targets include interventional MRI suites for real-time neurosurgical guidance and cloud-native reconstruction pipelines enabling subscription-based service models. The most penetrable segment comprises capital-constrained outpatient imaging networks seeking to decouple acquisition hardware from computational infrastructure. A software-as-medical-device go-to-market angle through Japan's PMDA pathway accelerates time-to-revenue for AI-enabled scan acceleration tools.
For Investors and Strategic Acquirers: Consolidation pressure builds where third-party service organizations achieve sufficient scale to satisfy hospital risk management frameworks and capture multi-vendor contracts. The market supports long-term viability through recurring revenue streams from contrast agent protocols, coil array upgrades, and AI software companion sales. Acquisition target archetypes include specialized radiofrequency coil fabricators with proprietary designs for extremity and cardiac applications. The signal to monitor is reimbursement coding expansion for spectroscopic MRI applications, which would trigger capital allocation shifts across diagnostic center networks and accelerate replacement cycles for aging installed bases.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification timelines compress launch windows for high-field systems in German and French hospital networks. |
| Hospital System Partnership | Integrated health network procurement committees concentrate vendor access and anchor replacement demand in United States stroke centers. |
| Software Companion Development | Japan's PMDA software-as-medical-device classification accelerates commercialization of AI-enabled reconstruction algorithms. |
| Reimbursement Strategy | Medicare coding differentials for high-field diagnostic accuracy steer United States radiology department procurement specifications. |
| Backward Integration | In-house niobium-titanium wire production mitigates supply concentration risk from limited qualified metallurgical suppliers. |
Study Parameters
Multiple input streams — hospital procurement database analysis, regulatory filing review, and primary stakeholder interviews — were reconciled to construct segment-level demand estimates. Conversations with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and radiology department chairs informed installation base dynamics and replacement cycle timing. Secondary validation drew from FDA 510(k) clearances, EU MDR notified body documentation, NMPA registration records, and CMS Medicare reimbursement coding updates. Bottom-up equipment shipment modeling and top-down healthcare capital expenditure analysis were cross-referenced for triangulation.
Data-stream reconciliation across the projection horizon applied structured growth assumptions to closed-bore, open-bore, high-field, and low-field product categories. Segmentation dimensions modeled include magnet architecture, end-user facility type, clinical application area, and reconstruction technology sophistication. CAGRs were derived from equipment replacement cycle analysis and penetration rate assumptions for emerging applications. Forecast inputs incorporated helium supply chain constraints, AI software adoption curves, and regulatory pathway timelines across FDA, EU MDR, PMDA, and NMPA jurisdictions.
Revisions become necessary when reimbursement coding shifts, superconducting wire supply disruptions, or AI software regulatory reclassifications materialize. Deviation in Medicare hospital outpatient prospective payment system rates for MRI procedures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
North America Flow Cytometry Market