
 Medical Videoscope Market | 2026-2036
Medical Videoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Videoscope Market Intelligence
The purchasing locus for routine diagnostic procedures is decoupling from large hospital capital expenditure cycles to smaller, more frequent acquisitions by outpatient surgery centers. Olympus Corporation sustains its market leadership through a vast portfolio and deep relationships with gastroenterology departments. KARL STORZ GmbH & Co. KG competes on the basis of its specialized rigid endoscope technology for surgical applications. Stryker Corporation leverages its strong position in surgical equipment to bundle endoscopes with other visualization systems.
A medical videoscope is an instrument for visualizing internal body cavities, integrating a distal-tip image sensor, typically a CMOS or CCD chip, to transmit video. Its primary function is to enable minimally invasive diagnostic and therapeutic procedures, such as urological examinations and surgical assistance. Flexible videoscopes for gastrointestinal procedures continue to dominate due to high procedural volumes. Meanwhile, capsule videoscopes are gaining traction for non-invasive diagnostics in specific patient populations.
Market access is governed by stringent regulatory bodies, including the US FDA, the European Union's MDR framework, and Japan's PMDA. These authorities mandate rigorous clinical data for pre-market approval and post-market surveillance, impacting development timelines. The critical decision for healthcare providers involves weighing the total cost of ownership of reusable systems against the infection control advantages of disposable videoscopes.
Market Dynamics
The central dynamic in the medical videoscope market is the tension between the total cost of ownership for reusable systems and the heightened regulatory pressure from bodies like the FDA to mitigate cross-contamination risks, which accelerates the move toward single-use devices.
Growth Catalysts
- FDA Guidance on Infection Control:US Food and Drug Administration communications on the risks associated with reprocessed duodenoscopes are compelling healthcare facilities to adopt videoscopes with disposable components or fully single-use designs to ensure patient safety and reduce liability.
- Shift to Outpatient Centers:The migration of routine diagnostic procedures, especially in gastroenterology and urology, from hospital settings to ambulatory surgery centers in North America and Europe drives demand for more cost-effective and operationally efficient videoscope systems.
- Procedural Volume in Developed Markets:High and stable volumes of endoscopic procedures in countries like Germany and Japan, supported by public and private health insurance reimbursement, provide a consistent demand base for both new and replacement videoscopes.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for reusable videoscope systems, including processors, light sources, and reprocessing equipment, remains a substantial barrier for smaller clinics and hospitals in emerging economies.
- Stringent Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes extensive clinical evidence and post-market surveillance requirements, lengthening product development timelines and increasing compliance costs for manufacturers.
- Technical Limitations of Alternatives:While capsule endoscopy offers a non-invasive diagnostic option, its lack of therapeutic capability and maneuverability limits its use, preventing it from broadly substituting for conventional flexible videoscopes in most GI procedures.
Strategic Opportunities
- Expansion in Emerging Economies:Markets such as India and Brazil represent significant growth potential as healthcare infrastructure develops and a growing middle class gains access to advanced diagnostic procedures, increasing the addressable patient population.
- AI and Machine Learning Integration:The convergence of artificial intelligence with endoscopic imaging creates opportunities for computer-aided detection (CADe) systems that assist clinicians in identifying polyps and other abnormalities in real-time, improving diagnostic accuracy.
- Growth in Therapeutic Endoscopy:Advances in videoscope design, including larger instrument channels and enhanced articulation, are enabling more complex therapeutic interventions, expanding the role of endoscopy beyond diagnostics into minimally invasive treatment.
Industry Challenges
- Specialized Training Requirements:The effective use of advanced videoscopes and, critically, the correct reprocessing of reusable devices, demand highly skilled endoscopists and technicians, creating a training bottleneck that can limit technology adoption.
- Complex Post-Market Surveillance:Manufacturers face an increasing operational burden to comply with rigorous post-market surveillance and reporting mandates from regulators like the FDA and notified bodies under the EU MDR.
- Component Supply Chain Vulnerability:The reliance on a concentrated group of global suppliers for critical components like high-resolution CMOS image sensors and micro-optics exposes the market to potential disruptions and price volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Videoscope Market |
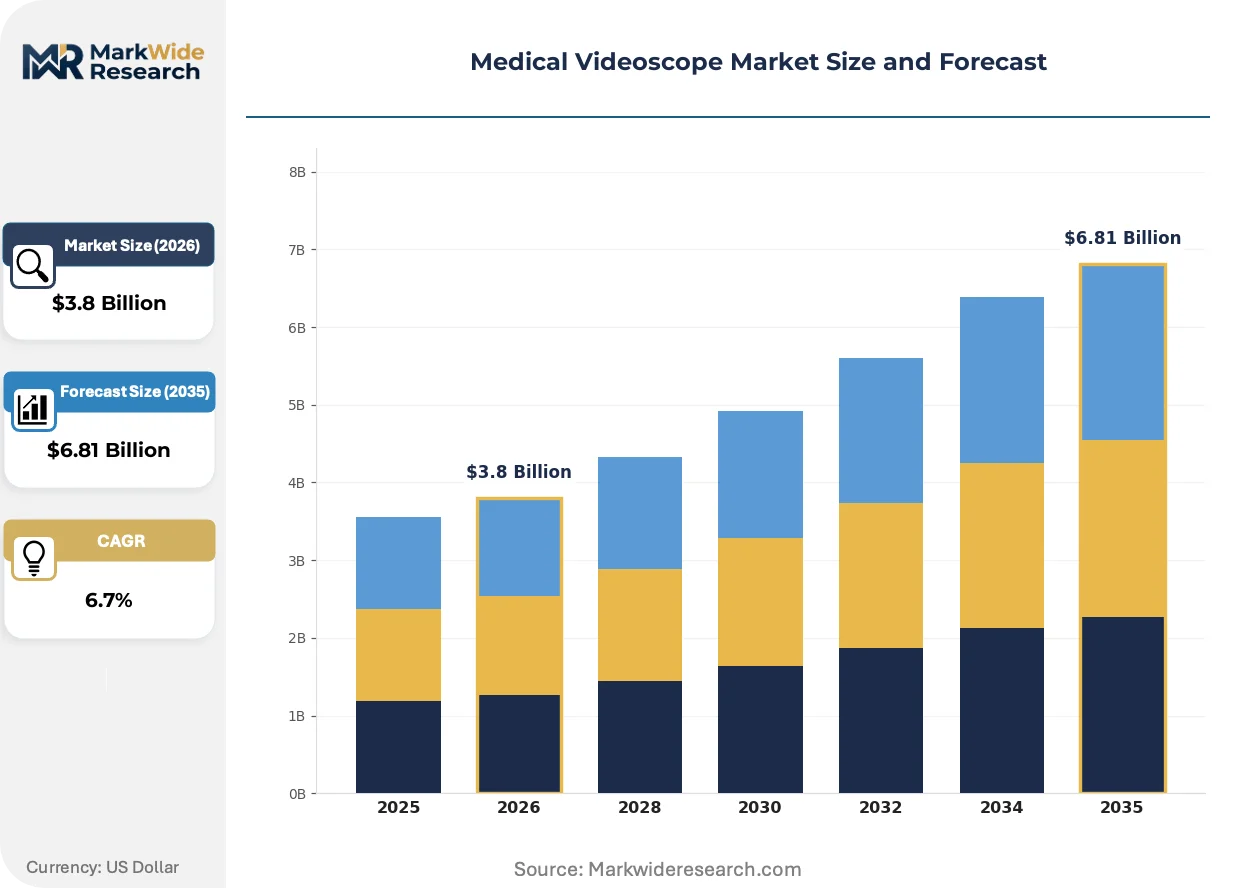
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Videoscopes, Rigid Videoscopes, Capsule Videoscopes, Ultra-Slim Videoscopes Technology: Digital Imaging, Video Processing, Optical Fiber, Wireless Transmission End User: Hospitals, Clinics, Outpatient Surgery Centers, Research Institutions Application: Gastrointestinal Procedures, Respiratory Assessments, Urological Examinations, Surgical Assistance |
| Companies Covered | Olympus Corporation, Stryker Corporation, KARL STORZ GmbH & Co. KG, Fujifilm Holding Corporation, Hoya Corporation, Richard Wolf GmbH, Conmed Corporation, Smith & Nephew PLC, Welch Allyn, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Videoscope Market Strategic Shifts & Innovations
Integration of digital technologies is transforming the videoscope from a simple visualization tool into a data-centric platform. This evolution is driven by advancements in imaging sensors, software analytics, and the industry-wide response to heightened standards for procedural safety and efficacy.
Artificial intelligence-driven computer-aided detection systems are being integrated directly into videoscope processors. Gastroenterology departments in major academic hospitals are the primary adopters of this technology for colorectal cancer screening. This software is automating the real-time identification of subtle mucosal abnormalities during colonoscopies, aiming to reduce human error and improve adenoma detection rates.
Regulatory scrutiny from the US FDA regarding the cleaning and reprocessing of complex devices is a powerful trend. This pressure creates significant operational and legal risk for hospitals related to healthcare-associated infections. Consequently, endoscopy departments are increasingly prioritizing videoscopes with disposable endcaps or adopting fully disposable single-use bronchoscopes and duodenoscopes to eliminate cross-contamination risk.
A fundamental shift in acquisition models is visible, moving away from large, centralized hospital capital budgets. This change disrupts the traditional sales process that targets hospital executives, creating an opening for vendors who offer operational-expense-based subscription or pay-per-procedure models. The trend is most pronounced within private equity-backed gastroenterology clinic networks in the United States.
Medical Videoscope Market Segmentation
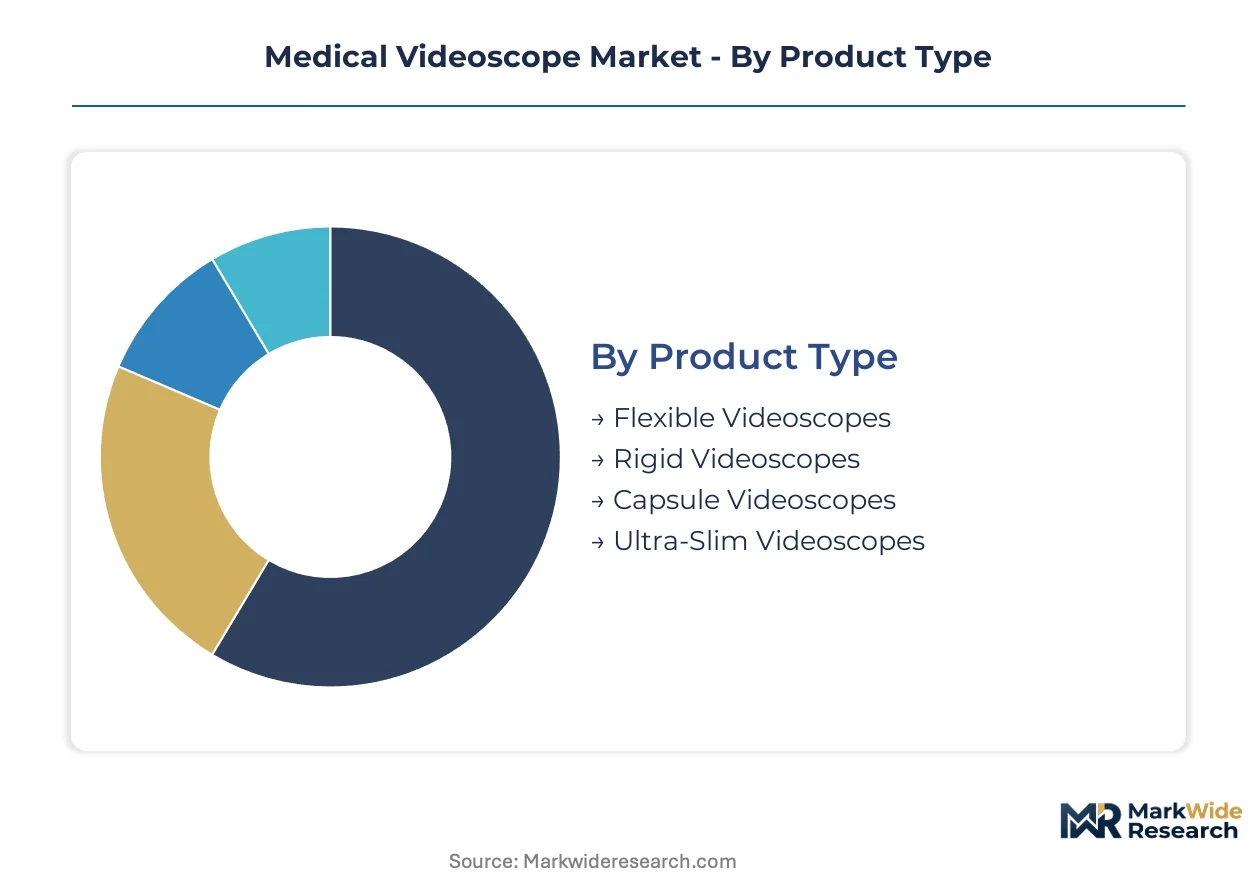
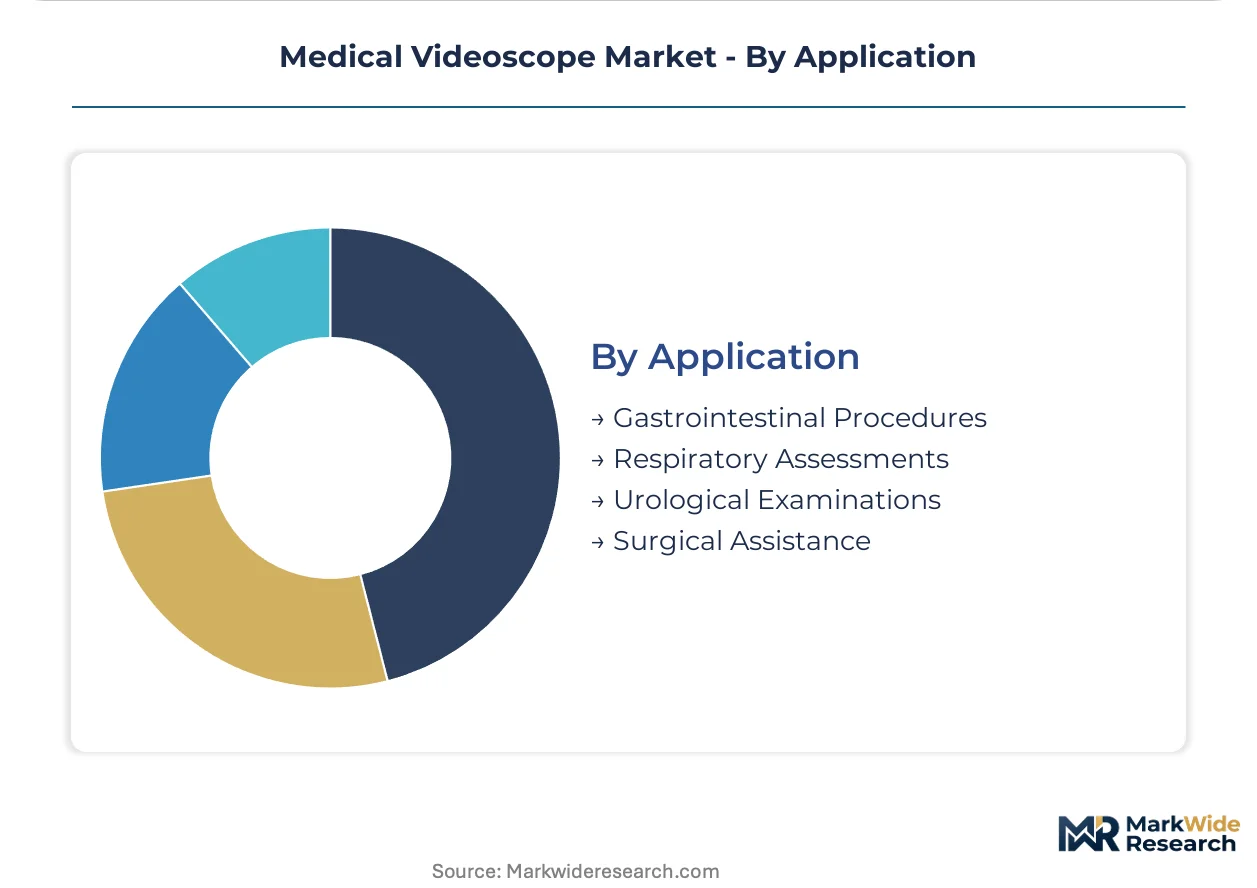
The medical videoscope market segmentation provides critical insights into purchasing behaviors and technological adoption trends. Understanding these distinct segments helps manufacturers tailor product development and market access strategies. Each segment reflects unique operational demands and clinical requirements across healthcare settings.
Product Type:
The upgrade and replacement cycles for medical videoscopes significantly influence demand across various product types.
- Flexible Videoscopes:These instruments feature a pliable insertion tube with a distal-tip image sensor, facilitating navigation through tortuous anatomical pathways. High procedural volumes in gastroenterology departments in the United States drive consistent demand for new and replacement flexible systems.
- Rigid Videoscopes:Used primarily in surgical applications, these instruments provide high-resolution visualization for procedures like laparoscopy and arthroscopy.
- Capsule Videoscopes:These ingestible devices capture images as they pass through the gastrointestinal tract, offering a non-invasive diagnostic option for specific patient populations. Their adoption is increasing in specialized clinics seeking alternatives for patients unable to undergo conventional endoscopy.
- Ultra-Slim Videoscopes:Designed for delicate or narrow anatomical access, these devices are gaining traction in pediatric and ENT procedures.
Flexible Videoscopes sits at the top of the volume ranking, with Capsule Videoscopes climbing the fastest.
Technology:
Technology segmentation highlights the functional advancements enhancing diagnostic precision and procedural efficiency in videoscope systems.
- Digital Imaging:This technology integrates high-resolution CMOS or CCD sensors at the videoscope's distal tip, enabling real-time video transmission with superior clarity. Its integration into new systems improves diagnostic accuracy, particularly for subtle mucosal abnormalities during endoscopy.
- Video Processing:Advanced algorithms enhance image quality, reduce noise, and provide features like color enhancement and structural magnification for better tissue differentiation. These capabilities are crucial for computer-aided detection systems in academic hospitals in Germany.
- Optical Fiber:Traditional videoscopes utilize optical fibers for light transmission and image relay, offering robust performance in many systems.
- Wireless Transmission:This technology enables untethered data transfer from capsule videoscopes, improving patient comfort and simplifying diagnostic workflow.
Digital Imaging capability underpins most modern videoscope platforms, while Wireless Transmission is gaining share fastest in specific diagnostic niches.
End User:
The diverse end-user landscape dictates varied procurement patterns and service requirements for medical videoscope systems.
- Hospitals:Large hospital networks represent significant capital expenditure for comprehensive videoscope systems, including reprocessing equipment and multiple device types. Their demand often focuses on high-volume, multi-specialty solutions and advanced therapeutic capabilities.
- Clinics:Specialized clinics, particularly in gastroenterology, require dedicated videoscope solutions tailored to their specific procedural focus.
- Outpatient Surgery Centers:These facilities prioritize cost-effective, operationally efficient systems, often favoring single-use or disposable-component videoscopes due to infection control mandates. The shift of routine procedures to these centers in the United States drives their procurement decisions.
- Research Institutions:These entities procure advanced videoscope technologies for clinical trials, academic studies, and the development of new diagnostic methods.
Hospitals remain the largest purchasing segment, but Outpatient Surgery Centers exhibit the steepest expansion trajectory for new installations.
Application:
Application segments reflect the primary clinical areas where medical videoscopes are deployed, driven by specific procedural volumes and diagnostic needs.
- Gastrointestinal Procedures:This segment encompasses diagnostic and therapeutic endoscopy of the esophagus, stomach, and colon, representing the highest volume of procedures globally. High incidences of digestive diseases in developed markets like Japan sustain consistent demand for these videoscopes.
- Respiratory Assessments:Bronchoscopy and laryngoscopy procedures rely on specialized videoscopes for examining the airways and vocal cords.
- Urological Examinations:Cystoscopy and ureteroscopy utilize videoscopes for diagnosing and treating conditions within the urinary tract.
- Surgical Assistance:Videoscopes provide crucial visualization during minimally invasive surgeries, supporting procedures across various specialties from orthopedics to general surgery. The increasing adoption of laparoscopic techniques globally elevates demand for advanced surgical videoscopes.
Gastrointestinal Procedures command the largest share of videoscope utilization, with Surgical Assistance applications showing significant growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives production migration in the medical videoscope market, as manufacturers seek geographies with favorable compliance costs. This dynamic influences investment decisions and supply chain configurations. The tension between stringent oversight and operational efficiency shapes regional market development.
United States
United States demand for videoscopes stems from the shift to outpatient centers and high procedural volumes. FDA guidance on infection control compels facilities to adopt disposable components. Specialized gastroenterology clinics in major metropolitan areas like New York and Los Angeles are concentrating demand.
Germany
German demand is sustained by stable endoscopic procedure volumes and robust health insurance reimbursement. The EU MDR framework imposes extensive clinical evidence and post-market surveillance requirements. Academic hospitals in cities such as Munich actively integrate advanced video processing and AI systems.
Japan
Japanese demand reflects high incidences of digestive diseases and consistent requirements for flexible systems. PMDA mandates rigorous clinical data for pre-market approval and post-market surveillance. Tokyo and Osaka serve as key hubs for advanced medical device research and clinical adoption.
India
Indian demand expands with developing healthcare infrastructure and a growing middle class accessing diagnostics. The country's national pharmaceutical regulator (CDSCO) governs medical device imports and approvals. Major cities like Mumbai and Bangalore are witnessing significant expansion in private hospital networks.
Brazil
Brazilian demand grows as healthcare infrastructure improves and advanced diagnostic procedures become more accessible. ANVISA oversees medical device registration and market access requirements in the country. São Paulo and Rio de Janeiro are central to medical device distribution and clinical adoption.
Medical Videoscope Market Key Industry Players
Portfolio diversification dominates the current landscape, with companies expanding their offerings to cover a broader range of clinical applications. The market structure exhibits a tiered consolidation, featuring established multinational corporations alongside specialized technology innovators. Strategic partnerships and technology licensing are prevalent competitive moves, enabling access to new imaging modalities and AI integration.
Within the established leader archetype, Olympus Corporation maintains its market leadership through a vast portfolio and deep relationships with gastroenterology departments. KARL STORZ GmbH & Co. KG exemplifies specialization, competing on the basis of its rigid endoscope technology for surgical applications. Stryker Corporation occupies a strong position leveraging its surgical equipment portfolio to bundle endoscopes with other visualization systems.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker Corporation |
| KARL STORZ GmbH & Co. KG |
| Fujifilm Holding Corporation |
| Hoya Corporation |
| Richard Wolf GmbH |
| Conmed Corporation |
| Smith & Nephew PLC |
| Welch Allyn, Inc. |
| Others |
Cost & Logistics Intelligence
FDA guidance on infection control gates qualified supply for medical videoscopes, influencing premium-tier pricing for compliant single-use devices. This regulatory pressure directly shapes procurement decisions and market access.
Pricing Analysis
Distributor margins significantly influence the final cost of medical videoscopes. A hybrid pricing model combines capital expenditure for reusable systems with operational expense-based subscriptions for disposable components. Price differentiation stems from infection control advantages and integrated AI capabilities, with outpatient surgery centers being most price-sensitive. Pricing pressure stems from these centers prioritizing cost-effective systems, while large hospital networks show less sensitivity for advanced therapeutic solutions.
Supply Chain Analysis
Certification requirements from the US FDA and EU MDR framework gate access for medical videoscope components. Supply concentration centers on Japan, Germany, and the United States for finished devices, with critical dependencies on high-resolution CMOS image sensors and micro-optics. A structural risk is supply chain vulnerability due to reliance on a concentrated group of global suppliers. Distribution runs through direct sales teams for large hospitals and specialized distributors for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical videoscope market presents a margin-expansion story, driven by the premium-tier shift towards advanced AI-integrated diagnostic systems. This evolution enables higher value capture per procedure and device.
For Market Incumbents: To counter the operational and legal risks from healthcare-associated infections, incumbents must accelerate investment in fully disposable or disposable-component videoscope designs. Strengthening relationships with private equity-backed gastroenterology clinic networks in the United States, leveraging operational-expense-based models, represents a key channel control lever. This mitigates disruption from new acquisition models.
For New Entrants and Emerging Players: Specialized clinics seeking non-invasive diagnostic options represent a penetrable segment for new entrants. Target expansion in emerging economies like India and Brazil, focusing on cost-effective capsule videoscopes. A go-to-market angle involves offering bundled solutions that combine diagnostic hardware with AI-driven analysis for improved accuracy in underserved patient populations.
For Investors and Strategic Acquirers: Roll-up economics work for specialized gastroenterology clinic networks because of the structural shift of routine diagnostic procedures to outpatient settings. Long-term viability is sustained by aging populations and consistent procedural volumes. Target mid-sized technology innovators specializing in AI-driven imaging or single-use devices for platform expansion. A model refresh is warranted upon material change in the market share of operational-expense-based models.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Integration | Olympus Corporation integrates AI algorithms into new videoscope processors for enhanced diagnostic accuracy. |
| Single-Use Device Development | Stryker Corporation develops fully disposable bronchoscope systems to mitigate cross-contamination risks in respiratory assessments. |
| Outpatient Channel Partnership | Fujifilm Holding Corporation forms strategic alliances with private equity-backed gastroenterology clinic networks in the United States. |
| Emerging Market Expansion | KARL STORZ GmbH & Co. KG establishes new distribution and service centers across major cities in Brazil. |
| Regulatory Compliance Enhancement | Hoya Corporation allocates significant R&D resources to generate extensive clinical evidence for EU MDR approval. |
Research Approach
Direct dialogue with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided primary insights. This qualitative grounding was validated against extensive secondary research, including US FDA filings, EU MDR documents, hospital procurement databases, and GPO contracts. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
Market volume and value projections were generated through a robust analytical framework across the analysis window. The model incorporated segmentation dimensions including product type, technology, end-user, application, and regional adoption patterns. Compound annual growth rates were extrapolated from historical trends and future demand drivers. Key industry-specific inputs included endoscopic procedural volumes and regulatory updates from bodies like the US FDA.
Inputs from public financial disclosures and regulatory databases were available through the study window; gaps in real-time procurement data from smaller clinics introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and market access dynamics. A model refresh is warranted upon material change in global health policy or component supply chain stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
CT Guided Intervention Market