
 United States Mammography Market | 2026-2036
United States Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
United States Mammography Market Outlook
Equipment leasing and managed service agreements is fragmenting capital deployment across imaging centers that previously deferred purchases. Hologic Inc. leverages its integrated detector manufacturing to control supply continuity for digital breast tomosynthesis platforms. GE Healthcare anchors its installed base through long-term service contracts that sustain recurring revenue from hospital networks. Siemens Healthineers differentiates via photon-counting detector research that positions its next-generation systems for premium procurement cycles.
Mammography encompasses X-ray-based breast imaging systems that apply compression plates and low-dose radiation, typically operating at 25–35 kVp tube voltage, to generate diagnostic images of breast tissue for early cancer detection. The primary purpose centers on population screening programs and diagnostic workup of suspicious lesions to reduce mortality through stage-shifted diagnosis. Digital mammography and 3D mammography together capture the dominant share of procurement budgets, with tomosynthesis systems commanding margin pools due to superior lesion visualization in dense breast tissue. Screening applications generate the highest procedure volumes, though diagnosis and risk assessment segments expand faster as genetic testing integration and AI-assisted density scoring broaden clinical utility.
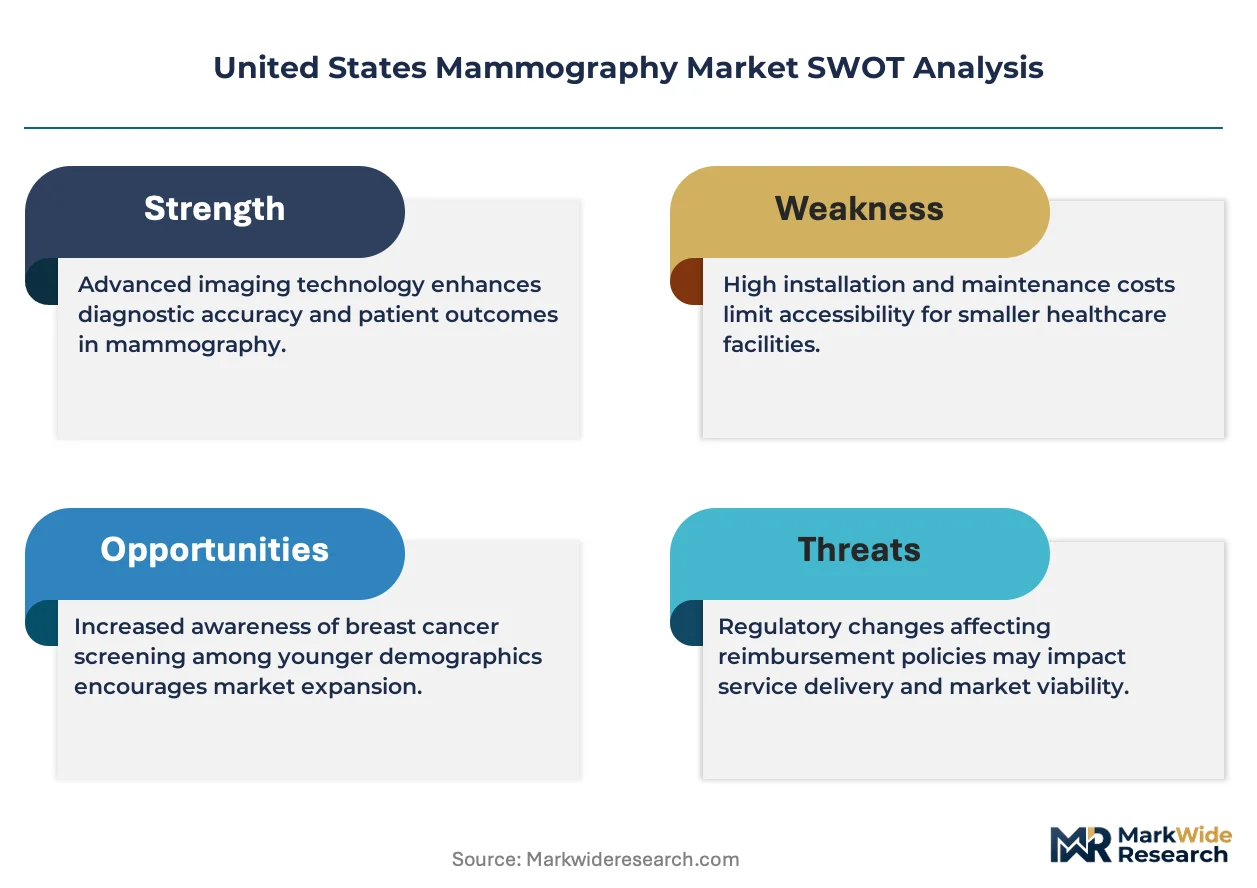
FDA mammography quality standards under the Mammography Quality Standards Act govern equipment performance, personnel qualifications, and facility accreditation, directly shaping replacement timelines and upgrade obligations. State-level dense breast notification laws in California, New York, Connecticut, and Texas compel disclosure of tissue density findings, stimulating demand for supplemental imaging capabilities and tomosynthesis adoption. CMS reimbursement policies for screening and diagnostic mammography establish the revenue foundation that providers weigh against capital outlays. Stakeholders must monitor evolving AI algorithm reimbursement pathways and state mandate proliferation to align product portfolios with shifting clinical and economic incentives.
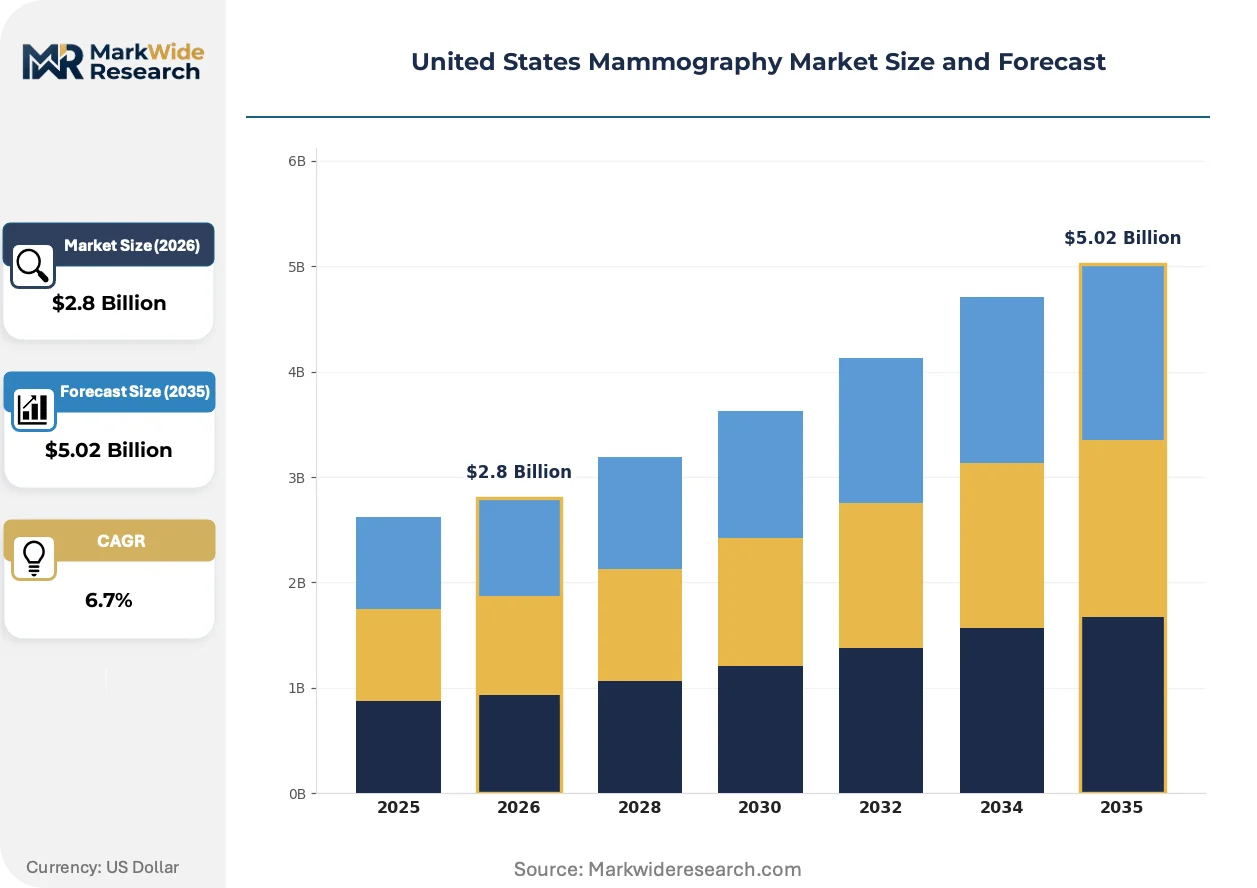
Market Dynamics
State dense breast notification laws are compressing equipment replacement cycles as imaging centers face mandatory disclosure obligations that obsolete 2D-only systems. This regulatory pressure converges with value-based care contracting to accelerate capital deployment toward integrated 3D platforms.
Growth Catalysts
- MQSA Accreditation Requirements:FDA-mandated quality standards force facility recertification every three years, driving systematic detector upgrades and software refreshes across hospital networks.
- Dense Breast Tissue Mandates:Connecticut, New York, and Texas notification laws compel supplemental imaging referrals, expanding addressable procedure volumes for tomosynthesis-capable sites.
- Integrated AI Workflows:Computer-aided detection algorithms embedded in screening protocols reduce radiologist reading time and expand throughput capacity at high-volume breast imaging centers.
Market Restraints
- Detector Supply Concentration:Amorphous selenium and cesium iodide substrate manufacturing concentrates in East Asian specialty chemical suppliers, exposing OEMs to input volatility and logistics disruption.
- CMS Reimbursement Compression:Medicare fee schedule adjustments for screening mammography constrain revenue per procedure, lengthening payback periods for capital-intensive 3D system investments.
- Technical Limitation in Dense Tissue:Standard 2D projection mammography exhibits reduced sensitivity in heterogeneously dense breasts, creating liability exposure that limits continued deployment of legacy equipment.
Strategic Opportunities
- Rural Health Clinic Expansion:Federally qualified health centers in Mississippi, Alabama, and rural Texas remain underpenetrated for 3D screening, presenting mobile unit and teleradiology partnership models.
- Risk Assessment Integration:Polygenic risk score incorporation into screening protocols creates demand for combined imaging-genetic service bundles at academic medical centers.
- Photon-Counting Detector Transition:Next-generation direct-conversion technology promises dose reduction and spectral imaging capability, positioning early adopters for premium procurement cycles as FDA clearance pathways mature.
Industry Challenges
- Radiologist Workforce Constraints:Fellowship-trained breast imager supply fails to match screening volume expansion, forcing reliance on teleradiology networks and AI triage tools that require validation workflows.
- Legacy PACS Integration Complexity:Tomosynthesis data volumes overwhelm older picture archiving systems, necessitating parallel storage infrastructure investments that fragment IT capital planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Mammography Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, Analog Mammography, 3D Mammography, Breast Ultrasound End User: Hospitals, Diagnostic Imaging Centers, Oncology Clinics, Women's Health Centers Technology: X-Ray, MRI, Ultrasound, Tomosynthesis Application: Screening, Diagnosis, Treatment Monitoring, Risk Assessment |
| Companies Covered | Hologic Inc., GE Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Koninklijke Philips NV, Carestream Health, Canon Medical Systems Corporation, Planmed Oy, Konica Minolta Healthcare Americas, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Mammography Market Strategic Shifts
Artificial intelligence integration is restructuring radiologist workflow allocation and equipment specification requirements across breast imaging programs. Three convergent developments are redefining competitive positioning and procurement criteria.
Contrast-enhanced mammography is hybridizing with digital breast tomosynthesis to create dual-modality lesion characterization protocols. Academic medical centers in Boston and Baltimore are piloting these combined workflows for staging and neoadjuvant therapy monitoring. The technique is compressing demand for separate breast MRI slots in high-throughput screening programs.
FDA draft guidance on AI-assisted diagnostic devices is mandating locked algorithm versions and continuous performance monitoring for mammography applications. Device manufacturers must establish post-market surveillance systems that track real-world sensitivity metrics. This regulatory architecture favors established vendors with clinical evidence libraries over emerging algorithm developers.
Hospital systems are consolidating imaging service line purchasing under centralized supply chain functions, displacing decentralized radiology department autonomy. Integrated delivery networks in the Northeast corridor now negotiate enterprise-wide equipment and service contracts spanning multiple sites. This concentration shifts vendor relationships toward long-term partnership structures with performance guarantees.
United States Mammography Market Segmentation
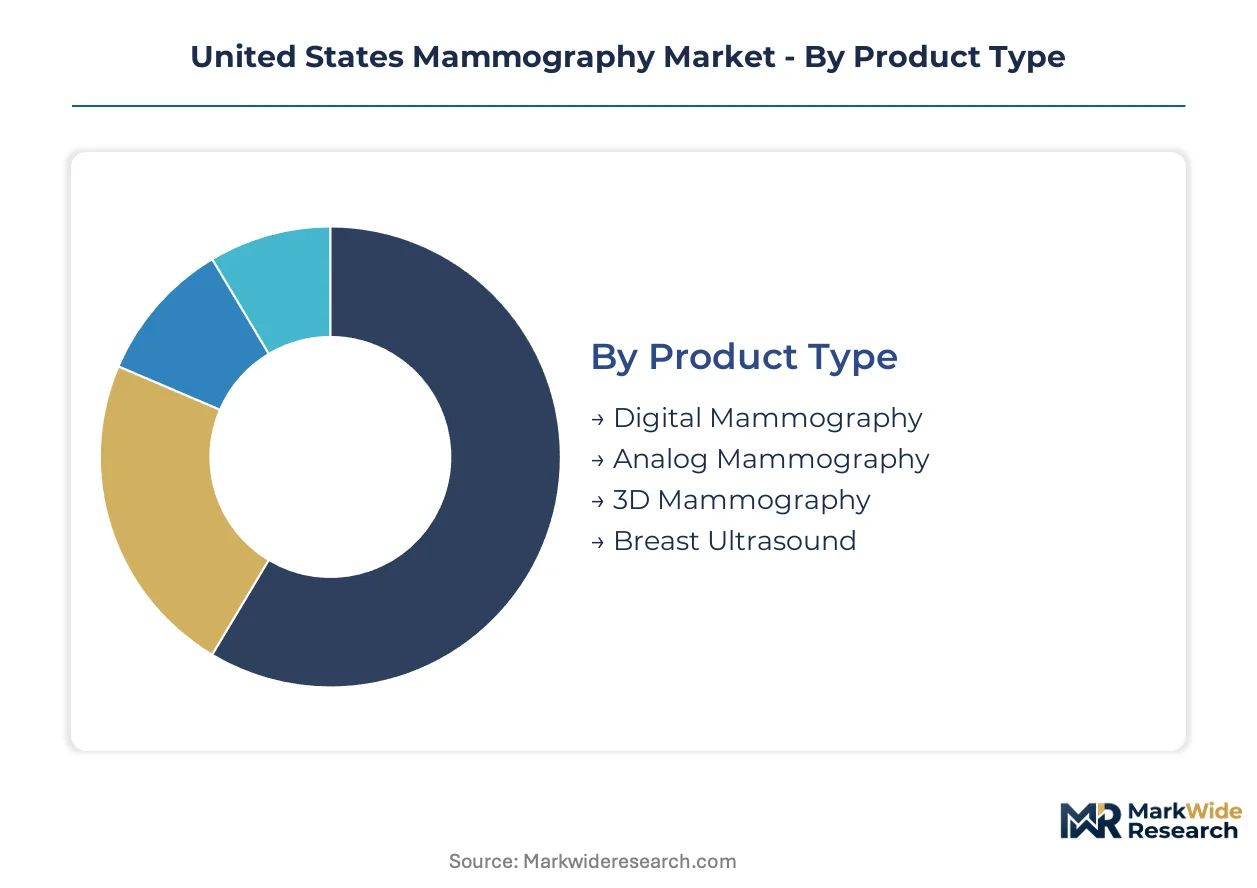
Equipment configuration and service intensity vary sharply across segment boundaries in the United States mammography market. Procurement patterns diverge between hospital networks and independent imaging centers, while technology selection increasingly hinges on state-level dense breast notification compliance rather than clinical preference alone.
Product Type:
After-sales service intensity escalates dramatically with detector complexity and software integration depth.
- Digital Mammography:Flat-panel detector systems utilizing amorphous selenium or cesium iodide scintillators dominate installed base maintenance contracts. Hospital systems in the Northeast corridor from Boston to Baltimore prioritize these platforms for MQSA recertification compliance, with service agreements typically spanning 7-10 years to manage detector degradation and calibration cycles.
- 3D Mammography:Digital breast tomosynthesis platforms command premium service tiers due to multi-slice reconstruction software and higher data throughput requirements. Connecticut and New York dense breast notification laws accelerate replacement of 2D-only systems, concentrating demand for integrated 3D platforms with embedded AI workflows at high-volume screening sites.
- Analog Mammography:Film-screen systems persist in select rural health clinics and mobile screening units with limited capital budgets.
- Breast Ultrasound:Handheld and automated systems serve supplemental imaging roles for dense tissue evaluation, typically deployed without long-term service捆绑.
Digital mammography holds the largest share; momentum sits with 3D mammography.
End User:
Capital deployment cycles and procurement autonomy diverge across institutional settings.
- Hospitals:Integrated delivery networks consolidate purchasing under centralized supply chain functions, negotiating enterprise-wide equipment and service contracts. These institutions prioritize FDA-cleared platforms with established post-market surveillance systems to satisfy Joint Commission accreditation.
- Diagnostic Imaging Centers:Independent operators face compressed margins under CMS reimbursement pressure, driving preference for equipment leasing and managed service agreements that defer ownership risk.
- Oncology Clinics:Academic medical centers in Boston and Baltimore pilot contrast-enhanced mammography protocols for neoadjuvant therapy monitoring.
- Women's Health Centers:Federally qualified health centers in Mississippi and rural Texas remain underpenetrated for 3D screening, presenting mobile unit partnership opportunities.
Hospitals capture the dominant procurement volume; diagnostic imaging centers are expanding most quickly through alternative financing structures.
Technology:
Detector physics and regulatory clearance pathways stratify competitive positioning.
- Tomosynthesis:Multi-angle X-ray acquisition with iterative reconstruction algorithms delivers superior lesion visualization in heterogeneously dense breast tissue. FDA quality standards mandate locked software versions and continuous performance monitoring, favoring established vendors with clinical evidence libraries.
- X-Ray:Conventional projection mammography at 25-35 kVp tube voltage retains utility for screening volume in cost-constrained settings.
- Ultrasound:Elasticity imaging and automated whole-breast systems address supplemental screening demand triggered by state notification laws.
- MRI:Breast MRI serves high-risk surveillance and staging applications, with demand compression from emerging contrast-enhanced mammography hybrids.
Tomosynthesis leads technology investment; ultrasound gains share fastest as a supplemental modality.
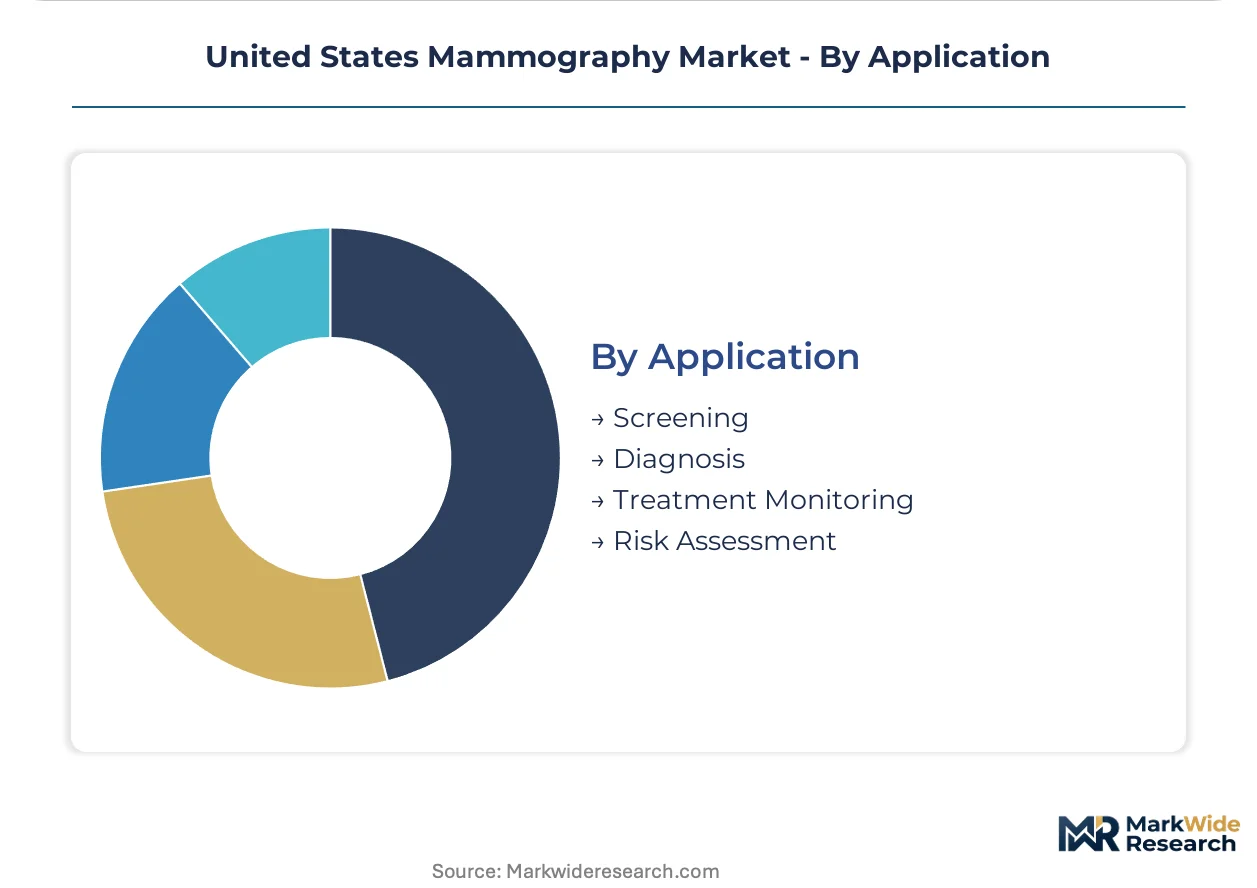
Application:
Reimbursement rates and procedure volumes create divergent margin profiles across clinical use cases.
- Screening:Population-based programs generate highest procedure volumes under CMS fee schedules, though reimbursement compression constrains revenue per exam. MQSA accreditation requirements force systematic detector upgrades across hospital networks to maintain program certification.
- Diagnosis:Diagnostic workup of suspicious lesions commands higher technical fees and attracts AI-assisted workflow investments to reduce radiologist reading time.
- Treatment Monitoring:Neoadjuvant chemotherapy response assessment utilizes specialized protocols at academic medical centers.
- Risk Assessment:Polygenic risk score integration creates demand for combined imaging-genetic service bundles, expanding fastest as genetic testing penetration deepens.
Screening generates the largest procedure volume; risk assessment climbs the fastest as precision medicine protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality standards and state-level dense breast notification laws are redistributing equipment demand across sub-regional markets, concentrating procurement in jurisdictions with mandatory disclosure obligations and value-based care contracting penetration.
Northeast Corridor
Connecticut and New York dense breast notification laws compel supplemental imaging referrals that accelerate 3D system upgrades. MQSA accreditation requirements force systematic detector refreshes across hospital networks from Boston to Baltimore. Academic medical centers in Boston pilot contrast-enhanced mammography protocols for neoadjuvant therapy monitoring.
Texas
State notification mandates expand addressable procedure volumes for tomosynthesis-capable sites in Dallas-Fort Worth and Houston. Federally qualified health centers in rural Texas remain underpenetrated for 3D screening, presenting mobile unit partnership opportunities. CMS reimbursement policies establish the revenue foundation that providers weigh against capital outlays.
California
Dense breast disclosure obligations in Los Angeles and San Francisco Bay Area markets drive demand for integrated AI workflows. Diagnostic imaging centers face compressed margins under Medicare fee schedule adjustments, shifting preference toward equipment leasing structures. Integrated delivery networks negotiate enterprise-wide contracts spanning multiple sites.
Southeast
Federally qualified health centers in Mississippi and Alabama present mobile unit and teleradiology partnership models for screening expansion. Radiologist workforce constraints force reliance on teleradiology networks and AI triage tools. State-level regulatory adoption lags the Northeast corridor, extending legacy equipment replacement cycles.
Midwest
Hospital systems in Illinois and Ohio consolidate imaging service line purchasing under centralized supply chain functions. Value-based care contracts accelerate capital deployment toward integrated 3D platforms. Legacy PACS integration complexity necessitates parallel storage infrastructure investments that fragment IT capital planning.
United States Mammography Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement segments. The market structure concentrates around integrated OEMs with captive detector manufacturing and established service networks. Three archetypes dominate: full-platform manufacturers with vertical supply control, imaging specialists with AI-embedded workflows, and regional service contractors with managed equipment agreements. Competitive moves center on long-term service contract anchoring and enterprise-wide purchasing consolidation.
Among full-platform manufacturers, Hologic Inc., GE Healthcare, and Siemens Healthineers occupy positions that exemplify divergent strategic emphases. Hologic leverages integrated detector manufacturing to control supply continuity. GE Healthcare anchors hospital network relationships through extended service agreements. Siemens Healthineers sits within the premium technology tier, positioning around photon-counting detector research. These three represent the dominant competitive anchors that structure procurement negotiations across integrated delivery networks and independent imaging centers.
| Leading Market Players |
|---|
| Hologic Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Koninklijke Philips NV |
| Carestream Health |
| Canon Medical Systems Corporation |
| Planmed Oy |
| Konica Minolta Healthcare Americas, Inc. |
| Others |
Value Chain & Pricing Dynamics
East Asian specialty chemical suppliers dominate amorphous selenium and cesium iodide substrate manufacturing, concentrating margin capture upstream while OEMs downstream compete on service contract duration and AI-embedded platform premiums. This supply asymmetry forces detector-dependent manufacturers to absorb input volatility through long-term purchasing agreements that reshape competitive economics across procurement tiers.
Pricing Analysis
Certification level under FDA MQSA standards creates the primary spread between premium 3D tomosynthesis platforms and legacy 2D systems. Three-tier pricing structure across premium, standard, and economy levels reflects detector complexity, software integration depth, and embedded AI workflow capability. Cost compression in standard-tier equipment is intensifying because CMS reimbursement compression for screening mammography constrains provider capital budgets. Independent imaging centers exhibit highest price sensitivity due to compressed margins, while integrated hospital networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Tariff exposure between East Asian semiconductor suppliers and US-based OEM assembly facilities dominates supply chain risk assessment for detector components. Manufacturing concentrates in Japan, South Korea, and Taiwan for flat-panel detector substrates and specialized scintillator crystals. Raw material dependencies include high-purity selenium, rare-earth phosphors, and precision-machined tungsten X-ray tubes. Single-source vulnerability persists for photon-counting detector substrates where qualifying alternative suppliers requires multi-year FDA validation cycles. Distribution runs through authorized service networks that bundle installation, calibration, and multi-year maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States mammography market sits in a cyclical recovery phase driven by MQSA-mandated detector replacement cycles converging with dense breast notification law compliance deadlines. This regulatory-driven equipment refresh creates predictable demand visibility for vendors positioned across replacement timelines.
For Market Incumbents: Insulate service revenue streams by extending multi-year detector maintenance contracts ahead of photon-counting technology transitions. Lock in hospital network relationships through enterprise-wide purchasing agreements that displace independent imaging center competitors. Vertical integration into captive detector manufacturing, exemplified by Hologic's supply continuity control, defends margin pools against East Asian input volatility.
For New Entrants and Emerging Players: Federally qualified health centers in Mississippi, Alabama, and rural Texas represent the most penetrable entry point for mobile 3D screening units and teleradiology partnership models. AI-assisted density scoring algorithms cleared through FDA's locked-version guidance pathway offer a software-first entry angle that avoids capital-intensive hardware manufacturing. Radiologist workforce constraints create demand for workflow automation tools that reduce reading time per exam.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic imaging center chains facing CMS reimbursement compression and equipment leasing obligation maturities. Long-term viability over a five-to-ten year window hinges on positioning for photon-counting detector adoption curves and AI reimbursement pathway clarity. Monitor FDA draft guidance finalization on continuous performance monitoring requirements as the signal indicating which algorithm developers will survive regulatory consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance for AI-Embedded Tomosynthesis | Locked algorithm versions under FDA draft guidance favor established vendors with clinical evidence libraries over emerging developers. |
| Hospital System Enterprise Contracting | Integrated delivery networks in the Northeast corridor consolidate purchasing under centralized supply chain functions spanning multiple sites. |
| Photon-Counting Detector R&D Partnership | Direct-conversion technology promises dose reduction and spectral imaging capability for premium procurement cycles. |
| Rural Mobile Screening Unit Deployment | Federally qualified health centers in Mississippi and rural Texas remain underpenetrated for 3D screening capabilities. |
| Polygenic Risk Score Integration | Combined imaging-genetic service bundles at academic medical centers expand addressable procedure volumes beyond standard screening. |
Study Parameters
A standing panel of breast imaging radiologists, hospital purchasing committee directors, biomedical equipment engineers, and GPO contracts managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA MQSA facility inspection databases, CMS Medicare claims data, hospital procurement registries, and state dense breast notification law legislative tracking. Bottom-up equipment shipment modeling and top-down healthcare capital expenditure analysis were triangulated to constrain estimate variance.
Scenario-bracketing around MQSA recertification timelines, dense breast notification law adoption curves, and AI reimbursement pathway developments structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, end-user institutional type, detector technology tier, and clinical application intensity. CAGRs were derived from installed base replacement cycle analysis and procedure volume elasticity to reimbursement rate changes. Forecast inputs incorporated radiologist workforce supply projections and PACS infrastructure upgrade requirements.
Practitioners should monitor FDA final guidance on AI-assisted device performance monitoring, CMS fee schedule rulemaking, and state-level dense breast notification mandate proliferation for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Ultrasound Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Global Surgical Imaging Arms Market