
 Canada Nuclear Medicine Market | 2026-2036
Canada Nuclear Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Nuclear Medicine Market Insights
Software-defined imaging protocols is recalibrating how vendors bundle hardware and analytics in Canada. GE Healthcare leverages its cyclotron network to sustain isotope supply security across provincial health systems. Siemens Healthineers anchors its position through integrated PET-MRI platforms that dominate tertiary care installations. Jubilant Radiopharma specializes in radiopharmaceutical distribution, occupying a critical logistics layer between production and hospital nuclear medicine departments.
Nuclear medicine encompasses the clinical use of radioactive isotopes for diagnostic imaging and targeted therapy, requiring half-life management within 6-110 hours depending on the tracer and sterile manufacturing under GMP conditions to ensure patient safety. The field serves primarily to detect malignancies, assess myocardial perfusion, and evaluate neurological function through gamma ray emission tracking. Radiopharmaceuticals command the largest revenue pool given recurring consumption and supply chain complexity, while PET technology leads growth due to superior resolution and expanding tracer portfolios for oncology applications. Hospitals remain the dominant end user channel, though imaging centers are capturing volume as provincial health authorities outsource non-emergency diagnostic capacity.
Health Canada and the Canadian Nuclear Safety Commission jointly govern isotope production, transport, and clinical administration, with Vanessa's Law strengthening post-market surveillance requirements for radiopharmaceutical safety. The Canadian Partnership Against Cancer coordinates national imaging standards that influence provincial procurement specifications and equipment replacement cycles. Stakeholders must monitor cyclotron infrastructure investments and tracer pipeline approvals to anticipate supply availability and competitive positioning shifts.
Market Dynamics
Cyclotron infrastructure scarcity across Canadian provinces is concentrating radiopharmaceutical supply within Ontario and Quebec corridors, forcing hospital networks into long-term offtake agreements with limited domestic producers.
Growth Catalysts
- Vanessa's Law framework:Health Canada's strengthened post-market surveillance requirements accelerate novel diagnostic agent approvals, compressing regulatory timelines for innovative tracers entering clinical use.
- Oncology imaging expansion:Canadian academic medical centers in Toronto, Montreal, and Vancouver are scaling PET-CT installations to address rising cancer screening volumes and precision medicine protocols.
- Tc-99m generator alternatives:Cyclotron-produced Tc-99m is displacing reactor-dependent molybdenum supply chains, reducing import vulnerability from aging international reactors.
Market Restraints
- Isotope import concentration:Over eighty percent of diagnostic isotopes consumed in Atlantic Canada originate from foreign reactors, exposing procurement to geopolitical and logistical disruption.
- Cyclotron capex intensity:Each provincial cyclotron facility requires capital deployment exceeding standard imaging equipment budgets, constraining Health Ministry allocation decisions.
- Short half-life logistics:F-18 tracers degrade within 110 hours, mandating just-in-time production coordination that eliminates inventory buffering and amplifies supply fragility.
Strategic Opportunities
- Western Canada capacity gap:Alberta and British Columbia maintain limited domestic isotope production, creating whitespace for regional cyclotron investments serving prairie and pacific hospital networks.
- Theranostic convergence:Paired diagnostic-therapeutic radiopharmaceuticals for neuroendocrine and prostate malignancies enable premium pricing and recurring patient monitoring revenue streams.
- Imaging center outsourcing:Provincial health authorities in Ontario are transferring non-emergency nuclear medicine procedures to independent diagnostic facilities, expanding addressable channel volume.
Industry Challenges
- Radiochemist workforce scarcity:Canadian universities produce insufficient PET radiochemists to staff expanding cyclotron facilities, extending recruitment timelines and constraining operational ramp rates.
- GMP certification complexity:Sterile manufacturing compliance under Health Canada and CNSC joint oversight requires eighteen-to-twenty-four month facility qualification periods that delay commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Nuclear Medicine Market |
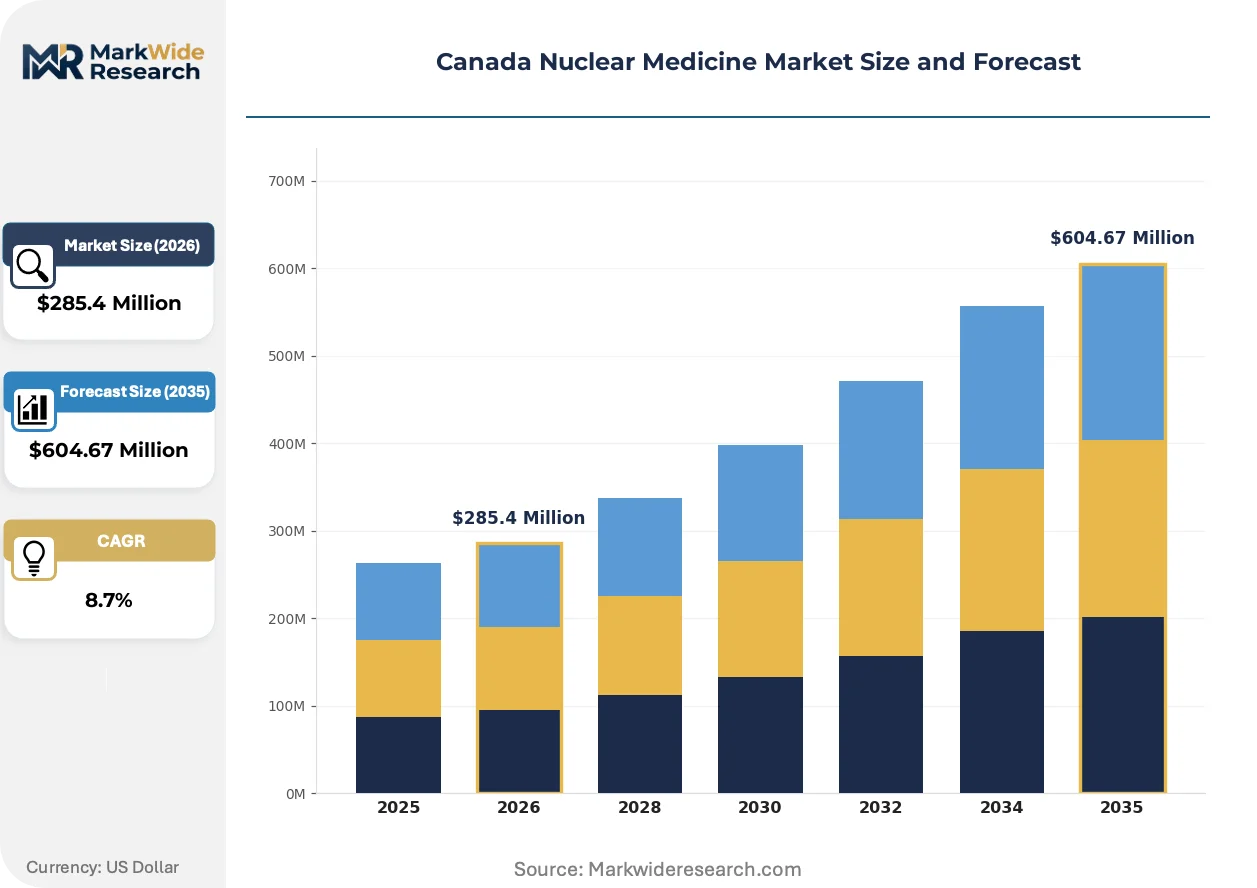
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Imaging Agents, Diagnostic Kits, Therapeutic Agents End User: Hospitals, Clinics, Imaging Centers, Research Institutions Application: Oncology, Cardiology, Neurology, Thyroid Disorders Technology: PET, SPECT, Gamma Cameras, Cyclotrons |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Nordion, Lantheus Medical Imaging, Jubilant Radiopharma, BWXT Medical, Curium Pharma, Bracco Imaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Nuclear Medicine Market Trends and Innovations
Software-defined imaging protocols are dissolving traditional hardware-software bundling arrangements, compelling vendors to unbundle analytics from scanner sales and restructure service revenue models.
Total-body PET systems are absorbing research investment from major Canadian academic centers, enabling simultaneous whole-body tracer kinetics measurement that reduces scan times and radiation exposure. University Health Network in Toronto and McGill University Health Centre are piloting installations that compress multi-bed acquisition protocols into single-position imaging. This capability is absorbing demand from traditional sequential PET-CT configurations, pressuring vendors to accelerate platform refresh cycles.
Health Canada's Vanessa's Law amendments are mandating mandatory adverse event reporting for radiopharmaceuticals, tightening pharmacovigilance obligations that increase compliance overhead for distributors. The framework requires real-world evidence collection post-approval, shifting regulatory burden toward post-market surveillance rather than pre-market submission intensity. Smaller radiopharma developers lacking established pharmacovigilance infrastructure face disproportionate adaptation costs relative to integrated hospital networks.
Provincial procurement consolidation is compressing vendor relationship structures, with Ontario's Health Shared Services and Quebec's Santé Québec centralizing equipment acquisition decisions previously fragmented across individual hospitals. Group purchasing organizations are displacing direct manufacturer contracting for cyclotron maintenance and tracer supply agreements. This concentration is most visible in the Greater Toronto Area, where three procurement entities now coordinate equipment replacement for over forty nuclear medicine departments.
Canada Nuclear Medicine Market Segmentation
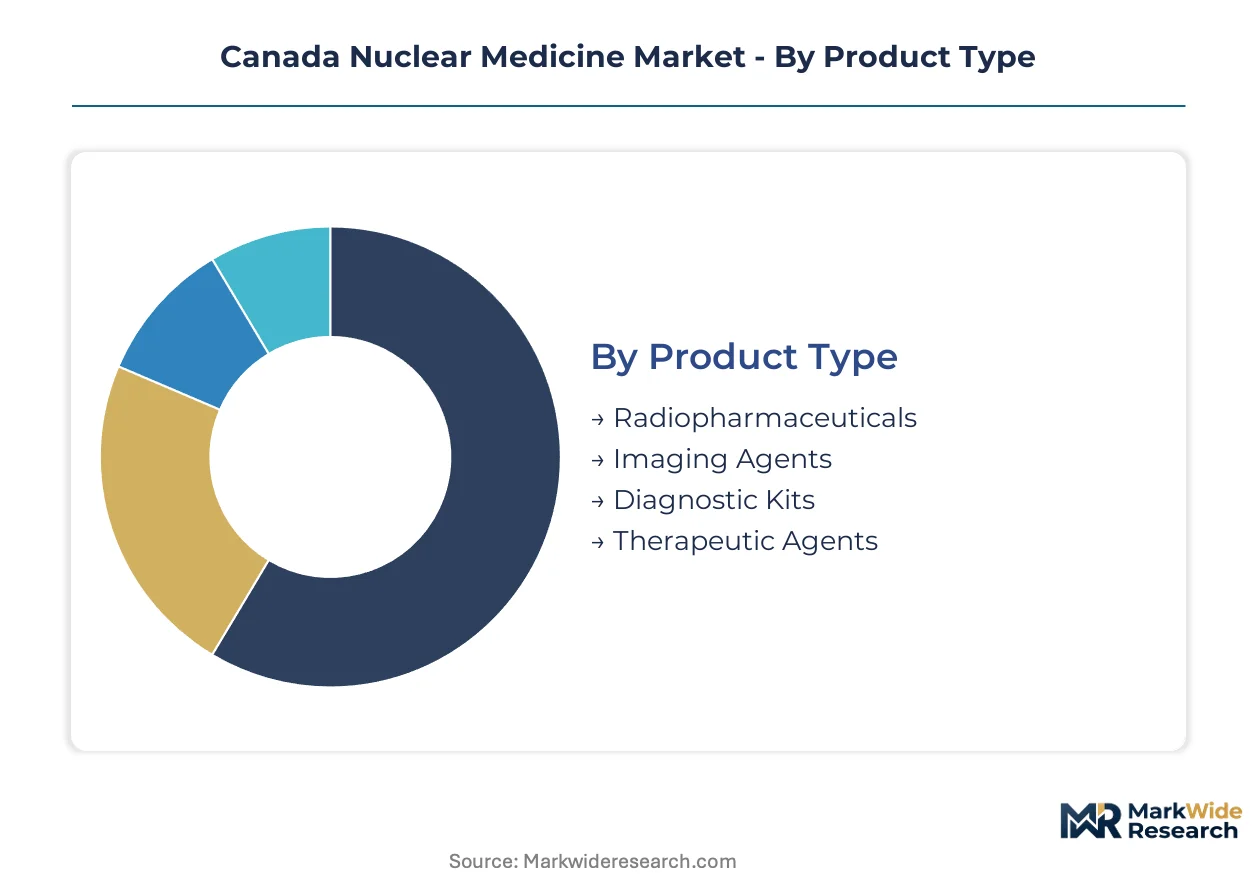
Segmentation in Canada's nuclear medicine market reveals how procurement decisions split between consumable supply chains and capital equipment cycles. Hospital networks prioritize radiopharmaceutical reliability over scanner sophistication, while provincial purchasing authorities weight total cost of ownership against clinical throughput metrics.
Product Type:
Procurement budgets differentiate between recurring consumable expenses and one-time capital deployments, with radiopharmaceutical contracts commanding multi-year offtake negotiations.
- Radiopharmaceuticals:Radioactive tracers including F-18 FDG, Tc-99m compounds, and Ga-68 formulations require cyclotron or generator production within 110-hour half-life windows. Ontario's Health Shared Services consolidates hospital procurement for these consumables, locking in supply security through GE Healthcare's cyclotron network across provincial corridors.
- Imaging Agents:Contrast-enhanced radiopharmaceuticals for hybrid imaging modalities enable superior tissue differentiation in PET-CT and PET-MRI protocols. Demand concentrates in Toronto's University Health Network and McGill University Health Centre, where academic research programs absorb novel agent volumes for clinical trials.
- Diagnostic Kits:Pre-formulated reagent sets for thyroid function and renal clearance studies reduce preparation complexity in smaller hospital departments.
- Therapeutic Agents:Lu-177 and I-131 compounds for neuroendocrine tumor and thyroid malignancy treatment require specialized handling infrastructure and nuclear medicine physician certification.
Volume sits with Radiopharmaceuticals; growth tilts toward Therapeutic Agents.
End User:
Facility type determines regulatory compliance burden and reimbursement pathway complexity under provincial health authority frameworks.
- Hospitals:Tertiary academic medical centers in Ontario, Quebec, and British Columbia anchor procurement volumes through integrated nuclear medicine departments with cyclotron proximity. These institutions manage the full spectrum of diagnostic and therapeutic procedures under Health Canada and CNSC joint oversight.
- Imaging Centers:Independent diagnostic facilities in Ontario's Greater Toronto Area capture outsourced non-emergency procedures from hospital backlogs. Provincial health authority contracting shifts PET-CT volume to these centers, expanding their addressable share of oncology screening.
- Clinics:Cardiology-focused practices in community settings perform myocardial perfusion imaging with portable gamma camera systems.
- Research Institutions:McGill, University of Toronto, and University of British Columbia operate cyclotron facilities supporting tracer development and total-body PET pilot programs.
Procurement volume clusters in Hospitals; Imaging Centers are expanding most quickly.
Application:
Clinical indication drives tracer selection and scanner configuration decisions across Canadian hospital networks.
- Oncology:Cancer detection and staging consumes the majority of PET-CT capacity, with F-18 FDG remaining the workhorse tracer. Toronto's Princess Margaret Cancer Centre and Vancouver's BC Cancer anchor demand for precision medicine protocols requiring molecular imaging biomarkers.
- Cardiology:Myocardial perfusion imaging with Tc-99m sestamibi or rubidium-82 evaluates coronary artery disease in aging Canadian populations. Quebec's Institut universitaire de cardiologie et de pneumologie de Québec maintains specialized capacity.
- Neurology:Amyloid and tau PET tracers for Alzheimer's disease diagnosis face limited reimbursement outside research protocols.
- Thyroid Disorders:I-131 uptake studies and ablation therapy represent established procedures with stable demand curves.
Oncology commands installed base; neurology imaging shows steepest expansion trajectory pending reimbursement expansion.
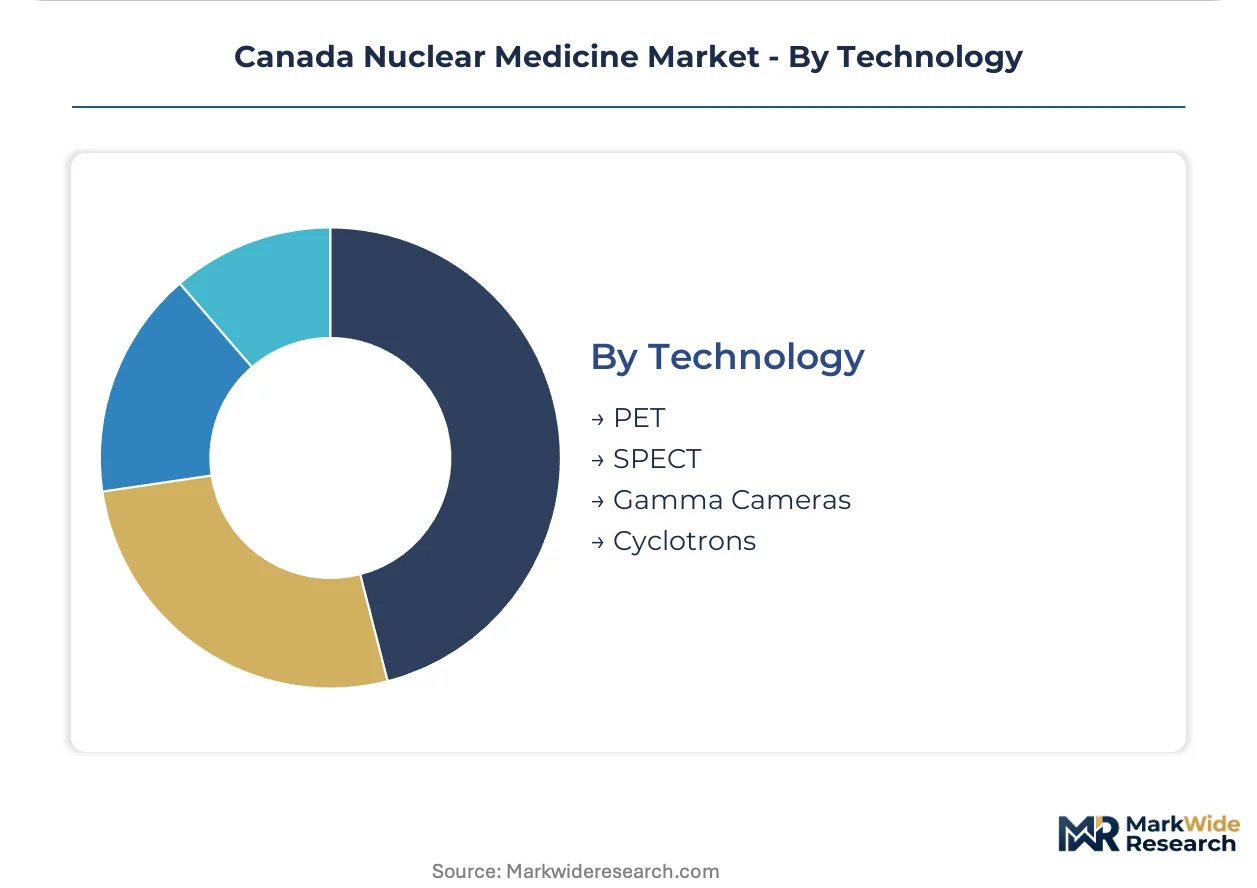
Technology:
Capital allocation decisions balance resolution performance against operational complexity and radiochemist staffing requirements.
- PET:Positron emission tomography delivers superior spatial resolution and quantitative metabolic assessment, dominating new installations in academic centers. Siemens Healthineers' integrated PET-MRI platforms anchor tertiary care procurement in Montreal and Vancouver.
- SPECT:Single photon emission computed tomography retains cost advantages for cardiac and bone imaging in community hospital settings with established Tc-99m supply chains.
- Gamma Cameras:Anger camera systems support planar imaging for thyroid, renal, and hepatobiliary studies with lower capital barriers.
- Cyclotrons:Particle accelerator infrastructure enables domestic isotope production, with Ontario and Quebec corridors concentrating operational capacity while Western Canada depends on import supply.
Scanner volume rests with SPECT; PET platform refresh cycles are accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cyclotron production clusters in Ontario and Quebec generate the majority of domestic isotopes, while Atlantic Canada and the Prairie Provinces remain dependent on import corridors. This production-consumption divide shapes procurement risk profiles across provincial health systems.
Ontario
Toronto's University Health Network and Princess Margaret Cancer Centre anchor PET-CT demand for oncology staging and precision medicine protocols. Health Canada's Vanessa's Law framework accelerates tracer approvals through strengthened post-market surveillance. GE Healthcare's cyclotron network concentrates production capacity along the Toronto-Ottawa corridor, securing supply for over forty hospital nuclear medicine departments.
Quebec
McGill University Health Centre pilots total-body PET installations while Institut universitaire de cardiologie et de pneumologie de Québec maintains specialized cardiac imaging capacity. The Canadian Nuclear Safety Commission governs isotope transport across provincial borders under joint oversight with Health Canada. Montreal's academic medical centers drive demand for Ga-68 formulations in neuroendocrine tumor imaging.
British Columbia
BC Cancer in Vancouver coordinates molecular imaging biomarker programs for the Pacific region with limited domestic cyclotron infrastructure. Provincial procurement relies on tracer shipments from Ontario and cross-border supply agreements. Vancouver General Hospital anchors diagnostic volumes while facing extended logistics windows for F-18 tracers with 110-hour half-life constraints.
Alberta
Calgary and Edmonton hospital networks perform substantial cardiac and oncology imaging with minimal local isotope production capacity. The province represents whitespace for regional cyclotron investment serving prairie hospital networks. Alberta Health Services contracts with Ontario-based distributors for Tc-99m and F-18 supply security.
Atlantic Canada
Over eighty percent of diagnostic isotopes consumed in New Brunswick, Nova Scotia, and Newfoundland originate from foreign reactors, exposing procurement to geopolitical disruption. Health Canada regulates import pathways while provincial health authorities maintain limited buffer inventory. Halifax's Queen Elizabeth II Health Sciences Centre anchors regional diagnostic capacity with extended supply chain lead times.
Canada Nuclear Medicine Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while specialized radiopharmaceutical distributors occupy critical logistics layers between production and hospital departments. The market structure reflects consolidation around cyclotron infrastructure ownership and tertiary care imaging platform installations. Strategic archetypes include integrated healthcare conglomerates with cyclotron networks, specialized radiopharma logistics providers, and precision imaging platform specialists. Dominant competitive moves center on cyclotron capacity expansion and long-term offtake agreements with provincial health authorities.
Among integrated healthcare technology providers, GE Healthcare, Siemens Healthineers, and Jubilant Radiopharma exemplify distinct competitive positions. GE Healthcare represents the cyclotron-integrated archetype with provincial network coverage. Siemens Healthineers occupies the precision imaging platform tier through PET-MRI installations. Jubilant Radiopharma exemplifies specialized distribution capabilities bridging production facilities and hospital nuclear medicine departments.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Nordion |
| Lantheus Medical Imaging |
| Jubilant Radiopharma |
| BWXT Medical |
| Curium Pharma |
| Bracco Imaging |
| Others |
Pricing and Supply Chain Analysis
PET radiochemist concentration in Ontario's Greater Toronto Area creates labor-cost differentials that widen pricing spreads between premium academic centers and community hospital tiers. Health Canada's GMP certification requirements layer compliance overhead onto facility budgets, forcing smaller provinces to absorb premium markups for tracer shipments from centralized cyclotron hubs.
Pricing Analysis
Margin tightening in standard-tier hospital contracts reflects provincial procurement consolidation through Ontario's Health Shared Services and Quebec's Santé Québec. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with research premiums from community hospitals on volume contracts and imaging centers on spot purchases. Cost-down pressure on economy-tier tracers accelerates because Atlantic Canada lacks domestic cyclotron capacity. Academic medical centers show least price sensitivity due to research funding buffers, while independent imaging centers face acute margin compression from fixed reimbursement rates.
Supply Chain Analysis
Dual-sourcing requirements from Health Canada and CNSC mandate qualified backup suppliers for all hospital networks, extending vendor qualification timelines. Geographic supply concentrates in Canada and the United States, with limited European reactor backup for Tc-99m generators. Raw material dependencies center on enriched uranium targets, cyclotron target materials, and sterile manufacturing consumables. Single-source vulnerability pervades F-18 FDG supply given 110-hour half-life constraints that eliminate inventory buffering. Distribution runs through Jubilant Radiopharma's logistics network bridging cyclotron facilities and hospital nuclear medicine departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclotron infrastructure scarcity props pricing power for incumbent producers, creating durable margin pools for those with secured isotope supply. The supply-constrained structure favors asset-heavy participants over lean distributors.
For Market Incumbents: Anticipate radiochemist workforce scarcity constraining operational expansion by locking long-term employment contracts with Ontario and Quebec training programs. Secure backward integration into cyclotron maintenance capabilities to reduce vendor dependency and capture service revenue streams. Counter emerging entrant threats in Western Canada by pre-empting offtake agreements with Alberta Health Services before regional capacity materializes. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Atlantic Canada creates entry whitespace for regional distribution specialists with foreign reactor partnerships. Target under served cardiac imaging demand in Calgary and Edmonton hospital networks lacking local tracer production. Pursue theranostic agent specialization as the go-to-market angle, leveraging Lu-177's longer half-life to reduce logistics complexity versus diagnostic tracers. For Investors and Strategic Acquirers: The window for entry favors cyclotron-integrated platforms with established GMP certification over pure-play distribution assets. Long-term viability hinges on provincial health authority contracting concentration, with integrated producers capturing recurring revenue streams through multi-year offtake structures. Watch Health Canada tracer pipeline approvals as the inflection signal indicating supply expansion versus continued scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Capacity Expansion | Domestic isotope production reduces Atlantic Canada's import dependency and secures supply continuity. |
| GMP Certification Investment | Health Canada facility qualification opens commercial pathways for novel radiopharmaceutical launches. |
| Theranostic Pipeline Development | Paired diagnostic-therapeutic agents enable premium pricing in neuroendocrine and prostate malignancy segments. |
| Provincial Procurement Partnership | Long-term offtake agreements with Ontario Health Shared Services lock in volume commitments. |
| Radiochemist Training Program | University partnerships address workforce scarcity constraining cyclotron facility operational ramp rates. |
Research Methodology
Document review covered Health Canada regulatory filings, CNSC licensing databases, and provincial health authority procurement records, complemented by interviews with nuclear medicine department heads, cyclotron facility managers, GPO contracts specialists, and radiopharmaceutical distribution executives. Secondary validation drew from hospital equipment procurement databases, Canadian Nuclear Safety Commission annual reports, and academic medical center capital expenditure disclosures. Bottom-up facility capacity assessments and top-down provincial health spending analysis were triangulated to anchor market sizing.
Segment-level projections across product type, end user, application, and technology dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from tracer consumption trajectories, scanner installation cycles, and cyclotron capacity buildout schedules. Industry-specific inputs incorporated Vanessa's Law implementation timelines, provincial cyclotron investment announcements, and reimbursement pathway expansions for novel imaging agents.
Inputs from Health Canada and CNSC regulatory databases were available through the study window; gaps in real-time provincial procurement transaction data introduce uncertainty bands around quarterly volume estimates. Deviation in Western Canada cyclotron investment commitments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
Contrast Media Market
Medical Imaging
Portable MRI Market
Medical Imaging
Ultrasound Market