
 Optical Coherence Tomography Market | 2026-2036
Optical Coherence Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Coherence Tomography Market Intelligence
Software-defined image analysis and subscription-based diagnostic platforms are restructuring how OCT systems generate recurring revenue beyond hardware sales. Carl Zeiss Meditec leverages its installed base of ophthalmology suites to sustain service contract penetration across European and North American clinics. Heidelberg Engineering anchors its position through proprietary segmentation algorithms that differentiate workflow integration for glaucoma specialists. Topcon Corporation competes on manufacturing scale, offering modular systems that extend upgrade paths without full device replacement.
Optical coherence tomography is a non-invasive interferometric imaging technique that captures micrometer-resolution cross-sectional tissue maps using near-infrared light, typically operating at wavelengths between 800 nm and 1300 nm depending on target tissue depth and resolution trade-offs. Swept-source OCT systems achieve deeper penetration at 1050 nm, making them essential for posterior segment ophthalmology and intravascular cardiology applications where tissue visualization beyond 2 mm is clinically necessary. Hospitals dominate end-user demand due to capital availability and patient throughput requirements, though ambulatory surgical centers represent the fastest-growing installation segment as outpatient retinal procedures migrate from inpatient settings. Frequency-domain platforms occupy the mature volume tier with stable margins, while hybrid OCT configurations command premium positioning by combining multiple imaging modalities in single devices.
FDA 510(k) clearance requirements shape product development timelines and clinical evidence thresholds for new OCT entrants seeking US market access, while the EU MDR framework demands more extensive post-market surveillance documentation than its predecessor directive. Japan's PMDA maintains distinct technical standards for ophthalmic device software validation that create additional compliance layers for multinational manufacturers. Stakeholders must monitor how reimbursement coding revisions in major markets redefine which OCT procedures qualify for institutional procurement budgets.
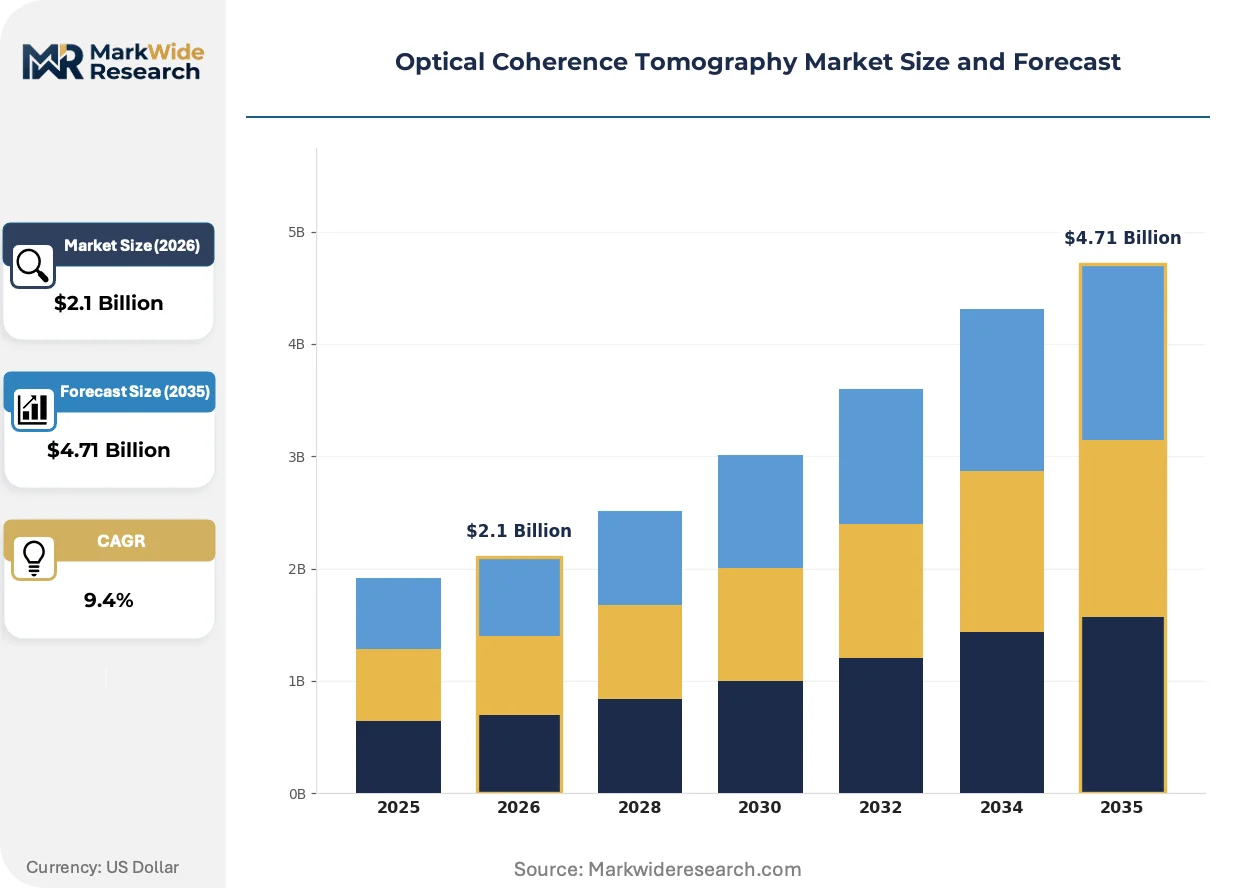
Market Dynamics
Software-defined diagnostic platforms are restructuring revenue models across ophthalmology suites, converting capital equipment sales into recurring service architectures that bind clinicians to vendor ecosystems through proprietary segmentation algorithms and cloud-based image repositories.
Growth Catalysts
- Swept-source wavelength expansion:1050 nm systems penetrate deeper into posterior segments, enabling choroidal and intravascular visualization that frequency-domain platforms cannot achieve. Retinal specialists in Japan and Germany are standardizing these configurations for complex glaucoma monitoring.
- FDA 510(k) pathway efficiency:Class II medical device clearance timelines for OCT software modifications run shorter than de novo classifications, accelerating iterative algorithm deployment for US market entrants.
- Ambulatory surgical center migration:Outpatient retinal procedures are relocating from hospital campuses to ASCs, creating demand for compact, modular systems with upgradeable optical engines rather than full device replacement cycles.
Market Restraints
- Superluminescent diode supply concentration:High-performance light sources for spectral-domain systems concentrate among Japanese and German component suppliers, exposing manufacturers to single-source vulnerability and extended lead times.
- EU MDR post-market surveillance burden:Clinical evidence documentation requirements for software-as-medical-device classifications demand retrospective patient data collection that extends compliance costs beyond pre-market approval phases.
- Optical coherence elastography substitution:Emerging biomechanical tissue characterization methods compete for research funding and clinical validation in corneal disease applications where mechanical property mapping offers diagnostic information beyond structural imaging.
Strategic Opportunities
- India's diagnostic infrastructure expansion:Tier-2 and tier-3 ophthalmology clinics lack swept-source penetration, creating first-mover advantage for manufacturers offering lease-to-own financing on 1050 nm platforms.
- Intraoperative OCT convergence:Microscope-integrated systems combining optical coherence tomography with surgical visualization are integrating into vitreoretinal operating theaters, opening premium pricing tiers for real-time tissue feedback during membrane peeling.
- Japan PMDA software validation streamlining:Revised technical standards for AI-assisted image analysis reduce validation documentation for algorithms trained on domestic patient populations, lowering barriers for Tokyo-based development centers.
Industry Challenges
- Computational pathology skill scarcity:Clinical engineers capable of validating machine learning segmentation against ground-truth histology remain concentrated at academic medical centers, constraining deployment velocity for automated diagnostic workflows.
- Legacy PACS integration friction:Hospital information systems built on DICOM archives from the 2010s require middleware development for cloud-native OCT platforms, extending sales-to-implementation cycles.
- Interoperability standardization delays:IEEE 2791 data provenance specifications for biological imaging remain inconsistently adopted across vendor ecosystems, complicating multi-site clinical trials requiring cross-platform image comparison.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Coherence Tomography Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time-Domain OCT, Frequency-Domain OCT, Swept-Source OCT, Hybrid OCT Application: Ophthalmology, Cardiology, Oncology, Dermatology Technology: In Vivo Imaging, Ex Vivo Imaging, Spectral Domain, Doppler OCT End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Research Institutions |
| Companies Covered | Carl Zeiss Meditec AG, Heidelberg Engineering GmbH, Topcon Corporation, Optovue, Abbott, Leica Microsystems, Thorlabs Inc., NIDEK Co. Ltd., Novacam Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Coherence Tomography Market Strategic Shifts & Innovations
Computational imaging architectures are displacing hardware-centric product development, embedding diagnostic intelligence directly into acquisition systems rather than treating analysis as downstream workstation functionality.
Adaptive optics is integrating wavefront correction into ophthalmic OCT systems, compensating for ocular aberrations that degrade lateral resolution in conventional scanning. Academic medical centers in the United States and Germany are deploying these configurations for photoreceptor layer imaging in inherited retinal disease trials. The technology is integrating research-grade visualization into clinical workflows, compressing the gap between investigative instrumentation and reimbursable diagnostic equipment.
EU MDR Article 10 post-market clinical follow-up requirements now mandate systematic collection of real-world performance data for Class IIa and IIb software-enabled devices. Manufacturers must establish prospective registries or leverage existing electronic health record integrations to demonstrate sustained safety and effectiveness. Small-cap entrants without installed base scale face disproportionate compliance costs, accelerating consolidation toward established European and North American vendors with existing surveillance infrastructure.
Subscription-based diagnostic platforms are unbundling hardware ownership from image analysis access, allowing ambulatory surgical centers to convert capital expenditures into operational budgets aligned with procedure volume fluctuations. This model displaces traditional equipment financing in United States markets where ASC reimbursement rates create cash-flow sensitivity to upfront capital commitments. Germany's clinic chains exhibit similar preference migration, though statutory procurement rules slow contractual innovation relative to private US facilities.
Optical Coherence Tomography Market Segmentation
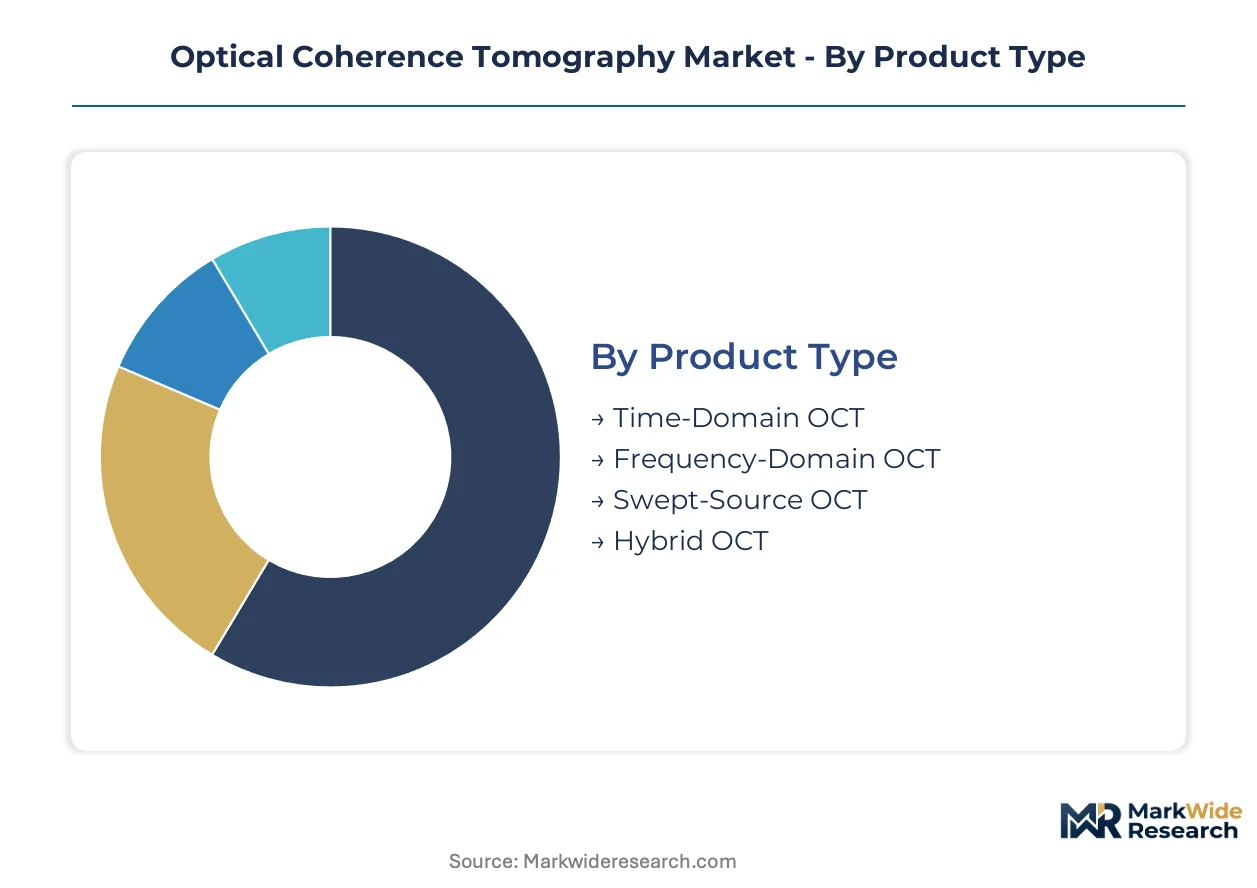
Optical coherence tomography segmentation reflects divergent technical architectures and clinical workflows. Product configurations range from mature frequency-domain platforms to emerging hybrid systems. End-user economics and reimbursement structures determine which technology tiers penetrate specific care settings.
Product Type:
Customization intensity varies sharply across this category, from standardized spectral-domain platforms to bespoke hybrid configurations integrating multiple optical engines.
- Swept-Source OCT:1050 nm wavelength systems achieve tissue penetration beyond 2 mm, enabling choroidal and intravascular visualization. Retinal specialists in Japan and Germany are standardizing these configurations for complex glaucoma monitoring where posterior segment depth is clinically necessary.
- Frequency-Domain OCT:Spectral-domain platforms dominate installed base volume with stable margins and proven reimbursement pathways. Hospital systems in the United States prioritize these systems for high-throughput ophthalmology departments where capital efficiency outweighs premium feature requirements.
- Time-Domain OCT:First-generation mechanical scanning systems retain niche utility in research settings requiring specific historical protocol continuity.
- Hybrid OCT:Multi-modality configurations combine OCT with angiography or autofluorescence in single devices, commanding premium pricing for comprehensive diagnostic workstations.
Most installed capacity flows through Frequency-Domain OCT. Expansion is steepest in Swept-Source OCT.
Application:
Clinical validation depth and regulatory pathway complexity create distinct margin tiers across therapeutic areas.
- Ophthalmology:Retinal imaging constitutes the dominant revenue pool with established CPT reimbursement codes and FDA 510(k) clearance precedents. Aging demographics in the United States, Germany, and Japan sustain replacement demand as hospital systems expand OCT installations as standard diagnostic protocol.
- Cardiology:Intravascular applications leverage swept-source penetration for plaque characterization during catheterization procedures. Japanese medical device manufacturers concentrate development resources here due to domestic interventional cardiology volume and PMDA regulatory familiarity.
- Oncology:Ex vivo tissue margin assessment during tumor resection represents an emerging use case with investigational device exemption requirements constraining near-term commercialization.
- Dermatology:Non-melanoma skin cancer delineation and cosmetic procedure planning drive modest demand in private dermatology practices with discretionary capital budgets.
Revenue concentration sits with Ophthalmology. Cardiology applications are expanding most quickly as intravascular indications mature.
Technology:
Acquisition methodology and analysis depth separate research-grade from clinically deployable platforms.
- Spectral Domain:Fourier-transform detection enables high-speed volumetric capture with micrometer resolution. This architecture underpins most reimbursable clinical workflows in hospital-based ophthalmology suites.
- Doppler OCT:Phase-resolved blood flow quantification adds functional hemodynamic data to structural imaging. Vascular specialists in German university hospitals are piloting these systems for microcirculation assessment in diabetic retinopathy.
- In Vivo Imaging:Real-time tissue visualization during procedures drives demand for integrated surgical microscope configurations in vitreoretinal operating theaters.
- Ex Vivo Imaging:Benchtop pathology applications require distinct optical configurations with higher numerical aperture objectives for cellular-resolution histology correlation.
Deployment volume concentrates in Spectral Domain technology. Doppler OCT is gaining share fastest as functional imaging protocols enter clinical validation.
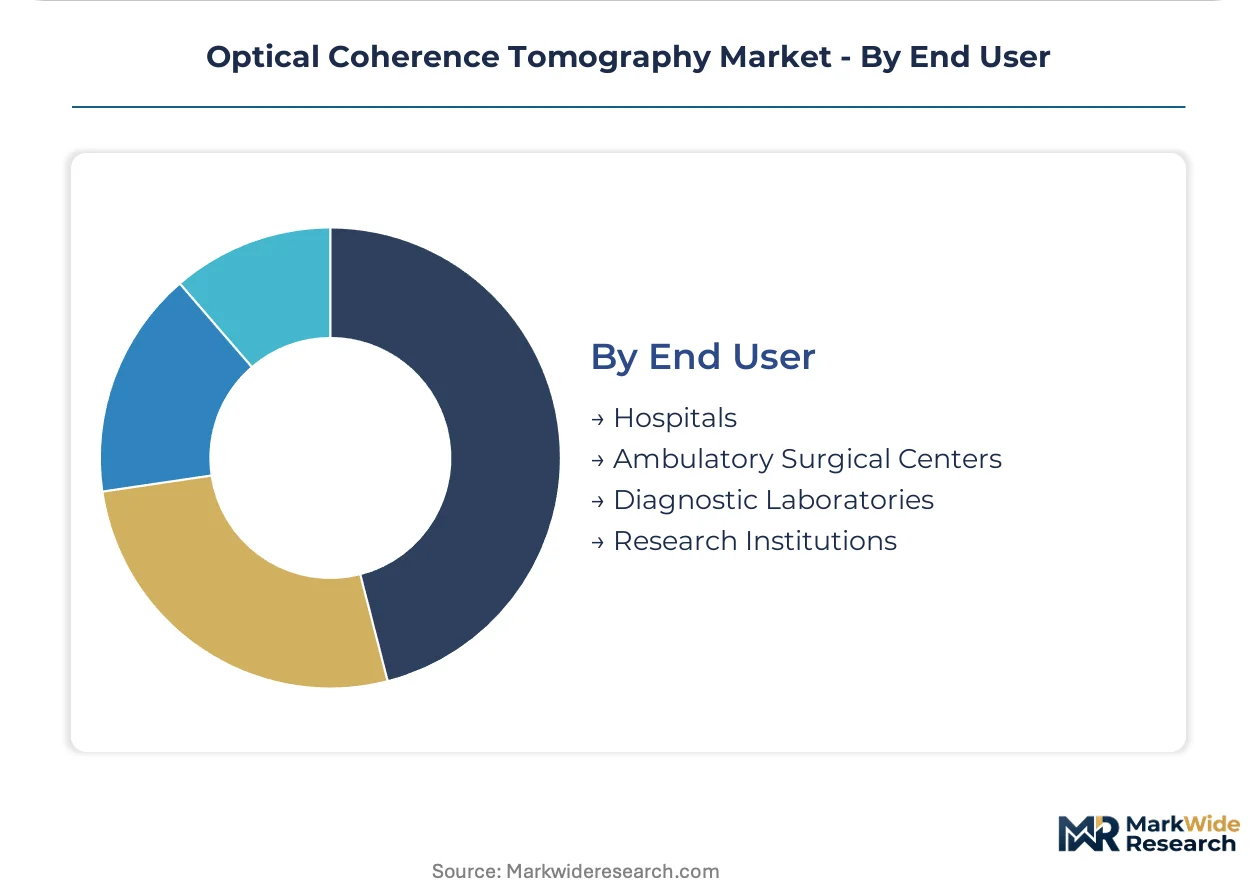
End User:
Capital availability and patient throughput requirements segment procurement behavior across care settings.
- Hospitals:Academic medical centers and community hospital systems deploy multi-station configurations with centralized PACS integration. Capital budgets and established service contracts with Carl Zeiss Meditec and Heidelberg Engineering sustain upgrade cycles.
- Ambulatory Surgical Centers:Outpatient retinal procedure migration from inpatient settings drives demand for compact, modular systems. United States ASCs prefer subscription-based diagnostic platforms that convert capital expenditures into operational budgets aligned with procedure volume fluctuations.
- Diagnostic Laboratories:Centralized imaging facilities serving multiple referring practices require high-throughput automation and standardized reporting protocols.
- Research Institutions:Adaptive optics and computational imaging prototypes deploy here before commercialization, with funding from NIH and German Research Foundation supporting next-generation development.
Hardware ownership concentrates in Hospitals. Ambulatory Surgical Centers show the steepest expansion trajectory as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs diverge sharply across jurisdictions, prompting manufacturers to concentrate software development in regions with streamlined medical device validation while maintaining hardware assembly near component clusters in Germany and Japan.
United States
Hospital systems in California and the Northeast Corridor expand OCT installations as standard diagnostic protocol for aging populations. FDA 510(k) clearance pathways for Class II medical devices accelerate iterative algorithm deployment compared with de novo classifications. Boston's academic medical centers pilot adaptive optics configurations for photoreceptor layer imaging in inherited retinal disease trials.
Germany
Statutory procurement rules shape clinic chain purchasing decisions, slowing subscription-based diagnostic platform adoption relative to private US facilities. EU MDR Article 10 post-market clinical follow-up requirements mandate systematic collection of real-world performance data for software-enabled devices. Heidelberg anchors development of proprietary segmentation algorithms for glaucoma specialists.
Japan
PMDA maintains distinct technical standards for ophthalmic device software validation that create additional compliance layers for multinational manufacturers. METI funding supports swept-source wavelength expansion at 1050 nm for posterior segment visualization. Tokyo-based development centers benefit from revised AI-assisted image analysis standards that reduce validation documentation for domestically trained algorithms.
India
Tier-2 and tier-3 ophthalmology clinics lack swept-source penetration, creating first-mover advantage for manufacturers offering lease-to-own financing on 1050 nm platforms. CDSCO regulatory pathways for imported medical devices require local clinical evidence generation that extends market entry timelines. Maharashtra and Karnataka host expanding diagnostic infrastructure serving domestic patient volumes.
United Kingdom
NHS procurement frameworks prioritize capital-efficient frequency-domain platforms for high-throughput ophthalmology departments. MHRA post-Brexit regulatory alignment with EU MDR creates transitional documentation burdens for software-as-medical-device classifications. London's academic medical centers concentrate computational pathology expertise for machine learning segmentation validation.
Optical Coherence Tomography Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated ophthalmology suite vendors commanding service contract penetration while modular component suppliers compete on manufacturing scale. The vendor base concentrates among German and Japanese precision optics conglomerates with captive distribution networks. Three archetypes dominate: wavelength-engineering specialists, software-defined diagnostic platforms, and microscope-integrated surgical visualization systems. Competitive moves center on proprietary algorithm development and ambulatory surgical center distribution partnerships.
Among Germany-based precision optics conglomerates, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify the integrated-suite archetype, leveraging installed base scale to sustain service contract penetration across European and North American clinics. Topcon Corporation represents the manufacturing-scale tier, offering modular systems that extend upgrade paths without full device replacement cycles. These three anchors illustrate how geographic clustering near superluminescent diode suppliers in Japan and Germany shapes competitive positioning through component access and regulatory familiarity.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Heidelberg Engineering GmbH |
| Topcon Corporation |
| Optovue |
| Abbott |
| Leica Microsystems |
| Thorlabs Inc. |
| NIDEK Co. Ltd. |
| Novacam Technologies Inc. |
| Others |
Cost & Logistics Intelligence
EU MDR Article 10 post-market surveillance mandates gate qualified supply access and premium-tier pricing power by forcing manufacturers to maintain prospective registries and electronic health record integrations. Compliance costs disproportionately burden small-cap entrants without installed base scale, accelerating consolidation toward established vendors with existing surveillance infrastructure and pricing leverage.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for spectral-domain platforms while subscription-based diagnostic platforms convert capital expenditures into operational budgets. Three-tier pricing structure across premium, standard, and economy levels separates swept-source configurations with AI-assisted segmentation from basic frequency-domain systems. Cost compression in standard-tier hardware is intensifying because modular upgrade paths extend replacement cycles. Ambulatory surgical centers in the United States exhibit highest price sensitivity due to reimbursement rate constraints, while academic medical centers show lowest sensitivity given research funding access.
Supply Chain Analysis
Superluminescent diode supply rests on Japanese and German specialty component producers, creating single-source vulnerability for spectral-domain system manufacturers. Optical engines draw from precision optics clusters in Germany, Japan, and the United States, with swept-source laser assemblies concentrated among Tokyo-based suppliers. Tariff exposure on imported ophthalmic device components complicates cost planning for multinational assemblers. Distribution runs through captive service networks of integrated suite vendors and third-party medical device distributors serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR post-market clinical follow-up requirements and FDA 510(k) pathway efficiencies continuously reshape competitive access and procurement economics.
For Market Incumbents: Deploy proprietary algorithm development as the primary lever against optical coherence elastography substitution threats in corneal applications. Deepen backward integration into superluminescent diode supply through strategic partnerships with Japanese component suppliers. Anchor service contract penetration across European and North American clinic chains to lock in replacement demand.
For New Entrants and Emerging Players: Capture India's tier-2 and tier-3 ophthalmology clinics through lease-to-own financing structures on 1050 nm platforms where swept-source penetration remains minimal. Target ambulatory surgical centers in the United States with compact modular systems aligned with outpatient procedure migration. Lead with cloud-native image analysis subscriptions that bypass legacy PACS integration friction.
For Investors and Strategic Acquirers: Roll-up economics work for software-defined diagnostic platforms because EU MDR compliance costs disproportionately burden small-cap entrants without surveillance infrastructure. Five-to-ten year viability favors vendors with installed base scale and proprietary segmentation algorithm portfolios. Watch PMDA software validation streamlining for Tokyo-based development centers as the inflection signal for AI-assisted image analysis consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Cloud-native platforms bind clinicians to vendor ecosystems through proprietary segmentation algorithms and subscription architectures. |
| Hospital System Partnership | Multi-station configurations with centralized PACS integration secure capital budget allocation and service contract renewals. |
| Reimbursement Strategy | CPT code qualification determines institutional procurement eligibility for automated diagnostic workflows in ophthalmology suites. |
| CE Marking Pathway | EU MDR Article 10 compliance mandates systematic real-world performance data collection for software-as-medical-device classifications. |
| FDA Submission | 510(k) clearance timelines for Class II device modifications accelerate iterative algorithm deployment relative to de novo pathways. |
Research Approach
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market cluster. Primary interviews with retinal specialists, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, PMDA submission databases, EU MDR technical documentation, and hospital procurement records. Bottom-up unit economics triangulated against top-down market sizing across product configurations and end-user segments.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product architecture, clinical application, acquisition technology, and care setting procurement behavior. CAGRs derived from installed base replacement cycles, outpatient procedure migration patterns, and software subscription conversion rates. Swept-source wavelength adoption curves and AI-assisted segmentation validation timelines served as ophthalmology-specific forecast inputs.
Regulatory pathway delays, reimbursement coding revisions, and superluminescent diode supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about EU MDR implementation consistency and ASC migration velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Africa Mammography Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
South America CT Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Smart X-Ray Detectors Market