
 Digital Breast Tomosynthesis Market | 2026-2036
Digital Breast Tomosynthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Breast Tomosynthesis Market Analysis
Buyer concentration among hospital networks and large diagnostic chains is restructuring procurement patterns across the Digital Breast Tomosynthesis landscape. Hologic, Inc. leverages its installed base of 3D mammography systems to sustain recurring revenue from service contracts and software upgrades. GE Healthcare anchors its position through integrated digital imaging platforms that span detection, diagnosis, and workflow management. Siemens Healthineers competes on advanced reconstruction algorithms that reduce radiation dose while preserving image clarity.
Digital breast tomosynthesis acquires multiple low-dose X-ray projections across an arc of 15 to 50 degrees, reconstructing thin tomographic slices that minimize tissue overlap artifacts inherent to conventional 2D mammography. Its primary purpose is to improve sensitivity and specificity in breast cancer screening, particularly for women with dense breast tissue. The 3D mammography product segment leads volume deployment where screening programs have secured reimbursement parity with 2D exams, while contrast-enhanced mammography represents the fastest-growing modality for diagnostic workup of suspicious findings. Among end users, diagnostic imaging centers capture expanding share as decentralized screening models reduce patient travel burden and accelerate appointment throughput.
The US FDA oversees quality standards under the Mammography Quality Standards Act, while the EU MDR imposes stricter clinical evidence requirements for breast imaging devices seeking CE marking. Japan's PMDA maintains rigorous technical documentation standards that shape product development priorities for Asia-Pacific entry. Stakeholders must monitor evolving reimbursement thresholds and radiation dose guidelines as health technology assessment bodies recalibrate cost-effectiveness criteria for population screening.
Market Dynamics
Reimbursement parity between 3D mammography and conventional 2D screening is compressing upgrade cycles and forcing manufacturers to bundle software analytics with hardware sales.
Growth Catalysts
- Population-based screening mandates:National health systems in Germany and Japan have incorporated 3D tomosynthesis into standard breast cancer protocols, expanding eligible patient pools.
- FDA's 3D mammography certification requirements:Quality benchmarks under the Mammography Quality Standards Act are accelerating replacement of aging 2D systems in US imaging centers.
- Contrast-enhanced protocol expansion:Dual-energy subtraction techniques are penetrating diagnostic workup workflows for women with dense breast tissue.
Market Restraints
- Capital intensity of gantry replacement:Full-field digital mammography systems require substantial infrastructure investment that constraints independent radiology practices.
- Radiation dose accumulation concerns:Health technology assessment bodies in France and the United Kingdom scrutinize cumulative exposure limits for repeated screening intervals.
- Detector supply concentration:Amorphous selenium and cesium iodide flat-panel manufacturing clusters in East Asia create input vulnerability for Western OEMs.
Strategic Opportunities
- Decentralized screening hubs:Mobile mammography units and community-based diagnostic imaging centers in rural India and Brazil bypass hospital infrastructure bottlenecks.
- Artificial intelligence integration:Computer-aided detection algorithms are converging with tomosynthesis reconstruction to reduce radiologist reading burden.
- EU MDR clinical evidence pathways:Stricter CE marking requirements for breast imaging devices create first-mover advantage for firms with robust post-market surveillance data.
Industry Challenges
- Radiologist training deficits:Interpretation of multi-slice tomosynthesis datasets demands specialized skills that outpace current fellowship program output.
- Legacy PACS integration friction:Older picture archiving systems in mid-sized hospital networks struggle with 3D dataset storage and transmission bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Breast Tomosynthesis Market |
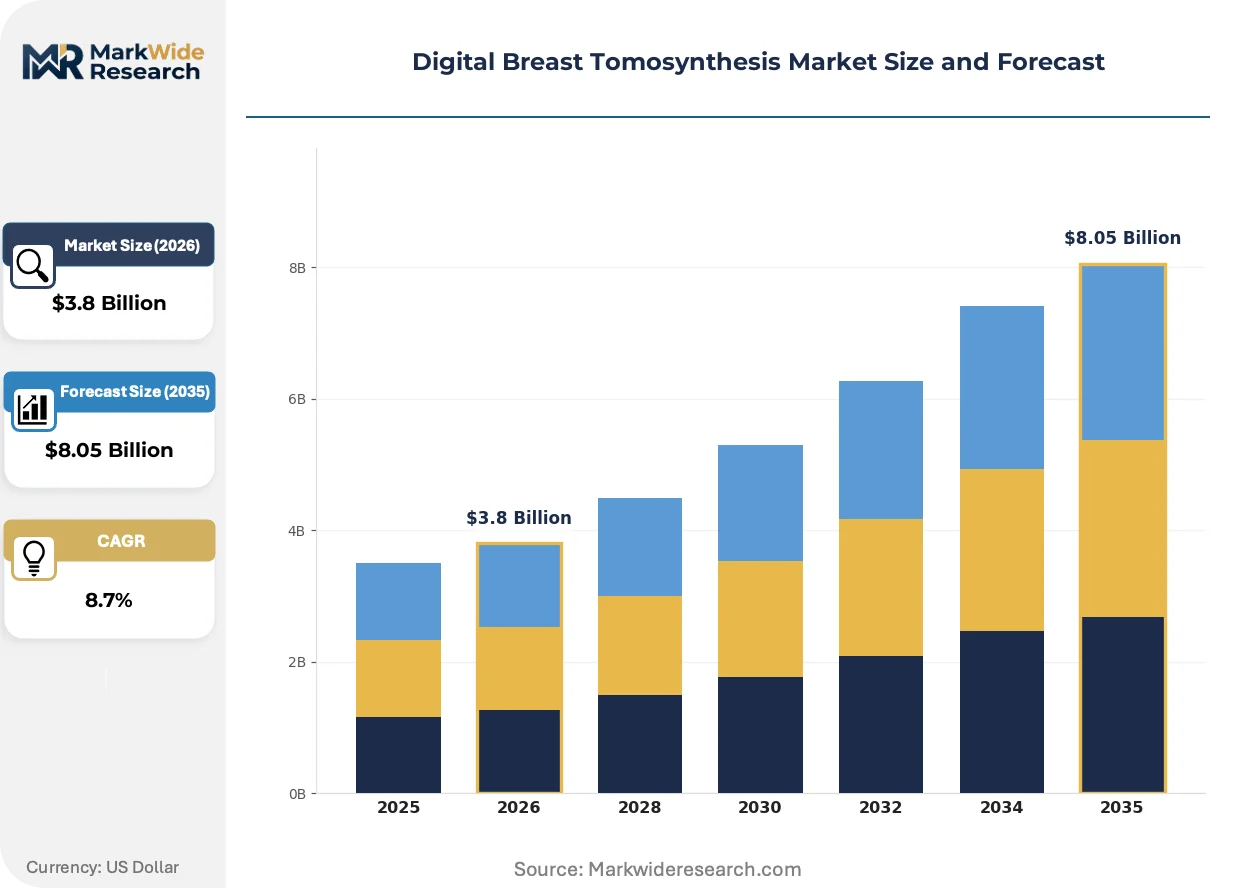
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Mammography, 3D Mammography, Contrast-Enhanced Mammography, Automated Breast Ultrasound End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Outpatient Clinics Technology: Digital Imaging, Analog Imaging, Hybrid Systems, Software Solutions Application: Cancer Detection, Risk Assessment, Screening Programs, Follow-Up |
| Companies Covered | Hologic, Inc., GE Healthcare, Siemens Healthineers, Fujifilm Corporation, Planmed Oy, Internazionale Medico Scientifica, Analogic Corporation, Varex Imaging Corporation, Trivitron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Breast Tomosynthesis Market Emerging Trajectories
Algorithmic reconstruction and dose optimization are compressing the gap between diagnostic accuracy and patient safety, while procurement centralization is restructuring how imaging platforms reach end users.
Photon-counting detector technology is converging with digital breast tomosynthesis architectures to eliminate electronic noise and improve low-contrast lesion visibility. Academic medical centers in the Netherlands and Sweden are piloting these systems for high-risk screening cohorts. The technology is converging with spectral imaging capabilities that separate calcium from soft tissue without additional radiation exposure.
The EU MDR imposes stricter clinical evidence requirements for breast imaging devices seeking CE marking, mandating prospective studies for novel reconstruction algorithms. Manufacturers must submit post-market performance data that extends beyond pre-market equivalence demonstrations. Smaller OEMs with limited clinical affairs resources face disproportionate compliance burdens relative to established imaging conglomerates.
Hospital network procurement consortia are consolidating vendor selection authority previously held by individual radiology departments. Integrated delivery networks in the United States now negotiate enterprise-wide imaging contracts spanning detection, biopsy, and pathology platforms. This concentration is visible most acutely in the American Midwest and Southeastern states where Catholic health systems and for-profit chains dominate regional market access.
Digital Breast Tomosynthesis Market Segmentation
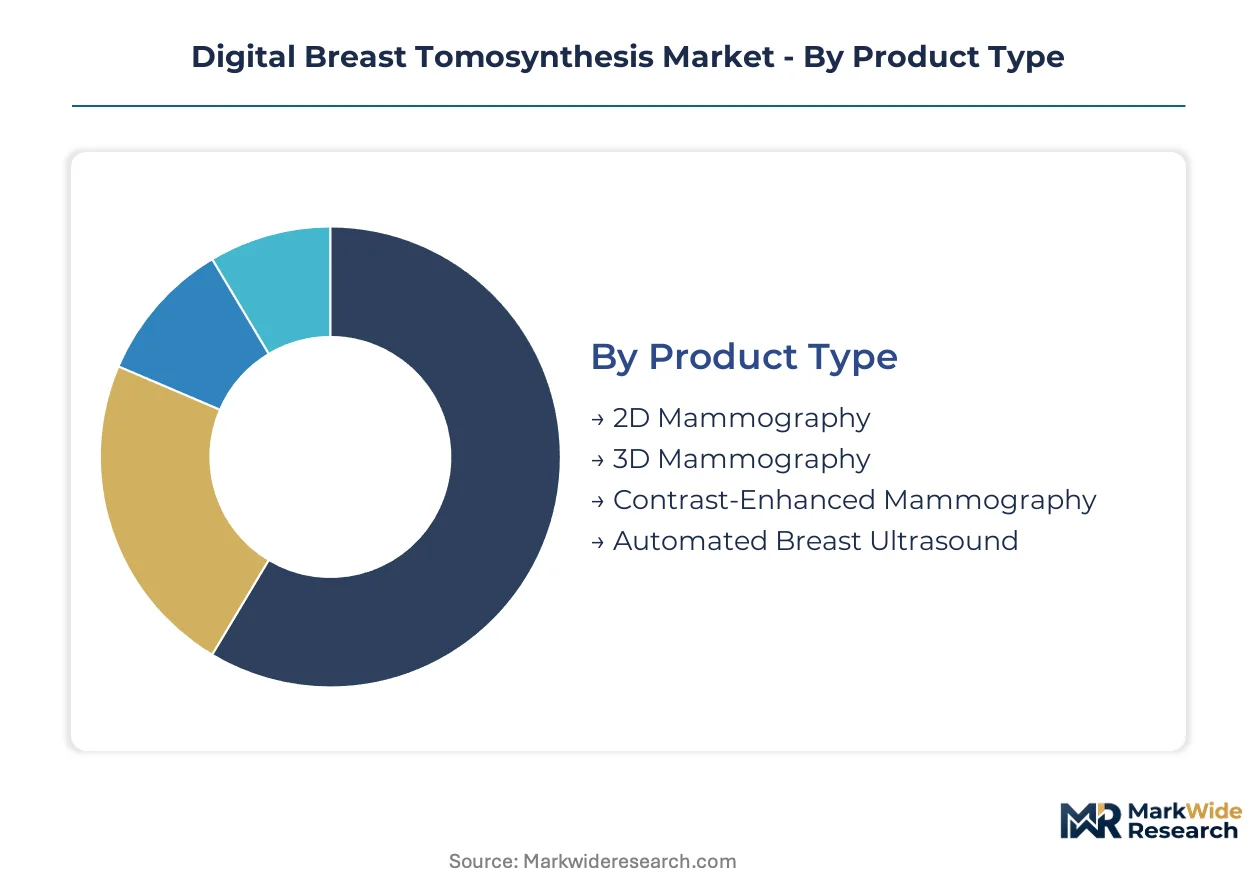
Segmentation in digital breast tomosynthesis reveals how upgrade cycles, reimbursement pathways, and clinical workflows reshape procurement priorities across hardware and software categories. Understanding these divisions exposes where capital concentrates and where emerging modalities gain traction.
Product Type:
Replacement cycles for full-field digital mammography systems now hinge on reimbursement parity decisions by national health technology assessment bodies.
- 2D Mammography:Conventional projection radiography remains entrenched in resource-constrained settings and legacy screening programs. Demand persists in Brazil and India where infrastructure budgets lag reimbursement reform timelines.
- 3D Mammography:Tomosynthesis reconstruction from multiple low-dose projections generates thin tomographic slices that eliminate tissue overlap artifacts. Volume concentrates in the United States, Germany, and Japan where screening programs secured reimbursement parity with 2D exams.
- Contrast-Enhanced Mammography:Dual-energy subtraction techniques enable vascular assessment without MRI referral. The modality is expanding most quickly in diagnostic workup protocols for women with dense breast tissue.
- Automated Breast Ultrasound:Supplementary screening for dense breast populations operates as a secondary detection layer. Deployment clusters in US academic medical centers addressing supplemental screening mandates.
3D Mammography sits at the top of the volume ranking, with Contrast-Enhanced Mammography climbing the fastest.
End User:
Procurement authority is migrating from individual radiology departments toward centralized hospital network consortia and diagnostic chain headquarters.
- Hospitals:Integrated delivery networks in the American Midwest and Southeastern states negotiate enterprise-wide imaging contracts spanning detection through pathology. Capital intensity favors systems with service contract bundling.
- Diagnostic Imaging Centers:Decentralized screening hubs reduce patient travel burden and accelerate appointment throughput. Germany's population-based screening expansion drives capacity additions in standalone facilities.
- Research Institutes:Academic medical centers in the Netherlands and Sweden pilot photon-counting detector architectures. Protocol development focuses on high-risk screening cohorts and dose optimization studies.
- Outpatient Clinics:Community-based access points in rural India and Brazil bypass hospital infrastructure bottlenecks through mobile mammography deployment.
Diagnostic Imaging Centers command the steepest expansion trajectory, with Outpatient Clinics gaining share fastest in emerging markets.
Technology:
Software analytics integration is displacing pure hardware procurement as the primary vendor differentiation mechanism.
- Digital Imaging:Amorphous selenium and cesium iodide flat-panel detectors capture X-ray projections for computational reconstruction. Manufacturing concentration in East Asia creates input vulnerability for Western OEMs.
- Analog Imaging:Legacy screen-film systems persist only in lowest-resource settings. Replacement demand is negligible outside humanitarian screening programs.
- Hybrid Systems:Configurations combining 2D synthetic views with 3D tomosynthesis datasets address workflow compression needs. FDA certification requirements under the Mammography Quality Standards Act shape validation protocols.
- Software Solutions:Computer-aided detection algorithms converge with reconstruction engines to reduce radiologist reading burden. EU MDR clinical evidence pathways mandate prospective performance studies for CE marking.
Digital Imaging retains volume leadership, with Software Solutions capturing margin expansion fastest.
Application:
Clinical utility definitions are broadening as screening program eligibility criteria expand and risk-stratification tools mature.
- Cancer Detection:Diagnostic workup of suspicious findings drives contrast-enhanced protocol adoption. Sensitivity requirements differ between screening-detected and symptomatic presentation pathways.
- Risk Assessment:Density quantification and lesion characterization inform personalized screening intervals. Integration with genetic testing workflows is emerging in US academic centers.
- Screening Programs:Population-based mandates in Germany and Japan incorporate 3D tomosynthesis into standard protocols. Eligible patient pool expansion depends on age-range and density-based inclusion criteria.
- Follow-Up:Post-treatment surveillance and benign lesion monitoring generate recurring imaging volume. Cumulative radiation exposure limits draw scrutiny from French and British health technology assessment bodies.
Screening Programs anchor volume concentration, with Risk Assessment ascending most rapidly as personalization tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan demonstrate divergent pathways for 3D mammography scale-up, with the former integrating tomosynthesis into statutory screening frameworks while the latter pursues density-based eligibility expansion. Both markets contrast with India's emerging mobile deployment model and Brazil's diagnostic chain consolidation.
United States
FDA certification requirements under the Mammography Quality Standards Act are accelerating replacement of aging 2D systems across hospital networks and diagnostic imaging centers. Reimbursement parity between 3D and conventional screening exams compresses upgrade cycles nationwide. The American Midwest and Southeastern states concentrate procurement authority within Catholic health systems and for-profit chains that negotiate enterprise-wide imaging contracts.
Germany
Statutory health insurance integration of 3D tomosynthesis into population-based breast cancer protocols expands eligible patient pools beyond prior density-based limitations. The EU MDR imposes stricter clinical evidence requirements for device CE marking, favoring manufacturers with robust post-market surveillance capabilities. Bavaria and North Rhine-Westphalia anchor diagnostic imaging center capacity additions as decentralized screening models reduce patient travel burden.
Japan
PMDA technical documentation standards shape product development priorities for Asia-Pacific market entry, with density-based screening eligibility criteria driving contrast-enhanced protocol adoption. METI industrial policy supports photon-counting detector pilot programs at academic medical centers. The Kanto region around Tokyo concentrates hospital network procurement decisions, while Kansai diagnostic chains accelerate standalone facility deployment.
India
Community-based diagnostic imaging centers in rural Maharashtra and Gujarat bypass hospital infrastructure bottlenecks through mobile mammography unit deployment. The country's national pharmaceutical regulator maintains import licensing requirements that shape OEM partnership strategies with domestic distributors. Telangana and Karnataka emerge as service hub clusters for Western equipment manufacturers seeking aftermarket revenue streams.
Brazil
Diagnostic chain consolidation in São Paulo and Minas Gerais redirects procurement authority from individual radiology departments toward centralized headquarters. ANVISA medical device registration requirements create compliance timelines that favor established imaging conglomerates over smaller entrants. The country's national supplemental health regulator influences private insurance reimbursement thresholds for 3D screening exams.
Digital Breast Tomosynthesis Market Vendor Landscape
North American producers anchor the premium-system tier; European specialists hold algorithmic differentiation and dose-optimization capabilities. Market structure tilts toward consolidated procurement relationships between hospital networks and imaging conglomerates, with mid-tier independents occupying service-intensive niches. Three archetypes dominate: full-platform integrators, reconstruction-software specialists, and detector-component suppliers. Competitive moves concentrate on strategic partnerships for AI integration and geographic licensing agreements for emerging market access.
Within the full-platform integrator tier, Hologic, Inc. and GE Healthcare occupy positions defined by installed base scale and enterprise contract penetration. Siemens Healthineers exemplifies the algorithmic-specialist archetype, with reconstruction-engine capabilities that reduce radiation dose while preserving image clarity. These three conglomerates represent the primary competitive anchors, with Fujifilm Corporation and Planmed Oy sitting within the mid-tier service and regional-access segment where procurement flexibility and localized support capabilities differentiate positioning.
| Leading Market Players |
|---|
| Hologic, Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Corporation |
| Planmed Oy |
| Internazionale Medico Scientifica |
| Analogic Corporation |
| Varex Imaging Corporation |
| Trivitron Healthcare |
| Others |
Supply Flow & Price Mechanics
Captive integration of flat-panel detector manufacturing by East Asian suppliers anchors both supply security and pricing power for Western OEMs navigating procurement consolidation. This vertical control over amorphous selenium and cesium iodide inputs shapes cost structures across premium and standard system tiers while hospital network buyers leverage volume scale for service contract bundling.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for digital imaging components while Western OEMs defend margin position through software analytics bundling. Three-tier pricing structure across premium photon-counting systems, standard tomosynthesis platforms, and economy 2D retrofit configurations reflects FDA certification tier and after-sales service depth. Cost compression in the standard tier intensifies because diagnostic imaging centers prioritize throughput metrics over reconstruction algorithm sophistication. Independent radiology practices exhibit highest price sensitivity, while integrated delivery networks in the American Midwest accept premium positioning for enterprise contract coherence.
Supply Chain Analysis
Freight cost volatility for precision gantry components from Germany and Japan complicates inventory planning for OEMs assembling systems in North American and European final configuration facilities. Manufacturing concentration for amorphous selenium flat-panels in South Korea, Taiwan, and China creates single-source vulnerability for detector substrates, while cesium iodide scintillator supply draws from Japanese chemical processors. Tariff exposure on precision motion control systems sourced from German suppliers threatens margin stability for mid-tier independents. Distribution runs through hospital network procurement consortia and diagnostic chain headquarters that negotiate enterprise-wide imaging contracts spanning detection through pathology platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA's Mammography Quality Standards Act certification requirements and EU MDR clinical evidence pathways continuously refresh replacement demand and elevate compliance barriers for new entrants.
For Market Incumbents: To counter algorithmic displacement by AI-native diagnostic software vendors, Hologic, GE Healthcare, and Siemens Healthineers should deepen backward integration into photon-counting detector architectures and secure exclusive hospital system partnerships for enterprise imaging contracts spanning detection, biopsy, and pathology workflows. For New Entrants and Emerging Players: Rural diagnostic imaging centers in India and Brazil represent the most penetrable buyer archetype, with mobile mammography deployment models and localized service capabilities offering entry pathways that bypass entrenched OEM hospital network relationships. Contrast-enhanced mammography protocols for dense breast populations present white-space expansion opportunity. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier imaging service specialists because hospital procurement centralization creates stranded radiology department relationships that regional players can aggregate. Target firms with dense breast tissue screening protocol expertise and established CE marking documentation. Watch FDA photon-counting detector approval timelines as inflection indicator for next-generation platform transition.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 3D Mammography Certification Pathway | Accelerates replacement cycles for aging 2D systems under Mammography Quality Standards Act enforcement. |
| EU MDR Clinical Evidence Development | Mandates prospective post-market surveillance studies that favor established manufacturers with regulatory affairs scale. |
| Hospital System Partnership Expansion | Locks in enterprise-wide imaging contracts across Catholic health networks and for-profit chains in American Southeast. |
| AI Companion Software Development | Reduces radiologist reading burden for multi-slice tomosynthesis datasets amid training deficit constraints. |
| Reimbursement Strategy Execution | Secures parity pathways for 3D screening exams with statutory health insurance frameworks in Germany and Japan. |
Methodological Framework
Bottom-up diagnostic imaging center capacity modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and radiology department directors combined with secondary validation against FDA 510(k) filings, EU MDR CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement system records. Triangulation across these sources ensures cross-verification of installed base estimates and replacement cycle timing.
Historical trendline analysis of upgrade cycles from 2D to 3D mammography systems informs projection parameters across the analysis window. Segmentation modeling spans product type, end user category, technology architecture, and application purpose, with regional regulatory cluster and reimbursement pathway status as additional forecast dimensions. CAGRs derive from curve-fitting against technology adoption S-curves and health technology assessment body approval timelines, incorporating radiation dose guideline evolution and AI integration penetration as industry-specific inputs.
Underlying measurement precision varies by segment; 3D mammography installed base estimates carry tighter precision than contrast-enhanced protocol adoption figures where pilot program status creates ambiguity. Forecasts reflect assumptions regarding reimbursement parity expansion, regulatory approval timelines, and supply chain stability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
South America CT Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market