
 Global CT Scanners Market | 2026-2036
Global CT Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Global CT Scanners Market Foresight
The capability gap between photon-counting CT developers and conventional detector manufacturers is collapsing as capital requirements for semiconductor-grade crystal growth fall. Siemens Healthineers leverages its dual-source architecture to sustain premium positioning in cardiac imaging. GE Healthcare anchors North American hospital networks through long-term service contracts and tube-replacement logistics. Shanghai United Imaging Healthcare competes on domestic cost structures while navigating export certification complexity in Europe.
Computed tomography scanners generate cross-sectional anatomical images using rotating X-ray tubes and detector arrays, with modern systems achieving sub-millimeter spatial resolution through helical acquisition and iterative reconstruction algorithms. Photon-counting CT represents a detector-material leap, replacing energy-integrating scintillators with cadmium-zinc-telluride semiconductors that directly convert X-ray photons to electronic signals, enabling spectral imaging at equivalent or reduced dose. Spiral CT systems dominate installed base economics due to proven throughput and service infrastructure, while photon-counting CT captures fastest-growing demand as hospitals prioritize tissue-characterization accuracy for oncology staging. Mobile CT units command margin premiums in stroke-network configurations where deployment speed determines reimbursement capture.
The FDA enforces radiation dose benchmarks through the National Electrical Manufacturers Association XR-29 standard, while the EU Medical Device Regulation requires clinical evidence updates for legacy CT platforms. China's NMPA accelerates approval pathways for domestically manufactured photon-counting systems under innovation-device designation. Stakeholders must monitor detector supply chain concentration and spectral-imaging reimbursement decisions.
Market Dynamics
Photon-counting detector technology is collapsing the historical performance gap between premium and mid-tier CT platforms, forcing incumbent manufacturers to accelerate semiconductor-grade crystal production investments or cede spectral imaging margins.
Growth Catalysts
- Oncology Staging Demand:Academic medical centers in China, Germany, and the United States are expanding CT fleet capacity to handle complex tumor characterization protocols requiring dual-energy acquisition.
- FDA MQSA Extension:Updated radiation dose reporting requirements under the Mammography Quality Standards Act extension are accelerating detector material upgrades across installed base systems.
- Cadmium-Zinc-Telluride Maturation:Falling capital requirements for semiconductor-grade crystal growth are democratizing photon-counting CT access beyond early-adopter institutions.
Market Restraints
- Detector Supply Concentration:Cadmium-zinc-telluride substrate production concentrates among three specialized foundries in Japan and Germany, creating single-source vulnerability for CT OEMs.
- EU MDR Clinical Evidence Burden:The EU Medical Device Regulation requires retrospective clinical evidence updates for legacy CT platforms, extending recertification timelines and freezing capital allocation.
- Helical CT Infrastructure Lock-In:Decades of spiral CT service infrastructure investment creates switching costs that delay photon-counting adoption at mid-tier hospitals.
Strategic Opportunities
- Mobile Stroke Networks:Deployable CT units configured for thrombectomy triage command reimbursement premiums where deployment speed determines patient capture in Brazil and India.
- NMPA Innovation Pathways:China's National Medical Products Administration accelerates approval timelines for domestically manufactured photon-counting systems under innovation-device designation.
- Spectral Imaging Reimbursement:Proposed Category III CPT codes for tissue-characterization CT in the United States would unlock new revenue streams for hospitals investing in detector upgrades.
Industry Challenges
- Semiconductor Physics Talent Scarcity:Cadmium-zinc-telluride crystal growth and photon-counting ASIC design require specialized skill sets concentrated among legacy nuclear imaging suppliers.
- Legacy PACS Integration Friction:Spectral CT data volumes overwhelm conventional picture-archiving infrastructure, forcing hospitals into parallel storage investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CT Scanners Market |
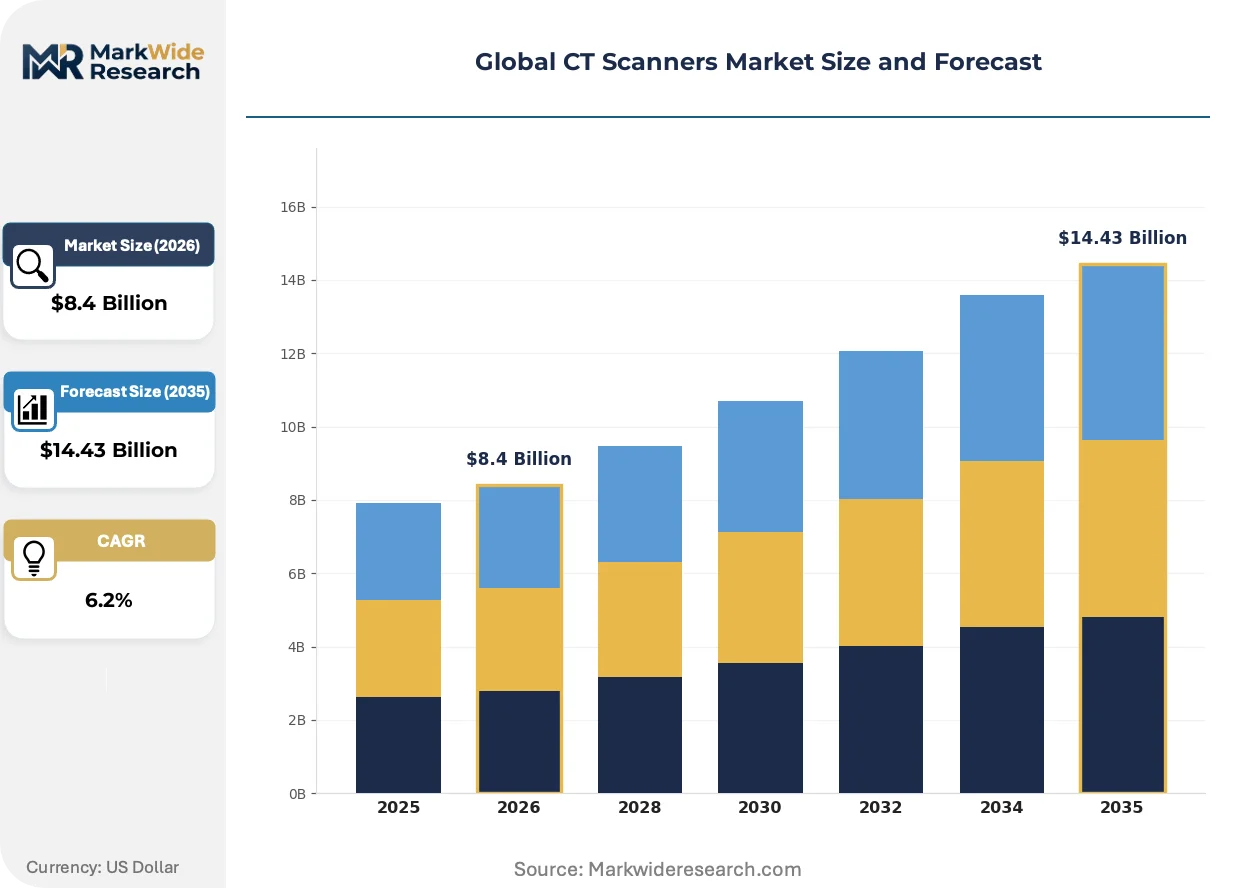
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary CT, Portable CT, Mobile CT, Cone Beam CT Technology: Spiral CT, Multi-slice CT, Dual-source CT, Photon-counting CT Application: Cardiovascular Imaging, Oncology Imaging, Neurological Imaging, Pulmonary Assessment End User: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings Corporation, Neusoft Medical Systems, Shanghai United Imaging Healthcare, Shimadzu Corporation, Hitachi Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CT Scanners Market Shifts & Advancements
Detector material physics and regulatory dose frameworks are jointly compressing the technology refresh cycle, shortening replacement intervals for energy-integrating platforms while spectral imaging capabilities redefine clinical utility benchmarks.
Photon-counting CT is displacing conventional scintillator-based detectors across premium hospital segments. Cadmium-zinc-telluride semiconductors directly convert X-ray photons to electronic signals, eliminating the light-conversion step that degrades energy resolution in legacy systems. Major oncology centers in the United States and Germany are prioritizing photon-counting platforms for staging protocols requiring iodine quantification. This displacement is compressing residual value for helical CT fleets and forcing service contract renegotiations.
The EU Medical Device Regulation's clinical evidence requirements for legacy platform recertification are extending compliance timelines. Manufacturers must submit retrospective performance data for systems predating the 2017 framework, diverting regulatory affairs resources from new product submissions. European hospital procurement committees are responding by accelerating replacement schedules for pre-MDR systems rather than absorbing recertification costs.
Chinese hospital consolidation in tier-one cities is concentrating purchasing authority among provincial health commissions. Bulk procurement frameworks for Shanghai, Beijing, and Guangzhou hospital networks are displacing individual hospital capital committees as the primary decision node. This concentration favors domestic manufacturers with cost-optimized photon-counting platforms and established NMPA innovation-device relationships.
Global CT Scanners Market Segmentation
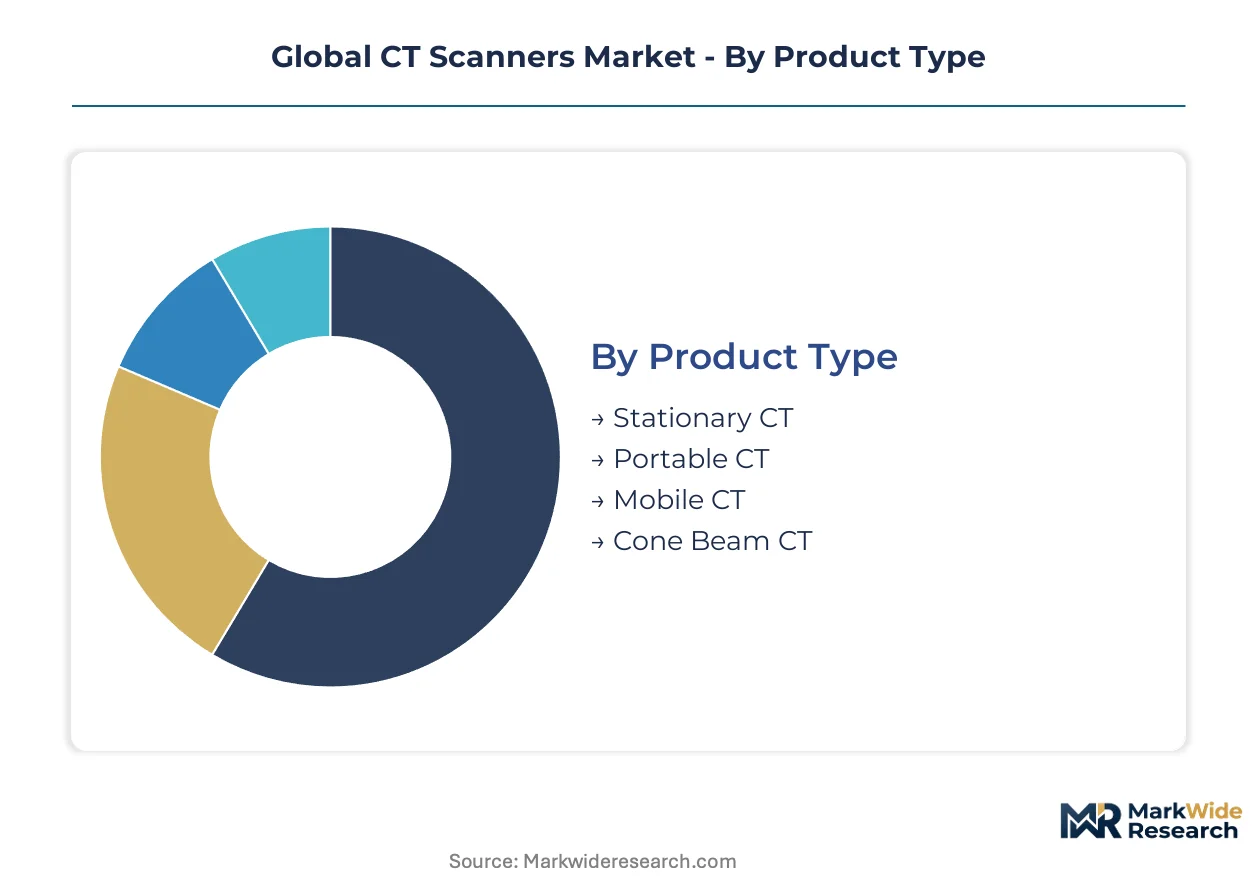
CT scanner procurement decisions cluster around detector physics, deployment mobility, and reimbursement capture mechanics. Segmentation reveals where capital allocation concentrates across academic medical centers, consolidated hospital networks, and point-of-care triage configurations.
Product Type:
FDA XR-29 dose reporting requirements and EU MDR recertification burdens are diverting replacement capital toward platforms with detector-upgrade pathways.
- Stationary CT:Fixed-room installations with gantry weights exceeding 2,000 kilograms dominate oncology staging throughput at academic medical centers in Germany and the United States. Helical acquisition protocols and established service infrastructure sustain residual demand despite photon-counting displacement pressure.
- Mobile CT:Self-contained units on wheeled chassis command stroke-network premiums where deployment speed determines thrombectomy patient capture in Brazil and India. NMPA innovation-device pathways are accelerating domestic Chinese production for tier-one city bulk procurement.
- Portable CT:Compact systems with battery-power options serve ICU bedside imaging where patient transport risks outweigh resolution trade-offs.
- Cone Beam CT:Flat-panel detector architecture optimized for dental and extremity imaging occupies lower-throughput diagnostic niches.
Established volume favors Stationary CT; emerging adoption favors Mobile CT.
Technology:
Cost tiers separate energy-integrating legacy platforms from semiconductor-grade spectral systems requiring cadmium-zinc-telluride substrate supply.
- Photon-counting CT:Cadmium-zinc-telluride semiconductors directly convert X-ray photons to electronic signals, eliminating light-conversion degradation. Major oncology centers in the United States and Germany prioritize these platforms for iodine quantification protocols.
- Spiral CT:Continuous patient translation during tube rotation enables sub-millimeter volumetric acquisition. Decades of installed base economics and service infrastructure sustain mid-tier hospital demand despite spectral imaging displacement.
- Multi-slice CT:Parallel detector arrays capturing 64 to 320 simultaneous slices balance throughput against capital expenditure constraints.
- Dual-source CT:Two X-ray tubes operating at distinct kilovolt potentials deliver temporal resolution for cardiac imaging without beta-blocker administration.
Procurement gravity concentrates on Photon-counting CT for new installations; Spiral CT sustains replacement cycles where spectral reimbursement remains unconfirmed.
Application:
Customer type determines resolution requirements and throughput economics across diagnostic workflows.
- Oncology Imaging:Tumor characterization protocols requiring dual-energy acquisition and iodine quantification are concentrating demand at photon-counting-equipped academic medical centers in China, Germany, and the United States.
- Cardiovascular Imaging:Coronary artery visualization demands sub-millimeter spatial resolution and motion-correction algorithms, sustaining dual-source CT premiums.
- Neurological Imaging:Stroke triage protocols prioritize speed over spectral capability, favoring mobile CT deployment in network configurations.
- Pulmonary Assessment:Interstitial lung disease tracking and emphysema quantification utilize standard helical throughput without spectral differentiation.
Reimbursement expansion favors Oncology Imaging; network efficiency favors Cardiovascular Imaging.
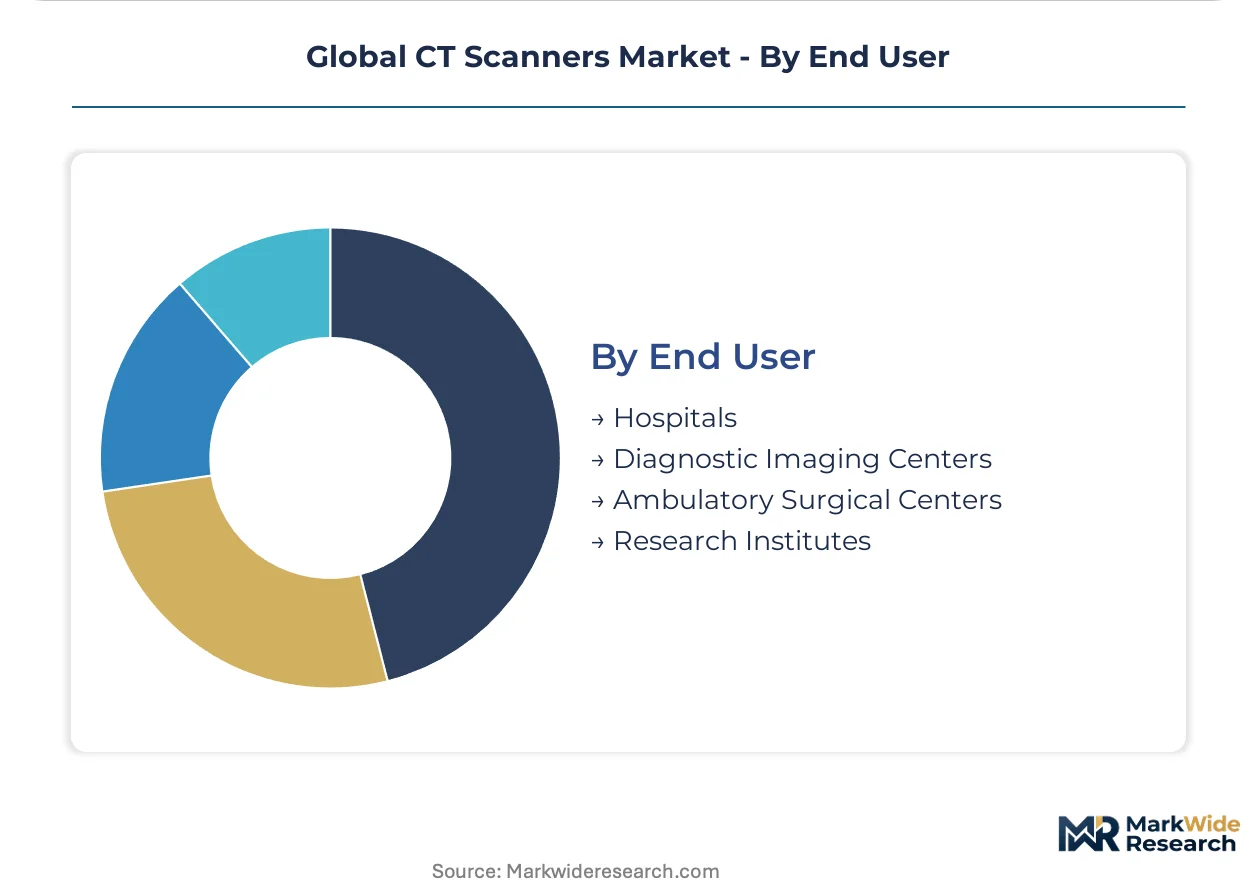
End User:
Volume concentration and capital access separate institutional tiers across procurement authority structures.
- Hospitals:Consolidated networks in Shanghai, Beijing, and Guangzhou exercise provincial health commission purchasing authority for bulk photon-counting procurement. Long-term service contracts and tube-replacement logistics anchor vendor relationships.
- Diagnostic Imaging Centers:Independent facilities prioritize throughput-per-dollar metrics and PACS integration compatibility over spectral imaging capabilities.
- Ambulatory Surgical Centers:Limited capital budgets and space constraints favor compact helical systems with proven reimbursement codes.
- Research Institutes:Phantom studies and algorithm development drive demand for experimental photon-counting platforms ahead of clinical deployment.
Capital deployment favors Hospitals; spectral imaging access favors Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification complexity in Europe and domestic cost advantages in Asia are reshaping trade flows for photon-counting systems. Germany and Japan maintain detector substrate production dominance while China scales domestic manufacturing capacity.
United States
Academic medical centers in Boston, Houston, and Palo Alto are expanding CT fleet capacity for complex tumor characterization protocols. The FDA's XR-29 dose reporting standard accelerates detector material upgrades across installed base systems. The Cleveland Clinic and MD Anderson anchor premium photon-counting procurement in the Midwest and Southwest corridors.
Germany
Major oncology centers in Munich and Heidelberg prioritize spectral imaging platforms for iodine quantification staging workflows. The EU Medical Device Regulation extends recertification timelines for legacy helical CT platforms. Baden-Württemberg's semiconductor foundry cluster supplies cadmium-zinc-telluride substrates to European OEMs.
China
Hospital consolidation in Shanghai, Beijing, and Guangzhou concentrates purchasing authority among provincial health commissions. The NMPA accelerates approval pathways for domestically manufactured photon-counting systems under innovation-device designation. Yangtze River Delta bulk procurement frameworks favor cost-optimized domestic platforms.
Japan
Specialized foundries in the Kansai and Chubu regions concentrate semiconductor-grade crystal growth for photon-counting detector substrates. METI industrial policy supports advanced medical imaging component exports. Osaka-based suppliers anchor the three-firm cadmium-zinc-telluride production network.
Brazil
Mobile CT deployment in São Paulo and Rio de Janeiro stroke networks commands reimbursement premiums where deployment speed determines patient capture. ANVISA regulatory pathways for imported diagnostic equipment create certification bottlenecks. Southeast Brazil's hospital networks prioritize deployable units over fixed-room installations.
Global CT Scanners Market Competitive Landscape
Concentration sits with diversified imaging conglomerates and domestic cost-optimized specialists. The vendor base separates into three tiers: premium-tier photon-counting developers with semiconductor supply control, mid-tier helical CT service incumbents leveraging installed base lock-in, and emerging domestic manufacturers exploiting regulatory fast-tracks. Competitive moves center on long-term service contract anchoring and detector substrate supply partnerships.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers exemplify premium-tier positioning through dual-source architecture and spectral imaging portfolios. Shanghai United Imaging Healthcare represents the domestic specialist archetype competing on cost structures within China's tier-one city procurement frameworks. Koninklijke Philips occupies a position between premium technology access and mid-tier service infrastructure scale.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Neusoft Medical Systems |
| Shanghai United Imaging Healthcare |
| Shimadzu Corporation |
| Hitachi Healthcare |
| Others |
Supply & Pricing Matrix
Semiconductor-grade crystal growth scale economies in Japan and Germany concentrate substrate supply among three specialized foundries, simultaneously establishing price floors for photon-counting CT systems and compressing margins for detector-dependent OEMs unable to secure captive supply arrangements.
Pricing Analysis
Hospital network procurement committees anchor CT system pricing through multi-year service contract bundling. Three-tier pricing structure across premium photon-counting, standard helical, and economy refurbished platforms separates academic medical centers from mid-tier hospitals and diagnostic imaging centers. Pricing pressure stems from China's provincial bulk procurement frameworks favoring domestic cost structures. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints and space limitations.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes delays cadmium-zinc-telluride substrate shipments from Osaka and Kansai foundries to German detector assembly plants. Japan, Germany, and China concentrate semiconductor-grade crystal growth, scintillator material processing, and gantry manufacturing respectively. The supply chain draws from cadmium, zinc, telluride raw materials and specialized ASIC components. Single-source vulnerability concentrates among Japanese substrate producers. Distribution runs through hospital GPO contracts and provincial health commission bulk frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from tube replacement programs and detector upgrade pathways is expanding faster than hardware sales as hospitals extend fleet lifecycles through modular retrofits rather than full system replacement.
For Market Incumbents: Compound installed base lock-in through long-term tube replacement logistics and spectral imaging software subscription layering. Accelerate backward integration into cadmium-zinc-telluride substrate production to offset Japanese foundry concentration risk. Defend against Shanghai United Imaging Healthcare's NMPA-fast-tracked domestic platforms by anchoring North American hospital networks through exclusive service contracts. For New Entrants and Emerging Players: Aftermarket detector retrofit capabilities for legacy helical CT fleets represent the most penetrable service gap as incumbents prioritize new system sales over upgrade pathway development. Target mid-tier hospital networks in Brazil and India where mobile stroke network deployment premiums reward speed-to-market over brand recognition. Pursue ANVISA and CDSCO regulatory fast-tracks ahead of premium-tier competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among detector substrate suppliers with multi-year offtake agreements to Siemens Healthineers and GE Healthcare. Semiconductor-grade crystal growth specialists command durable margins over the projection horizon due to physics talent scarcity and three-firm supply concentration. Monitor NMPA innovation-device approval velocity as inflection indicator for Chinese domestic manufacturer market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Substrate Supply Agreement | Secures cadmium-zinc-telluride wafer allocation from Osaka foundries for photon-counting platform scaling. |
| NMPA Innovation-Device Pathway | Accelerates approval timelines for domestically manufactured spectral imaging systems in Shanghai procurement frameworks. |
| Hospital System Partnership | Locks long-term service contracts with Cleveland Clinic and MD Anderson for tube replacement logistics. |
| Software Companion Development | Enables iodine quantification protocols for oncology staging at German academic medical centers. |
| Reimbursement Strategy | Positions for Category III CPT code expansion for tissue-characterization CT in United States payment systems. |
Research Methodology
A standing panel of hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at CT OEMs provided ongoing calibration against primary interview transcripts and secondary validation. Sources included FDA 510(k) filings, NMPA innovation-device registries, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks from trade associations and regulatory filings. The forecast framework segmented by detector technology, product mobility tier, clinical application, and end-user institutional type. CAGRs derived from replacement cycle analysis, spectral imaging reimbursement trajectory, and provincial health commission capital allocation patterns. Modeled inputs included cadmium-zinc-telluride substrate production capacity and NMPA approval velocity.
Forecasts assume regulatory continuity in FDA XR-29 dose reporting, EU MDR recertification timelines, and NMPA innovation-device pathways; material policy shifts would require re-modeling. Detector supply concentration, spectral imaging reimbursement decisions, and hospital consolidation velocity represent primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Italy Mammography Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market