
 Medical X-Ray Market | 2026-2036
Medical X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Medical X-Ray Market Analysis
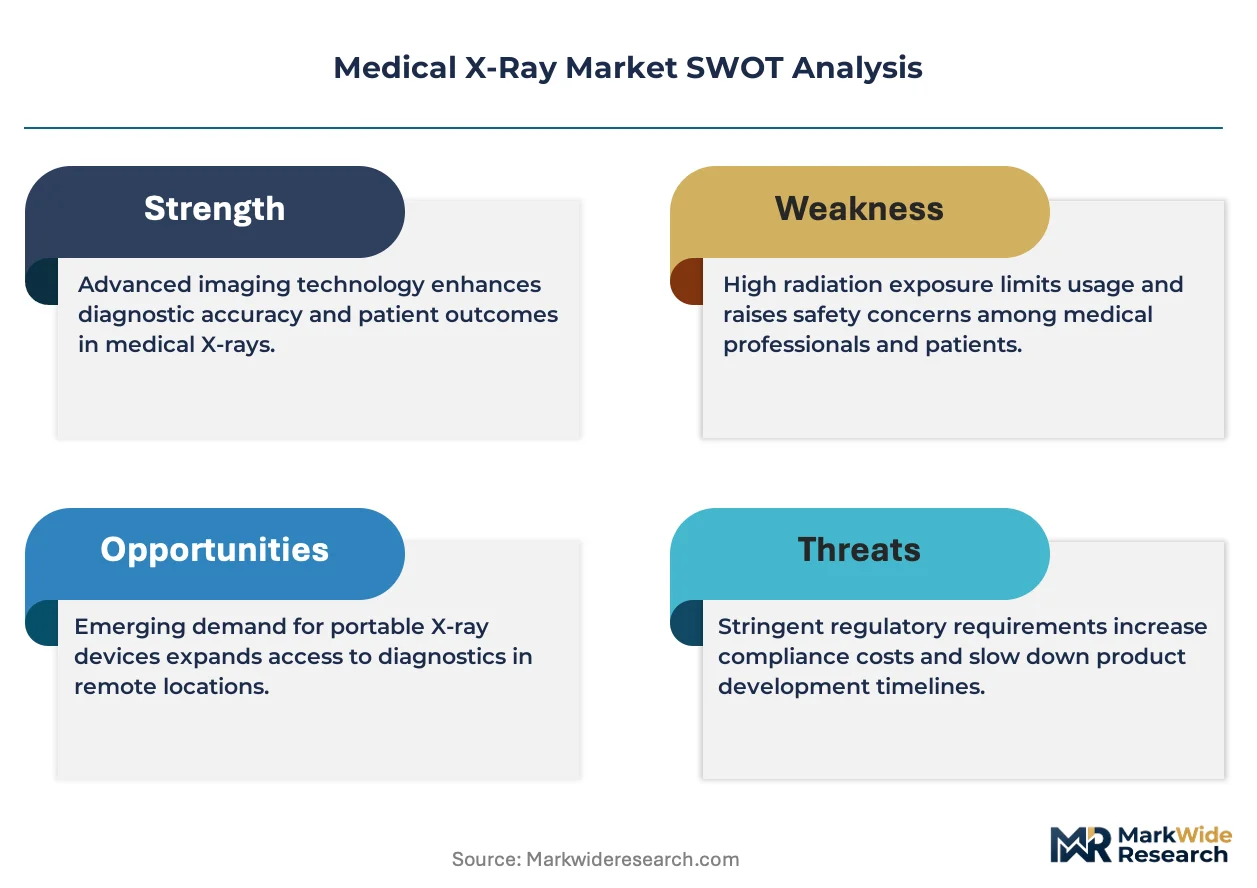
Cesium iodide scintillator layers is restructuring flat panel detector economics across the Medical X-Ray landscape. Siemens Healthineers AG leverages vertical integration from detector materials through system assembly to capture margin pools in premium radiography. GE Healthcare anchors North American hospital procurement through long-term service contracts tied to digital X-Ray installations. Canon Medical Systems specializes in fluoroscopy hybrid suites that combine diagnostic and interventional workflows.
Medical X-Ray denotes ionizing radiation imaging systems utilizing tungsten anode tubes generating bremsstrahlung radiation in the 20-150 kVp range, with image capture transitioning from film-screen combinations to solid-state digital receptors for anatomical visualization and disease diagnosis. Digital X-Ray systems now dominate installed base replacements as computed radiography plate systems face obsolescence from slower workflow throughput and higher long-term consumable costs. Flat panel detector technology leads technology segmentation with direct conversion amorphous selenium and indirect conversion cesium iodide architectures displacing traditional radiography in high-volume hospital settings.
The FDA 510(k) pathway and IEC 60601-1-3 dose standards govern product entry and radiation safety benchmarks in the United States, while the EU MDR and CE marking requirements reshape conformity assessment burdens for fluoroscopy and portable X-Ray equipment sold across European member states. Stakeholders must monitor how AI-enabled diagnostic algorithms trigger new regulatory classification categories that could separate software-enabled systems from conventional hardware-only platforms.
Market Dynamics
The transition from computed radiography to flat panel detector systems is compressing replacement cycles across hospital radiology departments while simultaneously elevating capital expenditure requirements for integrated delivery networks.
Growth Catalysts
- FDA 510(k) Modernization:Streamlined clearance pathways for AI-enhanced imaging platforms are accelerating commercialization timelines for software-enabled diagnostic systems in the United States.
- Cesium Iodide Scintillator Adoption:Indirect conversion detector architectures are displacing amorphous selenium in high-throughput hospital settings due to superior dose efficiency and manufacturing scalability.
- Integrated Delivery Network Consolidation:Hospital system aggregation in the United States is standardizing procurement specifications across multi-facility footprints, favoring vendors with comprehensive service capabilities.
Market Restraints
- Tungsten Supply Concentration:Anode tube manufacturing depends on concentrated rare earth processing capabilities, creating input cost volatility exposure for system producers.
- EU MDR Conformity Burden:Enhanced clinical evidence requirements for fluoroscopy equipment are extending certification timelines and elevating regulatory compliance costs for European market entry.
- Computed Radiography Obsolescence:Legacy plate-based systems face accelerated depreciation as workflow throughput limitations render them economically uncompetitive against digital alternatives.
Strategic Opportunities
- Rural Hospital Digitalization:Underpenetrated community health systems in the United States present retrofit demand for cost-optimized digital radiography configurations.
- AI-Radiology Convergence:Machine learning algorithms integrated with acquisition hardware are creating new reimbursement categories for computer-aided detection in mammography and chest imaging.
- Portable System Expansion:Battery-powered mobile X-Ray units are penetrating emergency department and intensive care workflows previously served by fixed installations.
Industry Challenges
- Detector Calibration Expertise:Solid-state receptor maintenance requires specialized biomedical engineering capabilities that outpace current training pipeline output.
- Legacy PACS Integration:Digital detector deployment frequently encounters interoperability friction with entrenched picture archiving and communication infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical X-Ray Market |
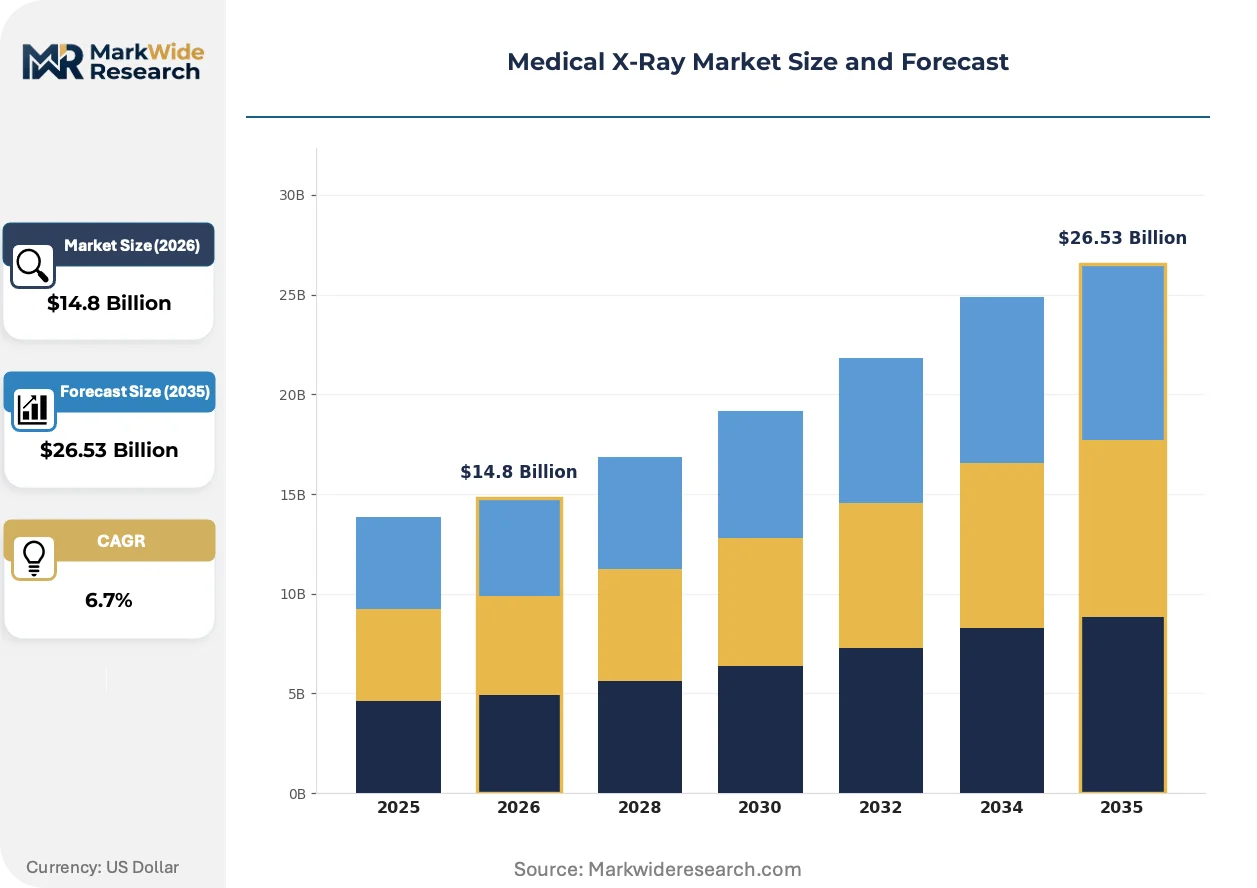
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital X-Ray, Analog X-Ray, Portable X-Ray, Fluoroscopy Application: Orthopedics, Dentistry, Cardiovascular, Oncology End User: Hospitals, Outpatient Clinics, Diagnostic Imaging Centers, Academic Institutions Technology: Flat Panel Detectors, Computed Radiography, Traditional Radiography, Wireless Systems |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, Shimadzu Corporation, FUJIFILM Holdings Corporation, Carestream Health, Hologic, Inc., Varex Imaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical X-Ray Market Emerging Trajectories
Artificial intelligence integration is fundamentally restructuring radiological workflow economics while regulatory frameworks adapt to software-enabled medical devices. Three developments are commanding strategic attention.
Deep learning algorithms trained on annotated imaging datasets are automating preliminary abnormality detection in chest radiography and skeletal studies. Community hospitals and urgent care networks are deploying these tools to address radiologist staffing constraints. The technology is automating routine screening workflows and compressing report turnaround times from hours to minutes.
The FDA's 510(k) modernization initiative is recalibrating submission requirements for AI-enhanced imaging platforms, distinguishing standalone software from embedded diagnostic algorithms. Manufacturers must now navigate predicate device selection complexities when software constitutes the primary technological advancement. United States-based vendors are restructuring regulatory affairs functions to accommodate iterative algorithm updates under modified clearance pathways.
Service contract unbundling is fragmenting traditional equipment procurement economics as hospital systems separate hardware acquisition from maintenance and software subscription components. Third-party service organizations are capturing detector calibration and tube replacement activities previously captive to original equipment manufacturers. This pattern is most pronounced in United States metropolitan markets where independent service organizations have achieved scale.
Medical X-Ray Market Segmentation
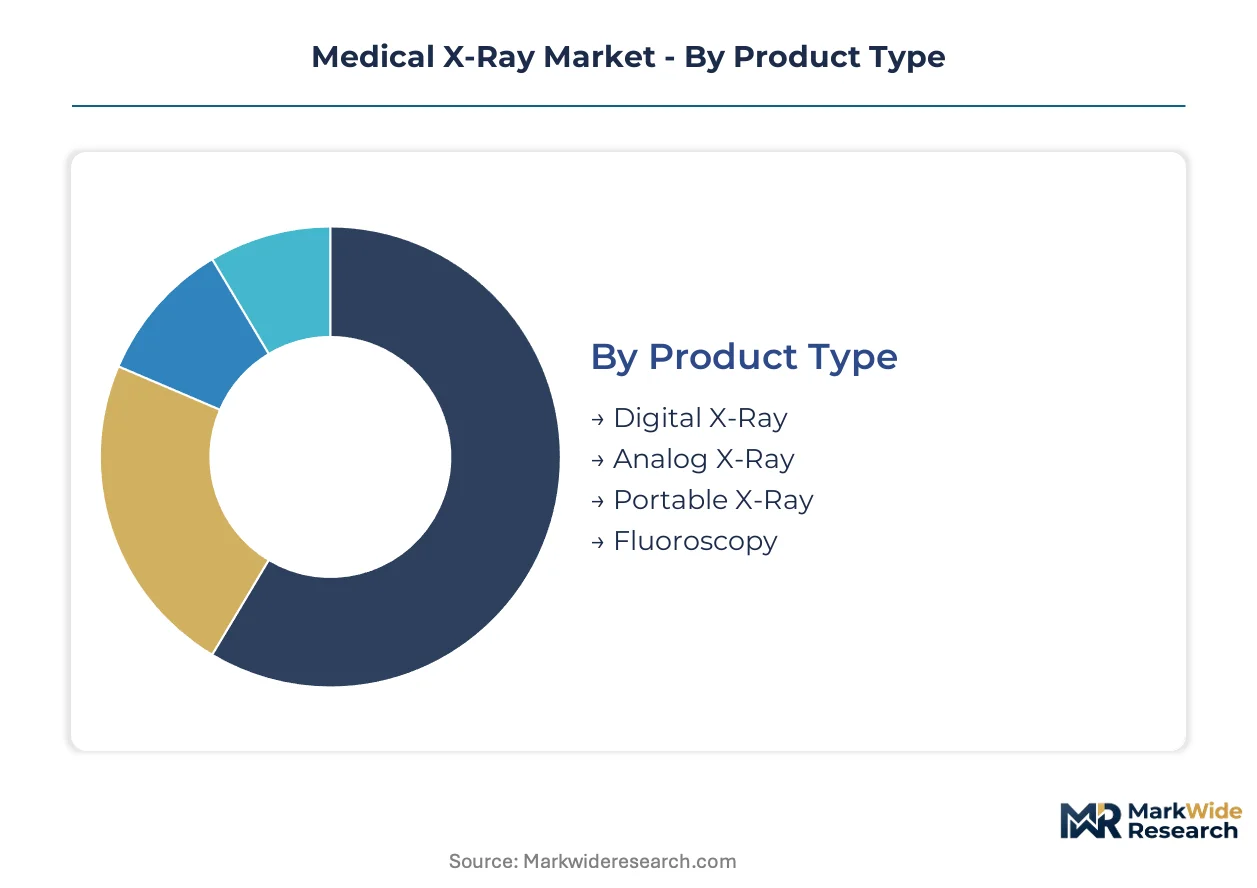
Medical X-Ray segmentation reveals divergent procurement economics across technology generations and care settings. Product type and technology splits expose where capital investment concentrates versus where legacy depreciation accelerates.
Product Type:
Volume deployment clusters in standard digital configurations, while premium procurement targets hybrid interventional suites and mobile platforms.
- Digital X-Ray:Fixed installations with amorphous selenium or cesium iodide flat panel detectors deliver immediate image availability and DICOM integration. Hospital radiology departments in the United States prioritize these systems for throughput gains over computed radiography plate workflows.
- Portable X-Ray:Battery-powered mobile units with wireless detector panels serve intensive care and emergency department bedside imaging. Demand concentrates in tertiary hospitals expanding point-of-care diagnostics without patient transport risks.
- Analog X-Ray:Film-screen systems persist in resource-constrained settings where capital replacement cycles extend beyond standard depreciation schedules.
- Fluoroscopy:Continuous X-Ray with image intensification or flat panel receptors enables real-time interventional guidance in cardiac catheterization and orthopedic surgery.
Mature deployment sits with Analog X-Ray. Newer deployment is concentrated in Portable X-Ray.
Application:
Procedure reimbursement rates and imaging protocol complexity determine equipment specification intensity across clinical specialties.
- Orthopedics:Weight-bearing extremity and spinal imaging requires specialized detector positioning and high-resolution skeletal visualization. Outpatient surgery centers in the United States deploy dedicated digital radiography rooms for fracture and arthroplasty follow-up.
- Cardiovascular:Angiography and interventional fluoroscopy demand pulsed exposure control and rapid frame acquisition. Academic medical centers anchor procurement for hybrid operating room configurations combining surgical and imaging capabilities.
- Dentistry:Intraoral and panoramic X-Ray systems serve private practice networks with compact footprints and lower kVp requirements.
- Oncology:Radiation therapy simulation and treatment verification utilize megavoltage imaging and cone-beam CT integration.
Orthopedics commands the largest installed base. Cardiovascular exhibits the steepest expansion trajectory for interventional platform investment.
End User:
Capital access and patient volume scale create distinct purchasing patterns across provider types.
- Hospitals:Integrated delivery networks aggregate multi-system procurement with bundled service contracts and enterprise PACS integration requirements. These buyers prioritize vendor stability and 24-hour technical response capabilities.
- Diagnostic Imaging Centers:Independent facilities compete on throughput and report turnaround, driving preference for automated exposure control and AI-enhanced workflow tools.
- Outpatient Clinics:Limited space and lower daily exam volumes favor compact digital systems with minimal infrastructure modification.
- Academic Institutions:Research-active medical schools require imaging platforms supporting protocol customization and dose optimization studies.
Hospital procurement dominates capital expenditure. Diagnostic Imaging Centers are gaining share fastest among independent providers.
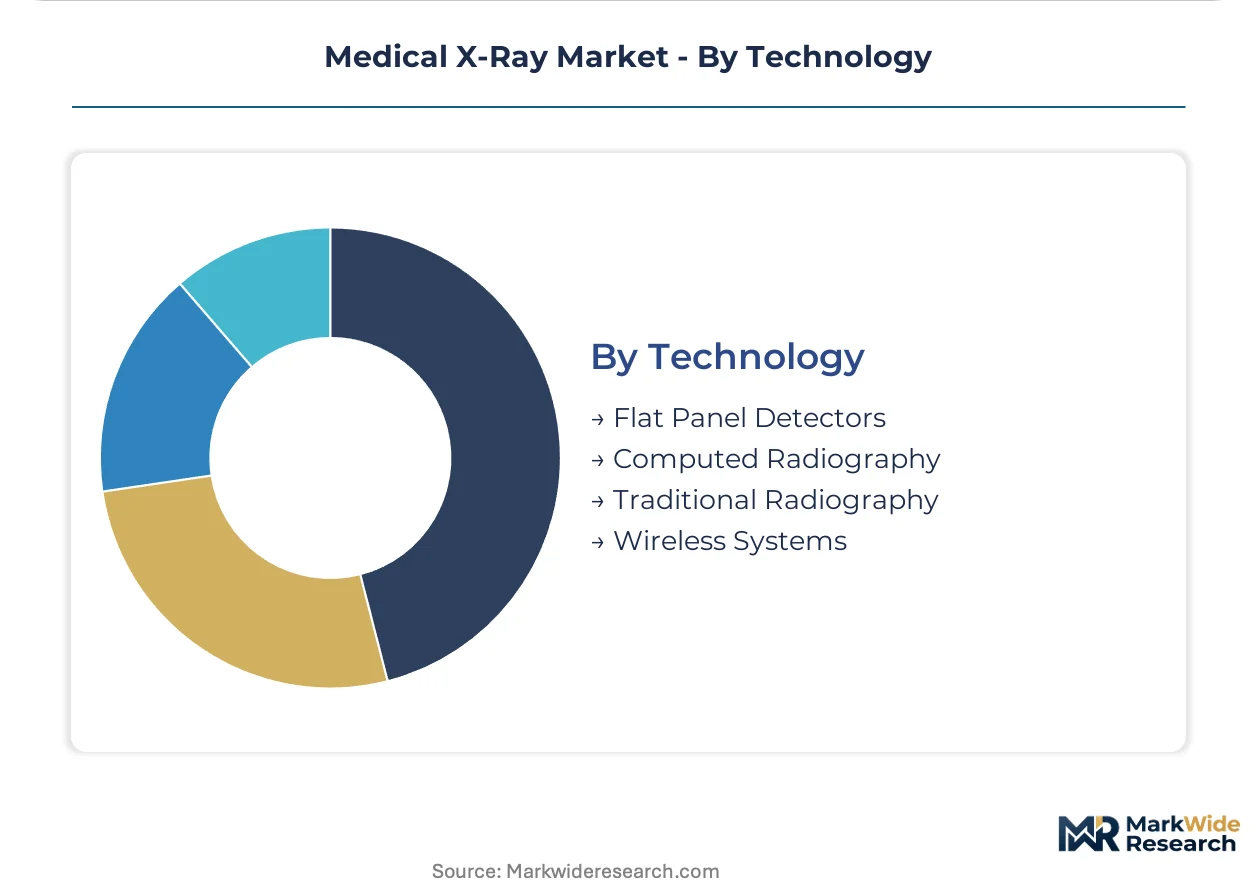
Technology:
Detector architecture determines dose efficiency, image quality, and long-term maintenance economics.
- Flat Panel Detectors:Direct conversion amorphous selenium and indirect cesium iodide architectures capture X-Ray photons with immediate digital readout. High-throughput hospital settings favor these systems for workflow acceleration and dose reduction.
- Wireless Systems:Battery-powered portable detectors with Wi-Fi or cellular transmission eliminate tethering constraints. Emergency departments and operating rooms prioritize these for positioning flexibility.
- Computed Radiography:Photostimulable phosphor plate systems with laser scanning readout face accelerated obsolescence from slower processing and higher consumable costs.
- Traditional Radiography:Film-screen combinations persist only where digital infrastructure investment remains prohibitive.
Traditional Radiography occupies residual replacement demand. Wireless Systems are expanding most quickly into mobile clinical workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentrates in the United States, where integrated delivery networks aggregate capital equipment purchasing across multi-facility footprints. Europe follows with fluoroscopy and interventional platform demand anchored by Germany and France. Asia-Pacific expansion centers on China and Japan as healthcare infrastructure digitalization accelerates.
United States
Integrated delivery networks drive standardization across multi-hospital systems, favoring vendors with comprehensive service capabilities. FDA 510(k) modernization is streamlining clearance pathways for AI-enhanced imaging platforms. Boston and Minneapolis medical device clusters house detector manufacturing and system assembly operations serving North American demand.
Germany
Academic medical centers anchor procurement for hybrid operating room configurations combining surgical and imaging capabilities. EU MDR conformity assessment requirements are extending certification timelines for fluoroscopy equipment. Bavaria's medical technology corridor hosts flat panel detector research and precision manufacturing for European distribution.
China
Tertiary hospitals are expanding digital radiography procurement as domestic detector production scales. NMPA regulatory pathways are adapting to software-enabled medical device classifications. Shanghai and Beijing medical device parks concentrate system integration and AI algorithm development for regional markets.
Japan
Metropolitan hospitals prioritize compact digital systems with minimal infrastructure modification for space-constrained facilities. PMDA maintains stringent radiation safety benchmarks aligned with IEC 60601-1-3 standards. The Kansai region around Osaka hosts specialized fluoroscopy manufacturing for precision interventional platforms.
India
Private hospital chains are retrofitting computed radiography systems with cost-optimized digital configurations. CDSCO import regulations govern clearance timelines for foreign-manufactured X-Ray equipment. Maharashtra's Mumbai-Pune corridor concentrates diagnostic imaging center expansion and third-party service organization growth.
Medical X-Ray Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium system integration consolidating around full-stack vendors while component supply fragments across detector material specialists. The vendor base organizes into three archetypes: vertically integrated imaging conglomerates, focused detector technology suppliers, and regional assembly specialists. Consolidation pressures are intensifying as integrated delivery networks demand single-source accountability for hardware, software, and service. Dominant competitive moves include strategic partnerships for AI algorithm integration and geographic expansion through localized manufacturing partnerships.
Among Germany-based diversified health technology conglomerates, Siemens Healthineers AG occupies a position exemplifying vertical integration from detector materials through system assembly. GE Healthcare represents the North American hospital procurement anchor through long-term service contract structures. Canon Medical Systems, a Japanese precision equipment specialist, sits within the fluoroscopy hybrid suite segment combining diagnostic and interventional workflows.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Shimadzu Corporation |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| Hologic, Inc. |
| Varex Imaging Corporation |
| Others |
Supply Flow & Price Mechanics
Tungsten price benchmarks cascading through anode tube manufacturing compress margins for mid-tier system assemblers while concentrating pricing power among detector material specialists. This input cost volatility stratifies procurement tiers across hospital radiology departments and independent imaging centers.
Pricing Analysis
Volume deployment concentrates in standard digital configurations where per-unit transactional pricing dominates, while premium interventional suites command project-based contracting with embedded service subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled platforms with FDA 510(k) clearance from basic digital radiography and refurbished analog systems. Price differentiation hinges on detector resolution specifications and bundled maintenance terms. Cost compression in economy tiers is intensifying because domestic manufacturers in China and India are scaling flat panel detector production. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize performance specifications over capital expenditure constraints.
Supply Chain Analysis
Single-source vulnerability sits with cesium iodide crystal growth capabilities concentrated in Japan and Germany for high-purity scintillator layers. Detector manufacturing draws from rare earth processing in China for gadolinium-based phosphors, tungsten powder from Vietnam and Russia for anode tube filaments, and amorphous selenium deposition equipment from South Korea. Tariff exposure on precision electronics components threatens margin stability for portable system assemblers. Distribution runs through original equipment manufacturer direct sales forces for hospital IDN procurement, with third-party service organizations capturing aftermarket detector calibration and tube replacement in metropolitan United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat panel detector fabrication capacity constraints prop pricing power for incumbent material specialists, creating supply-constrained conditions that favor backward-integrated conglomerates over pure-play assemblers.
For Market Incumbents: Deepen captive cesium iodide crystal growth capabilities to defend against emerging Chinese detector material suppliers. Secure long-term service contract renewals with United States integrated delivery networks before third-party independent service organizations achieve biomedical engineering training scale. Prioritize FDA 510(k) pathway investment for AI-enhanced algorithm iterations to maintain software subscription revenue streams against software-only diagnostic entrants. For New Entrants and Emerging Players: Capture rural hospital digitalization demand in the United States Southeast and Midwest where computed radiography obsolescence accelerates replacement cycles. Target cost-optimized wireless detector configurations for emergency department point-of-care expansion. Pursue white-label manufacturing partnerships with established tube assembly specialists to bypass capital-intensive detector material fabrication. For Investors and Strategic Acquirers: Distressed-cycle entries favor detector calibration service specialists in United States metropolitan markets where independent service organization consolidation is fragmenting traditional OEM maintenance economics. Long-term viability over the projection horizon rests on software-enabled diagnostic platforms with recurring revenue architectures. Watch FDA 510(k) clearance velocity for AI-enhanced imaging as inflection indicator for algorithm differentiation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines for AI-enhanced platforms reshape competitive positioning in United States hospital procurement. |
| Hospital System Partnership | Integrated delivery network consolidation favors vendors with enterprise PACS integration and 24-hour technical response capabilities. |
| Backward Integration | In-house cesium iodide scintillator production captures margin pools from detector materials through system assembly. |
| Software Companion Development | Machine learning algorithms for chest radiography and mammography create new reimbursement categories and recurring revenue streams. |
| Reimbursement Strategy | Computer-aided detection coding alignment with CMS Medicare coverage determines algorithm adoption velocity in community hospital settings. |
Methodological Framework
SEC 10-K filings, FDA 510(k) clearance databases, and hospital procurement contract records formed the secondary backbone, cross-referenced with primary interviews across biomedical engineering directors, GPO contracts managers, and radiology department heads. Bottom-up and top-down triangulation validated installed base estimates and replacement cycle assumptions. Primary fieldwork captured detector calibration expertise constraints and legacy PACS integration friction from hospital IT administrators and third-party service organization operators.
Bottom-up modeling segmented volume and value across product type, detector technology, application specialty, and end-user facility scale, while top-down cross-checks anchored aggregate figures to healthcare capital expenditure surveys and medical device trade data. CAGRs were derived from replacement cycle compression analysis and AI-enhanced platform penetration assumptions across the analysis window. Forecast inputs incorporated EU MDR conformity assessment timeline extensions and NMPA software-enabled device classification adaptations.
The model holds under stable tungsten supply conditions and continued IDN consolidation; deviation in rare earth export restrictions or FDA algorithm reclassification would shift trajectory bounds. Forecasts reflect documented assumptions on detector manufacturing scale and regulatory pathway efficiency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Spain Digital X-Ray Market