
 Diagnostic X-Ray System Market | 2026-2036
Diagnostic X-Ray System Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic X-Ray System Market Outlook
Radiographer workforce shortages across developed health systems is unwinding capacity planning assumptions for imaging departments. Siemens Healthineers AG leverages its installed base of digital radiography rooms to sustain recurring service revenue streams. GE Healthcare anchors its competitive stance through proprietary detector manufacturing and AI-embedded reconstruction algorithms. Philips differentiates via integrated workflow solutions that connect acquisition to PACS archiving.
A diagnostic x-ray system generates projection radiographs by directing bremsstrahlung radiation through anatomical structures onto solid-state or phosphor-based detectors, with tube voltages typically ranging from 40 to 150 kVp depending on tissue penetration requirements. Digital X-Ray systems now dominate replacement cycles as facilities retire analog and computed radiography cassettes, while Direct Radiography detectors command premium positioning due to faster throughput and lower dose profiles. Portable X-Ray units are gaining share in intensive care and emergency settings where patient transport risks outweigh mobility trade-offs.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are extending product development timelines and elevating clinical evidence standards for new system introductions. The EPA's radiation emission guidelines and OSHA occupational exposure limits further constrain system design parameters and shielding specifications. Stakeholders must weigh detector technology migration paths against reimbursement stability in key procedural categories.
Market Dynamics
The migration from computed radiography to direct radiography detector technology is compressing replacement cycles and redistributing capital allocation across hospital procurement departments worldwide.
Growth Catalysts
- Orthopedic procedural volume expansion:Aging populations in Germany and Japan are driving knee and hip replacement surgeries, requiring dedicated digital radiography suites for pre-operative planning and post-operative monitoring.
- EU MDR recertification timelines:The Medical Device Regulation's phased implementation deadlines are accelerating replacement purchases as facilities retire legacy systems that cannot meet updated clinical evidence requirements.
- India's diagnostic center chain consolidation:Private equity-backed networks like Metropolis and Dr. Lal PathLabs are standardizing on DR platforms across their expanding footprints to capture outpatient imaging demand.
Market Restraints
- Flat-panel detector supply concentration:Manufacturing of amorphous silicon and CMOS-based detectors concentrates among Korean and Japanese component suppliers, creating vulnerability to semiconductor fab capacity constraints.
- Radiographer workforce shortages:The UK, Australia, and Canada report vacancy rates exceeding 15% in diagnostic imaging departments, limiting throughput expansion even where equipment is available.
- Reimbursement compression in Medicare:The US Centers for Medicare & Medicaid Services has reduced technical component payments for routine chest and extremity radiographs, extending payback periods for capital equipment.
Strategic Opportunities
- Mobile DR penetration in ICU settings:Portable systems with wireless detector panels are capturing share in intensive care units where patient transport risks and bed turnover pressures favor bedside imaging.
- AI-embedded reconstruction algorithms:Deep learning-based noise reduction and bone suppression technologies are creating differentiation opportunities for OEMs that integrate FDA-cleared software with hardware platforms.
- Vietnam and Indonesia hospital buildouts:Government infrastructure programs in Southeast Asian markets are greenfield opportunities bypassing the CR-to-DR transition entirely.
Industry Challenges
- FDA 510(k) clinical evidence requirements:Substantial equivalence demonstrations for iterative reconstruction algorithms now require larger patient cohort studies, extending clearance timelines by 8-14 months.
- PACS integration complexity:Healthcare IT departments face escalating costs connecting new DR systems to legacy vendor-neutral archives with disparate DICOM conformance levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic X-Ray System Market |
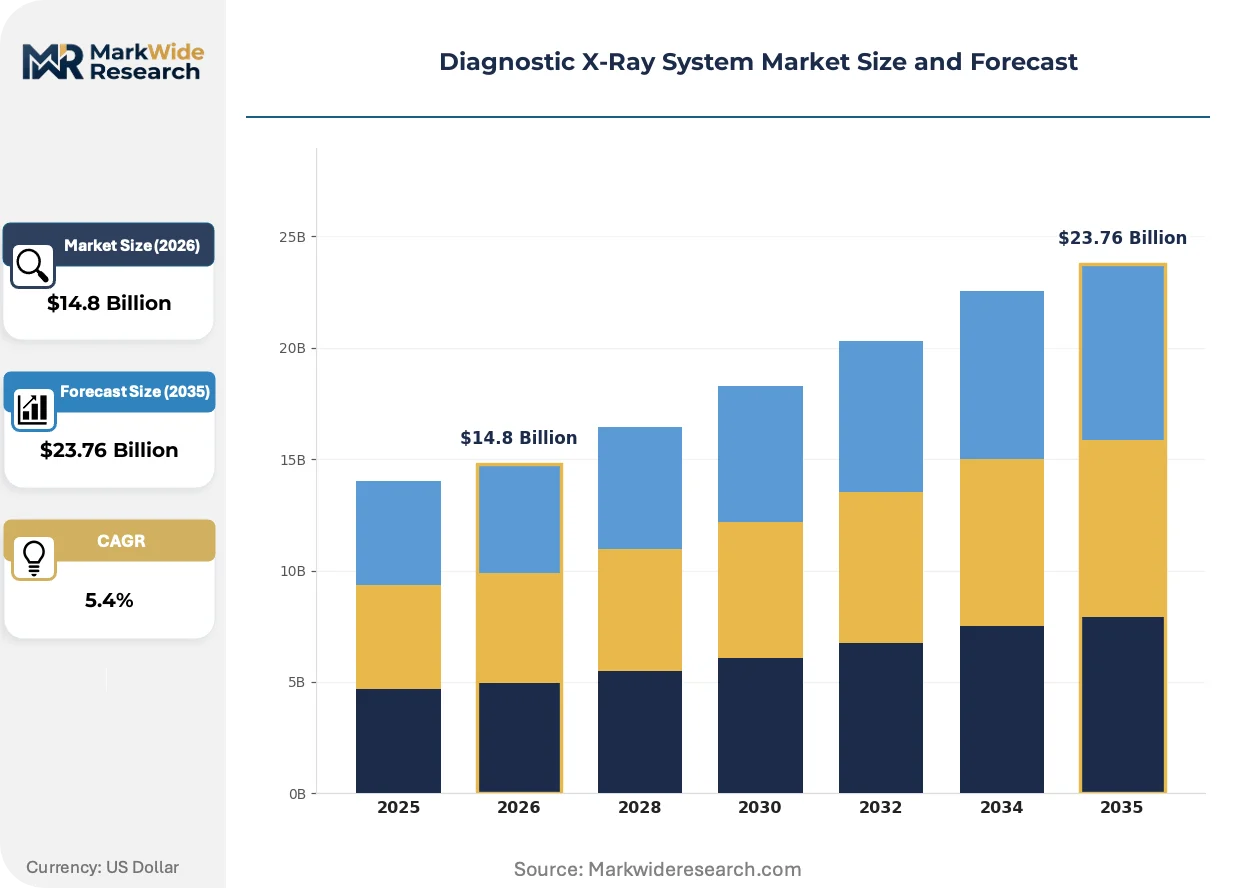
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital X-Ray, Analog X-Ray, Portable X-Ray, Fixed X-Ray End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Laboratories Technology: Cassette-Based, Computed Radiography, Direct Radiography, Fluoroscopy Application: Orthopedics, Cardiovascular, Oncology, Gynecology |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, Shimadzu Corporation, Fujifilm Holdings Corporation, Carestream Health, Hitachi, Ltd., Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic X-Ray System Market Strategic Shifts
Detector technology maturation and regulatory evidence standards are converging to reshape how imaging departments evaluate total cost of ownership across 10-15 year equipment lifecycles.
Direct radiography detectors with cesium iodide scintillator layers are supplanting gadolinium oxysulfide phosphor panels in premium system configurations. Tertiary care hospitals in the US and Western Europe are prioritizing these conversions during their current replacement waves. The shift is compressing price premiums for high-quantum-efficiency detectors as manufacturing scales and yield rates improve across Korean and Taiwanese fabs.
EU MDR technical documentation obligations are extending product development timelines and elevating clinical evidence standards for new system introductions. Manufacturers must now compile post-market surveillance data and risk management files that exceed the previous Medical Device Directive requirements. Small and mid-cap OEMs without dedicated regulatory affairs teams are outsourcing compliance to specialized consultants, adding 12-18% to launch costs.
Service contract unbundling is disrupting the traditional bundled financing model that dominated radiography capital sales for two decades. Hospital procurement departments in the UK and Netherlands are separating equipment acquisition from multi-year maintenance agreements, pressuring OEM service margins. Independent service organizations with ISO 13485 certification are capturing 15-25% of aftermarket service revenue in mature European markets where detector replacement rather than full system swap is the preferred refresh strategy.
Diagnostic X-Ray System Market Segmentation
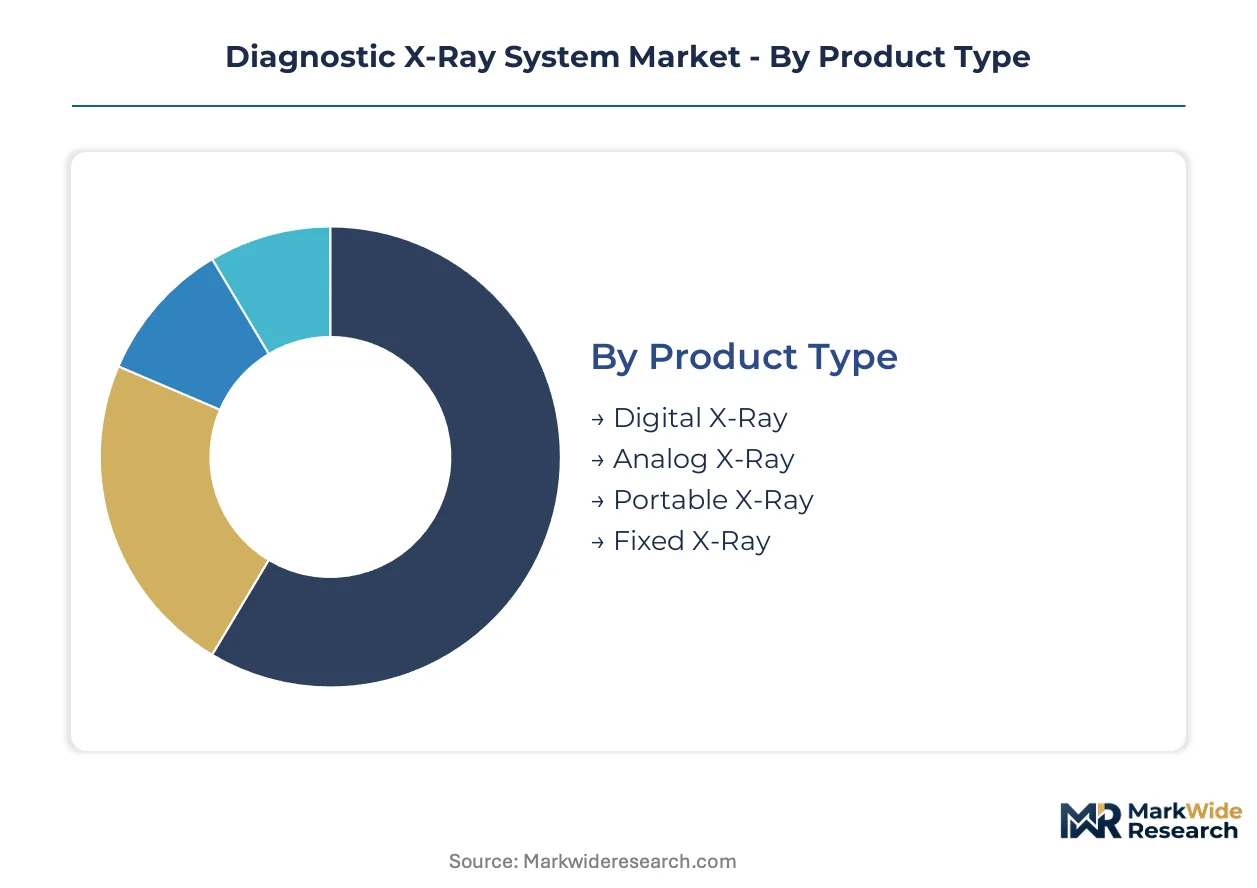
Equipment replacement cycles and technology migration paths differ sharply across product configurations, creating distinct competitive arenas for manufacturers. Procurement priorities vary by care setting, with hospital networks favoring integrated workflows while independent diagnostic centers prioritize throughput economics.
Product Type:
Domestic hospital procurement concentrates on fixed installations, while portable systems drive export demand from Southeast Asian markets building first-time imaging capacity.
- Digital X-Ray:Solid-state detector arrays with cesium iodide scintillator layers capture projection images at sub-second intervals. Demand clusters in Germany's hospital modernization programs and India's diagnostic chain standardization efforts, where DR platforms replace legacy computed radiography rooms during planned capital cycles.
- Portable X-Ray:Battery-powered mobile units with wireless flat-panel detectors enable bedside imaging in intensive care settings. Adoption accelerates in Vietnam and Indonesia where new hospital construction favors flexible equipment deployment over fixed-room installations.
- Analog X-Ray:Film-screen cassette systems persist in cost-constrained rural clinics and secondary care facilities.
- Fixed X-Ray:Ceiling-suspended tube stands with integrated bucky tables dominate orthopedic and trauma suites.
Digital X-Ray commands the established base. The steepest expansion runs through Portable X-Ray.
End User:
Procurement authority concentrates in consolidated hospital networks, while diagnostic centers optimize for outpatient throughput volume.
- Hospitals:Integrated imaging departments with dedicated radiography suites, fluoroscopy rooms, and emergency trauma bays. Replacement demand concentrates in tertiary centers across Japan and the UK where aging infrastructure meets EU MDR recertification deadlines.
- Diagnostic Centers:High-throughput outpatient facilities with standardized DR platforms and automated workflow software. India's Metropolis and Dr. Lal PathLabs networks drive volume procurement as private equity consolidation accelerates.
- Outpatient Clinics:Limited-service settings with compact digital systems for extremity and chest imaging.
- Research Laboratories:Specialized small-animal and specimen radiography systems with micron-level resolution.
Hospitals anchor the installed base. Diagnostic centers are climbing the fastest as outpatient imaging migrates from acute care settings.
Technology:
Manufacturing yield improvements at Korean and Taiwanese fabs are compressing price premiums for direct radiography detectors versus legacy computed radiography.
- Direct Radiography:Amorphous silicon or CMOS photodiode arrays with direct signal conversion eliminate intermediate processing steps. Tertiary hospitals in the US and Western Europe prioritize these systems for dose reduction and throughput gains during current replacement waves.
- Computed Radiography:Photostimulable phosphor plates requiring laser scanning and erasure cycles. Demand persists in budget-constrained facilities transitioning from analog film, particularly in secondary care networks across Eastern Europe and Latin America.
- Cassette-Based:Film-screen combinations with silver halide emulsion layers for chemical processing.
- Fluoroscopy:Continuous X-ray beam systems with image intensifier or flat-panel detectors for real-time guidance.
Computed Radiography retains residual volume in replacement-delayed facilities. Direct Radiography represents the fastest-growing trajectory as detector costs decline and dose optimization mandates tighten.
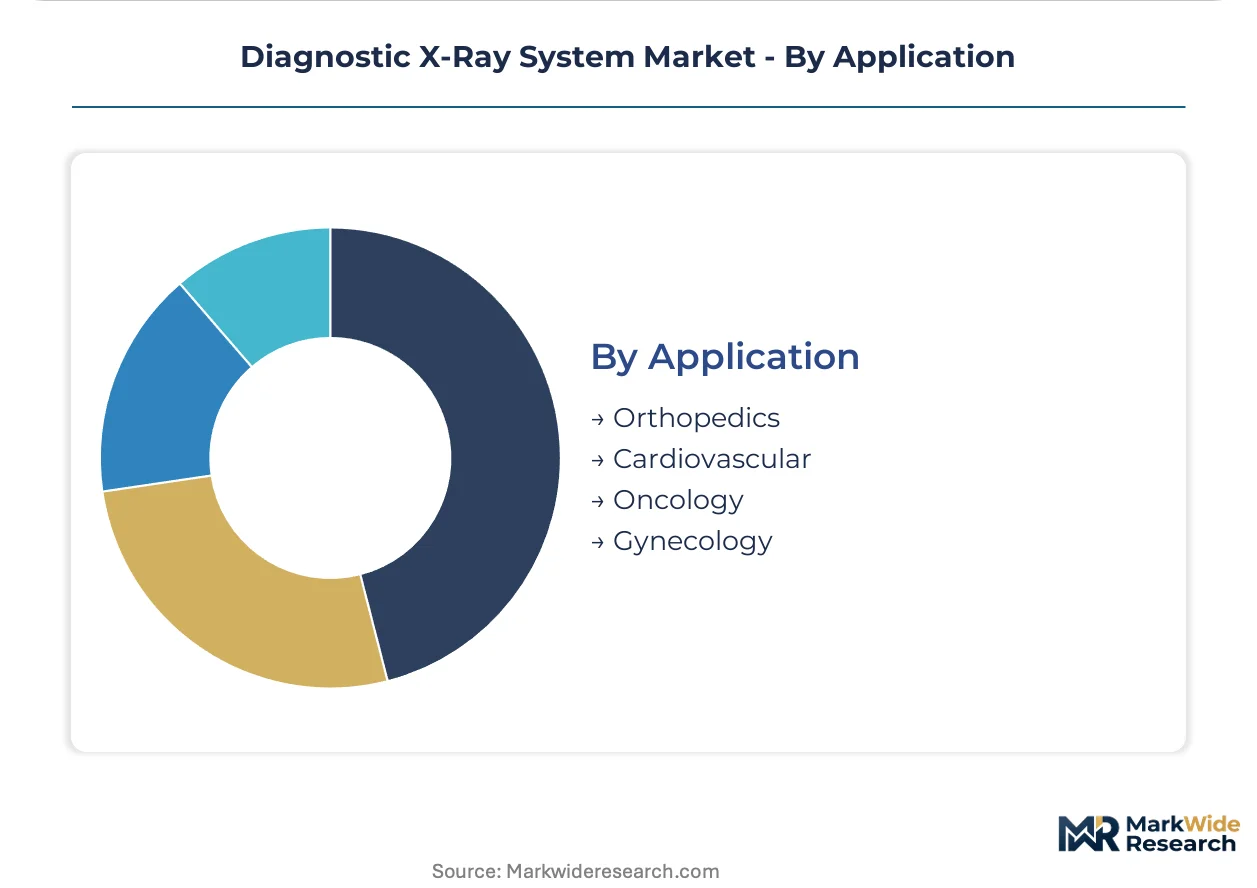
Application:
Procedure reimbursement stability varies by specialty, with orthopedic imaging maintaining stronger technical component payments than cardiovascular screening.
- Orthopedics:Weight-bearing extremity, spine, and pelvis radiography for pre-operative planning and post-operative hardware assessment. Germany and Japan's aging populations drive knee and hip replacement volumes, requiring dedicated digital suites for implant sizing and alignment verification.
- Cardiovascular:Chest radiography for device placement confirmation and congestive heart failure monitoring. Demand concentrates in integrated cardiovascular service lines where X-ray complements catheterization laboratory workflows.
- Oncology:Staging studies and treatment response monitoring with repeated exposure protocols prioritizing low-dose detector technology.
- Gynecology:Hysterosalpingography and pelvic imaging for fertility assessment and IUD placement verification.
Orthopedics holds the dominant procedure volume. Oncology is gaining share fastest as adaptive therapy protocols multiply imaging frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the primary geography shaping product launch cadences, while EU MDR recertification timelines and India's diagnostic center expansion create parallel demand corridors across distinct regulatory environments.
United States
Medicare reimbursement compression for routine chest and extremity radiographs is extending equipment payback periods, yet hospital networks continue DR replacement cycles to maintain throughput. FDA 510(k) substantial equivalence requirements for iterative reconstruction algorithms now demand larger patient cohort studies, delaying clearances by 8-14 months. The Cleveland Clinic and Mayo Clinic anchor tertiary care procurement concentrated in the Midwest and Northeast corridors.
Germany
Hospital network modernization programs are driving dedicated digital radiography suite installations for orthopedic pre-operative planning and post-operative monitoring. EU MDR technical documentation obligations with phased implementation deadlines are accelerating replacement purchases as facilities retire legacy systems. Bavaria's university hospital clusters and North Rhine-Westphalia's integrated care networks concentrate procurement authority.
India
Private equity-backed diagnostic center chains including Metropolis and Dr. Lal PathLabs are standardizing on DR platforms across expanding footprints to capture outpatient imaging demand. CDSCO medical device registration requirements are streamlining for Class B and C devices, reducing import clearance friction. Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore hub concentrate new facility construction.
Japan
Aging demographics are multiplying knee and hip replacement volumes, requiring dedicated imaging capacity for implant sizing and alignment verification. PMDA pre-market approval timelines for software-embedded systems are converging with FDA standards, harmonizing development pathways. Tokyo's tertiary hospital density and Osaka's manufacturing base anchor demand and supply concentration.
Vietnam
Government hospital infrastructure buildouts are creating greenfield opportunities that bypass the CR-to-DR transition entirely, favoring wireless portable systems for flexible deployment. The Ministry of Health's equipment standardization directives are elevating digital platform requirements for new facility accreditation. Ho Chi Minh City's private hospital construction and Hanoi's public hospital renovation programs concentrate procurement activity.
Diagnostic X-Ray System Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum commanding detector manufacturing and AI-embedded reconstruction capabilities while mid-cap players compete on regional service density and price-accessible configurations. The market structure rewards backward integration into flat-panel detector supply and forward integration into PACS workflow connectivity. Three archetypes dominate: full-stack OEMs with captive detector fabs, software-anchored integrators licensing hardware platforms, and regional assemblers sourcing standardized detector panels. Consolidation pressure is concentrating share through strategic partnerships for AI algorithm development and geographic expansion into Southeast Asian greenfield markets.
Among Germany-based integrated health technology conglomerates, Siemens Healthineers AG exemplifies the full-stack archetype with installed base leverage for recurring service revenue. GE Healthcare anchors the North American premium tier through proprietary manufacturing positions. Koninklijke Philips N.V. occupies a workflow-integrated position emphasizing acquisition-to-archive connectivity. Canon Medical Systems and Shimadzu Corporation represent Japanese diversified precision equipment manufacturers with imaging heritage. Fujifilm Holdings Corporation and Carestream Health exemplify transition-era specialists migrating from film and computed radiography toward direct radiography platforms.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Shimadzu Corporation |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Hitachi, Ltd. |
| Hologic, Inc. |
| Others |
Value Chain & Pricing Dynamics
Amorphous silicon fab utilization rates above 85% in Korean and Taiwanese manufacturing facilities compress detector cost curves while simultaneously concentrating bargaining power among a handful of component suppliers. This scale dynamic establishes asymmetric pricing power where OEMs with captive detector production command margin buffers unavailable to assembly-dependent competitors, particularly as hospital procurement departments unbundle service contracts from hardware acquisitions.
Pricing Analysis
Price spreads between German hospital network tenders and Indian diagnostic chain bulk purchases exceed 40% for equivalent DR platform specifications, reflecting divergent after-sales bundling norms and regulatory certification cost absorption. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-embedded systems from CE-marked configurations and basic CR-to-DR transition units. Cost compression in the standard tier intensifies because independent service organizations with ISO 13485 certification capture aftermarket revenue previously monopolized by OEMs. Diagnostic center chains in India exhibit highest price sensitivity due to private equity margin targets, while Japanese tertiary hospitals prioritize dose optimization over acquisition cost.
Supply Chain Analysis
Amorphous silicon thin-film transistor backplane manufacturing concentrates in South Korea, Taiwan, and Japan, creating single-source vulnerability for DR detector arrays that feed assembly lines in Germany, the United States, and China. Cesium iodide scintillator crystals and CMOS photodiode wafers constitute critical input dependencies alongside rare earth phosphor materials for legacy CR plate production. Tariff exposure on semiconductor components imported into the United States threatens margin stability for non-integrated OEMs lacking Korean or Taiwanese captive supply. Distribution runs through hospital GPO contracts in North America, direct tender processes in Germany, and distributor networks across Southeast Asian greenfield markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling is accelerating faster than hardware replacement cycles, transforming capital equipment vendors into recurring revenue platforms where detector refresh subscriptions and AI software companion fees expand lifetime customer value beyond initial system sales.
For Market Incumbents: Fortify installed base retention by embedding FDA-cleared iterative reconstruction algorithms as standard features rather than premium upgrades, neutralizing software-anchored integrators licensing third-party detector platforms. Deepen backward integration into CMOS photodiode wafer supply through strategic foundry partnerships in Taiwan, insulating margin structures from semiconductor fab capacity constraints. Prioritize PACS workflow connectivity investments that raise switching costs for hospital IT departments evaluating competitive DR replacements. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia government hospital buildouts where greenfield procurement bypasses legacy CR infrastructure entirely, favoring wireless portable systems without entrenched incumbent relationships. Target diagnostic center chains in India with detector-as-a-service financing models that align private equity-backed operators' capital efficiency preferences against traditional capital purchase structures. Pursue CDSCO registration pathways for Class B and C devices to reduce import clearance friction relative to FDA 510(k) timelines. For Investors and Strategic Acquirers: Regional assemblers with ISO 13485-certified service networks and established distributor relationships in Southeast Asia represent the most defensible acquisition archetype as OEM consolidation pressure intensifies. Long-term viability hinges on differentiation migration from hardware specifications to AI-embedded software companions and workflow integration depth. Monitor EU MDR recertification deadline compliance rates among mid-cap European OEMs as an inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Embedded Reconstruction Algorithm Development | FDA 510(k) clearance for deep learning noise reduction creates differentiation against commodity DR platforms. |
| Detector Manufacturing Partnership | Korean and Taiwanese fab alliances secure amorphous silicon backplane supply against semiconductor capacity constraints. |
| Hospital System Workflow Integration | PACS connectivity investments raise switching costs and capture recurring service revenue from integrated imaging departments. |
| Portable System Wireless Platform Launch | Battery-powered mobile units with flat-panel detectors capture ICU and emergency market share from fixed-room installations. |
| Reimbursement Strategy Alignment | CMS technical component payment navigation extends equipment payback periods for US hospital network customers. |
Study Parameters
The analysis maps digital radiography, portable X-ray, computed radiography transition, and fluoroscopy sub-sectors, each validated through radiology department heads, hospital procurement committee members, biomedical engineering directors, and GPO contracts managers across primary interview programs. Secondary validation draws from FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital capital expenditure records. Bottom-up equipment shipment modeling and top-down healthcare infrastructure spending analysis provide cross-check triangulation.
Consistency checks against external benchmarks confirm volume and value outputs across the projection horizon, with segmentation modeling spanning product configuration, end-user setting, detector technology migration stage, and clinical application intensity. CAGRs derive from replacement cycle compression rates, procedure volume elasticity to aging demographics, and detector cost curve trajectories. Forecast inputs incorporate EU MDR recertification deadline phasing, radiographer workforce vacancy trends, and diagnostic center chain consolidation velocity.
Underlying assumptions cover reimbursement stability in key procedural categories, semiconductor fab capacity expansion continuity, and regulatory clearance timeline normalization, with deviation risk concentrated in Medicare technical component payment compression and Korean detector supplier concentration. Practitioners should keep alternative scenarios live as EU MDR implementation enforcement patterns and India CDSCO registration streamlining evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
UK Imaging Services Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Global Spectral Computed Tomography (CT) Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
South America Nuclear Imaging Market