
 Radiology As a Service Market | 2026-2036
Radiology As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Radiology As a Service Market Intelligence
The gap between premium AI-augmented diagnostic tiers and commodity image-read services is repositioning vendor strategies across the radiology outsourcing landscape. Siemens Healthineers leverages its embedded imaging hardware base to bundle cloud-native workflow platforms with equipment leases. GE Healthcare anchors its teleradiology offerings through deep integration with hospital electronic health record systems. Philips Healthcare differentiates by specializing in advanced visualization tools for complex subspecialty reads.
Radiology As a Service denotes the delivery of diagnostic imaging interpretation, workflow orchestration, and quality assurance through remotely hosted platforms rather than on-site radiologist departments. These systems typically operate on DICOM-compliant data pipelines with sub-300-millisecond latency thresholds for real-time image streaming, enabling continuous diagnostic operations across distributed clinical sites. Tele-radiology services currently command the largest revenue share among service types, while AI Integration within the technology dimension attracts the fastest expansion as algorithms gain FDA clearance for triage and detection tasks. Cloud-based Solutions sustain dominant deployment preference, though Hybrid Cloud configurations are gaining traction among diagnostic centers balancing data sovereignty with scalability.
FDA premarket clearance pathways for AI-enabled diagnostic devices directly shape product development timelines and commercialization feasibility for platform vendors. HIPAA security rule compliance and state-level corporate practice of medicine doctrines constrain how teleradiology firms structure physician staffing and data custody across jurisdictions. Stakeholders must monitor evolving reimbursement determinations from CMS and private payers for remote interpretation services, as coverage parity with on-site reads will determine enterprise contract economics.
Market Dynamics
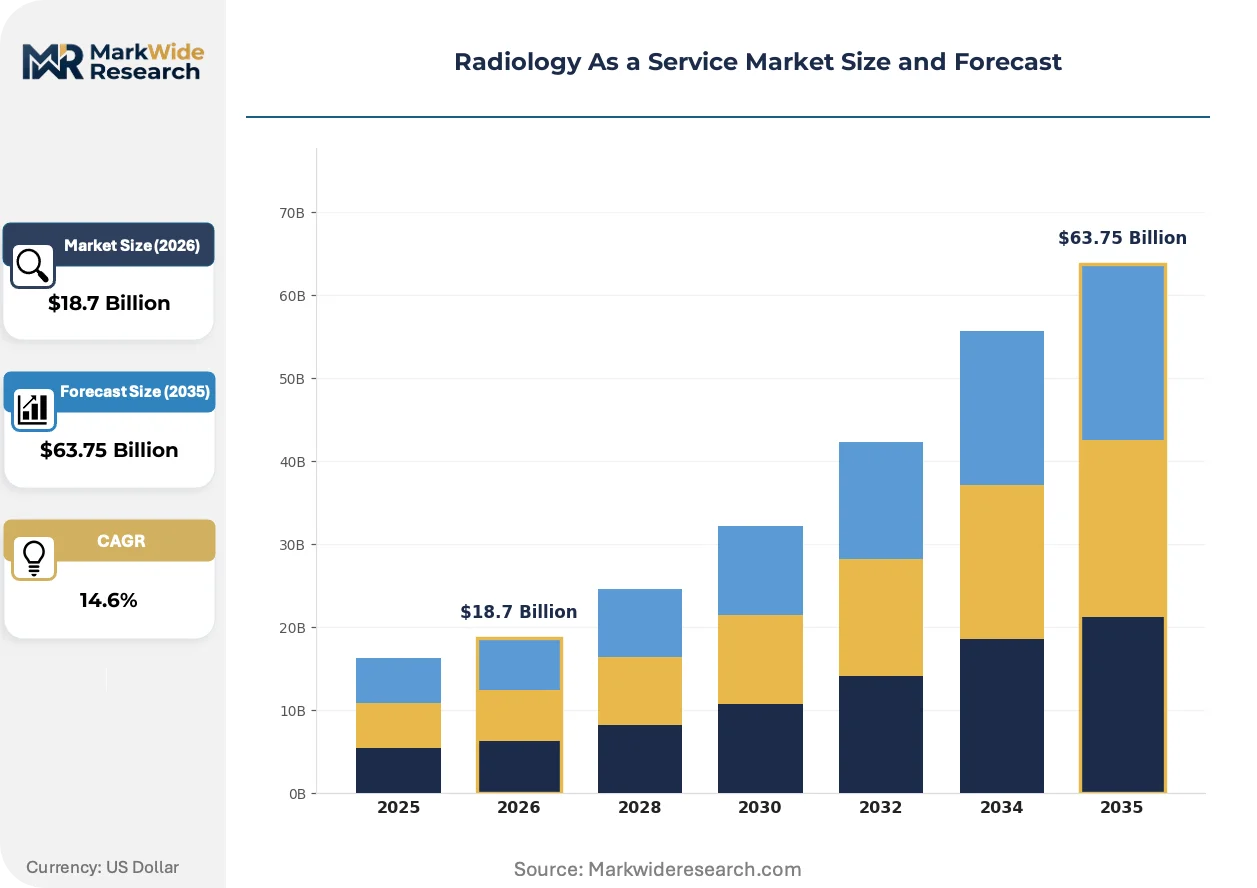
Cloud-native platform consolidation is compressing vendor margins while expanding service reach across distributed hospital networks, fundamentally restructuring how diagnostic interpretation capacity gets procured and delivered.
Growth Catalysts
- HIPAA-aligned data architectures:Enterprise buyers now mandate end-to-end encryption and audit-ready custody chains, accelerating platform upgrades among incumbent providers.
- Subspecialty read demand:Neuroradiology and pediatric cardiology interpretation shortages in the United States are pulling remote diagnostic services into academic medical center workflows.
- AI triage algorithms:FDA-cleared detection tools for intracranial hemorrhage and pulmonary embolism are embedding into teleradiology stacks, creating new service tier differentiation.
Market Restraints
- State-level corporate practice of medicine doctrines:These regulations constrain how teleradiology firms structure physician employment across California, Texas, and New York, fragmenting operational models.
- Hybrid cloud deployment costs:Diagnostic centers balancing data sovereignty requirements with scalability face capital intensity in on-premise infrastructure maintenance.
- Radiologist labor pool concentration:Board-certified specialists cluster in major metropolitan corridors, limiting remote staffing flexibility for rural hospital clients.
Strategic Opportunities
- Underpenetrated outpatient imaging centers:Independent diagnostic facilities in the southeastern United States lack integrated workflow platforms, representing whitespace for cloud-native entrants.
- CMS reimbursement parity expansion:Coverage determinations for remote interpretation services in emergency departments could normalize contract economics previously discounted against on-site reads.
- Edge computing convergence with 5G networks:Sub-100-millisecond latency thresholds enable real-time collaboration between on-site technologists and remote radiologists during interventional procedures.
Industry Challenges
- DICOM-HL7-FHIR integration complexity:Legacy electronic health record systems at mid-size hospital networks require costly middleware development for seamless image-workflow-data synchronization.
- AI algorithm validation timelines:FDA premarket submission pathways for multi-site performance studies extend product development cycles, compressing first-mover windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiology As a Service Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand Imaging, Tele-radiology, Diagnostic Review, Workflow Management Technology: Cloud-based Solutions, AI Integration, Data Analytics, Imaging Software End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Research Institutions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, RadNet, Inc., Virtual Radiologic, DeepHealth, Inc., DeepTek Inc., Enlitic Inc., Coreline Soft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiology As a Service Market Strategic Shifts & Innovations
Workflow orchestration automation and regulatory clarity around AI-enabled diagnostics are converging to redefine service delivery architectures across the radiology outsourcing landscape.
Federated learning architectures for diagnostic AI are expanding into multi-site training environments that preserve data locality while improving algorithm generalization. Academic medical centers in the United States are piloting these frameworks to pool rare pathology cases without centralizing sensitive patient records. This architecture is expanding into competitive differentiation for platform vendors seeking enterprise contracts with research-intensive health systems.
The FDA's evolving guidance on predetermined change control plans for machine learning-enabled devices is compressing post-market modification timelines for algorithm developers. Device manufacturers must now submit locked performance specifications and modification protocols upfront, shifting regulatory strategy from reactive submission to proactive risk management. Teleradiology platforms integrating third-party AI modules face heightened due diligence burdens in vendor qualification.
Subscription-based service contracts with usage-tier pricing are displacing per-study fee structures among integrated delivery networks. Hospital procurement teams favor predictable operational expenditure models that align radiology service costs with seasonal imaging volume fluctuations. This shift is most visible in the United States, where multi-hospital systems centralize vendor management through shared services organizations.
Radiology As a Service Market Segmentation
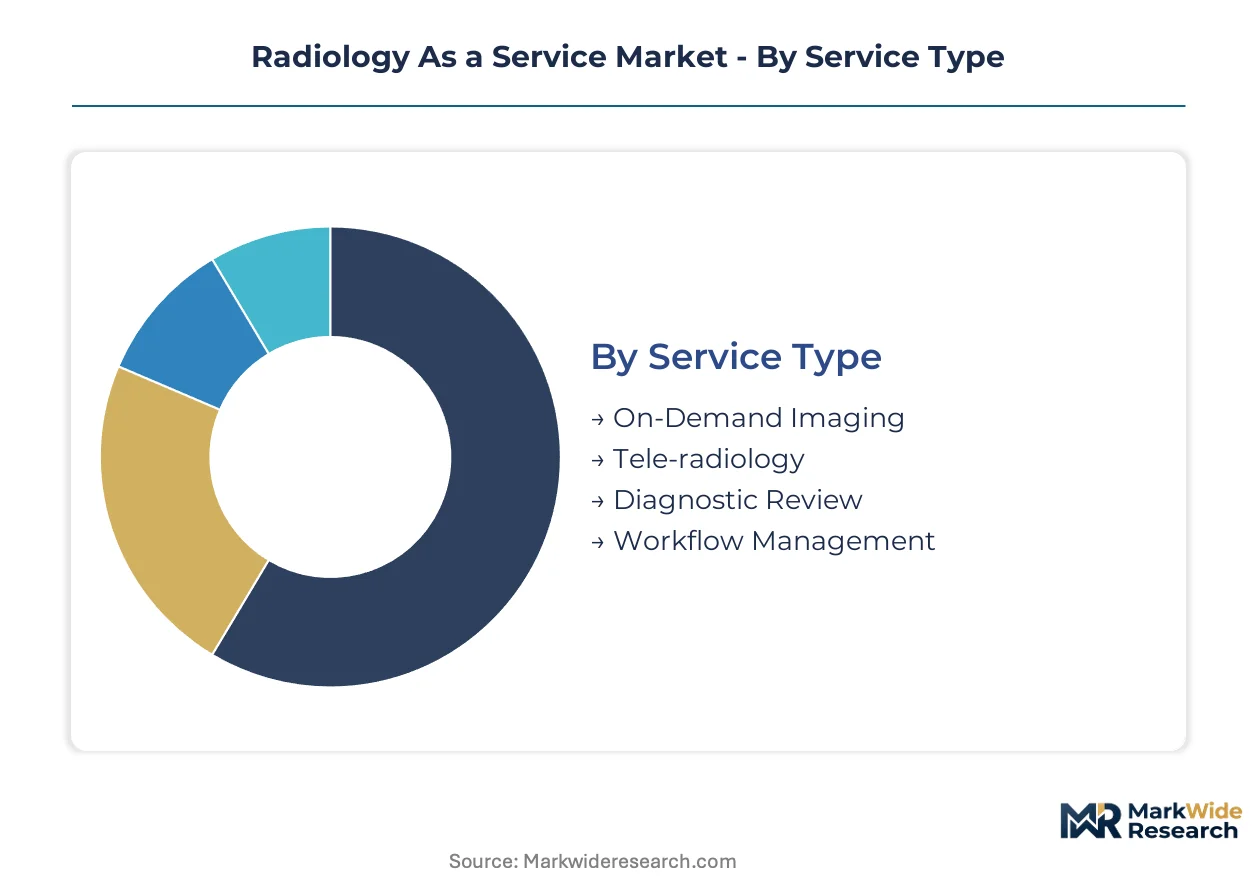
Radiology As a Service procurement decisions hinge on how service tiers align with existing imaging infrastructure refresh cycles and regulatory compliance mandates. Hospital networks evaluate segment combinations based on interoperability with legacy PACS systems and subspecialty coverage requirements.
Service Type:
Replacement of aging on-premise radiology departments with remotely hosted alternatives accelerates as equipment depreciation cycles converge with staffing shortages.
- Tele-radiology:Remote diagnostic interpretation delivered through DICOM-compliant networks with sub-300-millisecond latency thresholds. United States hospital networks in rural corridors deploy these services to address neuroradiologist and pediatric cardiologist shortages, with CMS reimbursement parity expanding contract feasibility.
- On-Demand Imaging:Asynchronous image interpretation triggered by acute care volume spikes without dedicated radiologist staffing. Emergency departments in the southeastern United States leverage this tier for overnight and weekend coverage where local specialist availability collapses.
- Diagnostic Review:Secondary opinion services for complex pathology cases requiring subspecialty confirmation.
- Workflow Management:Orchestration platforms automating study routing, quality assurance, and report distribution.
Tele-radiology sits at the top of the volume ranking, with On-Demand Imaging climbing the fastest.
Technology:
Technology selection follows a cost-tier logic where capital-constrained buyers prioritize proven infrastructure over experimental capabilities.
- Cloud-based Solutions:Fully hosted platforms eliminating on-premise server maintenance and enabling elastic capacity scaling. Integrated delivery networks in the United States favor these deployments for centralized imaging workflows across distributed hospital campuses.
- AI Integration:FDA-cleared algorithms embedded for intracranial hemorrhage triage and pulmonary embolism detection. Academic medical centers pilot these modules to reduce turnaround times for critical findings, though validation timelines extend procurement cycles.
- Data Analytics:Performance dashboards tracking radiologist productivity, report accuracy, and turnaround metrics.
- Imaging Software:Advanced visualization tools for complex subspecialty reads including 3D reconstruction.
Cloud-based Solutions capture the dominant procurement preference, while AI Integration gains share fastest among research-intensive health systems.
End User:
End-user segmentation reflects divergent maturity levels in digital imaging adoption across care delivery settings.
- Hospitals:Multi-facility health systems requiring 24/7 subspecialty coverage and enterprise workflow integration. These buyers mandate HIPAA-aligned data architectures and direct EHR connectivity, driving vendor consolidation toward platform-scale providers.
- Diagnostic Centers:Independent imaging facilities lacking capital for captive radiologist staffing. Outpatient operators in the southeastern United States represent whitespace for cloud-native entrants seeking volume outside consolidated hospital networks.
- Outpatient Clinics:Primary care and specialty practices with episodic imaging interpretation needs.
- Research Institutions:Academic medical centers deploying federated learning architectures for multi-site AI training.
Hospitals anchor current revenue concentration, with Diagnostic Centers expanding most quickly as independent facilities digitize operations.
Deployment:
Deployment architecture selection balances data sovereignty imperatives against scalability requirements in an increasingly regulated environment.
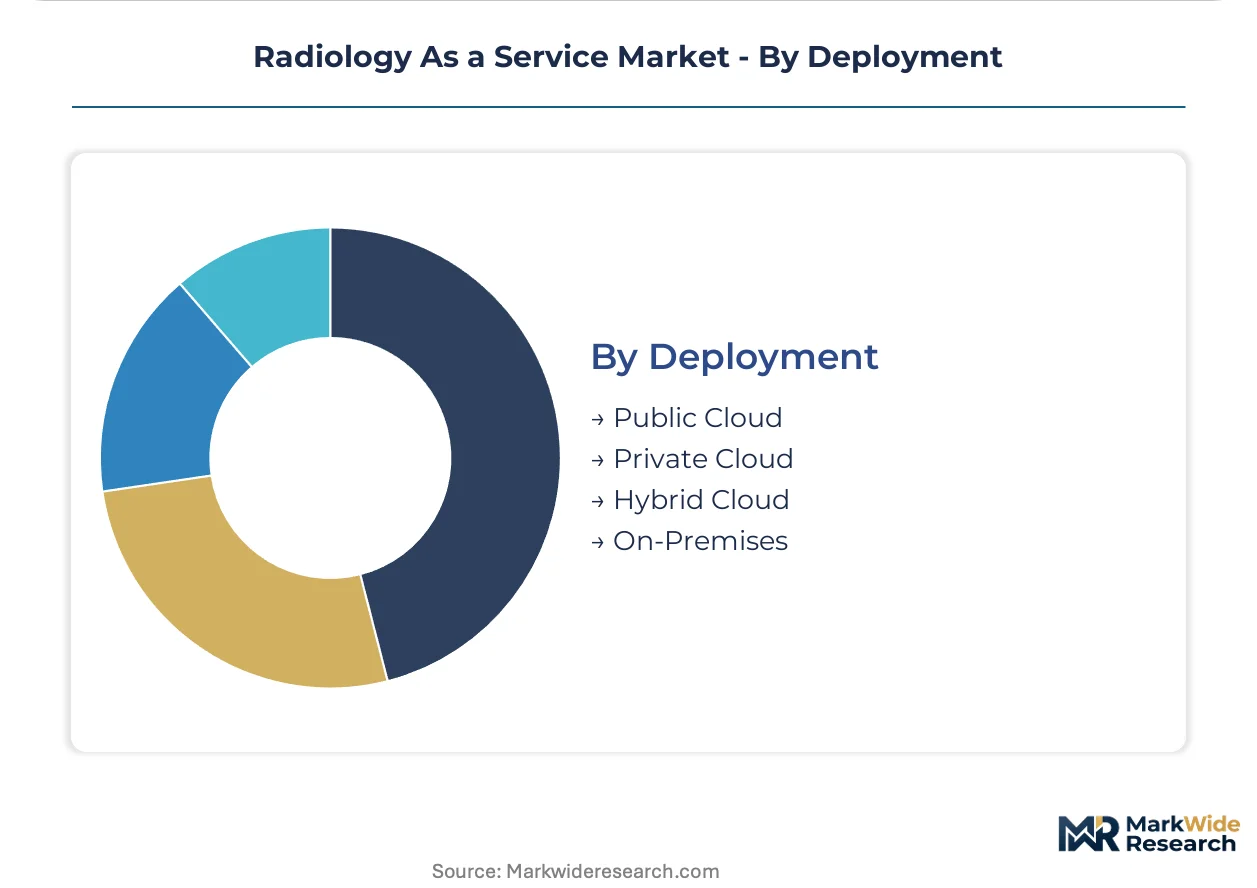
- Hybrid Cloud:Configurations partitioning sensitive patient data on-premise while leveraging public cloud for compute-intensive processing. Diagnostic centers across the United States adopt this model to satisfy state-level data residency requirements without sacrificing elastic capacity.
- Private Cloud:Dedicated infrastructure environments offering single-tenant isolation for high-security workloads. Large hospital networks deploy these for enterprise imaging archives subject to stringent audit and custody chain mandates.
- Public Cloud:Multi-tenant shared infrastructure with consumption-based pricing.
- On-Premises:Legacy self-managed installations persisting where regulatory or technical constraints block cloud migration.
Hybrid Cloud dominates new procurement decisions, with Private Cloud maintaining steepest expansion trajectory among security-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger teleradiology contract volume than Germany, where hospital procurement cycles lag by approximately eighteen months in cloud-native platform adoption. Canada and the United Kingdom accelerate implementation through national digital health frameworks, while Japan and Australia concentrate investment in subspecialty interpretation networks.
United States
Integrated delivery networks in Texas and Florida drive enterprise contract growth for centralized imaging workflows. HIPAA security rule compliance mandates reshape vendor qualification criteria across multi-hospital systems. The Research Triangle in North Carolina anchors pilot programs for federated learning architectures in academic medical centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia prioritize DICOM-compliant workflow orchestration for neuroradiology coverage gaps. The EU AI Act and MDR certification requirements extend procurement timelines for AI-embedded platforms. The Munich medical technology cluster hosts validation studies for predetermined change control plans under emerging FDA-aligned guidance.
United Kingdom
NHS Trusts in London and the Midlands expand teleradiology procurement to address radiologist staffing shortages in emergency departments. NHS Digital interoperability standards mandate FHIR-compliant data exchange for cloud-hosted diagnostic services. The Cambridge-Oxford-London triangle concentrates AI algorithm development partnerships between academic medical centers and platform vendors.
Japan
Metropolitan hospital networks in Tokyo and Osaka deploy remote interpretation services for pediatric cardiology and musculoskeletal subspecialty reads. PMDA regulatory pathways for AI-enabled diagnostic devices shape vendor market entry strategies. The Kansai region's diagnostic imaging equipment manufacturers deepen integration partnerships with cloud-native platform providers.
Australia
Rural health districts in Queensland and Western Australia contract teleradiology services to replace on-site radiologist coverage in regional hospitals. The TGA's evolving guidance on software as a medical device influences procurement specifications for AI-integrated platforms. The Sydney-Melbourne corridor concentrates telehealth infrastructure investment supporting real-time image streaming capabilities.
Radiology As a Service Market Key Industry Players
Top-tier vendors anchor integrated platform offerings, while mid-scale specialists concentrate on subspecialty interpretation niches. The vendor base stratifies across equipment-anchored conglomerates, pure-play teleradiology operators, and AI-native software developers. Imaging hardware manufacturers exemplify the equipment-lease bundling archetype, cloud-native startups represent the workflow-automation archetype, and academic spin-offs occupy the AI-algorithm specialization archetype. M&A activity concentrates on AI module acquisition, while strategic partnerships dominate EHR integration efforts.
Among equipment-anchored conglomerates, Siemens Healthineers, GE Healthcare, and Philips Healthcare exemplify divergent platform strategies. Siemens Healthineers represents the embedded-hardware-to-cloud bundling archetype through its imaging equipment lease structures. GE Healthcare occupies a position emphasizing EHR system integration depth. Philips Healthcare exemplifies the advanced-visualization specialization archetype for complex subspecialty diagnostic workflows. These three conglomerates anchor competitive dynamics through divergent routes to enterprise contract capture.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| RadNet, Inc. |
| Virtual Radiologic |
| DeepHealth, Inc. |
| DeepTek Inc. |
| Enlitic Inc. |
| Coreline Soft |
| Others |
Cost & Logistics Intelligence
Integrated delivery networks in the United States concentrate procurement volume, locking in subscription-based SaaS contracts that displace per-study fee structures and compress vendor margins through centralized vendor management.
Pricing Analysis
Bundled equipment-lease-plus-platform offerings from Siemens Healthineers and GE Healthcare dominate enterprise pricing, while unbundled workflow-only subscriptions serve capital-constrained diagnostic centers. Price differentiation rests on HIPAA certification tier and subspecialty coverage depth. Pricing pressure intensifies as cloud-native startups undercut incumbents on pure workflow automation. Independent imaging facilities in the southeastern United States exhibit highest price sensitivity; academic medical centers with research budgets show lowest.
Supply Chain Analysis
Freight costs for imaging hardware shipments from Germany, the Netherlands, and Japan inflate total cost of ownership for platform vendors bundling equipment leases. The supply chain draws from semiconductor foundries in Taiwan for GPU acceleration modules, DICOM-compliant storage arrays manufactured in Ireland, and radiologist labor pools concentrated in India and Australia. Single-source vulnerability in FDA-cleared AI algorithm licensing creates supply risk. Distribution runs through hospital procurement committees and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: radiologist labor costs in India and Australia run 40-60% below United States metropolitan rates, while HIPAA compliance costs in the United States create regulatory moats against low-cost offshore competitors.
For Market Incumbents: Anchor enterprise relationships through deeper EHR integration than cloud-native challengers can match. Invest in backward integration into AI algorithm development to reduce third-party licensing exposure. Prioritize federated learning partnerships with academic medical centers to lock in research-intensive health systems against pure-play workflow entrants. For New Entrants and Emerging Players: Direct-to-diagnostic-center digital sales channels bypass hospital procurement committee friction. Target independent imaging facilities in the southeastern United States where cloud-native platform penetration lags furthest behind integrated delivery networks. Lead with AI-augmented subspecialty reads for neuroradiology and pediatric cardiology where board-certified specialist shortages create immediate demand pull. For Investors and Strategic Acquirers: Imaging hardware manufacturers are the most active acquirer in this space, seeking workflow software capabilities to complete bundled offering stacks. Long-term viability hinges on regulatory capture through FDA predetermined change control plans that extend algorithm modification timelines for competitors. Target acquisition archetype: AI-native triage algorithm developers with 510(k) clearance in intracranial hemorrhage or pulmonary embolism detection. Watch CMS reimbursement parity determinations for remote interpretation services as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Triage Module | Accelerates commercialization timelines for intracranial hemorrhage detection algorithms in emergency department workflows. |
| Hospital System Partnership | GE Healthcare's EHR integration depth exemplifies how workflow embedding locks out competing platform vendors. |
| Software Companion Development | Philips Healthcare's advanced visualization tools create subspecialty differentiation for complex neuroradiology reads. |
| Reimbursement Strategy | CMS coverage parity expansion for remote interpretation normalizes contract economics against discounted on-site read rates. |
| CE Marking Pathway | EU MDR certification requirements extend procurement timelines for AI-embedded platforms in German university hospitals. |
Research Approach
Bottom-up hospital network modeling reconciled against top-down teleradiology vendor tracking forms the analytical core. Primary interviews with radiology department chairs, hospital procurement officers, GPO contracts managers, and FDA regulatory consultants combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and DICOM standard documentation. Triangulation across stakeholder inputs and documentary sources ensures segment-level consistency.
Input-output matrices map imaging volume projections through service type, technology tier, deployment architecture, and end-user facility scale across the analysis window. CAGRs derive from weighted average of historical contract growth rates and forward-looking procurement pipeline indicators. Specific forecast inputs include radiologist staffing shortage severity by subspecialty and HIPAA compliance upgrade cycles among mid-size hospital networks.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures would alter the outlook if academic medical centers accelerate multi-site AI training without centralizing patient data. Forecasts reflect documented assumptions about CMS reimbursement parity timing and FDA algorithm clearance velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market