
 Global Veterinary Point of Care Market | 2026-2036
Global Veterinary Point of Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Point of Care Market Foresight
Companion animal practice is decoupling from traditional reference-lab dependency as clinics prioritize same-day clinical decisions. IDEXX Laboratories dominates in-clinic chemistry and immunoassay platforms through captive reagent ecosystems. Zoetis leverages its vaccine-diagnostics integration to anchor pull-through revenue in equine and livestock channels. Heska Corporation specializes in veterinary-specific hardware that competes on workflow speed against human-health crossover devices.
Veterinary point of care encompasses portable and benchtop diagnostic systems designed for species-specific sample matrices including whole blood, serum, urine, and fecal specimens, with analytical performance targets calibrated below human clinical thresholds but above field-screening minimums. The primary commercial purpose is to compress diagnostic turnaround from days to minutes, enabling treatment initiation during a single patient visit. Analyzers and test kits capture the dominant margin pool as consumable reagent streams lock in recurring revenue, while imaging equipment occupies a premium niche where portable ultrasound and digital radiography command higher capital outlays. Deployment through mobile units and on-farm field usage represents the fastest-growing structural segment as food-animal veterinarians and emergency response teams extend reach beyond brick-and-mortar infrastructure.
FDA Center for Veterinary Medicine oversees device clearances and quality-system requirements for diagnostic instruments marketed in the United States, while the EU Veterinary Medicines Regulation and IVDR framework reshape conformity assessment for test kits entering European Economic Area markets. Japan's Ministry of Agriculture, Forestry and Fisheries (MAFF) and PMDA coordinate on livestock disease surveillance standards that directly dictate specifications for domestic point-of-care procurement. Stakeholders must monitor how divergent data-localization requirements for cloud-connected analyzers fragment software architecture and service delivery models across jurisdictions.
Market Dynamics
Companion animal clinics are severing same-day diagnostic dependency on centralized reference laboratories as portable chemistry and immunoassay platforms compress turnaround from 24-48 hours to under 15 minutes. This structural decoupling reconfigures procurement budgets toward captive reagent ecosystems and workflow-integrated hardware.
Growth Catalysts
- CLIA-waived test kit pathways:FDA streamlined clearance routes for veterinary-specific immunoassays accelerate commercial entry for multiplex panels targeting canine pancreatitis and feline hyperthyroidism markers.
- Livestock biosecurity mandates:Japan's MAFF surveillance protocols for foot-and-mouth disease and avian influenza compel on-farm rapid testing infrastructure across cattle and poultry operations.
- Pet insurance penetration:Reimbursement frameworks in Germany and the United States now cover in-clinic diagnostic workups, removing price sensitivity barriers that previously funneled cases to lower-cost reference labs.
Market Restraints
- Reagent supply concentration:Proprietary cartridge ecosystems from dominant platform manufacturers lock clinics into single-source consumable streams with limited third-party alternatives.
- Species-specific matrix validation:Hematology and chemistry analyzers require separate calibration curves for avian, reptile, and exotic mammal blood parameters, fragmenting addressable volume per SKU.
- EU IVDR conformity costs:The 2022 In Vitro Diagnostic Regulation imposes clinical evidence requirements on veterinary test kits that previously circulated under self-certified CE marks, extending time-to-market by 18-24 months.
Strategic Opportunities
- Mobile veterinary units:Equine sports medicine and food-animal ambulatory services in Australia and Brazil lack fixed infrastructure, creating pull-through demand for battery-operated hematology and portable ultrasound systems.
- Cloud-connected analyzer architectures:Telemedicine integration enables rural clinics in Canada to transmit digital cytology and radiography to boarded specialists, expanding service scope without specialist hiring.
- One Health surveillance convergence:Zoonotic disease monitoring programs at the WHO-FAO-OIE tripartite level are funding point-of-care platforms capable of simultaneous human and animal pathogen detection at wildlife-livestock interfaces.
Industry Challenges
- Veterinary clinical pathologist scarcity:Diagnostic interpretation expertise concentrates in academic centers and corporate reference labs, leaving independent practitioners dependent on algorithmic support tools with unproven accuracy margins.
- Legacy practice management integration:In-clinic analyzers from Heska and IDEXX utilize proprietary data formats that resist seamless flow into third-party electronic medical record systems, forcing manual transcription or expensive middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Point of Care Market |
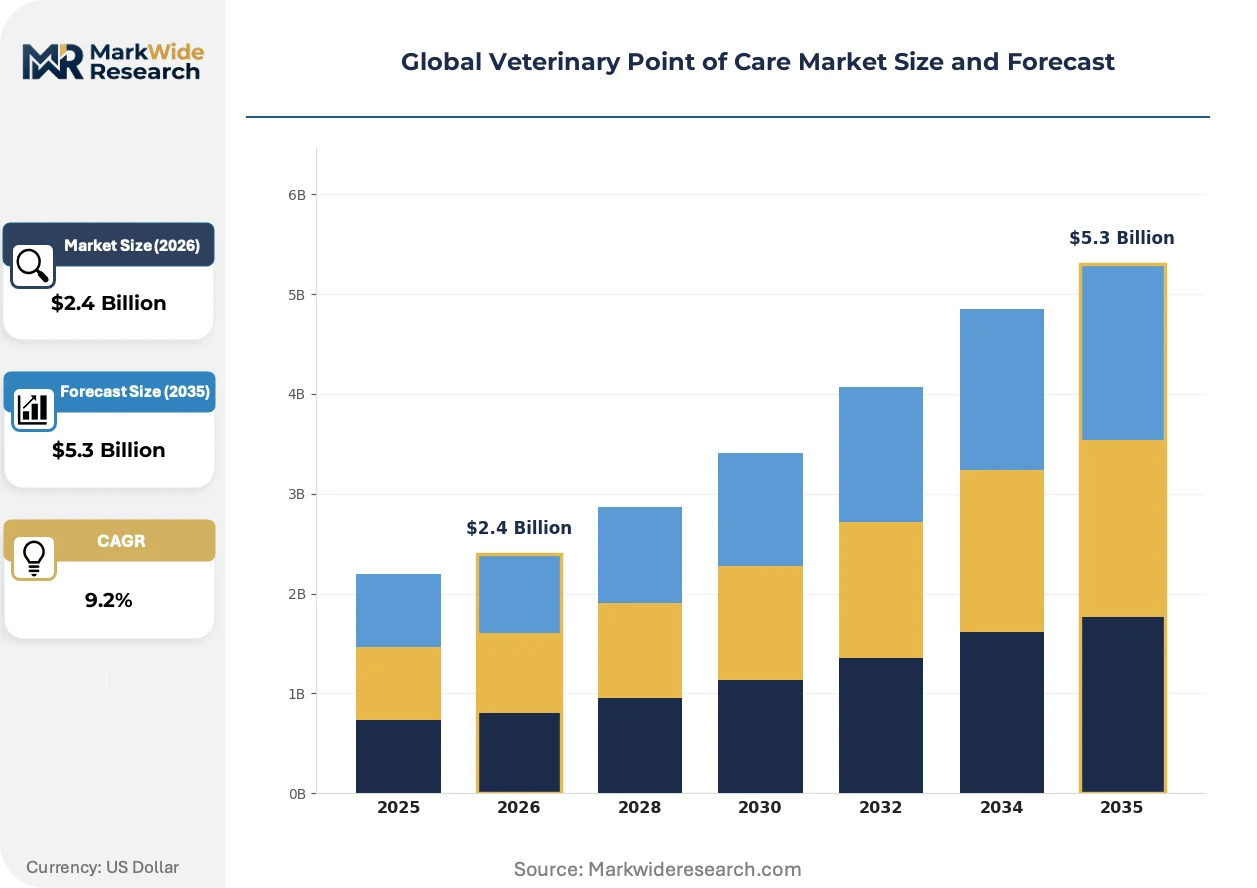
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Test Kits, Diagnostic Instruments, Imaging Equipment, Portable Devices Application: Canine Health, Feline Health, Equine Care, Livestock Monitoring, Exotic Animal Diagnostics End User: Veterinary Clinics, Mobile Veterinarians, Animal Hospitals, Research Facilities, Diagnostic Laboratories Deployment: In-Clinic, On-Farm, Mobile Units, Field Usage, Laboratory Settings |
| Companies Covered | IDEXX Laboratories, Zoetis, Virbac, Thermo Fisher Scientific, Antech Diagnostics, Heska Corporation, Mindray, Neogen, Woodley Equipment Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Point of Care Market Shifts & Advancements
Artificial intelligence and miniaturized optical sensors are converging to transform benchtop analyzers into decision-support systems that flag abnormal patterns without specialist interpretation. These advances compress the diagnostic workflow while expanding test menus beyond what reference laboratories traditionally offered.
Machine learning cytology platforms are automating differential cell counts and morphological classifications that previously required boarded pathologist review. Small animal emergency hospitals in the United States are deploying these systems overnight and during weekend shifts when specialist access is unavailable. This technology is automating the diagnostic bottleneck that historically forced 12-24 hour delays on critical care cases.
Japan's PMDA and MAFF have coordinated revised quality system requirements for cloud-connected livestock diagnostic devices that transmit epidemiological data to national disease surveillance databases. Manufacturers must now embed data-localization protocols that restrict cross-border server architecture. Domestic Japanese veterinary equipment suppliers are responding by building region-locked firmware that complies without fragmenting global product lines.
Subscription-based reagent purchasing is displacing capital-heavy instrument ownership models among independent companion animal practices. Leasing arrangements bundle hardware, maintenance, and consumable supply into per-test fees that align costs with patient volume. This shift is most visible in the United Kingdom and Netherlands where practice consolidation has concentrated buying power among corporate groups demanding operational flexibility over asset ownership.
Global Veterinary Point of Care Market Segmentation
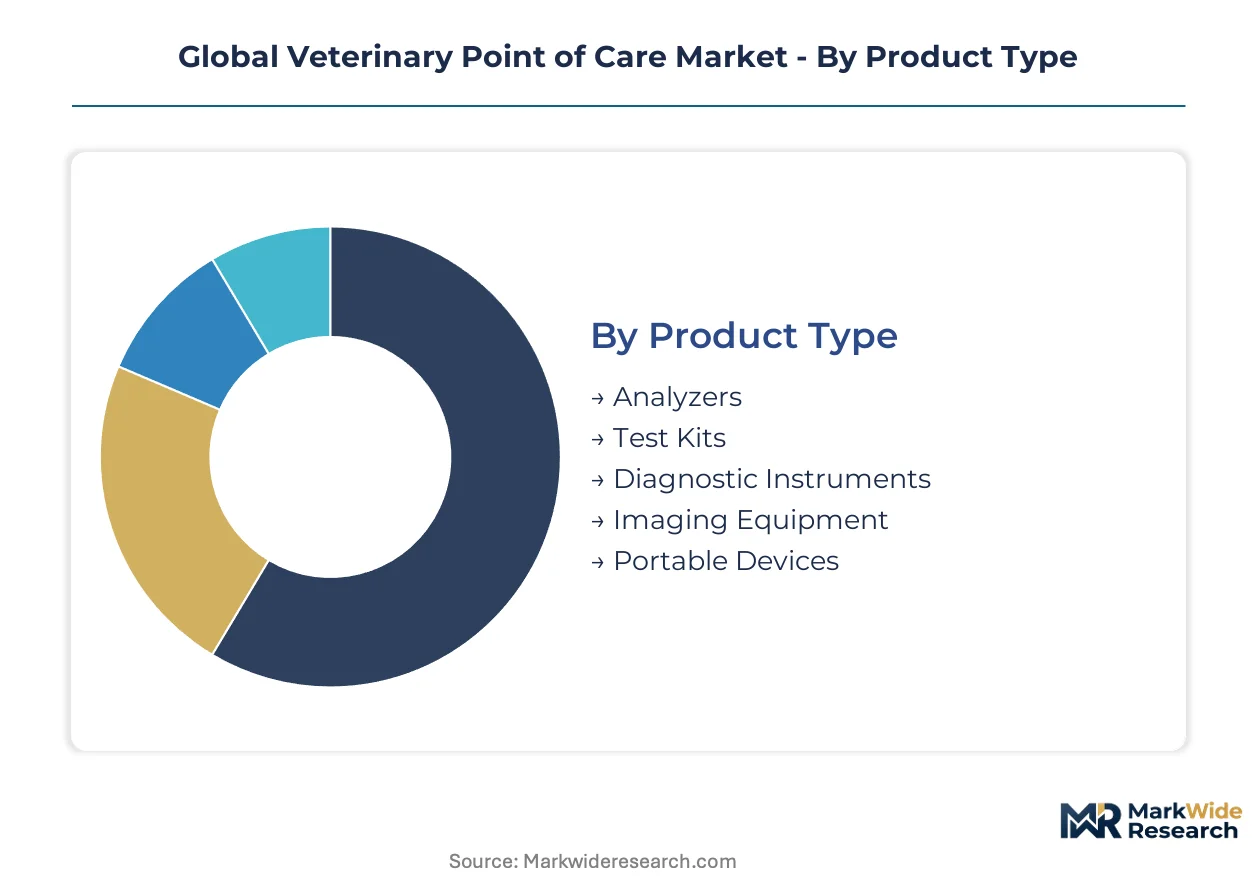
Veterinary point of care equipment fragments across four structural dimensions that determine procurement patterns, margin capture, and regulatory pathways. Each segmentation axis reveals distinct competitive dynamics between captive reagent ecosystems, workflow integration requirements, and species-specific validation burdens.
Product Type:
Supply concentration tilts heavily toward consumable-dependent platforms that lock clinics into recurring revenue streams through proprietary cartridge architectures.
- Analyzers:Benchtop chemistry and hematology systems process whole blood, serum, and urine with species-specific calibration curves. Demand clusters in companion animal hospitals across the United States and Germany where same-day turnaround commands premium pricing against reference lab alternatives.
- Test Kits:CLIA-waived immunoassay panels for canine pancreatitis, feline hyperthyroidism, and infectious disease screening dominate unit volume. Japan's livestock biosecurity mandates are accelerating procurement of multiplex pathogen detection kits for foot-and-mouth and avian influenza surveillance.
- Diagnostic Instruments:Integrated platforms combining sample preparation with automated readout reduce technician training requirements. Brazil's expanding cattle operations are adopting these systems for on-farm reproductive health monitoring.
- Imaging Equipment:Portable ultrasound and digital radiography systems command capital outlays five to ten times higher than analyzers. Equine sports medicine practices in Australia and the United Kingdom represent the primary demand concentration.
- Portable Devices:Battery-operated hematology and chemistry systems enable field deployment without fixed infrastructure. Mobile food-animal veterinarians in rural Canada and emergency response teams in disease outbreak zones are expanding the addressable base.
Today's leader: Analyzers. Tomorrow's challenger: Portable Devices.
Application:
Cost tier stratification separates premium-priced companion animal diagnostics from volume-driven livestock monitoring with divergent margin profiles.
- Canine Health:Rapid immunoassay panels for parvovirus, heartworm, and tick-borne disease dominate clinic throughput. Pet insurance reimbursement in Germany and the United States is removing price sensitivity barriers that previously diverted cases to reference laboratories.
- Feline Health:Pancreatitis and hyperthyroidism marker panels require higher analytical sensitivity due to smaller sample volumes. Specialist cat-only practices in Japan and the Netherlands are driving demand for workflow-optimized platforms with minimal sample requirements.
- Equine Care:Portable ultrasound for tendon and ligament assessment plus stall-side chemistry for competition monitoring. Racing and performance horse operations in Kentucky, Dubai, and Newmarket anchor procurement concentration.
- Livestock Monitoring:Reproductive health, metabolic profiling, and disease surveillance across cattle, swine, and poultry operations. Japan's MAFF surveillance protocols and Brazil's export certification requirements are mandating on-farm testing infrastructure.
- Exotic Animal Diagnostics:Avian, reptile, and small mammal hematology with species-specific reference intervals. Zoological institutions and exotic specialty practices in the United States and United Kingdom represent limited but high-margin demand.
Canine and feline applications currently capture the dominant revenue share, while livestock monitoring is climbing the fastest as biosecurity mandates expand across major protein-producing regions.
End User:
Customer type determines purchasing power concentration, with corporate veterinary groups extracting volume discounts that independent practices cannot match.
- Veterinary Clinics:Independent and corporate companion animal practices seeking same-day diagnostic autonomy. Subscription-based reagent purchasing is displacing capital ownership models among United Kingdom and Netherlands practice groups.
- Mobile Veterinarians:Ambulatory food-animal and equine practitioners operating without fixed infrastructure. Australia's vast pastoral zones and Brazil's remote cattle ranches are expanding the serviceable base for portable platforms.
- Animal Hospitals:Emergency and specialty referral centers requiring 24/7 diagnostic capability. Small animal emergency hospitals in the United States are deploying AI-assisted cytology systems overnight when pathologist access is unavailable.
- Research Facilities:Academic veterinary schools and pharmaceutical development sites with stringent validation requirements. Validation documentation demands for GLP compliance extend sales cycles but command premium pricing.
- Diagnostic Laboratories:Regional reference labs adopting point-of-care platforms for stat testing while maintaining central lab economies of scale. This hybrid model is gaining traction in Germany's fragmented laboratory landscape.
Veterinary clinics remain the volume anchor, though mobile veterinarians are gaining share fastest as battery-operated platforms extend reach beyond brick-and-mortar constraints.
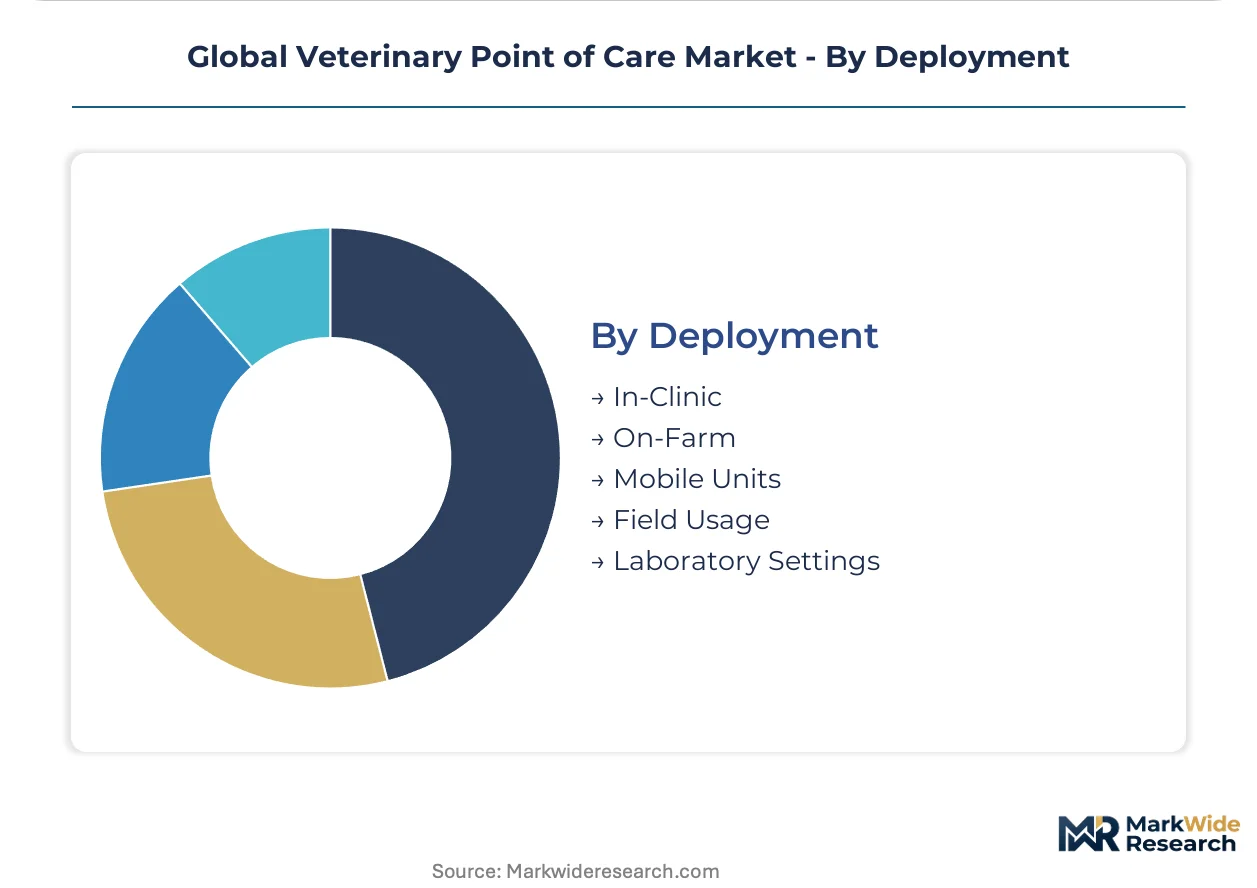
Deployment:
Maturity gradients separate established in-clinic workflows from emerging field deployment models with distinct regulatory and service requirements.
- In-Clinic:Fixed installation chemistry, hematology, and immunoassay platforms with integrated practice management connectivity. Legacy data format incompatibilities between IDEXX, Heska, and third-party EMR systems force expensive middleware investments.
- On-Farm:Livestock veterinarians conducting reproductive health and disease surveillance at production facilities. Japan's data-localization requirements for cloud-connected devices are fragmenting firmware architectures for this channel.
- Mobile Units:Self-contained diagnostic laboratories mounted in vehicles for equine sports medicine and emergency response. Hurricane and wildfire disaster veterinary teams in the United States and Australia are expanding fleet procurement.
- Field Usage:Handheld or backpack-portable devices for wildlife disease surveillance and remote location access. WHO-FAO-OIE funded zoonotic monitoring programs at wildlife-livestock interfaces are piloting dual human-animal pathogen detection platforms.
- Laboratory Settings:Point-of-care platforms deployed within reference lab facilities for rapid stat testing. This deployment mode is expanding most quickly in Germany as regional labs compete against corporate reference laboratory networks.
In-clinic deployment retains the dominant installed base, while field usage represents the steepest expansion trajectory as One Health surveillance programs fund portable pathogen detection capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as device makers relocate final assembly to jurisdictions with streamlined veterinary device clearances. The cost-of-compliance gap between the FDA Center for Veterinary Medicine and Japan's PMDA-MAFF coordination is driving platform development toward modular architectures that accommodate divergent data-localization mandates.
United States
Companion animal hospitals in Florida and Texas are deploying AI-assisted cytology systems overnight when boarded pathologist access is unavailable. The FDA's CLIA-waived pathway for veterinary immunoassays accelerates commercial entry for multiplex panels targeting canine pancreatitis markers. IDEXX Laboratories anchors its captive reagent ecosystem from manufacturing clusters in Maine and Iowa.
Germany
Pet insurance reimbursement frameworks now cover in-clinic diagnostic workups, removing price sensitivity barriers that previously funneled cases to reference laboratories. The EU IVDR imposes clinical evidence requirements on veterinary test kits that extend time-to-market by 18-24 months. Regional reference labs in Bavaria and North Rhine-Westphalia are adopting hybrid point-of-care models for stat testing.
Japan
MAFF surveillance protocols for foot-and-mouth disease and avian influenza compel on-farm rapid testing infrastructure across cattle and poultry operations. PMDA's revised quality system requirements for cloud-connected devices mandate data-localization protocols that restrict cross-border server architecture. Domestic suppliers in Osaka and Nagoya are building region-locked firmware to comply without fragmenting global product lines.
Brazil
Export certification requirements for cattle operations are mandating on-farm testing infrastructure across Minas Gerais and Mato Grosso. ANVISA's veterinary device framework lags FDA and PMDA harmonization, creating compliance friction for imported analyzers. Mobile food-animal veterinarians in the vast pastoral zones of the Pantanal are expanding demand for battery-operated hematology platforms.
Australia
Equine sports medicine practices in New South Wales and Victoria anchor procurement concentration for portable ultrasound systems. The TGA's veterinary device regulations align closely with FDA pathways, reducing regulatory friction for US-sourced platforms. Disaster veterinary response teams are expanding fleet procurement of self-contained mobile diagnostic laboratories for wildfire and flood deployment.
Global Veterinary Point of Care Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive reagent ecosystems commanding premium positioning against open-platform alternatives. The market structure concentrates around three to five dominant platform manufacturers whose proprietary cartridge architectures lock clinics into single-source consumable streams. Strategic archetypes include integrated life-science conglomerates, veterinary-dedicated device specialists, and human-health crossover manufacturers adapting clinical chemistry platforms. Competitive moves center on M&A activity targeting regional reference laboratory networks and technology licensing agreements for cloud-connected analyzer architectures.
Within the veterinary-dedicated tier, IDEXX Laboratories and Heska Corporation exemplify contrasting approaches to workflow integration and practice management connectivity. Zoetis occupies a position bridging vaccine-diagnostics integration across equine and livestock channels. These three anchors demonstrate how species-specific calibration expertise and captive consumable streams create defensive moats against human-health crossover competition.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Virbac |
| Thermo Fisher Scientific |
| Antech Diagnostics |
| Heska Corporation |
| Mindray |
| Neogen |
| Woodley Equipment Company |
| Others |
Supply & Pricing Matrix
Reagent cartridge manufacturing costs propagate downstream through captive ecosystem pricing, with proprietary optical sensor modules from Japanese suppliers feeding into tiered instrument-plus-consumable bundles that veterinary clinics in Germany and the United States absorb through subscription purchasing models.
Pricing Analysis
Distributor margin layers compress as direct-to-practice subscription contracts displace capital-sale intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated analyzer platforms from workflow-basic systems and refurbished entry units. Pricing pressure stems from corporate veterinary group procurement consolidation extracting volume discounts that independent practices cannot match. Mobile veterinarians in Australia's pastoral zones exhibit highest price sensitivity due to irregular caseloads, while emergency specialty hospitals in the United States show lowest sensitivity given 24/7 diagnostic imperatives.
Supply Chain Analysis
Refurbishment flows for hematology analyzers create secondary supply channels that extend equipment lifecycles and depress new-unit pricing in mature markets. Optical sensor manufacturing concentrates in Japan and Germany, while final instrument assembly clusters in the United States and China. Supply chains draw from rare-earth dependent laser diodes, species-specific calibration reagents, and lithium battery cells for portable platforms. Single-source vulnerability concentrates in proprietary cartridge molding operations. Distribution runs through veterinary distribution cooperatives in Europe and direct field service teams in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
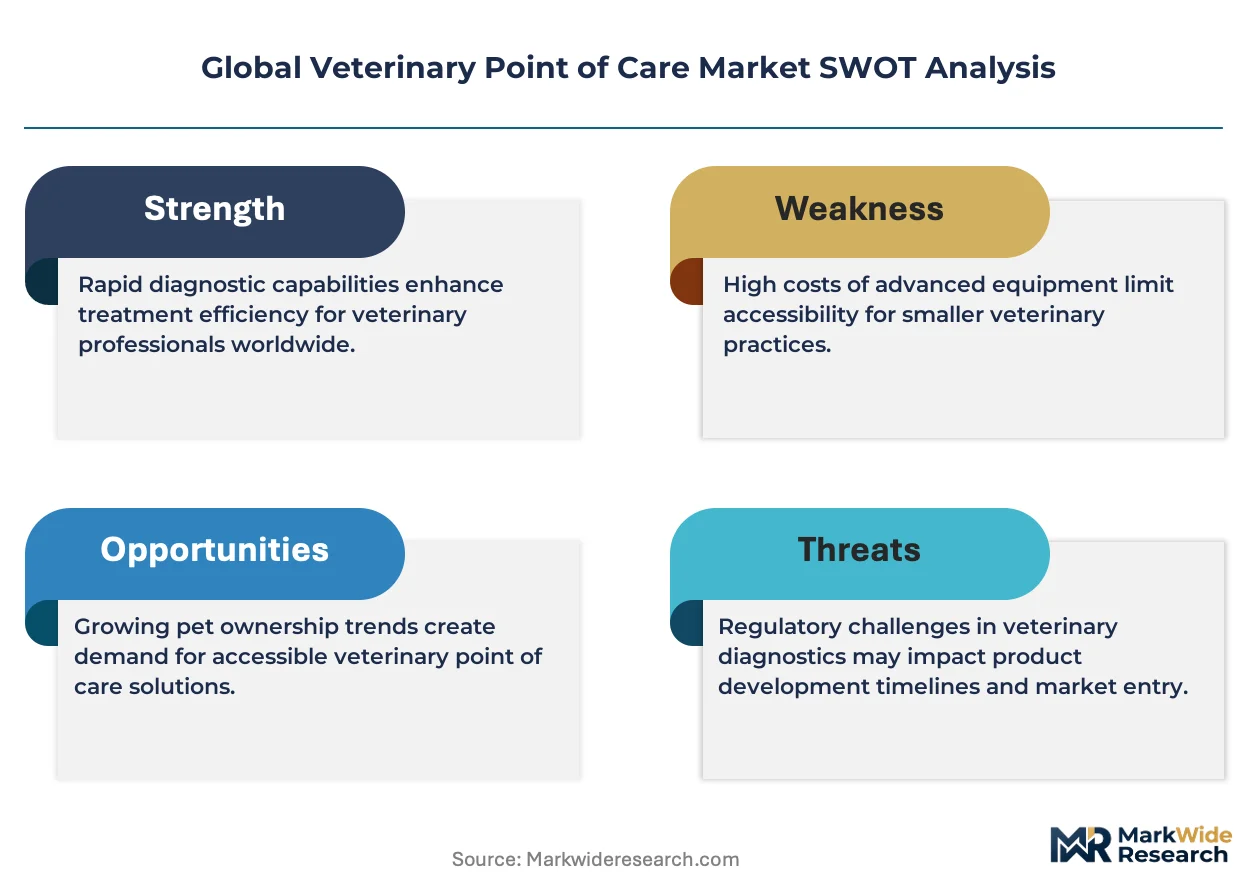
Margin expansion opportunities concentrate in consumable reagent streams and cloud-connected service tiers, as subscription purchasing displaces capital-heavy ownership models and reduces customer acquisition costs across the installed base.
For Market Incumbents: Cement captive reagent ecosystem loyalty through embedded AI diagnostic algorithms that lock clinics into proprietary data formats resisting third-party electronic medical record integration. Add service capacity in Japan to satisfy PMDA-MAFF data-localization mandates without fragmenting global firmware architectures. Defend against human-health crossover manufacturers by deepening species-specific calibration expertise in avian and exotic mammal parameters.
For New Entrants and Emerging Players: Mobile food-animal veterinarians in Brazil's Pantanal and Australia's remote cattle stations represent an underserved buyer archetype with unmet demand for battery-operated hematology platforms. Penetrate through veterinary cooperative purchasing groups in the Netherlands and United Kingdom that lack corporate group bargaining power. Deploy field-based technical service teams as differentiated go-to-market infrastructure against incumbent remote-support models.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional reference laboratory networks retain diagnostic interpretation expertise that AI platforms threaten to automate. Long-term viability favors manufacturers with vertically integrated reagent production and cloud architecture control. Target acquisition profiles center on veterinary-specific hardware specialists with installed base conversion potential. Monitor CLIA-waived test kit approval velocity at FDA as inflection indicator for competitive entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Analyzer Architecture | PMDA-MAFF data-localization mandates in Japan force region-locked firmware development without global product line fragmentation. |
| AI-Assisted Cytology Platform Launch | Small animal emergency hospitals in the United States deploy automated differential counts overnight when boarded pathologist access disappears. |
| Subscription-Based Reagent Purchasing | Corporate practice groups in the United Kingdom and Netherlands demand per-test fee structures aligning costs with patient volume fluctuations. |
| Mobile Diagnostic Unit Fleet Expansion | Disaster veterinary response teams in Australia and the United States procure self-contained laboratories for wildfire and flood deployment. |
| Species-Specific Calibration Investment | Avian, reptile, and exotic mammal reference intervals fragment addressable volume per SKU but defend margin against human-health crossover competition. |
Research Methodology
Multiple input streams — executive interviews with veterinary diagnostic platform manufacturers, procurement discussions with corporate practice group managers, and regulatory filings with FDA Center for Veterinary Medicine and Japan's PMDA — were reconciled against secondary validation from customs trade data, GPO contract databases, and veterinary medical association membership records. Bottom-up instrument installation counts and top-down reagent consumption estimates were triangulated to anchor market sizing.
Data-stream reconciliation across product type, application, end user, and deployment mode dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating pet insurance reimbursement expansion, livestock biosecurity mandate implementation, and cloud-connected analyzer adoption curves. Forecast inputs included CLIA-waived test kit approval timelines and corporate veterinary practice consolidation rates.
Underlying measurement precision varies by segment; analyzers and test kits carry tighter precision than imaging equipment and exotic animal diagnostics due to more transparent procurement channels. Forecasts reflect documented assumptions about regulatory pathway efficiency and reagent supply concentration stability. Practitioners should monitor EU IVDR conformity assessment delays and Japan data-localization enforcement intensity for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Animal Sedative Market
Veterinary
Bovine Mastitis Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Global Dog Vaccines Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Spay and Neuter Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Canine Parvovirus Market
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market