
 Mexico Nuclear Imaging Market | 2026-2036
Mexico Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Nuclear Imaging Market Foresight
High-resolution quantitative imaging is bifurcating the Mexico nuclear imaging landscape into premium molecular-diagnostic tiers and conventional functional-imaging tiers. GE HealthCare leverages its cyclotron network to sustain radiotracer availability across central Mexico. Siemens Healthineers anchors hybrid PET-MRI installations at tertiary oncology centers in Guadalajara and Monterrey. Philips competes through digital PET detector platforms that reduce scan duration for high-throughput hospital networks.
Nuclear imaging deploys gamma-emitting radiopharmaceuticals and positron-emitting tracers to visualize metabolic, perfusion, and receptor-based processes at spatial resolutions below five millimeters; its primary purpose is early-stage lesion detection, therapy response monitoring, and surgical planning in complex disease states. Hybrid systems command the highest capital allocation among product categories as Mexican institutions prioritize simultaneous anatomical and functional acquisition. Oncology applications generate the dominant procedure volume, though cardiology stress-perfusion protocols are expanding fastest at dedicated imaging clinics. AI integration within technology segments is attracting software-margin pools as vendors embed automated lesion segmentation and dose-optimization algorithms.
COFEPRIS maintains radiopharmaceutical licensing and Good Manufacturing Practice enforcement, while the Secretariat of Health sets nuclear medicine facility accreditation standards that constrain market entry to certified operators. CNSNS governs radioactive material handling, transport security, and waste disposal protocols that elevate operational compliance costs for clinic operators. Stakeholders must monitor forthcoming COFEPRIS biologic-equivalence guidelines for generic radiotracers, as these will determine whether domestic compounding facilities can displace imported diagnostic agents.
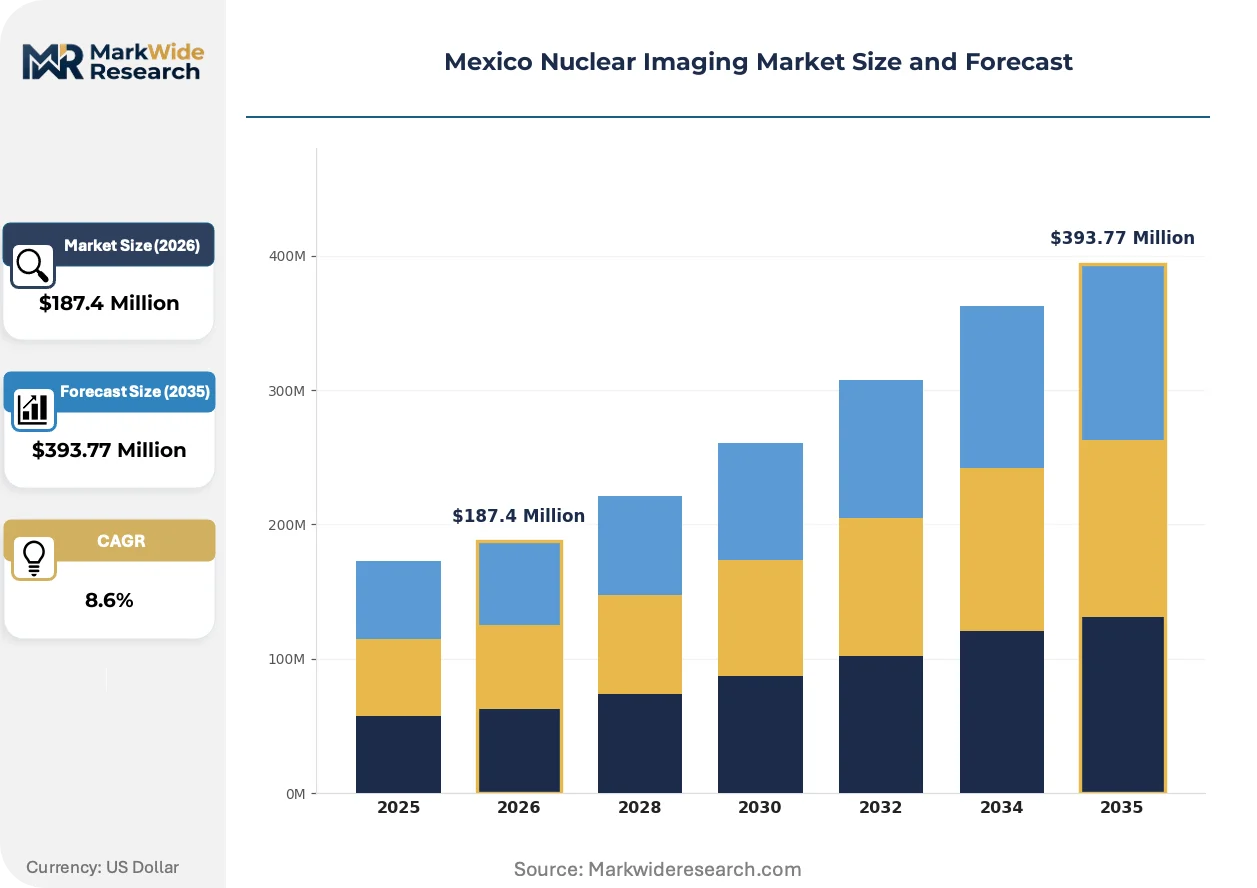
Market Dynamics
COFEPRIS regulatory modernization is compressing radiopharmaceutical approval timelines while CNSNS radioactive material protocols elevate operational compliance costs, creating a bifurcated competitive landscape where capital-rich hospital networks capture PET-CT procurement advantages over standalone imaging clinics.
Growth Catalysts
- Oncology Department Expansion:Public hospital networks in Mexico City and Monterrey are prioritizing PET-CT installations for lesion detection and therapy monitoring, driving capital equipment demand through dedicated oncology infrastructure budgets.
- COFEPRIS Acceleration Framework:Streamlined biologic-equivalence guidelines for generic radiotracers are opening procurement pathways for domestic compounding facilities to displace imported diagnostic agents.
- AI-Enabled Workflow Integration:Automated lesion segmentation algorithms embedded within hybrid imaging systems are reducing scan duration and radiologist interpretation burden at high-throughput hospital networks.
Market Restraints
- Cyclotron Network Concentration:Radiotracer production clusters in central Mexico create geographic supply vulnerability for peripheral states lacking on-site isotope generation capacity.
- CNSNS Compliance Cost Escalation:Radioactive material handling, transport security, and waste disposal protocols impose recurring operational expenditures that constrain clinic operator margins.
- FDG-18 Import Dependency:Positron-emitting tracer supply chains remain tethered to foreign manufacturing facilities, exposing procurement to currency fluctuation and logistics disruption.
Strategic Opportunities
- Guadalajara Metropolitan Corridor:Tertiary oncology centers in Jalisco state present underpenetrated demand for PET-MRI hybrid installations serving complex surgical planning cases.
- Cardiology Stress-Perfusion Protocols:Dedicated imaging clinics are expanding myocardial perfusion imaging volumes faster than oncology applications, creating service-line diversification potential.
- Digital PET Detector Platforms:Solid-state photon-counting technology convergence with conventional scintillation systems is enabling scan-time reduction that supports throughput expansion at constrained facilities.
Industry Challenges
- Radiopharmaceutical Compounder Certification:COFEPRIS Good Manufacturing Practice enforcement timelines delay domestic production scale-up, extending import dependency for critical diagnostic agents.
- Hybrid System Integration Complexity:PET-CT and PET-MRI installations require specialized medical physics expertise and facility shielding retrofitting that prolongs commissioning cycles at hospital sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Nuclear Imaging Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Scanners, SPECT Scanners, Hybrid Systems, Radiopharmaceuticals End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: Digital Imaging, Analog Imaging, 3D Imaging, AI Integration Application: Oncology, Cardiology, Neurology, Pain Management |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Bracco Imaging, Lantheus Medical Imaging, Curium Pharma, United Imaging Healthcare, Shimadzu, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Nuclear Imaging Market Shifts & Advancements
Digital detector architectures and AI-embedded reconstruction algorithms are compressing scan protocols while regulatory harmonization efforts reshape radiopharmaceutical sourcing strategies across Mexican imaging networks.
Silicon photomultiplier arrays are decomposing conventional photomultiplier tube dominance in PET detector stacks. Tertiary oncology centers in Monterrey and Guadalajara are adopting these solid-state platforms for their magnetic-field immunity and timing resolution advantages. The technology is decomposing legacy scintillation system upgrade cycles by enabling direct digital signal processing that eliminates analog-to-digital conversion stages.
COFEPRIS biologic-equivalence guidelines for generic radiotracers are creating domestic manufacturing pathways previously blocked by imported agent monopolies. Compounding facilities in Mexico City metropolitan corridor are securing Good Manufacturing Practice certifications to produce FDG-18 and specialized receptor-binding tracers. Hospital procurement departments are responding by diversifying supplier portfolios to include certified domestic compounders alongside established importers.
Service unbundling is separating equipment acquisition from radiopharmaceutical supply and maintenance contracts. Private hospital networks are negotiating direct cyclotron access agreements rather than bundled vendor packages, while independent imaging clinics are joining purchasing consortia to secure volume-based tracer pricing. This pattern is most visible in Mexico City where consolidated procurement groups now represent multiple clinic operators in centralized sourcing negotiations.
Mexico Nuclear Imaging Market Segmentation
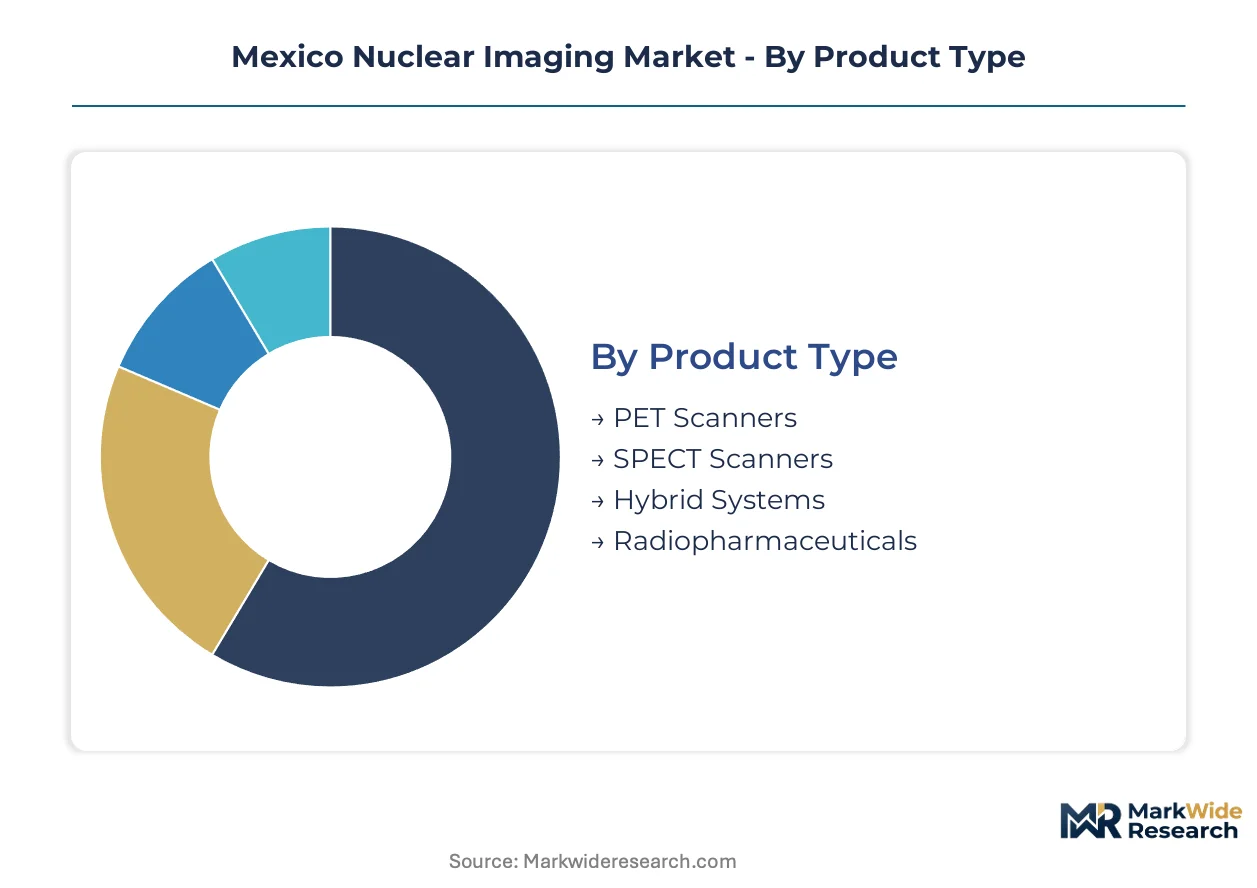
Segmentation in the Mexico nuclear imaging market reveals how capital allocation, regulatory compliance, and clinical workflow demands shape procurement decisions across institutional buyers. Understanding these divides clarifies where domestic production advantages compete against imported technology premiums.
Product Type:
Domestic radiopharmaceutical compounding clusters in Mexico City and Monterrey supply regional hospital networks, while hybrid systems and PET scanners remain import-dependent through GE HealthCare and Siemens Healthineers distribution channels.
- Hybrid Systems:PET-CT and PET-MRI configurations integrate metabolic and anatomical acquisition into single-session protocols. Tertiary oncology centers in Guadalajara and Monterrey prioritize these platforms for complex surgical planning cases where precise lesion localization determines resectability.
- Radiopharmaceuticals:FDG-18, technetium-based perfusion agents, and specialized receptor-binding tracers constitute the consumable backbone of nuclear imaging procedures. COFEPRIS-certified domestic compounders in the Mexico City metropolitan corridor are displacing imported diagnostic agents as biologic-equivalence guidelines mature.
- PET Scanners:Standalone positron-emission systems serve high-volume oncology departments requiring dedicated metabolic imaging capacity without concurrent CT acquisition.
- SPECT Scanners:Single-photon systems dominate myocardial perfusion imaging and bone scintigraphy procedures at mid-tier diagnostic centers.
Hybrid systems command the established base. The steepest expansion runs through radiopharmaceuticals as domestic compounding scales.
End User:
Capital intensity and procedure volume thresholds separate institutional buyers into tiered procurement segments with distinct financing mechanisms and regulatory exposure.
- Hospitals:Public hospital networks in Mexico City and Monterrey deploy dedicated oncology infrastructure budgets toward PET-CT installations. COFEPRIS facility accreditation requirements and CNSNS radioactive material protocols favor capital-rich operators with compliant shielding and waste management infrastructure.
- Diagnostic Centers:Standalone imaging facilities concentrate cardiology stress-perfusion protocols and routine oncology staging procedures. These operators face margin pressure from cyclotron network concentration in central Mexico that elevates radiotracer logistics costs.
- Imaging Clinics:Private operators in consolidated purchasing consortia negotiate volume-based tracer pricing and direct cyclotron access agreements.
- Research Institutions:Academic medical centers deploy hybrid systems for clinical trial imaging endpoints and translational radiopharmaceutical development.
Hospitals anchor equipment procurement volume. Diagnostic centers are gaining share fastest through cardiology service-line diversification.
Technology:
Detector architecture and computational processing capabilities determine scan throughput, dose efficiency, and integration complexity across Mexican installation sites.
- Digital Imaging:Silicon photomultiplier arrays and solid-state photon-counting platforms eliminate analog-to-digital conversion stages. Tertiary centers in Monterrey adopt these systems for magnetic-field immunity and timing resolution advantages in PET-MRI configurations.
- AI Integration:Automated lesion segmentation algorithms and dose-optimization software embed within reconstruction pipelines. High-throughput hospital networks deploy these tools to compress scan duration and reduce radiologist interpretation burden.
- 3D Imaging:Iterative reconstruction methods and volumetric acquisition protocols enhance lesion detectability in obesity and motion-compromised patients.
- Analog Imaging:Conventional photomultiplier tube-based systems persist at budget-constrained facilities with extended depreciation cycles.
Digital imaging holds the installed base. AI integration is climbing the fastest as vendors embed software-margin pools into hardware contracts.
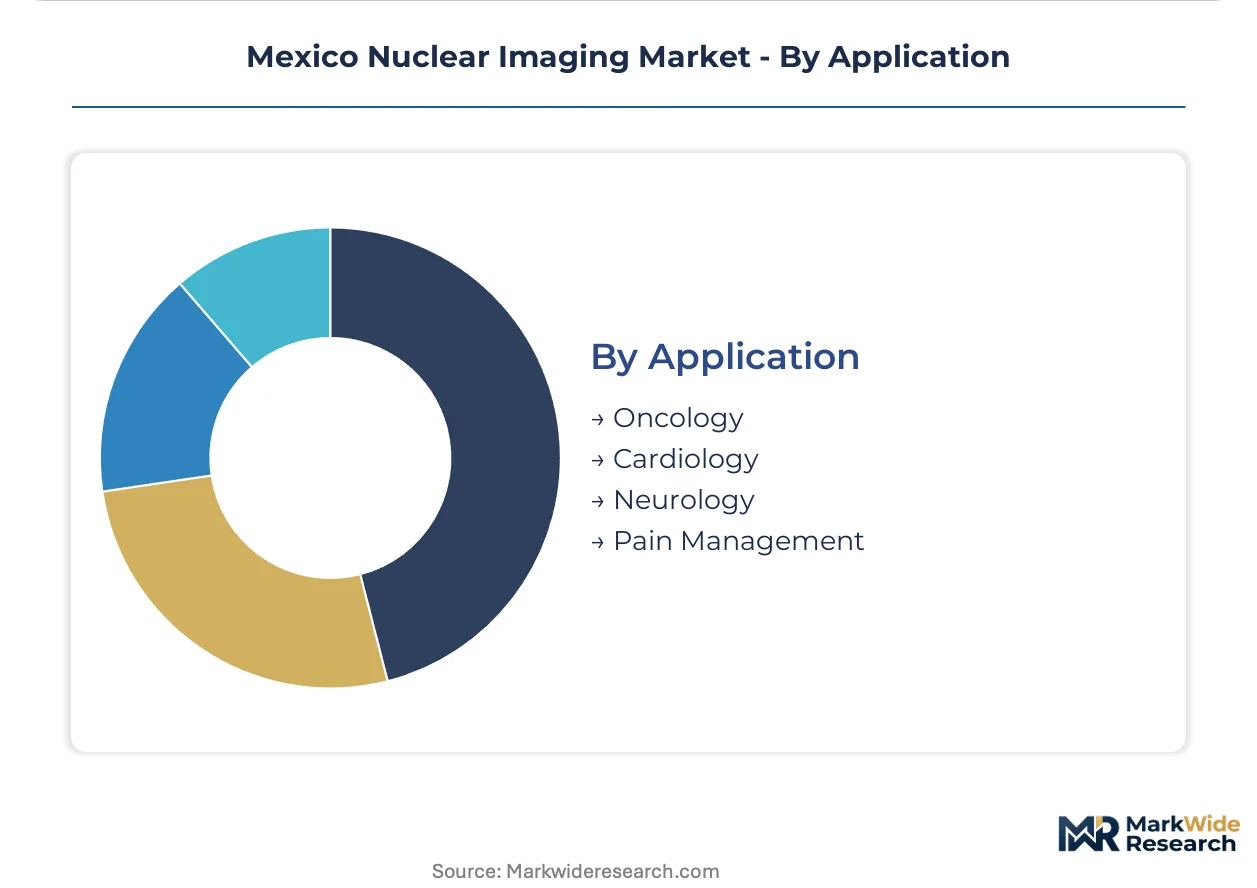
Application:
Clinical indication drives radiotracer selection, imaging protocol design, and reimbursement positioning across Mexican healthcare payment systems.
- Oncology:FDG-18 PET-CT dominates lesion detection, staging, and therapy response monitoring for lung, breast, colorectal, and lymphoid malignancies. Public hospital oncology departments in Mexico City and Monterrey generate the dominant procedure volume through dedicated cancer center infrastructure.
- Cardiology:Myocardial perfusion imaging with technetium-based agents and rubidium-82 PET expands fastest at dedicated imaging clinics. Stress-perfusion protocols address coronary artery disease burden in aging metropolitan populations.
- Neurology:Amyloid-binding tracers and dopaminergic system imaging serve dementia and movement disorder differential diagnosis at specialized academic centers.
- Pain Management:Bone scintigraphy and inflammatory agent imaging localize occult fracture, infection, and complex regional pain syndrome sources.
Oncology commands the established base. Cardiology represents the fastest-growing trajectory as dedicated clinics scale stress-perfusion service lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cyclotron production clusters in central Mexico concentrate radiotracer supply chains, while peripheral states face logistics vulnerability. Metropolitan corridors anchor equipment procurement through dedicated oncology infrastructure budgets and consolidated purchasing consortia.
Mexico City Metro
Public hospital networks deploy PET-CT installations for lesion detection and therapy monitoring through dedicated cancer center infrastructure. COFEPRIS facility accreditation standards constrain market entry to certified operators with compliant shielding protocols. Tertiary oncology centers in the metropolitan corridor generate dominant procedure volumes for FDG-18 PET-CT applications.
Nuevo León
Monterrey metropolitan hospitals prioritize hybrid PET-MRI configurations for complex surgical planning cases. CNSNS radioactive material handling protocols elevate operational compliance costs for clinic operators throughout the state. Siemens Healthineers anchors hybrid installations at tertiary centers serving northern Mexico's oncology demand.
Jalisco
Guadalajara's tertiary oncology centers present underpenetrated demand for PET-MRI hybrid systems. COFEPRIS biologic-equivalence guidelines for generic radiotracers are opening procurement pathways for domestic compounding facilities. The metropolitan corridor is scaling cardiology stress-perfusion protocols faster than oncology applications.
Bajío Region
Mid-tier diagnostic centers concentrate myocardial perfusion imaging with technetium-based agents and SPECT systems. Cyclotron network concentration in central Mexico creates geographic supply vulnerability for this peripheral zone. Independent imaging clinics are joining purchasing consortia to secure volume-based tracer pricing.
Northern Border States
Cross-border patient flows and medical tourism infrastructure drive demand for high-throughput digital PET platforms. CNSNS transport security protocols for radioactive materials impose recurring operational expenditures at border facilities. Consolidated procurement groups now represent multiple clinic operators in centralized sourcing negotiations.
Mexico Nuclear Imaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Mexico nuclear imaging market. The vendor base separates into three strategic tiers: multinational imaging system manufacturers with cyclotron networks, specialized radiopharmaceutical compounders securing COFEPRIS certifications, and regional distributors bundling equipment with maintenance contracts. Dominant competitive moves include backward integration into radiotracer production and geographic expansion through direct cyclotron access agreements rather than bundled vendor packages.
Among multinational equipment manufacturers, GE HealthCare, Siemens Healthineers, and Koninklijke Philips occupy positions anchoring the premium hybrid system segment. GE HealthCare represents the archetype of cyclotron-integrated supply chains sustaining radiotracer availability across central Mexico. Siemens Healthineers exemplifies the PET-MRI specialization vector at tertiary oncology centers. Koninklijke Philips sits within the digital detector platform tier competing on scan duration reduction for high-throughput networks.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Bracco Imaging |
| Lantheus Medical Imaging |
| Curium Pharma |
| United Imaging Healthcare |
| Shimadzu |
| Others |
Supply & Pricing Matrix
Domestic FDG-18 compounding displacing imported radiotracers simultaneously reshapes supply geography toward Mexico City-Monterrey production clusters and compresses procurement economics for hospital networks previously tethered to foreign currency exposure.
Pricing Analysis
COFEPRIS biologic-equivalence guidelines dictate the pricing tier structure across Mexican nuclear imaging procurement. Three-tier pricing structure across premium hybrid systems, standard PET-CT configurations, and economy SPECT platforms separates capital-rich tertiary centers from mid-tier diagnostic operators. Cost compression in the radiopharmaceutical tier is intensifying because domestic compounders undercut import landed costs by eliminating currency hedging and customs duties. Diagnostic centers and standalone imaging clinics exhibit highest price sensitivity, while public hospital networks with dedicated oncology infrastructure budgets demonstrate lowest sensitivity to capital equipment premiums.
Supply Chain Analysis
Cyclotron network concentration in central Mexico creates a chokepoint that elevates logistics costs for peripheral states lacking on-site isotope generation. Radiotracer production draws from USA, Canada, and domestic Mexican compounding facilities for FDG-18 and specialized receptor-binding agents. Raw material dependencies include enriched uranium feedstock, molybdenum-99 generators, and germanium-68/gallium-68 elution systems. Single-source vulnerability runs through foreign FDG-18 manufacturing facilities exposed to cross-border transport disruptions. Distribution runs through direct cyclotron access agreements and consolidated purchasing consortia rather than bundled vendor packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as AI-enabled workflow automation threatens to commoditize conventional hardware differentiation and redirect margin pools toward software-embedded reconstruction algorithms.
For Market Incumbents: Consolidate cyclotron network control through direct production facility investments in Guadalajara and Monterrey corridors to secure radiotracer supply autonomy against import dependency volatility. Deepen backward integration into silicon photomultiplier detector manufacturing to capture timing resolution advantages and reduce exposure to legacy scintillation system obsolescence. For New Entrants and Emerging Players: Cardiology stress-perfusion service gaps at mid-tier diagnostic centers in Jalisco and Bajío regions present white-space entry points where incumbents under-serve aging metropolitan populations with coronary artery disease burden. Target direct cyclotron access partnerships with COFEPRIS-certified domestic compounders to bypass bundled vendor procurement channels and compete on tracer pricing transparency. For Investors and Strategic Acquirers: COFEPRIS Good Manufacturing Practice certification timelines reshape the acquisition landscape by elevating domestic radiopharmaceutical compounders with secured production licenses above import-dependent distribution plays. Long-term viability centers on facilities with captive isotope generation capacity and established hospital network procurement relationships. Monitor CNSNS radioactive material transport security protocol amendments as the critical inflection signal for operational compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Direct isotope production in Guadalajara reduces peripheral state supply vulnerability and import dependency exposure. |
| COFEPRIS GMP Certification Investment | Domestic compounding licensure unlocks procurement pathways previously blocked by foreign agent monopolies. |
| Digital Detector Platform Deployment | Solid-state photon-counting technology at Monterrey tertiary centers enables scan-time reduction for throughput expansion. |
| AI-Embedded Reconstruction Licensing | Automated lesion segmentation algorithms redirect margin pools from hardware toward software-margin capture at high-throughput networks. |
| Cardiology Service Line Diversification | Stress-perfusion protocol expansion at Jalisco diagnostic clinics addresses fastest-growing application trajectory. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, nuclear medicine physicians, and cyclotron facility operators and secondary validation through COFEPRIS regulatory filings, CNSNS safety protocol databases, hospital equipment procurement records, and GPO contract repositories anchors the qualitative findings. Bottom-up installation data triangulates against top-down healthcare infrastructure budget allocations across Mexican states.
Sensitivity analysis on cyclotron network expansion scenarios and domestic compounding scale-up timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user institution tier, detector technology architecture, and clinical application with regional regulatory cluster overlays. CAGRs derive from equipment procurement pipeline tracking and procedure volume elasticity estimates tied to oncology department expansion and cardiology protocol adoption curves.
Material uncertainties — COFEPRIS biologic-equivalence guideline implementation delays, CNSNS radioactive material handling protocol amendments, and FDG-18 import supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory modernization pace and domestic manufacturing certification timelines. Practitioners should keep alternative scenarios live as cyclotron network geographic coverage and AI-embedded workflow penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
South America CT Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
North America Open System MRI Market