
 Stationary Anode CT X-Ray Tube Market | 2026-2036
Stationary Anode CT X-Ray Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Anode CT X-Ray Tube Market Insights
China is reshaping supply dynamics through expanded domestic electron tube manufacturing corridors. Siemens Healthineers AG leverages vertical integration across its Munich and Shanghai facilities to control critical component flows. Varex Imaging Corporation anchors North American supply through its Salt Lake City operations, while Canon Electron Tubes & Devices Co., Ltd dominates precision ceramic-metal assembly for high-voltage seals.
A stationary anode CT X-ray tube employs a fixed tungsten or tungsten-rhenium target surface bombarded by a focused electron beam, typically operating at 40-150 kV with thermal management via embedded copper or molybdenum substrates and dielectric oil or forced-air cooling circuits. Its primary purpose is to generate controlled X-ray flux for computed tomography scanners where moderate duty cycles and cost-sensitive positioning outweigh rotating anode performance thresholds. Sealed tube architectures command the dominant installed base due to maintenance predictability, while stationary anode tube configurations retain strong positioning in entry-level CT and mobile C-arm systems where capital constraints limit rotating anode adoption. Fixed installation deployments concentrate margin pools in hospital radiology departments, whereas mobile installation segments face pricing pressure from shorter equipment lifecycles.
The FDA enforces 21 CFR 1020.32 performance standards for CT X-ray systems, directly shaping tube thermal specifications and output stability requirements for US market access. IEC 60601-2-44 governs international safety and essential performance benchmarks, while China's NMPA implements GB standards that mandate local testing for imported tubes. Stakeholders must monitor evolving dual carbon goals from China's MEE, as energy efficiency metrics increasingly factor into public hospital procurement scoring and supplier qualification protocols.
Market Dynamics
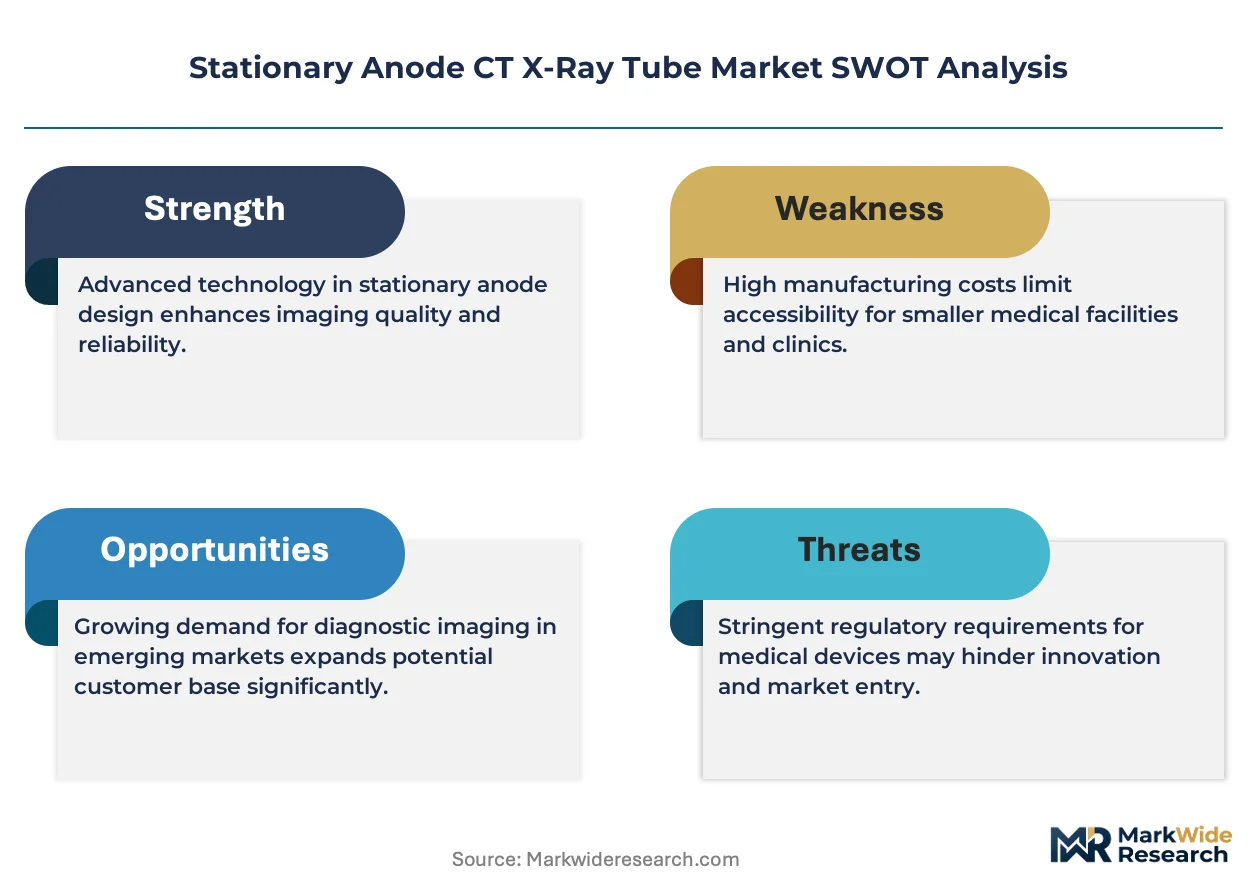
FDA diagnostic reference levels for CT radiation exposure are compressing thermal efficiency tolerances across tube architectures, forcing manufacturers to redesign anode substrates and cooling circuits to maintain output stability under stricter dose constraints.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturing incentives are accelerating hospital procurement of mid-range CT systems with stationary anode configurations. Government health infrastructure schemes are expanding diagnostic imaging access in tier-2 and tier-3 cities.
- Aging demographics in Southeast Asia:Diagnostic imaging centers across Thailand, Vietnam, and Indonesia are expanding CT scanner fleets to serve geriatric patient volumes. Stationary anode tubes meet cost-sensitive positioning for these expansion programs.
- IEC 60601-2-44 harmonization:International safety standard alignment is reducing certification friction for tube manufacturers entering multiple markets. Essential performance benchmarks create predictable qualification pathways for sealed tube architectures.
Market Restraints
- Tungsten-rhenium alloy cost volatility:Target material price swings compress margin predictability for tube manufacturers. Input concentration in Chinese mining and processing corridors creates supply vulnerability.
- Rotating anode performance threshold gaps:Thermal loading limitations constrain stationary anode adoption in high-duty-cycle trauma centers and cardiac CT applications. Rotating anode tubes retain positioning where scan volume intensity exceeds fixed-target thermal capacity.
- China's NMPA local testing mandates:GB standards requiring domestic certification for imported tubes extend market entry timelines. Regulatory friction disproportionately affects foreign suppliers without Shanghai or Beijing testing partnerships.
Strategic Opportunities
- Mobile C-arm system expansion:Point-of-care imaging deployment in ambulatory surgical centers creates demand for compact, cost-optimized tube configurations. Stationary anode architectures match capital constraints and moderate duty cycles of mobile installations.
- China's dual carbon goals from MEE:Energy efficiency metrics are increasingly factoring into public hospital procurement scoring. Suppliers qualifying under green procurement protocols gain preferential positioning in state-funded health infrastructure tenders.
- Ceramic-metal seal precision advances:Convergence of vacuum brazing automation with high-voltage dielectric materials is enabling longer-service-life tube designs. Canon Electron Tubes & Devices Co. and comparable specialists are capturing margin pools from reliability differentiation.
Industry Challenges
- Vacuum technology skill scarcity:Electron gun assembly and high-voltage seal fabrication require specialized technicians. Workforce gaps constrain production scaling for tube manufacturers expanding beyond legacy product lines.
- Legacy CT system integration complexity:Replacement tube compatibility with installed base architectures demands extensive retrofit engineering. OEMs face capex intensity in maintaining backward-compatible design portfolios across multiple scanner generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Anode CT X-Ray Tube Market |
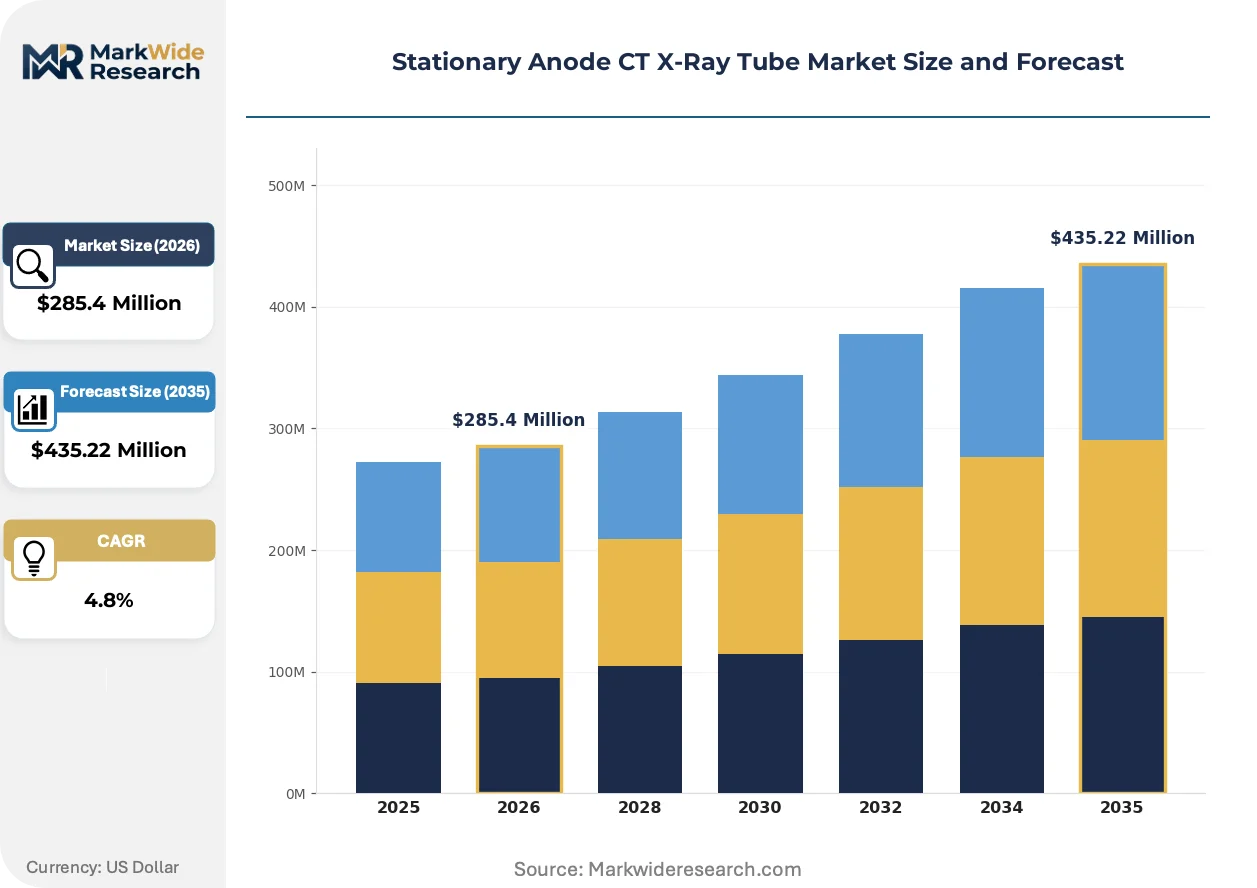
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Tube, Open Tube, Rotating Anode Tube, Stationary Anode Tube End User: Hospitals, Diagnostic Imaging Centers, Research Labs, Emergency Clinics Technology: X-Ray Computed Tomography, Digital Radiography, Fluoroscopy, Mammography Installation: Fixed Installation, Mobile Installation, Temporary Installation, Permanent Installation |
| Companies Covered | Siemens Healthineers AG, Dunlee, Varex Imaging Corporation, Canon Electron Tubes & Devices Co., Ltd, Oxford Instruments, IAE Sp.A, Comet Group, Toshiba Electron Tubes & Devices Co., Ltd, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Anode CT X-Ray Tube Market Trends and Innovations
Thermal management architectures are converging with radiation dose optimization protocols, reshaping how tube manufacturers balance output stability against cooling circuit complexity and material cost structures.
Dielectric oil-cooled stationary anode designs are hybridizing with forced-air convection circuits to reduce weight and maintenance intervals in mobile CT configurations. Rural diagnostic centers and emergency deployment units are adopting these hybrid thermal systems to extend equipment uptime without fixed infrastructure dependencies. The convergence is compressing traditional trade-offs between sealed tube reliability and rotating anode thermal performance in mid-range system categories.
The FDA's renewed enforcement of 21 CFR 1020.32 performance standards is tightening CT X-ray system thermal specification windows. Tube manufacturers must demonstrate output stability across expanded temperature and humidity ranges to maintain US market access. High-voltage seal and electron gun assembly segments face the most intensive retesting burdens as diagnostic reference levels push dose efficiency requirements downward.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance models. Independent service organizations are capturing replacement tube and refurbishment contracts from hospital procurement departments seeking cost containment. This pattern concentrates in India's government hospital networks, where budget pressures are decoupling equipment acquisition from long-term service agreements.
Stationary Anode CT X-Ray Tube Market Segmentation
Stationary anode CT X-ray tube procurement patterns diverge sharply across product architectures, end-user capital constraints, and deployment mobility requirements. Manufacturers must align thermal specifications and service models with distinct segment economics to capture margin pools effectively.
Product Type:
Mature sealed tube architectures dominate installed bases, while emerging configurations address evolving thermal efficiency mandates.
- Sealed Tube:Vacuum-integrated designs with embedded copper or molybdenum substrates eliminate external pumping infrastructure. Diagnostic imaging centers in India's tier-2 cities favor these architectures for maintenance predictability under constrained biomedical engineering staffing.
- Stationary Anode Tube:Fixed tungsten-rhenium targets operating at 40-150 kV serve moderate duty cycles where capital sensitivity outweighs rotating anode performance thresholds. Government health infrastructure schemes across Southeast Asia are accelerating procurement for mid-range CT systems.
- Open Tube:Demountable vacuum envelopes permit field refurbishment of electron gun assemblies. Research labs with captive vacuum technician pools exploit this flexibility for extended service lifecycles.
- Rotating Anode Tube:Disc-based thermal dissipation architectures address high-duty-cycle trauma and cardiac applications. Thermal loading advantages constrain stationary anode penetration in these throughput-intensive settings.
Sealed tube configurations retain volume leadership; stationary anode tube architectures hold the steepest expansion curve.
End User:
Customer type segmentation tracks capital availability against scan volume intensity, with public procurement patterns diverging from private diagnostic networks.
- Hospitals:Radiology departments with fixed infrastructure prioritize output stability and long service intervals. India's PLI scheme for medical devices is redirecting public hospital procurement toward domestically assembled mid-range systems.
- Diagnostic Imaging Centers:Profit-sensitive operators balance equipment utilization rates against maintenance cost predictability. Thailand and Vietnam's aging demographics are expanding geriatric-focused CT fleet investments.
- Emergency Clinics:Point-of-care deployment demands compact tube footprints with rapid thermal recovery. Mobile C-arm compatibility requirements dominate specification priorities.
- Research Labs:Experimental protocols require configurable exposure parameters and specialized target materials. Custom electron gun geometries command premium positioning.
Hospitals dominate absolute unit demand; diagnostic imaging centers are gaining share fastest in emerging economies.
Technology:
Application modality determines anode thermal specifications, with CT-specific architectures facing the most stringent dose optimization pressures.
- X-Ray Computed Tomography:Continuous rotation protocols demand sustained X-ray flux with minimal focal spot drift. FDA diagnostic reference levels are compressing thermal efficiency tolerances across tube substrate designs.
- Digital Radiography:Single-exposure protocols permit lower thermal mass anode configurations. Cost-optimized stationary anode tubes capture strong positioning in general radiography rooms.
- Fluoroscopy:Real-time imaging sequences require rapid anode cooling cycles. Hybrid dielectric oil and forced-air circuits are penetrating mobile C-arm installations.
- Mammography:Soft-tissue contrast optimization drives specialized target materials and filtration geometries. Regulatory compliance with IEC 60601-2-44 governs international market access.
X-ray computed tomography commands the premium tier; fluoroscopy applications are climbing the fastest on mobile system expansion.
Installation:
Deployment mobility shapes thermal management architecture trade-offs and service model economics.
- Fixed Installation:Permanent infrastructure supports liquid-cooled anode substrates with extended continuous duty ratings. Hospital radiology departments concentrate margin pools through long-term service agreements.
- Mobile Installation:Weight-constrained configurations favor forced-air or hybrid cooling circuits. Ambulatory surgical centers and emergency deployment units drive demand for compact tube footprints.
- Permanent Installation:Structural integration with building HVAC systems permits optimized thermal dissipation. Rural diagnostic centers in Indonesia adopt these configurations where infrastructure permits.
- Temporary Installation:Rapid deployment protocols prioritize plug-compatible tube replacement and minimal calibration. Disaster response and military field hospitals specify these architectures.
Fixed installation retains margin concentration; mobile installation is expanding most quickly on point-of-care imaging proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's electron tube manufacturing corridors concentrate critical component supply, while India's health infrastructure schemes and Southeast Asia's aging demographics reshape demand geography. Siemens Healthineers controls flows through Munich and Shanghai facilities. Varex Imaging anchors North American supply from Salt Lake City operations.
China
Domestic manufacturing corridors in Shanghai and Beijing are expanding electron tube production capacity to serve state-funded hospital procurement. The NMPA's GB standards mandate local testing for imported tubes, extending market entry timelines for foreign suppliers without domestic testing partnerships. Yangtze River Delta clusters are capturing margin pools from precision ceramic-metal assembly for high-voltage seals.
India
Government health infrastructure schemes are accelerating hospital procurement of mid-range CT systems with stationary anode configurations across tier-2 and tier-3 cities. The PLI scheme for medical devices redirects public hospital procurement toward domestically assembled systems. Maharashtra and Karnataka diagnostic centers are expanding CT scanner fleets to serve aging urban populations.
United States
The FDA's renewed enforcement of 21 CFR 1020.32 performance standards is tightening thermal specification windows for CT X-ray systems. Diagnostic reference levels for radiation exposure are compressing thermal efficiency tolerances across tube substrate designs. Salt Lake City operations anchor North American supply chain security for critical component flows.
Germany
Munich facilities leverage vertical integration to control critical component flows across European and Asian markets. The EU Medical Device Regulation creates predictable qualification pathways for sealed tube architectures entering multiple member states. Bavaria's precision engineering clusters concentrate vacuum brazing automation capabilities for high-voltage dielectric materials.
Thailand
Diagnostic imaging centers are expanding CT scanner fleets to serve geriatric patient volumes in Bangkok and provincial hubs. Stationary anode tubes match cost-sensitive positioning for these expansion programs. IEC 60601-2-44 harmonization reduces certification friction for tube manufacturers entering Thai procurement channels.
Stationary Anode CT X-Ray Tube Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in thermal management and electron gun fabrication. The vendor base organizes around three structural tiers: diversified imaging system OEMs with captive tube operations, independent tube manufacturers serving replacement markets, and precision materials specialists controlling ceramic-metal seal fabrication. Consolidation pressure concentrates among mid-scale fabricators facing tungsten-rhenium cost volatility. Dominant competitive moves include backward integration into target material supply and strategic partnerships with diagnostic imaging OEMs for co-development of dose-optimized tube architectures.
Among diversified health technology conglomerates, Siemens Healthineers AG and GE Healthcare exemplify platform integrators with captive tube design capabilities. Varex Imaging Corporation occupies a position among independent component suppliers serving multiple OEM channels. Canon Electron Tubes & Devices Co., Ltd represents precision specialists concentrating ceramic-metal assembly expertise for high-voltage seal applications.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Dunlee |
| Varex Imaging Corporation |
| Canon Electron Tubes & Devices Co., Ltd |
| Oxford Instruments |
| IAE Sp.A |
| Comet Group |
| Toshiba Electron Tubes & Devices Co., Ltd |
| GE Healthcare |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta electron tube manufacturing corridors is compressing supplier margins while amplifying pricing power for downstream OEMs with captive sourcing. Utilization rates below 75% in precision ceramic-metal assembly facilities are forcing contract manufacturers to absorb tungsten-rhenium cost volatility rather than pass through input spikes.
Pricing Analysis
FDA 21 CFR 1020.32 dictates the pricing tier structure across sealed tube architectures, with thermal specification windows separating premium-certified configurations from standard economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by IEC 60601-2-44 certification grade and after-sales service bundling. Cost compression in entry-level segments is intensifying because India's PLI scheme redirects public hospital procurement toward domestically assembled mid-range systems. Government hospital networks exhibit the highest price sensitivity, while research labs with captive vacuum technician pools demonstrate the lowest.
Supply Chain Analysis
Canon Electron Tubes & Devices and comparable precision specialists anchor contract-manufacturing capacity for high-voltage ceramic-metal seals. Geographic supply concentrates in China, Germany, and the United States, with Shanghai and Beijing clusters controlling electron gun fabrication and Salt Lake City operations anchoring North American component flows. Raw material dependencies center on tungsten-rhenium alloys from Chinese mining corridors, high-purity copper substrates, and specialized dielectric oils. Single-source vulnerability in tungsten-rhenium processing creates structural exposure to export restriction shocks. Distribution runs through OEM-captive channels for new equipment and independent service organizations for replacement tubes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA diagnostic reference levels are compressing thermal efficiency tolerances across tube architectures, creating a regulatory inflection that rewards manufacturers with dose-optimized anode designs. This technological disruption favors suppliers capable of converging radiation optimization with cooling circuit miniaturization.
For Market Incumbents: Insulate margin pools by deepening backward integration into tungsten-rhenium target material supply and expanding ceramic-metal seal automation capabilities in Bavaria or Yangtze River Delta facilities. Siemens Healthineers and comparable platform integrators face substitution risk from independent tube manufacturers capturing replacement contracts through after-sales service unbundling. Channel control through long-term hospital system partnerships remains the critical defensive lever.
For New Entrants and Emerging Players: Tier-2 and tier-3 cities in India represent the most penetrable geographic white space, with government health infrastructure schemes accelerating procurement of cost-optimized mid-range CT systems. Mobile C-arm configurations for ambulatory surgical centers offer a second entry vector where capital constraints limit rotating anode adoption. A go-to-market angle targeting independent service organizations with plug-compatible replacement tubes bypasses OEM-captive procurement channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision ceramic-metal assembly sub-segments as vacuum brazing automation requirements escalate. Long-term viability over the coming decade hinges on positioning upstream of dose-optimization mandates rather than competing on commoditized tube replacement. Acquisition targets should display captive high-voltage seal fabrication capabilities or established NMPA testing partnerships in Shanghai. The signal to monitor is NMPA local testing mandate enforcement intensity, which would extend market entry timelines for foreign suppliers without domestic infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten-Rhenium Supply | Canon Electron Tubes and comparable specialists secure margin pools from target material cost volatility absorption. |
| NMPA Testing Partnership Establishment | Foreign suppliers with Shanghai or Beijing certification infrastructure reduce regulatory friction for imported tube market entry. |
| Hybrid Thermal System Development | Dielectric oil-forced-air convergence addresses mobile C-arm weight constraints in emergency clinic deployments. |
| Independent Service Organization Channel Cultivation | After-sales unbundling in India's government hospital networks captures replacement tube contracts from OEM-captive models. |
| Dual Carbon Qualification Protocol | Energy efficiency metrics under China's MEE green procurement protocols gain preferential positioning in state-funded tenders. |
Research Methodology
A standing panel of CT system procurement managers, biomedical engineering directors, vacuum technology specialists, and GPO contracts administrators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, NMPA registration databases, hospital procurement contract disclosures, and IEC standard revision drafts. Bottom-up unit demand modeling triangulated against top-down imaging equipment installation forecasts.
Scenario bracketing anchored projections across base, upside, and downside demand trajectories without specifying discrete year markers. Segmentation dimensions spanned product architecture, end-user capital availability, installation mobility requirements, and regional regulatory cluster intensity. CAGRs were derived from installed base replacement cycles converging with new equipment procurement patterns. Industry-specific inputs included tungsten-rhenium alloy price indices and public hospital budget allocation disclosures from India's health infrastructure schemes.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic electron tube manufacturers or sudden NMPA testing mandate enforcement would shift outcomes. Forecasts assume continuity in FDA diagnostic reference level implementation pace and IEC 60601-2-44 harmonization trajectories. Quarterly review of tungsten-rhenium spot pricing, NMPA registration approval velocities, and Indian state-level health infrastructure tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Refurbished Medical Imaging Devices Market