
 Platelet and Plasma Market | 2026-2036
Platelet and Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet and Plasma Market Analysis
Software-defined blood component tracking is realigning how hospitals procure platelet and plasma supplies. Zimmer Biomet leverages its orthopedic implant installed base to bundle PRP kits with surgical hardware. Terumo Corporation anchors Asia-Pacific supply chains through its automated apheresis platform deployments. Stryker competes in the same theater with point-of-care centrifugation systems that reduce cold-chain dependency.
Platelet and plasma comprises blood-derived biologics fractionated through differential centrifugation, with platelet-rich plasma containing four-to-eightfold platelet concentration above baseline whole blood and fresh frozen plasma retaining labile clotting factors at negative eighteen degrees Celsius or below for up to one year. Orthopedic applications command the largest revenue pool as sports medicine protocols drive outpatient consumption, while aesthetic medicine represents the fastest-growing segment as dermatology clinics adopt microneedling combination therapies. Hematology maintains stable transfusion volumes through hospital blood bank contracts.
The FDA governs collection, processing, and labeling under 21 CFR 606 and 640 standards, while the EMA's blood guideline and WHO GMP for blood establishments shape European and developing-market quality benchmarks respectively. Blood banks must navigate divergent pathogen reduction mandates between FDA-approved amotosalen systems and CE-marked riboflavin protocols. Stakeholders should monitor how decentralized point-of-care processing shifts regulatory burden from centralized blood centers to individual hospital pharmacies.
Market Dynamics
Decentralized point-of-care processing is redistributing regulatory burden from centralized blood centers to hospital pharmacies, forcing infrastructure investments at the facility level and altering procurement patterns across orthopedic and aesthetic medicine channels.
Growth Catalysts
- Pathogen reduction mandates:FDA 21 CFR 640 standards and EMA blood guidelines are accelerating adoption of riboflavin and amotosalen systems across hospital blood banks, creating equipment upgrade cycles.
- Sports medicine protocols:Outpatient orthopedic clinics are integrating platelet-rich plasma into pre-operative joint repair workflows, expanding kit consumption beyond traditional transfusion settings.
- Microneedling combination therapies:Dermatology practices are layering PRP with aesthetic procedures, opening new revenue streams outside established hematology channels.
Market Restraints
- Plasma fractionation concentration:Supply chains depend on a limited network of high-volume collection centers, creating geographic vulnerability in rural hospital access.
- Cold-chain infrastructure costs:Fresh frozen plasma storage at negative eighteen degrees Celsius requires specialized freezer capacity that smaller facilities struggle to justify.
- Pathogen reduction protocol divergence:FDA-approved amotosalen systems remain incompatible with CE-marked riboflavin platforms, fragmenting equipment standardization across borders.
Strategic Opportunities
- Point-of-care centrifugation:Portable processing systems enable same-day PRP preparation in outpatient surgical centers, reducing dependency on centralized blood bank logistics.
- Software-defined tracking:Digital chain-of-custody platforms are penetrating hospital inventory management, creating subscription revenue models alongside hardware sales.
- PLI scheme alignment:India's production-linked incentive framework for medical devices is attracting component manufacturing investments that could reshape Asia-Pacific supply geography.
Industry Challenges
- Apheresis technician scarcity:Automated collection platforms require specialized operators, and training pipelines have not kept pace with equipment deployment rates.
- Dual certification timelines:Manufacturers seeking both FDA 510(k) and CE MDR approvals face sequential validation requirements that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet and Plasma Market |
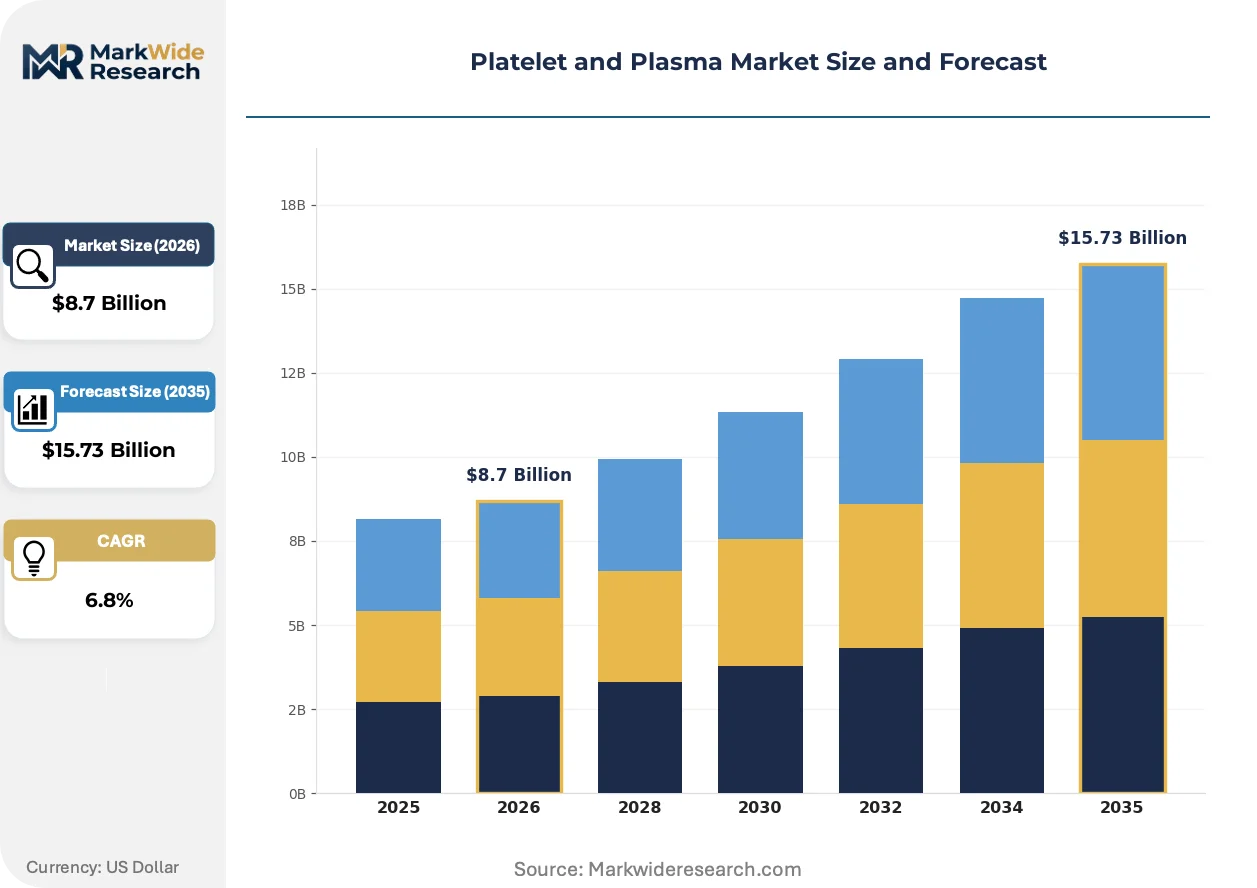
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet Rich Plasma, Platelet Poor Plasma, Fresh Frozen Plasma, Cryoprecipitate Application: Orthopedics, Aesthetic Medicine, Hematology, Cardiology End User: Hospitals, Clinics, Blood Banks, Research Laboratories Delivery Mode: In-Hospital, At-Home, Ambulatory, Emergency Services |
| Companies Covered | EmCyte Corporation, Arthrex Inc., Johnson & Johnson, Zimmer Biomet, Terumo Corporation, Stryker, Dr PRP USA LLC, Juventix Regenerative Medical, Celling Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet and Plasma Market Emerging Trajectories
Processing technology is migrating from centralized blood centers to surgical suites, compressing turnaround times and enabling same-day therapeutic applications that were previously logistically impossible.
Closed-system automated centrifugation is absorbing processing steps previously handled by open-bench laboratory methods. Orthopedic surgery centers in Germany and sports medicine clinics in the United States are adopting these platforms to eliminate cold-chain transport delays. The technology is absorbing margin pressure from blood bank intermediaries by enabling direct patient-specific preparation.
REACH chemical safety standards and the EU Medical Device Regulation are tightening material traceability requirements for plastic consumables used in plasma collection. Manufacturers must now document full polymer supply chains for apheresis kits and storage bags. European blood establishments are responding by consolidating supplier relationships to reduce audit complexity.
Hospital procurement departments are bundling PRP kits with orthopedic implant contracts, mirroring how device manufacturers package surgical hardware. This consolidation favors suppliers with broad product portfolios over standalone blood component vendors. The pattern is most pronounced in North American hospital systems seeking to reduce vendor management overhead through single-source agreements.
Platelet and Plasma Market Segmentation
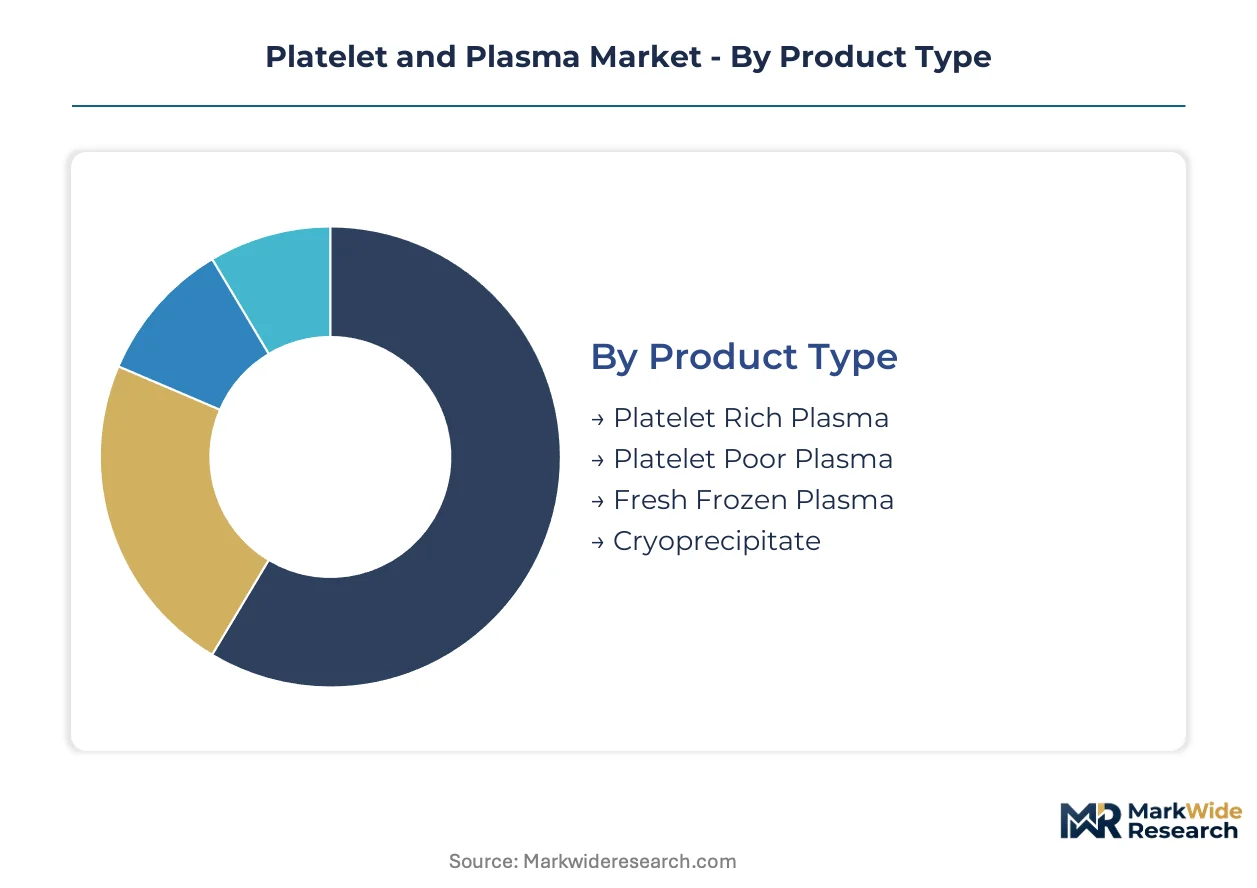
Segmentation in the platelet and plasma market determines capital allocation priorities, as product type dictates centrifugation infrastructure while application focus shapes regulatory compliance investments. Understanding these divisions enables stakeholders to match procurement strategies to specific therapeutic workflows and facility capabilities.
Product Type:
Capital intensity varies sharply across product categories, with fresh frozen plasma requiring the most substantial cold-chain infrastructure investment while point-of-care PRP systems demand lower fixed costs but higher per-unit processing expenses.
- Platelet Rich Plasma:Concentrated platelet suspensions achieve four-to-eightfold enrichment above baseline whole blood through differential centrifugation. Orthopedic surgery centers in Germany and sports medicine clinics across the United States are standardizing PRP protocols for joint repair, driving kit consumption through bundled implant contracts.
- Fresh Frozen Plasma:Labile clotting factors are retained at negative eighteen degrees Celsius or below for up to one year, mandating specialized freezer capacity that constrains adoption at smaller facilities. Hospital blood banks in the United States absorb the largest transfusion volumes as FDA 21 CFR 640 standards tighten collection protocols.
- Platelet Poor Plasma:The depleted supernatant remaining after PRP extraction contains fibrinogen and coagulation factors for specific therapeutic applications.
- Cryoprecipitate:Cold-insoluble precipitate rich in factor VIII and fibrinogen supports hemophilia management and surgical bleeding control.
Fresh frozen plasma absorbs the bulk of installed capacity; platelet rich plasma is expanding most quickly.
Application:
Margin profiles diverge across therapeutic areas, with aesthetic medicine commanding premium pricing per milliliter while hematology maintains stable volumes through contracted transfusion protocols.
- Orthopedics:Pre-operative joint repair workflows integrate PRP injections to reduce post-surgical inflammation and accelerate tissue regeneration. Zimmer Biomet bundles PRP kits with orthopedic hardware to capture recurring consumable revenue alongside implant sales.
- Aesthetic Medicine:Dermatology clinics combine microneedling with PRP application, creating outpatient revenue streams outside traditional hospital channels. Microneedling combination therapies are climbing the fastest as cosmetic procedures bypass insurance reimbursement constraints.
- Hematology:Transfusion-dependent patients rely on consistent platelet and plasma supply through centralized blood bank contracts.
- Cardiology:Cardiac surgery and interventional procedures utilize plasma derivatives for coagulation management during complex interventions.
Orthopedics captures the dominant revenue share; aesthetic medicine is gaining share fastest.
End User:
Procurement sophistication varies by facility type, with blood banks negotiating bulk supply agreements while research laboratories prioritize lot-to-lot consistency over volume discounts.
- Hospitals:Autologous blood processing programs are expanding across North American facilities as the FDA tightens collection and storage protocols. Infrastructure investments in point-of-care centrifugation are redistributing regulatory burden from centralized blood centers to individual hospital pharmacies.
- Blood Banks:High-volume collection centers anchor plasma fractionation supply chains, creating geographic vulnerability in rural hospital access. Pathogen reduction mandates under FDA and EMA guidelines are accelerating equipment upgrade cycles.
- Clinics:Outpatient surgical centers adopt portable processing systems to enable same-day PRP preparation.
- Research Laboratories:Investigational applications require characterized plasma components with documented traceability.
Hospitals command the largest procurement volumes; clinics are expanding most quickly.
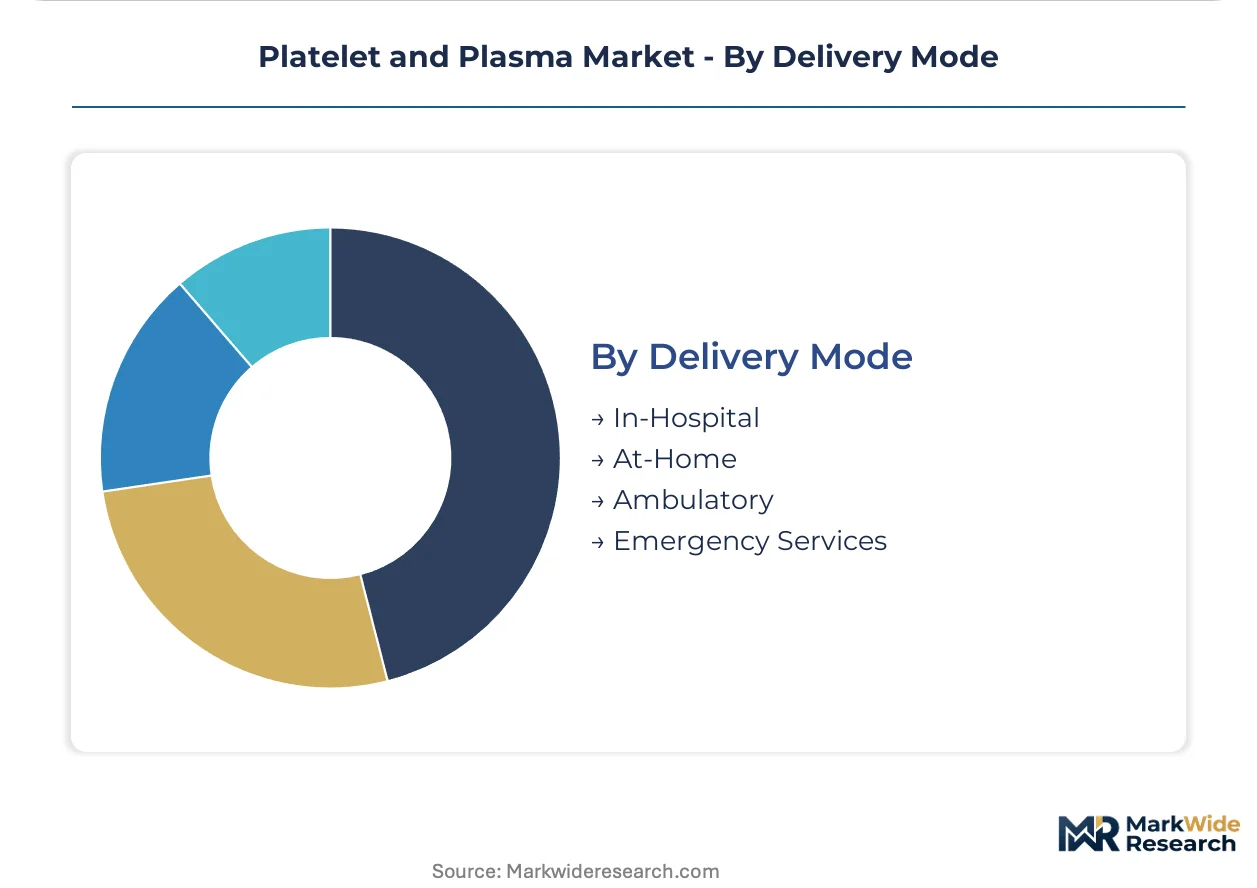
Delivery Mode:
Logistics complexity determines viable service territories, with in-hospital preparation eliminating transport risk while emergency services demand rapid-deployment cold-chain capabilities.
- In-Hospital:Closed-system automated centrifugation absorbs processing steps previously handled by open-bench laboratory methods, compressing turnaround times for same-day therapeutic applications. Terumo Corporation anchors Asia-Pacific supply chains through automated apheresis platform deployments.
- Ambulatory:Stryker competes with point-of-care centrifugation systems that reduce cold-chain dependency for outpatient surgical centers.
- At-Home:Patient-directed administration remains limited by regulatory constraints on self-infusion of blood-derived products.
- Emergency Services:Pre-hospital plasma transfusion protocols require portable thawing and warming equipment for trauma resuscitation.
In-hospital delivery dominates current infrastructure; ambulatory channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's concentration of orthopedic surgery centers anchors European platelet-rich plasma demand, with Germany's Rhineland corridor hosting the continent's densest cluster of sports medicine facilities processing autologous blood components.
United States
Outpatient surgical centers in Florida and Arizona are expanding point-of-care centrifugation capacity to serve aging populations seeking joint preservation alternatives. FDA 21 CFR 640 standards are tightening collection protocols across hospital blood banks, forcing infrastructure upgrades at the facility level. The Dallas-Fort Worth metroplex hosts the largest concentration of independent plasma collection centers, creating supply chain gravity that rural hospitals must navigate.
Germany
Orthopedic surgery centers in Munich and Hamburg have standardized PRP protocols as pre-operative practice for knee and shoulder repair. EMA blood guidelines and REACH chemical safety standards are tightening material traceability for plastic consumables used in apheresis kits. The Baden-Württemberg region anchors automated processing equipment manufacturing, with Stuttgart-area firms supplying centrifugation platforms across European blood establishments.
Japan
Aging demographics are expanding transfusion-dependent patient volumes in Tokyo and Osaka metropolitan hospitals. PMDA regulations govern blood product manufacturing standards, with METI industrial policy supporting domestic apheresis platform development. The Nagoya industrial corridor concentrates precision centrifuge component fabrication, feeding both domestic demand and Asia-Pacific export markets.
India
Private hospital chains in Mumbai and Delhi are importing automated apheresis platforms to reduce dependency on manual processing methods. The PLI scheme for medical devices is attracting component manufacturing investments that could reshape regional supply geography. Hyderabad's life sciences cluster is emerging as a contract manufacturing hub for blood collection consumables serving Middle Eastern and African markets.
Australia
TGA regulations mandate pathogen reduction for all platelet components, accelerating riboflavin system adoption across Melbourne and Sydney blood services. The country's remote hospital network is piloting portable thawing equipment for pre-hospital plasma transfusion in trauma cases. Perth's isolation is driving investment in decentralized processing capacity to reduce cold-chain transport vulnerability across Western Australia.
Platelet and Plasma Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the platelet and plasma supply chain, with automated apheresis platform manufacturers absorbing the bulk of fixed asset deployment while kit and consumable specialists operate with leaner balance sheets. The market structures around three tiers: diversified orthopedic conglomerates bundling PRP with implant hardware, dedicated blood technology firms anchoring automated collection infrastructure, and regional consumable suppliers serving fragmented clinic networks. Consolidation pressure is concentrating procurement decisions into fewer hospital system administrators, while technology licensing agreements are spreading processing capabilities beyond traditional blood bank boundaries.
Within the diversified orthopedic tier, Zimmer Biomet and Stryker exemplify platform strategies that capture recurring consumable revenue alongside capital equipment placement. Terumo Corporation anchors the dedicated blood technology segment, representing Japanese precision manufacturing in automated apheresis systems. Dr PRP USA LLC occupies a position among specialized kit suppliers targeting outpatient surgical centers with simplified preparation workflows.
| Leading Market Players |
|---|
| EmCyte Corporation |
| Arthrex Inc. |
| Johnson & Johnson |
| Zimmer Biomet |
| Terumo Corporation |
| Stryker |
| Dr PRP USA LLC |
| Juventix Regenerative Medical |
| Celling Biosciences |
| Others |
Supply Flow & Price Mechanics
Backward integration into automated centrifugation manufacturing anchors supply positions for diversified orthopedic conglomerates while simultaneously compressing per-unit margins for standalone kit suppliers dependent on contract manufacturing relationships.
Pricing Analysis
Cost-down pressure on consumable tiers accelerates because hospital procurement departments are bundling PRP kits with orthopedic implant contracts to reduce vendor management overhead. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated systems from CE-marked alternatives and unregulated clinic-grade preparations. Price differentiation traces to certification tier and after-sales service bundling, with ISO 13485-certified manufacturers commanding sustained premiums. Smaller outpatient surgical centers exhibit highest price sensitivity, while integrated hospital systems prioritize total cost of ownership over per-unit kit pricing.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-supplier qualification for apheresis platforms and plastic consumables alike. Manufacturing concentrates in Germany, Japan, and the United States, with Stuttgart-area firms supplying centrifugation platforms and Nagoya's precision component fabricators feeding Asia-Pacific export markets. Raw material dependencies span medical-grade polymers, precision bearings, and pathogen reduction reagents. Single-source vulnerability concentrates in riboflavin and amotosalen system supply, where FDA and EMA protocol divergence fragments equipment standardization. Distribution runs through hospital system GPO contracts and blood bank cooperative purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum favors manufacturers capturing both apheresis platform revenue and recurring consumable streams, with control over precision centrifuge component fabrication emerging as the decisive upstream lever.
For Market Incumbents: Deploy software-defined tracking capabilities to lock in hospital pharmacy subscriptions alongside hardware placements. Consolidate supplier relationships to reduce REACH audit complexity for European blood establishments. Defend against point-of-care centrifugation entrants by embedding closed-system automation deeper into orthopedic surgery workflows. For New Entrants and Emerging Players: The premium-economy price gap in aesthetic medicine creates entry space for simplified PRP preparation workflows targeting dermatology clinics outside traditional hospital channels. Microneedling combination therapies represent the most penetrable application segment, bypassing insurance reimbursement constraints that constrain hematology adoption. Pursue direct-to-clinic distribution models that circumvent blood bank intermediary margins. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic conglomerates seeking bundled implant-consumable revenue streams. Long-term viability hinges on regulatory certification breadth across FDA, CE MDR, and PMDA jurisdictions. Watch pathogen reduction protocol convergence between FDA and EMA standards as the inflection indicator for equipment standardization and margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Centrifugation Deployment | Stryker and Terumo systems reduce cold-chain dependency for outpatient surgical centers. |
| Software Companion Development | Digital chain-of-custody platforms create recurring subscription revenue alongside hardware sales. |
| CE Marking Pathway Investment | EMA blood guideline compliance opens European orthopedic surgery center procurement channels. |
| Hospital System Partnership | Zimmer Biomet bundles PRP kits with implant contracts to capture recurring consumable revenue. |
| Reimbursement Strategy | Aesthetic medicine protocols bypass insurance constraints through direct patient payment models. |
Methodological Framework
Document review covered FDA 21 CFR filings, EMA blood guideline updates, and hospital procurement database records, complemented by interviews with blood bank operations directors, orthopedic surgery center administrators, apheresis platform engineers, and GPO contracts managers. Secondary validation drew from SEC 10-K disclosures of listed manufacturers, WHO GMP for blood establishments documentation, and trade data for medical device imports. Bottom-up facility-level capacity estimates were triangulated against top-down market sizing from centralized blood center throughput data.
Cross-referencing historical growth patterns with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application focus, end-user facility category, and delivery mode complexity. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and equipment replacement cycle timing. Pathogen reduction mandate compliance costs and point-of-care processing adoption curves served as blood industry-specific forecast inputs.
Inputs from hospital procurement committees and blood establishment operators were available through the study window; gaps in real-time pricing data from private clinic transactions introduce uncertainty bands around aesthetic medicine segment estimates. Deviation in FDA-EMA pathogen reduction protocol harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Breast Shells Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
Swab Cups Market