
 US Plasma Fractionation Market | 2026-2036
US Plasma Fractionation Market Size, Share, and Industry Trends Forecast 2026-2036
US Plasma Fractionation Market Insights
Academic medical centers is rotating toward higher-volume plasma product contracts as community hospitals consolidate purchasing. CSL Behring leverages its vertically integrated collection-to-finished-product network across the US. Grifols sustains position through specialized hyperimmune globulin manufacturing. Octapharma anchors its US presence with large-scale albumin and factor concentrates production.
Plasma fractionation separates blood plasma into therapeutic proteins through cold ethanol precipitation and chromatographic purification, yielding albumin, immunoglobulins, and coagulation factors for critical care and chronic disease management. The immunoglobulin segment dominates value generation due to expanding neurology and immunology indications. Coagulation factors command premium positioning within hemophilia treatment protocols. Albumin remains a mature volume category with pricing pressure from hospital formularies.
FDA's plasma donor deferral policies and Current Good Manufacturing Practice standards govern collection volume and product release timelines, directly constraining supply elasticity. The Department of Health and Human Services oversees national blood policy coordination with the national blood supply. OSHA workplace exposure limits affect plasma center staffing costs. Stakeholders must monitor FDA's pathogen reduction technology guidance as it reshapes manufacturing investment priorities.
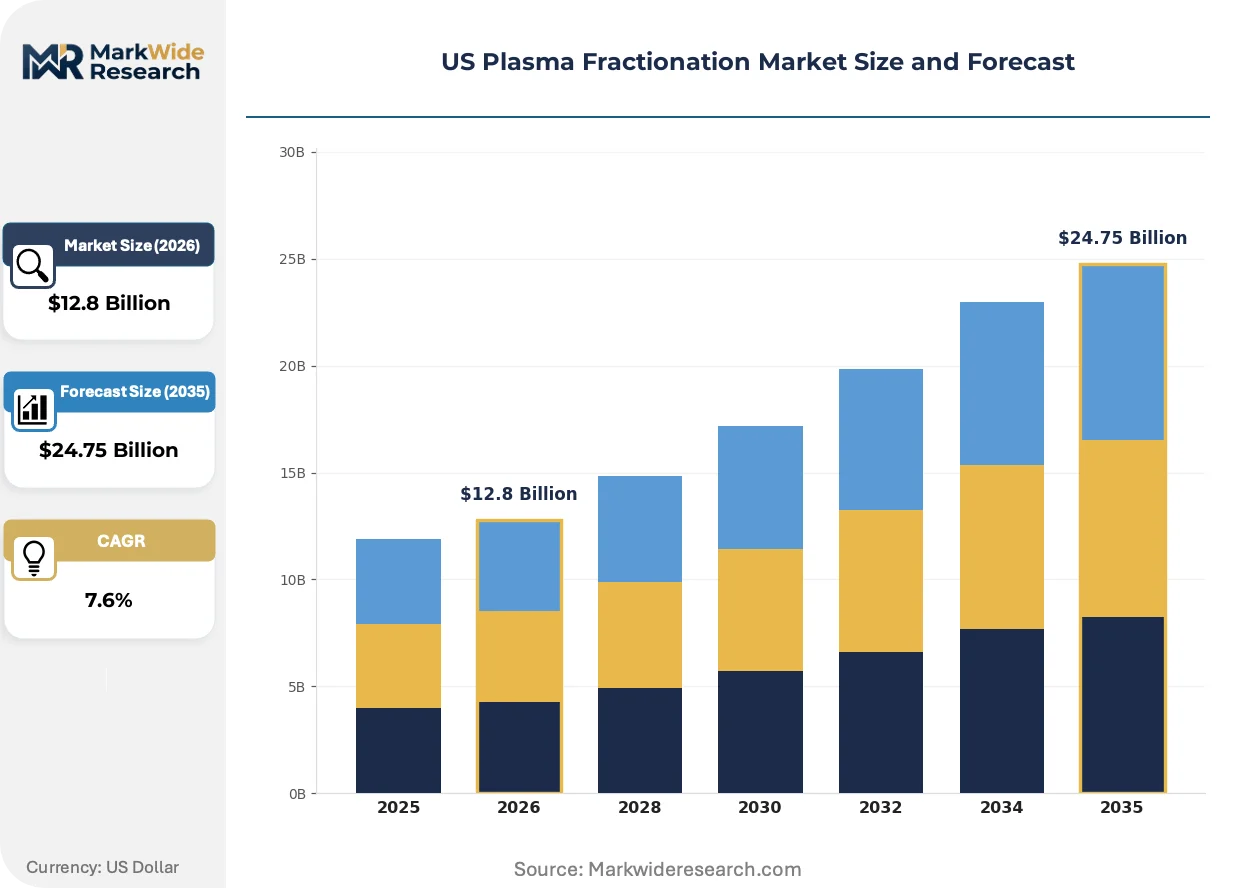
Market Dynamics
FDA's updated donor deferral protocols are compressing collection throughput while immunoglobulin demand from neurology centers accelerates, creating supply-demand asymmetry that reshapes competitive positioning across the value chain.
Growth Catalysts
- Chronic disease burden:Rising prevalence of primary immunodeficiency disorders and autoimmune neuropathies is expanding the addressable patient base for immunoglobulin therapies. Academic medical centers in Texas and Florida are scaling infusion center capacity.
- Fractionation yield improvements:Chromatographic purification advances are extracting higher immunoglobulin concentrations per liter of plasma input. CSL Plasma's Texas collection infrastructure is capturing volume efficiencies from process automation.
- OSHA compliance investments:Workplace safety mandates for plasma center operations are standardizing staffing protocols and reducing donor attrition. Collection facilities are extending operating hours to maximize throughput per location.
Market Restraints
- Donor pool limitations:FDA's permanent deferral for certain risk categories and geographic exposure history restricts eligible donor demographics. Collection centers face ceiling effects on per-site volume expansion.
- Plasma input cost volatility:Source plasma acquisition costs fluctuate with donor compensation competition between CSL Plasma, Grifols, and Octapharma collection networks. Margins compress when recruitment intensity escalates.
- Manufacturing scale barriers:Cold ethanol precipitation infrastructure requires capital-intensive bioprocessing facilities with multi-year construction timelines. New entrant capacity addition remains structurally constrained.
Strategic Opportunities
- Subcutaneous immunoglobulin formats:Home administration protocols are reducing infusion center dependency and expanding patient convenience. Neurology practices in California and New York are piloting self-instruction programs.
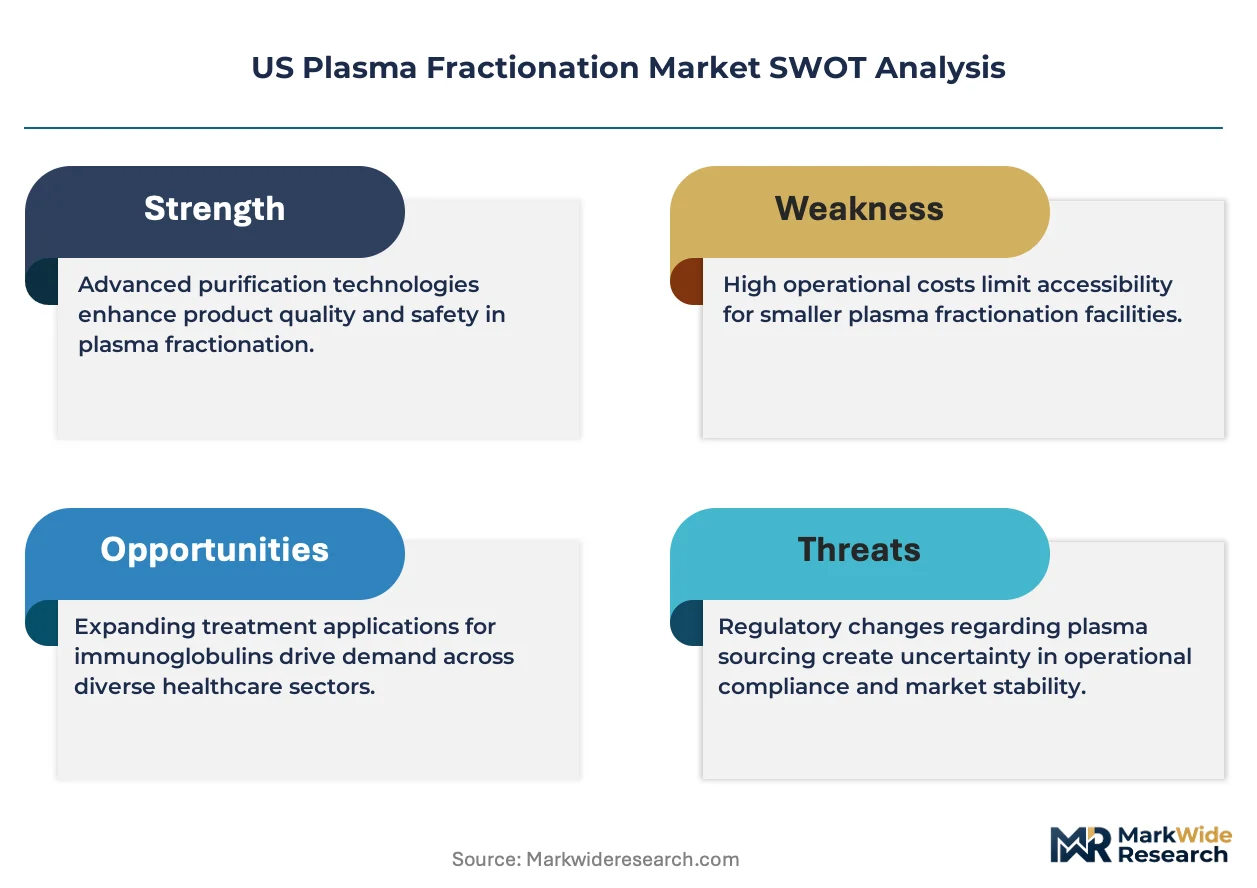
- Pathogen reduction technology:FDA guidance on solvent-detergent and nanofiltration methods is creating compliance-driven upgrade cycles. Fractionators investing early capture premium positioning in hospital formularies.
- Hyperimmune globulin specialization:Targeted antibody products for transplant and infectious disease applications command pricing premiums. Grifols' manufacturing focus in this category demonstrates viable differentiation.
Industry Challenges
- Bioprocessing talent scarcity:Plasma fractionation requires specialized expertise in protein chemistry and viral inactivation. The US faces competition for skilled technicians from biologics and cell therapy sectors.
- Legacy quality system integration:FDA's evolving Current Good Manufacturing Practice standards necessitate continuous validation documentation. Facilities with dated electronic batch records face compliance remediation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Plasma Fractionation Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Albumin, Immunoglobulins, Coagulation Factors, Fibrinogen, Protease Inhibitors Application: Immunodeficiency Disorders, Hemophilia, Burns Treatment, Liver Disease, Autoimmune Conditions End User: Specialty Clinics, Diagnostic Laboratories, Research Institutes, Blood Banks Distribution Channel: Direct Sales, Wholesale Distributors, Hospital Pharmacies, Online Healthcare Portals |
| Companies Covered | CSL Behring, Grifols, Octapharma, Takeda Pharmaceutical, Kedrion Biopharma, Baxter International, CSL Plasma, BPL, ADMA Biologics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Plasma Fractionation Market Trends and Innovations
Technology convergence between automated collection systems and real-time donor health monitoring is compressing collection cycle times while improving plasma quality consistency. These advances are reshaping how fractionators secure input supply.
Capillary blood collection devices for immunoglobulin level screening are miniaturizing pre-treatment diagnostic workflows. Community-based specialty pharmacies in Arizona and Colorado are deploying point-of-care testing to accelerate therapy initiation. This decentralization is reducing the lag between diagnosis and first infusion, compressing the traditional referral pathway.
FDA's pathogen reduction technology guidance is mandating enhanced viral inactivation steps for immunoglobulin products. Fractionators must validate solvent-detergent or nanofiltration methods prior to product release. Academic medical centers in Massachusetts and Pennsylvania are updating procurement specifications to favor manufacturers with demonstrated compliance.
Hospital formulary committees are consolidating plasma product contracts around fewer suppliers with vertically integrated collection networks. Large health systems in Texas and Illinois are negotiating multi-year agreements that bundle albumin, immunoglobulin, and factor concentrates. This concentration is displacing fragmented purchasing across individual hospital pharmacies and compressing vendor rosters to three or fewer approved suppliers per system.
US Plasma Fractionation Market Segmentation
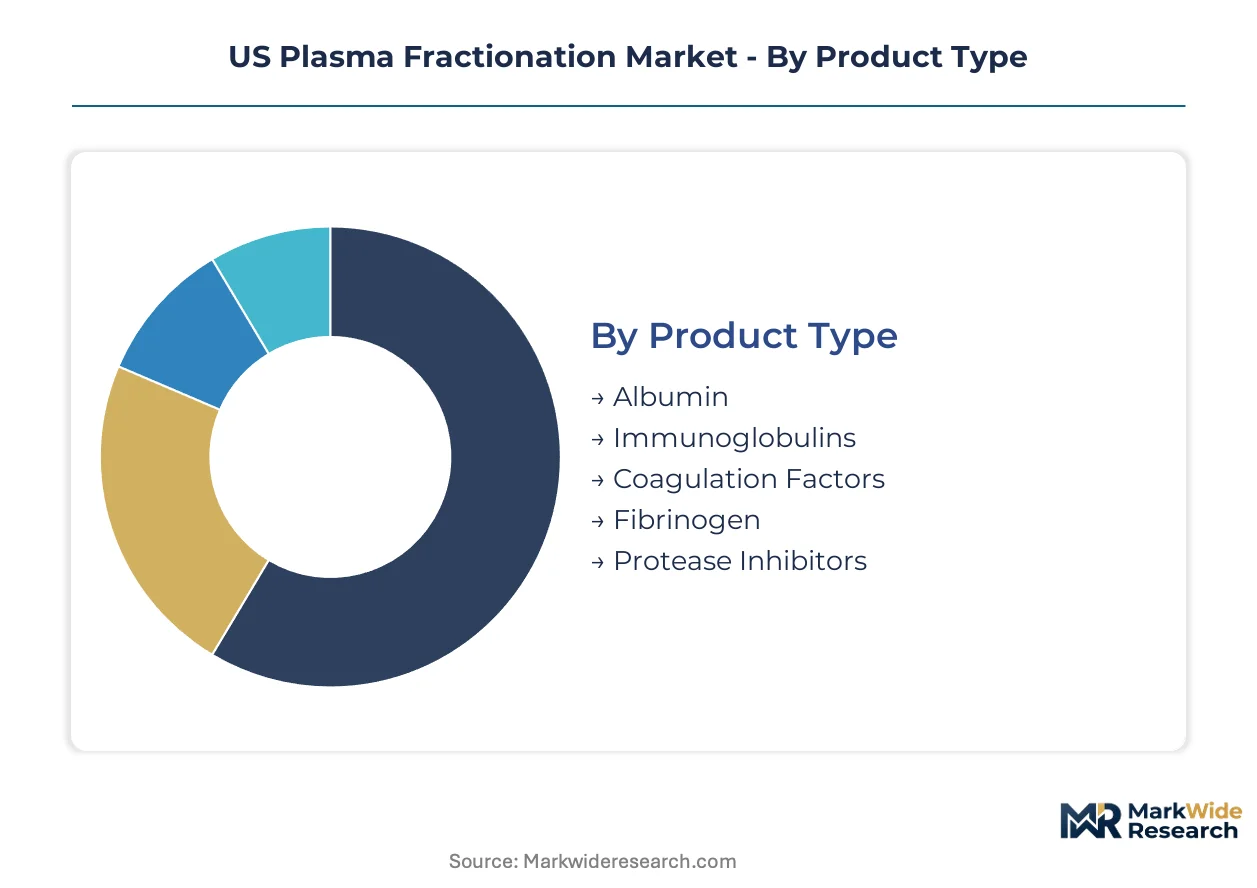
Segmentation in the US plasma fractionation market reveals how therapeutic protein categories, clinical applications, and procurement channels concentrate value differently. Understanding these fault lines exposes where substitution threats and supply bottlenecks reshape competitive dynamics.
Product Type:
Substitution pressure from recombinant alternatives and biosimilar competition varies sharply across protein categories, with some segments facing imminent displacement while others retain biological necessity.
- Immunoglobulins:Polyclonal antibody preparations derived from pooled plasma provide passive immunity for primary immunodeficiency and neurological autoimmune conditions. Texas academic medical centers are expanding infusion capacity for neurology indications as off-label use accelerates.
- Albumin:Human serum albumin maintains oncotic pressure in critical care settings and serves as a drug carrier protein. Hospital formularies in Illinois and California are tightening utilization protocols amid pricing pressure from synthetic colloid alternatives.
- Coagulation Factors:Factor VIII and Factor IX concentrates enable hemophilia prophylaxis; recombinant versions now dominate hemophilia A while plasma-derived retains share in hemophilia B and inhibitor patients.
- Fibrinogen:Clotting factor concentrate used in massive hemorrhage and congenital deficiencies; perioperative demand concentrates at trauma centers in Pennsylvania and Ohio.
- Protease Inhibitors:Alpha-1 antitrypsin and C1 esterase inhibitor products address rare genetic conditions; specialty pharmacy distribution in Florida and Arizona supports home infusion programs.
Albumin retains volume leadership; immunoglobulins hold the steepest expansion curve.
Application:
Cost tier stratification separates chronic maintenance therapies from acute rescue interventions, with reimbursement intensity tracking clinical urgency and treatment duration.
- Immunodeficiency Disorders:Primary immunodeficiency requires lifelong immunoglobulin replacement; subcutaneous administration formats are reducing infusion center dependency in New York and Massachusetts.
- Hemophilia:Plasma-derived factor concentrates serve inhibitor patients and those with allergic reactions to recombinant products; comprehensive care centers in Texas and California anchor demand concentration.
- Burns Treatment:Albumin resuscitation protocols in major burn units; military medical centers and civilian trauma networks in Maryland and Texas drive procurement specifications.
- Liver Disease:Albumin for ascites and hepatorenal syndrome; transplant centers in Florida and Illinois influence product selection through bundled contracting.
- Autoimmune Conditions:Immunoglobulin for CIDP, myasthenia gravis, and dermatomyositis; neurology practices in Pennsylvania and Ohio are expanding self-administration training programs.
Hemophilia commands premium pricing tiers; immunodeficiency applications are gaining share fastest.
End User:
Customer type fragmentation creates divergent procurement patterns, with institutional scale determining contract structure and supplier consolidation intensity.
- Specialty Clinics:Infusion centers for immunoglobulin and rare disease therapies; independent neurology and immunology practices in Arizona and Colorado are consolidating into multi-site networks.
- Diagnostic Laboratories:Control materials and calibrators for coagulation and protein assays; reference laboratories in North Carolina and California standardize on specific fractionator product lines.
- Research Institutes:Cell culture media supplements and experimental therapeutics; NIH-funded centers in Maryland and Massachusetts drive specification requirements.
- Blood Banks:Albumin and coagulation factors for transfusion support; regional blood centers in Texas and Illinois coordinate with fractionators on inventory management.
Specialty clinics concentrate revenue contribution; research institutes are expanding most quickly.
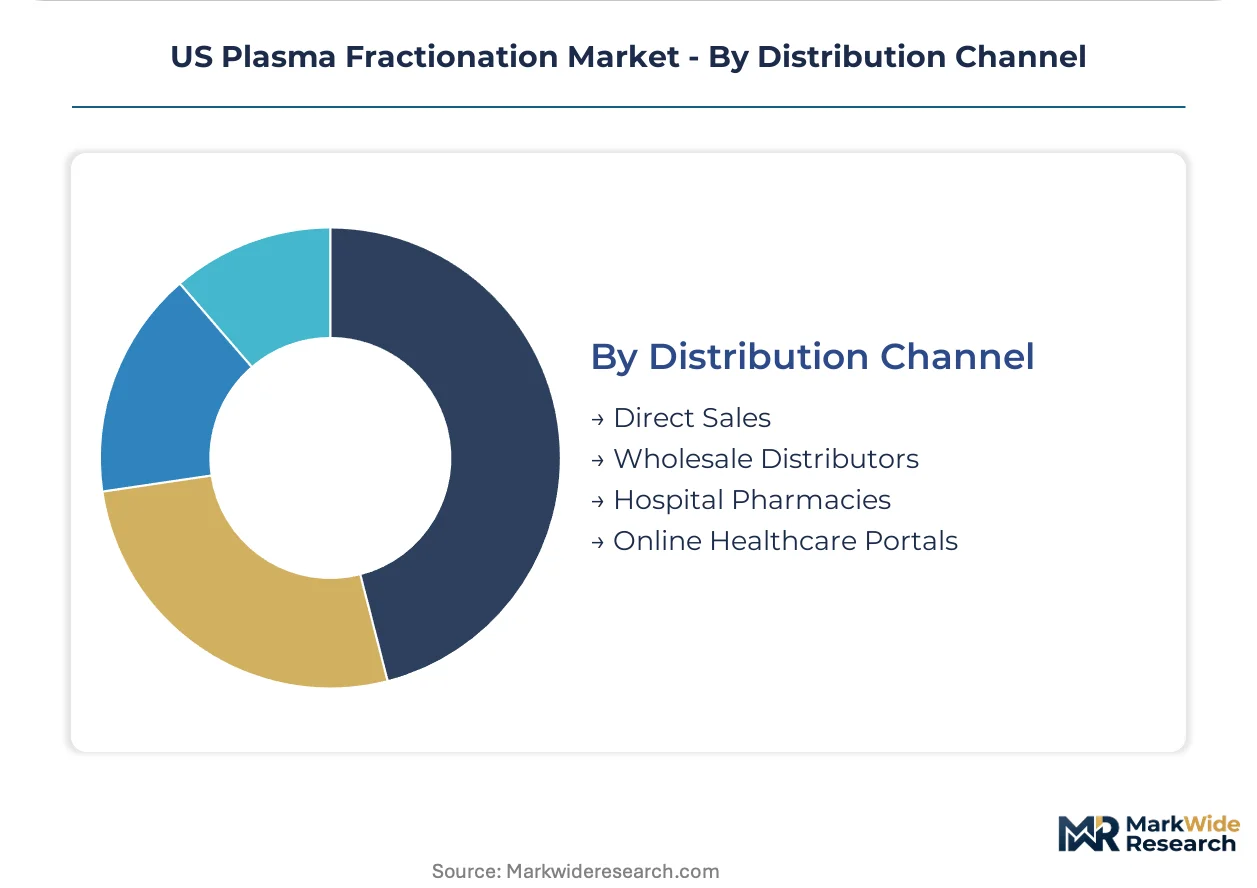
Distribution Channel:
Supply concentration in vertically integrated networks is compressing intermediary roles and favoring direct manufacturer-to-provider relationships.
- Direct Sales:Manufacturer contracts with large health systems and specialty pharmacies; CSL Behring and Grifols field organizations in Texas and Florida manage key account relationships directly.
- Wholesale Distributors:McKesson, AmerisourceBergen, and Cardinal Health maintain cold chain infrastructure for hospital and pharmacy customers across the Midwest and Southeast.
- Hospital Pharmacies:In-house procurement for emergency and surgical albumin use; formulary committees in Illinois and Pennsylvania are narrowing approved vendor lists.
- Online Healthcare Portals:Emerging channel for home infusion supplies and patient support materials; specialty pharmacies in California and New York are piloting digital prescription management.
Wholesale distributors retain volume leadership; direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interstate highway networks and cold-chain logistics corridors linking Texas collection centers to coastal manufacturing hubs anchor the US plasma fractionation infrastructure. Federal plasma transport regulations and state-level health facility licensing create a patchwork of operational requirements. Demand concentrates in three distinct regional clusters with divergent clinical priorities and procurement patterns.
Texas
CSL Plasma operates the nation's densest collection center network across Dallas-Fort Worth, Houston, and San Antonio metro corridors. FDA's donor deferral protocols and state health department facility inspections govern site licensing renewals. Academic medical centers in Houston and Dallas are expanding neurology infusion capacity for off-label immunoglobulin applications.
California
Specialty pharmacies in Los Angeles and San Francisco Bay Area pilot subcutaneous immunoglobulin home administration programs. OSHA workplace exposure standards and California OSHA's supplemental plasma center safety requirements elevate staffing costs. Research institutes at Stanford and UC San Francisco drive demand for albumin in cell culture media applications.
Illinois
Chicago-based health systems negotiate bundled plasma product contracts covering albumin, immunoglobulin, and factor concentrates. The Department of Health and Human Services coordinates regional blood policy with Illinois public health authorities. Hospital formulary committees at Northwestern Medicine and Rush University Medical Center are narrowing approved vendor lists to vertically integrated suppliers.
Pennsylvania
Comprehensive hemophilia treatment centers in Philadelphia and Pittsburgh anchor coagulation factor demand. FDA's Current Good Manufacturing Practice standards govern product release timelines for fractionators supplying the region. Neurology practices at University of Pennsylvania Health System are expanding self-administration training programs for chronic inflammatory demyelinating polyneuropathy patients.
Florida
Transplant centers in Miami and Tampa drive hyperimmune globulin procurement for cytomegalovirus prophylaxis protocols. State health facility licensing and Medicare reimbursement rates shape specialty clinic economics. Independent immunology practices in Orlando and Jacksonville are consolidating into multi-site networks to negotiate direct manufacturer contracts.
US Plasma Fractionation Market Competitive Landscape
Listed leaders compete with private specialists across collection network scale and therapeutic protein specialization. The market structure concentrates around three vertically integrated fractionators controlling upstream plasma supply and downstream finished-product distribution. Strategic archetypes separate collection-scale operators, hyperimmune globulin specialists, and recombinant-alternative diversifiers. Dominant competitive moves include backward integration into plasma collection networks and pathogen reduction technology licensing.
Within the vertically integrated tier, CSL Behring exemplifies collection-to-finished-product network control. Grifols occupies a position representing hyperimmune globulin manufacturing specialization. Octapharma anchors the large-scale albumin and factor concentrate production archetype. These three entities collectively represent the structural pattern of US plasma fractionation competition.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Octapharma |
| Takeda Pharmaceutical |
| Kedrion Biopharma |
| Baxter International |
| CSL Plasma |
| BPL |
| ADMA Biologics |
| Others |
Pricing and Supply Chain Analysis
CSL Plasma's Texas collection network achieves throughput economies that compress per-liter plasma acquisition costs below regional competitors, establishing price floors that fractionators without captive supply cannot match. This scale concentration simultaneously tightens margins for independent collection centers and elevates bargaining power for vertically integrated manufacturers in hospital contract negotiations.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with large health systems securing preferential immunoglobulin rates through multi-year albumin-factor bundles. Price differentiation rests on FDA Current Good Manufacturing Practice certification tiers and cold-chain reliability guarantees, with academic medical centers least sensitive and community hospitals most responsive to per-unit cost shifts. Pricing pressure stems from recombinant factor VIII substitution in hemophilia A, compressing plasma-derived factor premiums.
Supply Chain Analysis
Plasma inventory cycles run 7-12 months from collection to finished-product release, creating working capital intensity that favors deep-pocketed operators. Supply concentrates in the United States, with Austria and Switzerland anchoring European fractionation capacity for US import. Raw material dependencies center on source plasma volumes, chromatography resins, and solvent-detergent viral inactivation reagents. Single-source vulnerability permeates the collection network tier, where CSL Plasma, Grifols, and Octapharma control site access. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health cold-chain infrastructure to hospital and specialty pharmacy endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home infusion services and patient training programs represent the fastest-expanding recurring-revenue layer, outpacing hardware-equivalent product sales as subcutaneous immunoglobulin formats displace intravenous protocols.
For Market Incumbents: Secure captive plasma supply through collection center automation investments in Texas and Florida, defending against margin compression from donor compensation wars. Reinforce hospital formulary positioning by bundling pathogen reduction technology compliance into standard contract terms, creating switching costs for procurement committees evaluating alternative suppliers. For New Entrants and Emerging Players: Anchor in hyperimmune globulin specialization for transplant and infectious disease niches, where Grifols' manufacturing focus has demonstrated viable pricing premiums. Target independent immunology practices consolidating into multi-site networks in Arizona and Colorado, offering direct manufacturer contracts that bypass wholesale distributor markups. For Investors and Strategic Acquirers: Regional blood centers with FDA-licensed collection infrastructure and underutilized fractionation capacity represent the priority acquisition archetype for platform roll-up strategies. Monitor FDA pathogen reduction technology guidance compliance timelines as the inflection signal separating upgrade-ready assets from stranded legacy facilities requiring remediation capital.| Strategic Initiative | Industry Significance |
|---|---|
| Collection Network Automation | CSL Plasma's Texas infrastructure demonstrates throughput gains from robotic donor screening and automated plasmapheresis systems. |
| Pathogen Reduction Technology Licensing | Solvent-detergent and nanofiltration validation captures premium formulary positioning at Massachusetts and Pennsylvania academic medical centers. |
| Subcutaneous Format Development | Home administration protocols reduce infusion center dependency and expand addressable patient base in California and New York neurology practices. |
| Hyperimmune Globulin Manufacturing Scale-Up | Targeted antibody products for CMV prophylaxis command pricing premiums at Florida and Illinois transplant centers. |
| Specialty Pharmacy Direct Contracts | Bypassing wholesale distributors compresses channel costs and deepens patient adherence data capture for payor negotiations. |
Research Methodology
Operator-level perspectives from plasma center operations directors, FDA regulatory affairs leads, hospital formulary committee chairs, and specialty pharmacy procurement managers anchored the qualitative base. Secondary validation drew from FDA 483 inspection observations, CMS Medicare reimbursement databases, American Society for Apheresis clinical guidelines, and SEC 10-K filings from publicly traded fractionators. Bottom-up plasma volume modeling and top-down therapeutic protein demand estimation were triangulated against collection center throughput data.
Sensitivity analysis tested donor deferral policy scenarios and recombinant substitution rates across the projection horizon. Segmentation dimensions spanned product type, application, end user, and distribution channel, with regional regulatory cluster effects modeled separately. CAGRs were derived from plasma input volume trajectories and yield-per-liter improvement curves, cross-referenced against hospital formulary contract renewal cycles and specialty clinic expansion plans.
Material uncertainties — FDA donor screening protocol revisions, pathogen reduction technology mandate timing, and recombinant hemophilia product substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these regulatory and competitive dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Global Anti-Neoplastic Agents Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Orphan Drugs Market