
 Asia-Pacific Insulin Syringe Market | 2026-2036
Asia-Pacific Insulin Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insulin Syringe Market Outlook
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is bifurcating the Asia-Pacific insulin syringe landscape. Becton Dickinson leverages captive needle-forming and barrel-molding capacity to sustain margin control across high-volume safety syringe output. Terumo Corporation anchors its position through precision grinding technology for ultra-fine needles, while Nipro Corporation specializes in polypropylene barrel formulations for cost-sensitive institutional tenders.
An insulin syringe is a calibrated single-use or limited-use injection device comprising a graduated barrel, elastomer plunger, and attached hypodermic needle, typically manufactured through injection molding of medical-grade polymers followed by needle bonding and siliconization to ensure plunger glide consistency; its primary purpose is to deliver precise insulin dosages subcutaneously for glycemic management. The safety syringe segment leads value generation due to needlestick prevention mandates in hospital systems across Japan, Australia, and South Korea, while the smart technology tier represents the fastest structural expansion as connected dose-logging features penetrate premium homecare channels. Polypropylene dominates material selection for disposable units, though glass-barrel reusable designs retain niche share in India's government procurement programs where sterilization infrastructure supports circular use models.
Japan's PMDA enforces stringent biocompatibility and sterility assurance standards that elevate compliance costs for imported devices, while Australia's TGA alignment with EU MDR technical documentation requirements streamlines market access for CE-marked manufacturers. India's CDSCO medical device rules, recently expanded under the Drugs and Cosmetics Act framework, mandate registration and quality audits that are reshaping supplier qualification timelines for domestic tenders. Stakeholders must monitor how China's NMPA accelerated review pathways for innovative diabetes devices interact with provincial centralized procurement price ceilings to determine viable entry strategies.
Market Dynamics
Provincial centralized procurement in China is compressing unit economics while simultaneously accelerating volume consolidation toward safety-engineered and connected device platforms across hospital networks.
Growth Catalysts
- Japan's needlestick prevention mandates:PMDA-enforced safety syringe requirements in tertiary hospitals are displacing conventional designs and elevating compliance-driven replacement cycles.
- India's PLI scheme for medical devices:Domestic manufacturing incentives under CDSCO oversight are shortening import dependency for barrel-molding capacity and polypropylene feedstock conversion.
- Connected dose-logging platforms:Bluetooth-enabled syringes with timestamp capture are penetrating premium homecare channels in Australia's private diabetes management networks.
Market Restraints
- Medical-grade polymer cost volatility:Polypropylene resin price swings tied to naphtha cracking margins in Northeast Asian petrochemical clusters are squeezing disposable unit margins.
- Single-source needle grinding equipment:Precision lapping machinery for 31G ultra-fine needles concentrates among Japanese and Swiss equipment builders, creating supply bottleneck risk.
- Siliconization chemistry constraints:Dimethicone coating consistency requirements for plunger glide performance limit alternative material substitution in high-volume safety syringe output.
Strategic Opportunities
- Vietnam's underpenetrated provincial hospital tier:District-level diabetes clinics outside Ho Chi Minh City and Hanoi lack consistent safety syringe supply, creating first-mover whitespace for compliant manufacturers.
- Reusable glass-barrel tenders:India's government procurement programs supporting sterilization infrastructure offer circular-economy positioning against disposable dominance.
- TGA-CE alignment pathway:Australia's technical documentation convergence with EU MDR streamlines dual-market qualification for manufacturers targeting both Pacific and European hospital systems.
Industry Challenges
- Biocompatibility testing backlog:PMDA's cytotoxicity and sensitization assay queues are extending product registration timelines for novel elastomer plunger formulations.
- Legacy sterilization facility requalification:Ethylene oxide chamber upgrades to meet residual gas limits are forcing capital redeployment among contract sterilization providers serving Australian distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insulin Syringe Market |
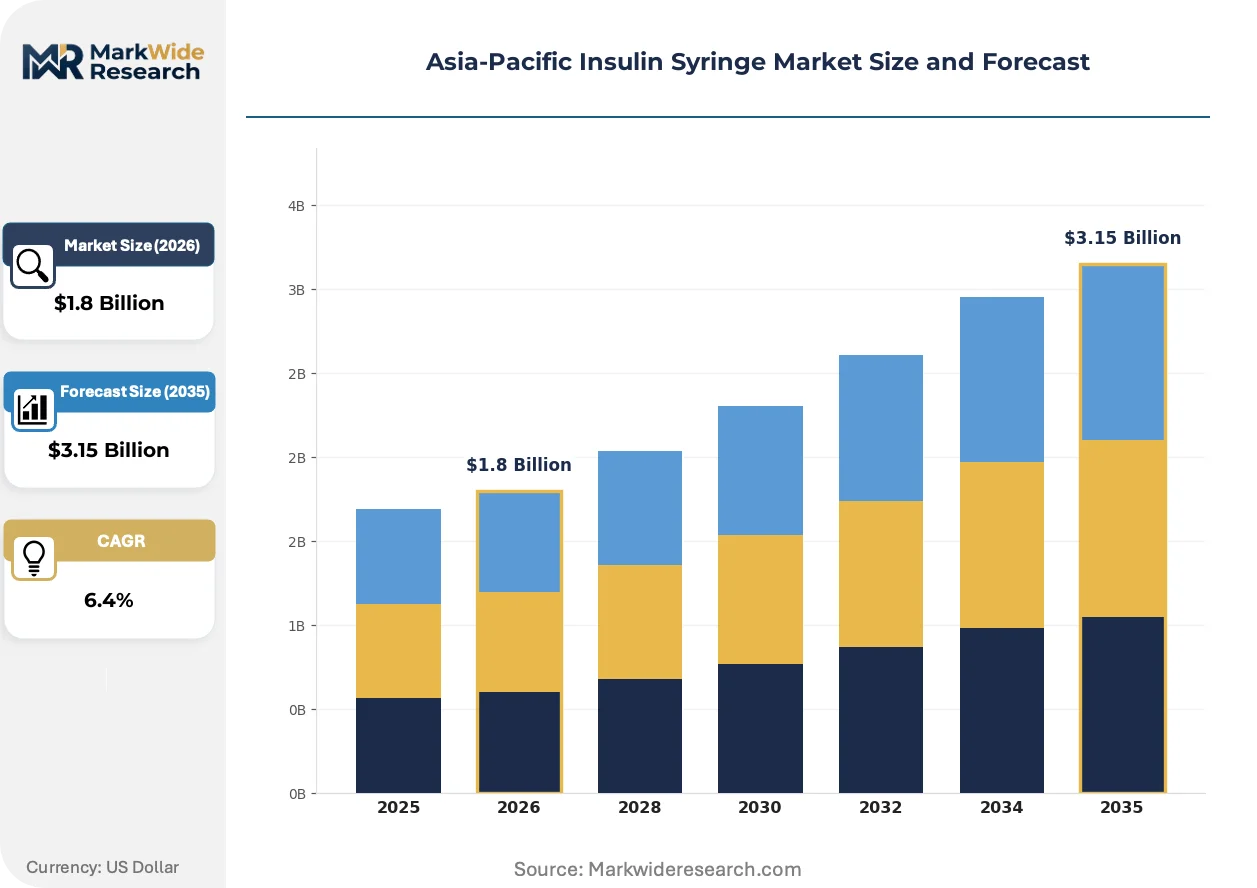
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefilled, Disposable, Reusable, Safety End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Standard, Smart, Insulin Pump-Compatible, Ergonomic Material: Plastic, Glass, Polypropylene, Others |
| Companies Covered | Becton Dickinson, Terumo Corporation, Nipro Corporation, HMD Healthcare Ltd., Cardinal Health Inc., Embecta Corp., Gerresheimer AG, SCHOTT AG, B. Braun, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insulin Syringe Market Strategic Shifts
Digital connectivity and materials science are converging to redefine device value propositions, while procurement centralization is compressing traditional channel structures across the region's largest healthcare systems.
Smart safety syringes with embedded NFC dose-logging chips are fragmenting the premium tier into connected and non-connected variants. Private endocrinology chains in South Korea's Seoul metropolitan area are adopting these devices at accelerated pace. The technology is fragmenting vendor selection criteria away from unit cost toward data interoperability and patient adherence analytics.
China's NMPA accelerated review pathways for innovative diabetes devices are compressing time-to-market for connected syringe platforms. Provincial procurement authorities are simultaneously imposing price ceilings that filter out non-compliant suppliers. The tension between speed-to-approval and margin compression is most acute in Jiangsu and Guangdong hospital network tenders.
Homecare channel disintermediation is compressing traditional distributor layers as pharmacy chains and direct-to-patient platforms capture insulin syringe volume. Australia's Chemist Warehouse and Japan's Matsumoto Kiyoshi are building private-label safety syringe portfolios. This pattern is most visible in Australia's metropolitan diabetes management programs where reimbursement pathways favor retail over institutional procurement.
Asia-Pacific Insulin Syringe Market Segmentation
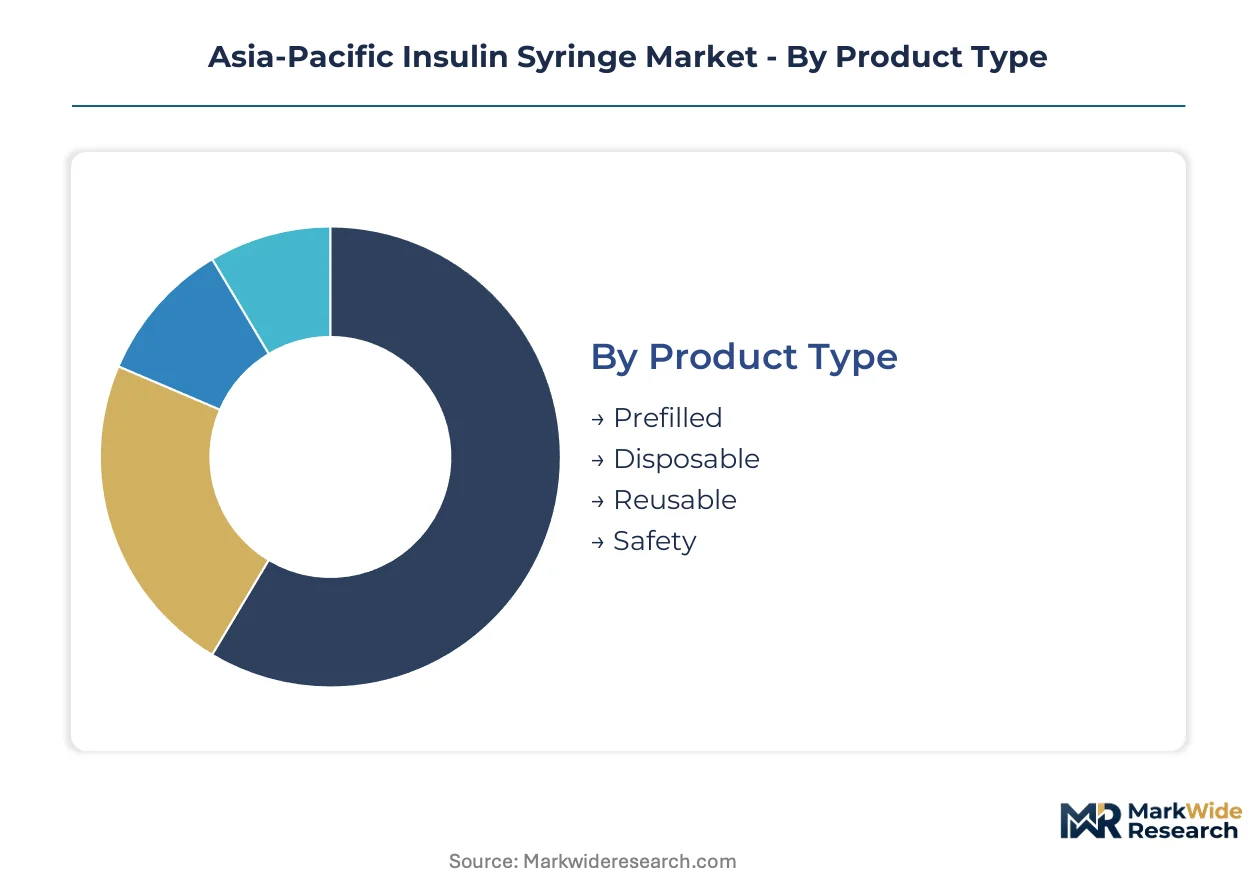
Channel configuration across Asia-Pacific insulin syringe markets varies sharply by segment, with institutional tenders favoring safety-engineered units while retail and direct-to-patient platforms drive smart device penetration. Understanding how each segment maps to procurement pathways reveals where margin compression concentrates versus where premium positioning holds.
Product Type:
Safety syringes dominate hospital procurement channels across Japan, Australia, and South Korea, while disposable units flow through pharmacy retail and homecare distributors. Prefilled formats concentrate in premium private diabetes networks.
- Safety:Needlestick-prevention mechanisms with retractable or shielded needle designs meet PMDA and TGA mandates in tertiary hospital systems. Demand clusters in Japan's metropolitan medical centers and Australia's state hospital networks where occupational safety regulations enforce replacement cycles.
- Disposable:Single-use polypropylene barrel units with bonded 31G needles serve high-volume institutional tenders and retail pharmacy channels. Volume concentrates in China's provincial centralized procurement programs and India's government hospital supply chains where unit cost drives selection criteria.
- Reusable:Glass-barrel designs with detachable stainless steel needles retain procurement share in India's government programs where sterilization infrastructure supports circular use models.
- Prefilled:Factory-loaded insulin cartridges integrated with disposable needle systems target premium homecare segments in South Korea's private endocrinology chains.
By volume, Disposable leads. By growth pace, Safety is ahead.
End User:
Cost-tier differentiation separates institutional buyers seeking compliance-driven safety features from retail channels where convenience and connectivity command premium positioning.
- Hospitals:Tertiary medical centers across Japan, Australia, and South Korea enforce safety syringe mandates through procurement specifications tied to needlestick prevention regulations. PMDA and TGA compliance requirements elevate technical barriers for tender participation.
- Homecare:Direct-to-patient platforms and pharmacy chains in Australia's metropolitan diabetes programs and Japan's retail drugstore networks are capturing volume through connected dose-logging devices. Bluetooth-enabled syringes with timestamp capture penetrate this channel fastest.
- Clinics:District-level diabetes facilities in Vietnam's provincial tiers and India's tier-two cities represent whitespace for compliant safety syringe supply where distribution infrastructure remains underdeveloped.
- Pharmacies:Australia's Chemist Warehouse and Japan's Matsumoto Kiyoshi are building private-label safety syringe portfolios, compressing traditional distributor margins through direct sourcing relationships.
By revenue contribution, Hospitals dominate. By expansion trajectory, Homecare is climbing the fastest.
Technology:
Application-specific requirements fragment vendor selection, with smart platforms demanding data interoperability capabilities while standard units compete on siliconization consistency and needle sharpness retention.
- Smart:NFC-embedded or Bluetooth-enabled syringes with dose-logging and timestamp capture are penetrating premium channels in South Korea's Seoul metropolitan private endocrinology chains. NMPA accelerated review pathways in China compress regulatory timelines for these platforms.
- Standard:Conventional graduated barrel designs with bonded needles serve cost-sensitive institutional tenders across India's CDSCO-regulated government procurement and Vietnam's district hospital networks.
- Insulin Pump-Compatible:Specialized Luer-lock or proprietary connection interfaces enable syringe-to-pump bridging for backup dosing scenarios in Australia's private diabetes management programs.
- Ergonomic:Flanged barrel designs and textured plunger surfaces target arthritis-affected patient populations in Japan's aging demographic segments.
By installed base, Standard leads. By value expansion, Smart is gaining share fastest.
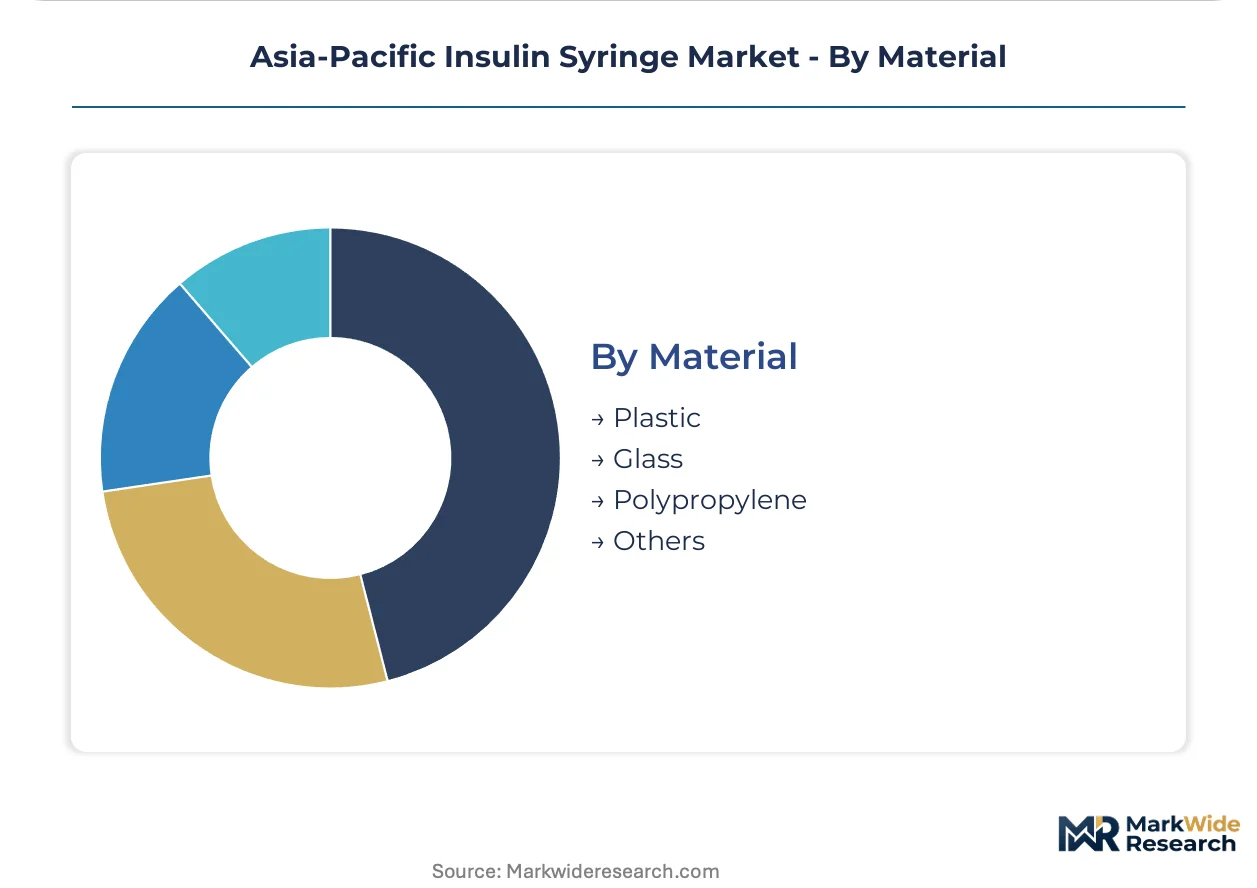
Material:
Supply concentration in Northeast Asian petrochemical clusters shapes procurement economics, with polypropylene resin price volatility directly impacting disposable unit margins.
- Polypropylene:Medical-grade polymer injection-molded barrels dominate disposable safety syringe output, with feedstock conversion capacity concentrating in integrated manufacturers capturing margin through captive resin supply.
- Glass:Borosilicate barrel formulations with etched graduation markings support India's reusable syringe tenders where sterilization infrastructure enables circular deployment models.
- Plastic:General-purpose polymer variants serve economy-tier disposable segments in price-sensitive provincial procurement programs.
- Others:Cyclic olefin copolymer and specialty polymer blends target premium connected devices requiring RF-transparency for embedded NFC chips.
By production volume, Polypropylene leads. By specification advancement, Others shows steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for precision needle-grinding equipment tilts the Asia-Pacific insulin syringe trade balance toward Japanese and Swiss machinery suppliers, while polypropylene resin feedstock flows from Northeast Asian petrochemical clusters into barrel-molding operations across the region.
China
Provincial centralized procurement programs in Jiangsu and Guangdong compress unit margins while filtering tenders toward safety-engineered and connected device platforms. NMPA accelerated review pathways shorten regulatory timelines for innovative diabetes devices. Manufacturing gravity clusters in the Yangtze River Delta around Shanghai and Suzhou where integrated molders capture margin through captive resin conversion.
Japan
Tertiary hospital networks in Tokyo and Osaka enforce PMDA-mandated needlestick prevention standards that displace conventional syringe designs. METI industrial policy supports domestic precision grinding equipment builders serving 31G ultra-fine needle production. Kanto region medical device manufacturers leverage JIS biocompatibility certification to anchor premium positioning in regional export markets.
India
Government hospital procurement programs under CDSCO oversight sustain demand for reusable glass-barrel designs where sterilization infrastructure enables circular deployment. PLI scheme incentives accelerate domestic barrel-molding capacity expansion for polypropylene conversion. Manufacturing concentrates in Gujarat and Maharashtra where medical device parks cluster molders and sterilization providers.
Australia
State hospital networks align procurement specifications with TGA technical documentation requirements that streamline CE-marked manufacturer access. Private diabetes management programs in Sydney and Melbourne drive connected dose-logging device penetration through retail pharmacy channels. Chemist Warehouse private-label sourcing compresses traditional distributor layers in metropolitan markets.
South Korea
Seoul metropolitan private endocrinology chains adopt NFC-embedded smart syringes at accelerated pace, fragmenting vendor selection toward data interoperability capabilities. MFDS regulatory frameworks enforce biocompatibility standards comparable to PMDA benchmarks. Busan-Ulsan industrial corridor hosts precision polymer processors serving medical-grade barrel formulations.
Asia-Pacific Insulin Syringe Market Competitive Environment
Concentration sits with integrated manufacturers commanding captive needle-forming and barrel-molding capacity, while assembly-dependent competitors face margin compression from resin price volatility and single-source equipment bottlenecks. The vendor base stratifies across three archetypes: diversified medical device conglomerates with polymer conversion integration, precision needle specialists with grinding technology leadership, and regional fabricators serving cost-sensitive institutional tenders. Competitive maneuvering centers on backward integration into polypropylene feedstock supply and strategic partnerships with contract sterilization providers to secure ethylene oxide capacity.
Among diversified medical technology conglomerates, Becton Dickinson and Terumo Corporation exemplify the integrated archetype with in-house control over critical production stages. Nipro Corporation occupies a position within the specialized materials tier, representing regional players that anchor procurement relationships through formulation expertise rather than scale. These three entities illustrate how competitive positioning fragments across capability vectors rather than consolidating around uniform business models.
| Leading Market Players |
|---|
| Becton Dickinson |
| Terumo Corporation |
| Nipro Corporation |
| HMD Healthcare Ltd. |
| Cardinal Health Inc. |
| Embecta Corp. |
| Gerresheimer AG |
| SCHOTT AG |
| B. Braun |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles for medical-grade polypropylene resin tether pricing power to Northeast Asian petrochemical cluster reliability, while provincial procurement price ceilings in China feed back into supplier selection toward integrated molders with captive feedstock conversion.
Pricing Analysis
The customization-premium spread between standard disposable units and connected dose-logging platforms reaches three-to-one across Australia's private diabetes networks. Contract-based long-term offtake dominates institutional tenders where volume scale and CDSCO certification grade drive selection, while retail pharmacy channels exhibit greatest price sensitivity due to Chemist Warehouse private-label compression. Cost compression in China's provincial procurement programs intensifies as NMPA accelerated review pathways expand eligible supplier pools.
Supply Chain Analysis
Single-source precision lapping machinery for 31G ultra-fine needle grinding concentrates among Japanese and Swiss equipment builders, creating chokepoint vulnerability for assembly-dependent competitors. Raw material flows draw from South Korean and Chinese petrochemical clusters for polypropylene resin, Japanese specialty steel for cannula blanks, and Malaysian rubber for elastomer plunger formulations. Tariff exposure on precision grinding equipment imports elevates total landed cost for regional fabricators. Distribution runs through hospital GPO contracts, pharmacy chain direct sourcing, and government tender fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific insulin syringe market represents early-cycle expansion as connected dose-logging platforms penetrate South Korea's private endocrinology chains and Australia's retail pharmacy networks, with homecare channel disintermediation accelerating volume capture outside traditional hospital procurement.
For Market Incumbents: Consolidate backward integration into polypropylene feedstock supply to defend margin position against resin price volatility from Northeast Asian naphtha cracking margin swings. Secure captive ethylene oxide sterilization capacity through long-term contract sterilization provider partnerships, as legacy facility requalification under TGA residual gas limits threatens supply assurance for Australian distributors. For New Entrants and Emerging Players: Anchor in Vietnam's district-level diabetes clinics outside Ho Chi Minh City and Hanoi where safety syringe distribution infrastructure remains underdeveloped and CDSCO-compliant manufacturers face shortened qualification timelines. Pursue reusable glass-barrel tenders in India's government procurement programs as sterilization infrastructure enables circular-economy positioning against disposable dominance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart safety syringe manufacturing as NFC-embedded chip integration and Bluetooth module assembly add fixed cost layers to previously standardized disposable production. Target acquisition candidates with precision needle-grinding technology leadership or polypropylene barrel formulation expertise rather than pure assembly operations. Monitor provincial centralized procurement price ceiling adjustments in Jiangsu and Guangdong as inflection indicators for margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Feedstock | Captive resin supply insulates margin from naphtha cracking volatility in Northeast Asian clusters. |
| NMPA Accelerated Review Pathway Pursuit | Compressed regulatory timelines enable faster market entry for connected dose-logging platforms in China. |
| Contract Sterilization Capacity Securement | Ethylene oxide chamber access under TGA residual gas limits ensures supply continuity for Australian distributors. |
| Private-Label Pharmacy Partnership | Direct sourcing relationships with Chemist Warehouse and Matsumoto Kiyoshi compress traditional distributor layers. |
| Reusable Glass-Barrel Tender Qualification | CDSCO registration for sterilization-compatible designs captures India's government procurement volume. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contract filings, CDSCO registration records, and NMPA approval announcements. Interviews with hospital purchasing committee members, biomedical engineers at tertiary medical centers, GPO contracts managers, and regulatory affairs leads at device manufacturers combined with bottom-up and top-down triangulation across safety syringe shipment data and polypropylene resin trade flows.
Segmentation dimensions modeled span product type, end-user channel, technology tier, and material composition across the projection horizon. CAGRs derive from installed base expansion rates, replacement cycle frequencies tied to PMDA needlestick prevention mandates, and connected device penetration curves in premium homecare channels. Forecast inputs incorporate provincial procurement volume allocations, PLI scheme capacity addition schedules, and precision grinding equipment delivery lead times.
Material uncertainties — biocompatibility testing backlogs at PMDA, polypropylene resin price volatility, and provincial procurement price ceiling adjustments — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory timeline stability and sterilization infrastructure capacity. Practitioners should keep alternative scenarios live as NMPA-EU MDR convergence negotiations and India's PLI scheme expansion criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Global Lancets Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Filter Needles Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Autoclaving Trays Market