
 Latex Gloves Market | 2026-2036
Latex Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Latex Gloves Market Outlook
Multi-source procurement is pivoting across the latex gloves supply base as buyers reduce dependency on single-origin manufacturing. Top Glove Corporation Bhd leverages integrated rubber-to-glove production across Malaysian facilities to sustain volume leadership. Hartalega Holdings Berhad anchors premium nitrile-latex hybrid positioning through automated manufacturing lines. Kossan Rubber Industries Bhd differentiates via specialty formulations for surgical applications.
Latex gloves consist of natural rubber latex harvested from Hevea brasiliensis trees, processed through dipping lines on ceramic formers, and vulcanized to achieve tensile strength exceeding 18 MPa for medical-grade certification; their primary purpose is to provide barrier protection against pathogens and chemicals in clinical and industrial settings. Examination gloves dominate volume throughput due to standardized procurement across hospital systems, while surgical gloves command margin concentration through sterility requirements and extended cuff designs. Household and industrial categories occupy stable replacement-demand positions with lower regulatory barriers.
FDA enforces powdered glove bans and biocompatibility testing under 21 CFR 880.6250, while EMA's MDR framework tightens conformity assessment for latex devices entering European clinical channels. OSHA mandates hand protection standards under 29 CFR 1910.138 for industrial latex glove deployment in US workplaces. Stakeholders must monitor regulatory divergence between FDA allergen labeling requirements and emerging EU restrictions on natural rubber latex proteins in prolonged-contact devices.
Market Dynamics
Malaysian production concentration and FDA enforcement of powdered glove bans are forcing buyers to restructure supply agreements while accelerating migration toward nitrile-latex hybrid formulations across hospital procurement systems.
Growth Catalysts
- EMA MDR Framework:Tightened conformity assessment for latex devices entering European clinical channels is compressing supplier qualification timelines and favoring pre-certified manufacturers with established biocompatibility dossiers.
- Hevea brasiliensis cultivation:Malaysia's dominance in natural rubber production anchors raw material security for integrated glove manufacturers operating dipping lines across Southeast Asian facilities.
- OSHA 29 CFR 1910.138:Mandated hand protection standards for industrial latex glove deployment in US workplaces sustain replacement-demand throughput across manufacturing, chemical handling, and food processing verticals.
Market Restraints
- Natural rubber price volatility:Latex concentrate input costs fluctuate with monsoon patterns and tapping labor availability across Malaysian and Thai plantation belts, compressing margin predictability for non-integrated processors.
- Allergen protein thresholds:FDA biocompatibility testing under 21 CFR 880.6250 and emerging EU restrictions on natural rubber latex proteins in prolonged-contact devices create formulation reformulation costs and label complexity.
- Nitrile substitution acceleration:Synthetic alternatives with comparable tensile strength and eliminated Type I hypersensitivity risk are capturing examination glove volume in price-sensitive procurement categories.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for medical device manufacturing are attracting greenfield glove production capacity to offset Southeast Asian supply concentration and serve domestic hospital procurement expansion.
- Surgical sterility specialization:Extended cuff designs and aseptic presentation formats command margin concentration through differentiated positioning against commoditized examination categories.
- Automated dipping lines:Convergence of ceramic former robotics and real-time thickness monitoring is enabling premium nitrile-latex hybrid production at scale previously restricted to conventional latex.
Industry Challenges
- Vulcanization process engineering:Achieving consistent tensile strength exceeding 18 MPa for medical-grade certification requires specialized chemical engineering talent scarce outside established Malaysian and Thai production clusters.
- FDA 510(k) clearance timelines:Biocompatibility testing and allergen labeling compliance documentation extend product launch cycles for novel formulations, compressing competitive response windows.
- Multi-source qualification overhead:Hospital systems pivoting away from single-origin supply agreements face duplicated audit costs and formulation consistency verification across geographically dispersed manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latex Gloves Market |
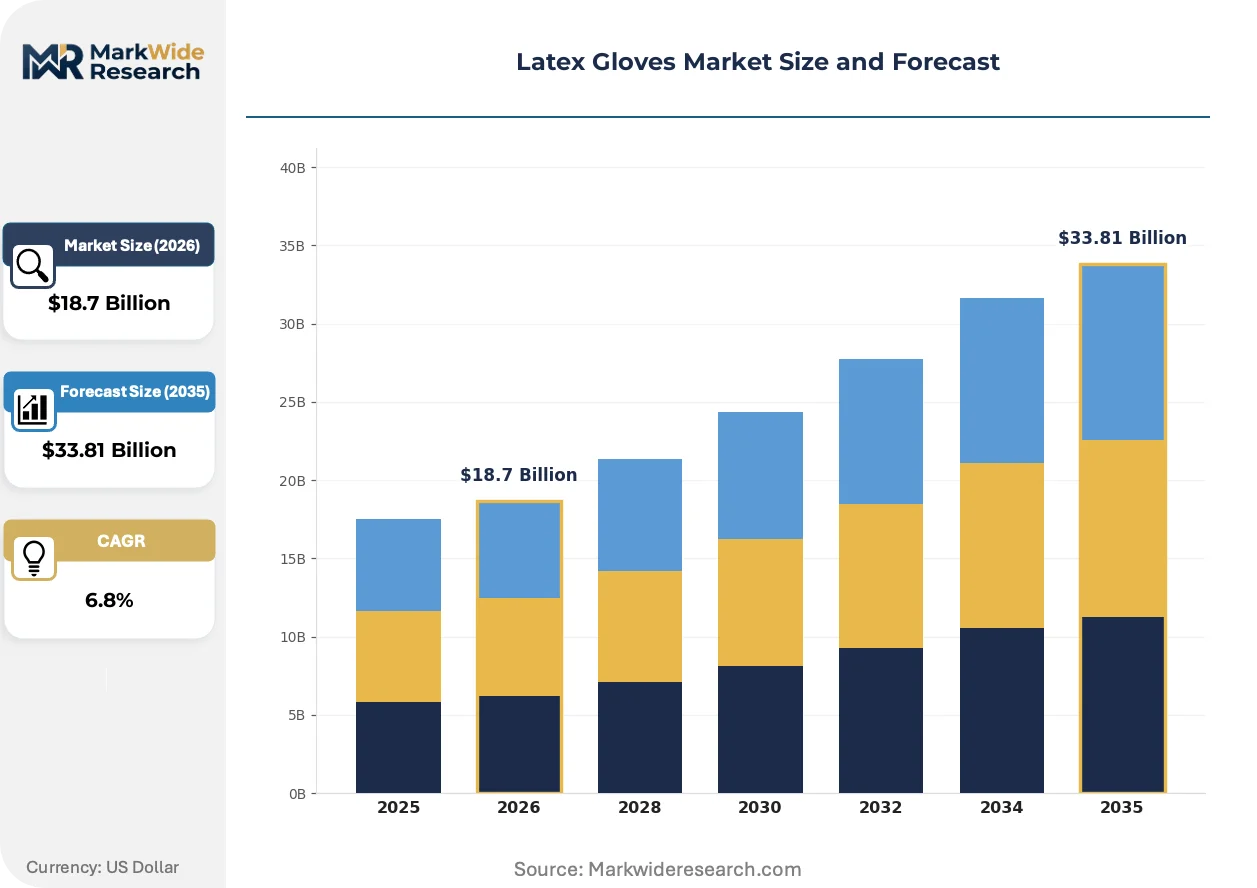
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gloves, Examination Gloves, Household Gloves, Industrial Gloves Application: Healthcare, Automotive, Food Processing, Manufacturing End User: Hospitals, Clinics, Laboratories, Dental Practices Distribution Channel: Online Retailers, Supermarkets, Medical Supply Stores, Direct Sales |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Kossan Rubber Industries Bhd, Supermax Corporation Berhad, Ansell Ltd, Sri Trang Gloves, Rubberex Corporation, Cardinal Health, Semperit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latex Gloves Market Strategic Shifts
Ceramic former automation, protein reduction chemistry, and procurement restructuring are compressing traditional manufacturing economics while elevating barrier performance specifications across clinical and industrial channels.
Nitrile-latex hybrid formulations are consolidating market positioning across premium examination and surgical categories. Hospital systems in Germany and Switzerland are specifying these materials for extended-duration procedures requiring both tactile sensitivity and chemical resistance. The technology is consolidating supplier tiers by requiring integrated polymer compounding capabilities that smaller dipping operations cannot replicate.
REACH Annex XVII restrictions on powder additives and EMA MDR protein concentration limits are restructuring formulation R&D priorities across European-facing manufacturers. Industrial consequence includes accelerated capital deployment toward leaching and washing process upgrades. Surgical glove segments with prolonged skin contact exposure face the steepest compliance cost escalation and are responding through captive plantation partnerships for low-protein latex feedstock.
Consolidated procurement through group purchasing organizations is compressing distributor margins and redirecting volume toward direct manufacturer contracts. Hospital networks in the United States are unbundling traditional distribution markups through e-procurement platforms with real-time inventory visibility. This pattern is most visible in multi-hospital systems across Texas, Florida, and California where standardized SKU rationalization programs are eliminating redundant supplier relationships.
Latex Gloves Market Segmentation
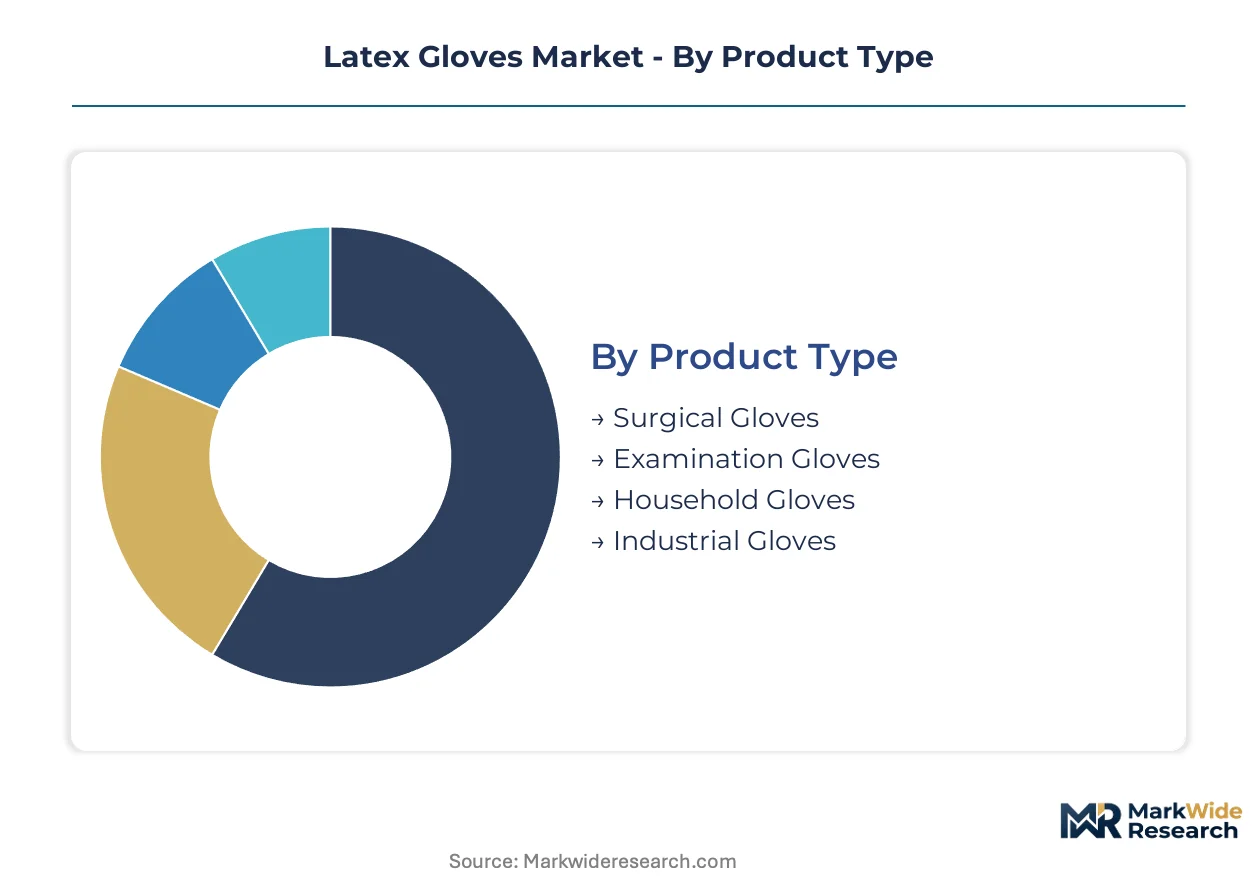
Segmentation in the latex gloves market reveals distinct procurement patterns across clinical and industrial channels, with product specifications and regulatory requirements driving divergent margin structures. Understanding these divisions enables manufacturers to align production capacity with the replacement cycles and compliance burdens specific to each category.
Product Type:
Upgrade cycles vary dramatically across glove categories, with clinical applications demanding more frequent specification refreshes than industrial or household segments due to evolving FDA and EMA standards.
- Surgical Gloves:Extended cuff designs and aseptic presentation formats require tensile strength exceeding 18 MPa and biocompatibility certification under 21 CFR 880.6250. Demand concentrates in tertiary hospital systems across Germany and Switzerland where extended-duration procedures mandate superior barrier integrity and tactile sensitivity.
- Examination Gloves:Standardized procurement across hospital systems drives volume throughput, with nitrile-latex hybrid formulations capturing share in price-sensitive categories. Malaysian integrated manufacturers dominate supply through automated dipping lines capable of medical-grade certification at scale.
- Household Gloves:Lower regulatory barriers support stable replacement demand through retail channels, with formulations optimized for durability rather than clinical barrier performance.
- Industrial Gloves:OSHA 29 CFR 1910.138 mandates sustain throughput across chemical handling, food processing, and manufacturing verticals where puncture resistance supersedes tactile precision requirements.
Examination gloves sit at the top of the volume ranking, with surgical gloves climbing the fastest as hospital procurement elevates sterility specifications.
Application:
Cost tier differentiation separates clinical applications with premium certification requirements from industrial deployments where regulatory burden and price sensitivity compress margins.
- Healthcare:FDA powdered glove bans and EMA MDR protein thresholds drive formulation reformulation costs and favor pre-certified manufacturers with established biocompatibility dossiers.
- Automotive:Chemical resistance specifications for solvent handling and assembly line deployment sustain replacement-demand throughput without clinical-grade certification overhead.
- Food Processing:USDA and FDA food-contact regulations mandate specific formulations, with color-coded glove programs supporting HACCP compliance across processing facilities.
- Manufacturing:OSHA hand protection standards anchor volume across metal fabrication, electronics assembly, and general industrial maintenance categories.
Healthcare commands the steepest margin tier, while food processing gains share fastest as safety protocols expand across processing networks.
End User:
Customer type determines procurement channel preference and contract structure, with consolidated hospital systems diverging from fragmented dental and laboratory purchasing patterns.
- Hospitals:Group purchasing organization consolidation compresses distributor margins and redirects volume toward direct manufacturer contracts through e-procurement platforms with real-time inventory visibility.
- Clinics:Smaller-scale procurement relies on medical supply distributors, with SKU rationalization programs eliminating redundant supplier relationships across multi-site practice networks.
- Laboratories:Research and diagnostic facilities prioritize chemical resistance and precision fit for extended-duration handling of reagents and samples.
- Dental Practices:Specialized sizing requirements and frequent change protocols sustain niche demand through dedicated dental supply channels.
Hospitals anchor procurement volume concentration, with laboratories expanding most quickly as diagnostic testing infrastructure scales.
Distribution Channel:
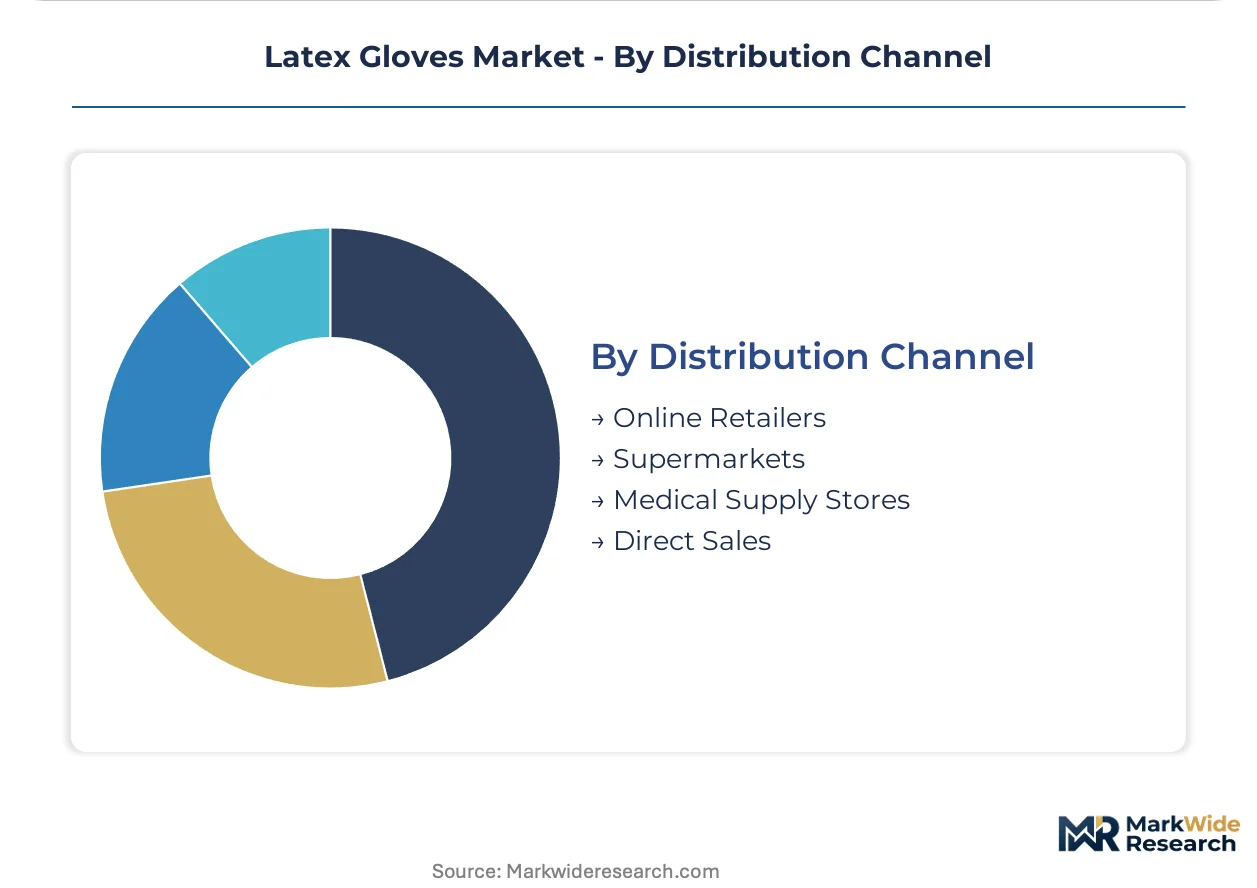
Supply concentration in Malaysian manufacturing clusters shapes channel economics, with direct sales capturing share from traditional distribution as procurement digitization accelerates.
- Online Retailers:E-procurement platforms with real-time inventory visibility are unbundling traditional distribution markups across hospital networks in Texas, Florida, and California.
- Supermarkets:Household and light industrial categories dominate this channel, with private-label programs capturing price-sensitive consumer demand.
- Medical Supply Stores:Regional distributors serving clinics and dental practices face margin compression as manufacturer direct contracts expand.
- Direct Sales:Large hospital systems negotiate volume agreements with Top Glove, Hartalega, and Kossan, eliminating intermediary markups through captive procurement platforms.
Direct sales sits at the top of the volume ranking for clinical segments, with online retailers climbing the fastest as procurement digitization penetrates mid-tier health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian rubber plantations and integrated dipping facilities anchor the global latex gloves supply base, with production clusters concentrated in Selangor and Perak provinces serving hospital procurement networks across North America, Europe, and Asia-Pacific.
United States
FDA enforcement of powdered glove bans under 21 CFR 880.6250 is restructuring procurement contracts across Texas, Florida, and California hospital systems. Group purchasing organizations are consolidating supplier relationships through direct manufacturer agreements. The Southeast medical corridor spanning Atlanta and Nashville is driving demand for sterile surgical presentation formats.
Germany
EMA MDR framework compliance is compressing supplier qualification timelines for latex devices entering European clinical channels. Tertiary hospital systems in Bavaria and North Rhine-Westphalia specify extended cuff designs for extended-duration procedures. REACH Annex XVII restrictions on powder additives are accelerating leaching process upgrades across manufacturing partners.
Malaysia
Hevea brasiliensis cultivation across Selangor and Perak plantation belts secures raw material access for integrated rubber-to-glove producers. Top Glove and Hartalega operate automated dipping lines with real-time thickness monitoring capabilities. The Port Klang export hub channels volume toward US and European hospital procurement systems.
India
PLI scheme incentives for medical device manufacturing are attracting greenfield glove production capacity to offset Southeast Asian supply concentration. Domestic hospital procurement expansion in Maharashtra and Gujarat is absorbing regional output. Central government procurement standardization is consolidating SKU rationalization programs across multi-hospital systems.
Thailand
Natural rubber tapping across southern plantation belts supplies latex concentrate to integrated processors and independent dipping operations. Bangkok-based manufacturers face margin compression from Malaysian scale competitors. Vulcanization process engineering talent scarcity limits medical-grade certification expansion outside established production clusters.
Latex Gloves Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and regulatory certification capabilities. Malaysian integrated producers dominate volume leadership through captive plantation supply and automated ceramic former lines. The vendor base stratifies into three archetypes: plantation-integrated giants with rubber-to-glove control, specialty surgical formulators with sterility expertise, and regional fabricators serving price-sensitive industrial categories. Competitive moves concentrate on backward integration into latex concentrate production and strategic partnerships with hospital procurement platforms.
Among Malaysian plantation-integrated manufacturers, Top Glove Corporation Bhd, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd exemplify the scale-driven archetype. These entities occupy positions defined by rubber security and automated production infrastructure. Ansell Ltd represents the specialty surgical tier with differentiated positioning around aseptic presentation formats. Sri Trang Gloves and Rubberex Corporation sit within the regional export-focused segment serving industrial and household replacement demand across Southeast Asian and Middle Eastern channels.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Bhd |
| Supermax Corporation Berhad |
| Ansell Ltd |
| Sri Trang Gloves |
| Rubberex Corporation |
| Cardinal Health |
| Semperit |
| Others |
Value Chain & Pricing Dynamics
Family-owned Malaysian plantation conglomerates with sovereign-linked financing anchors control over latex concentrate supply and wield asymmetric pricing power against hospital procurement systems in the United States and Germany. Their captive rubber-to-glove integration compresses input cost volatility for internal operations while forcing non-integrated competitors to absorb spot market fluctuations, creating tiered margin structures that stratify the vendor base.
Pricing Analysis
Input-cost pass-through from Hevea brasiliensis latex concentrate dominates pricing formation across medical-grade and industrial tiers. Three-tier pricing structure across premium surgical, standard examination, and economy industrial levels separates FDA-certified sterile presentation formats from bulk examination procurement and unregulated household categories. Pricing pressure stems from nitrile substitution in price-sensitive examination volumes as hospital systems rationalize SKU portfolios. Industrial buyers in food processing and chemical handling exhibit highest price sensitivity, while tertiary hospital systems in Germany and Switzerland absorb premium surgical pricing for extended-cuff sterility specifications.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA enforcement of powdered glove bans are forcing hospital procurement systems to qualify secondary Malaysian and Thai manufacturers alongside primary suppliers. Geographic supply concentration centers on Malaysia, Thailand, and emerging Indian production clusters following PLI scheme incentives. Raw material dependencies draw from Selangor plantation belts, ceramic former robotics, and vulcanization chemical inputs. Single-source vulnerability persists for low-protein latex feedstock specialized for surgical applications. Distribution runs through Port Klang export hub consolidation toward direct manufacturer contracts with United States group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the latex gloves market rests on automated dipping line deployment and nitrile-latex hybrid premium-tier capture, offsetting commodity examination price erosion.
For Market Incumbents: Anchor sterile surgical specialization through extended cuff designs and aseptic presentation formats that command premium positioning against nitrile substitution in examination categories. Deepen backward integration into Selangor plantation partnerships for low-protein latex feedstock security. Defend against Indian PLI-scheme entrants by accelerating FDA 510(k) biocompatibility dossier expansion. For New Entrants and Emerging Players: Launch via e-procurement platform partnerships serving mid-tier United States hospital systems in Texas and Florida where multi-source qualification mandates have opened procurement windows. Target industrial food processing verticals with color-coded HACCP compliance programs as the most penetrable segment outside clinical certification barriers. Penetrate through automated ceramic former lines capable of medical-grade tensile certification at sub-Malaysian scale economics. For Investors and Strategic Acquirers: Hospital systems consolidating through group purchasing organization mergers are the most active acquirer in this space, seeking captive glove supply security. Long-term viability over the mid-decade horizon hinges on nitrile-latex hybrid formulation capabilities and EMA MDR pre-certification status. Watch FDA allergen protein threshold tightening as the signal indicating accelerated consolidation toward integrated plantation-glove producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Supply | Captive Hevea brasiliensis access insulates margin from latex concentrate spot volatility. |
| Automated Ceramic Former Line Deployment | Real-time thickness monitoring enables premium hybrid production at Malaysian scale benchmarks. |
| FDA 510(k) Biocompatibility Expansion | Pre-certified allergen dossiers compress hospital procurement qualification timelines. |
| Direct GPO Contract Negotiation | E-procurement platform integration eliminates distributor markups across Texas and California systems. |
| Nitrile-Latex Hybrid Formulation R&D | Extended-duration procedure compatibility captures share in German and Swiss tertiary hospitals. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with hospital procurement managers, GPO contracts specialists, biomedical engineers, and Malaysian plantation operations directors with secondary validation. FDA 510(k) filings, EMA MDR submissions, OSHA enforcement records, and customs trade data anchored supply-side quantification. Bottom-up capacity modeling across Selangor and Perak facilities triangulated against top-down hospital expenditure tracking.
Segment-weighting approaches distributed volume and value across product type, application vertical, end-user scale, and distribution channel dimensions throughout the projection horizon. Surgical sterility tier, examination volume scale, and industrial chemical resistance specifications formed the core segmentation framework. CAGRs derived from replacement-demand elasticity modeling and procurement contract renewal cycles, with Hevea brasiliensis yield forecasts and regulatory enforcement timelines as key industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA allergen protein threshold acceleration or Malaysian monsoon disruption scenarios. Deviation in Indian PLI scheme capacity absorption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Collection Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Suture Wire Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Foley Trays Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Cryopreservation & Fertilization Media Market