
 Colon Decompression Kits Market | 2026-2036
Colon Decompression Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Colon Decompression Kits Market Outlook
Single-use sterile disposable architecture is reconfiguring colon decompression kit manufacturing, replacing reusable endoscope-dependent workflows with closed catheter systems. Olympus Corporation leverages its endoscopy ecosystem to sustain integrated decompression portfolios across Japanese and European hospital networks. Cook Medical LLC anchors North American supply through specialized interventional catheter production. Boston Scientific Corporation differentiates via gastroenterology channel control and physician training infrastructure.
Colon decompression kits are sterile catheter assemblies designed for transanal or endoscopically assisted decompression of acute colonic dilation, typically incorporating flexible tubing with multiple lumens for simultaneous irrigation, suction, and pressure monitoring. These devices serve the critical function of preventing cecal perforation in patients presenting with Ogilvie syndrome, malignant obstruction, or post-operative ileus. Double lumen kits capture the dominant procurement share among hospitals performing scheduled interventional procedures, while emergency kits represent the fastest-expanding technology segment as pre-positioned trauma inventory expands. Home care channels remain nascent due to reimbursement constraints and caregiver training requirements, concentrating margin pools in institutional settings.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device sterility, biocompatibility, and shelf-life validation across all marketed configurations. The European Medical Device Regulation mandates notified body oversight for colon decompression systems, extending conformity assessment timelines and elevating documentation burdens for manufacturers seeking CE marking. Stakeholders must monitor evolving CMS procedural coding decisions and hospital value-analysis committee criteria that increasingly bundle decompression devices into broader acute care episode payments.
Market Dynamics
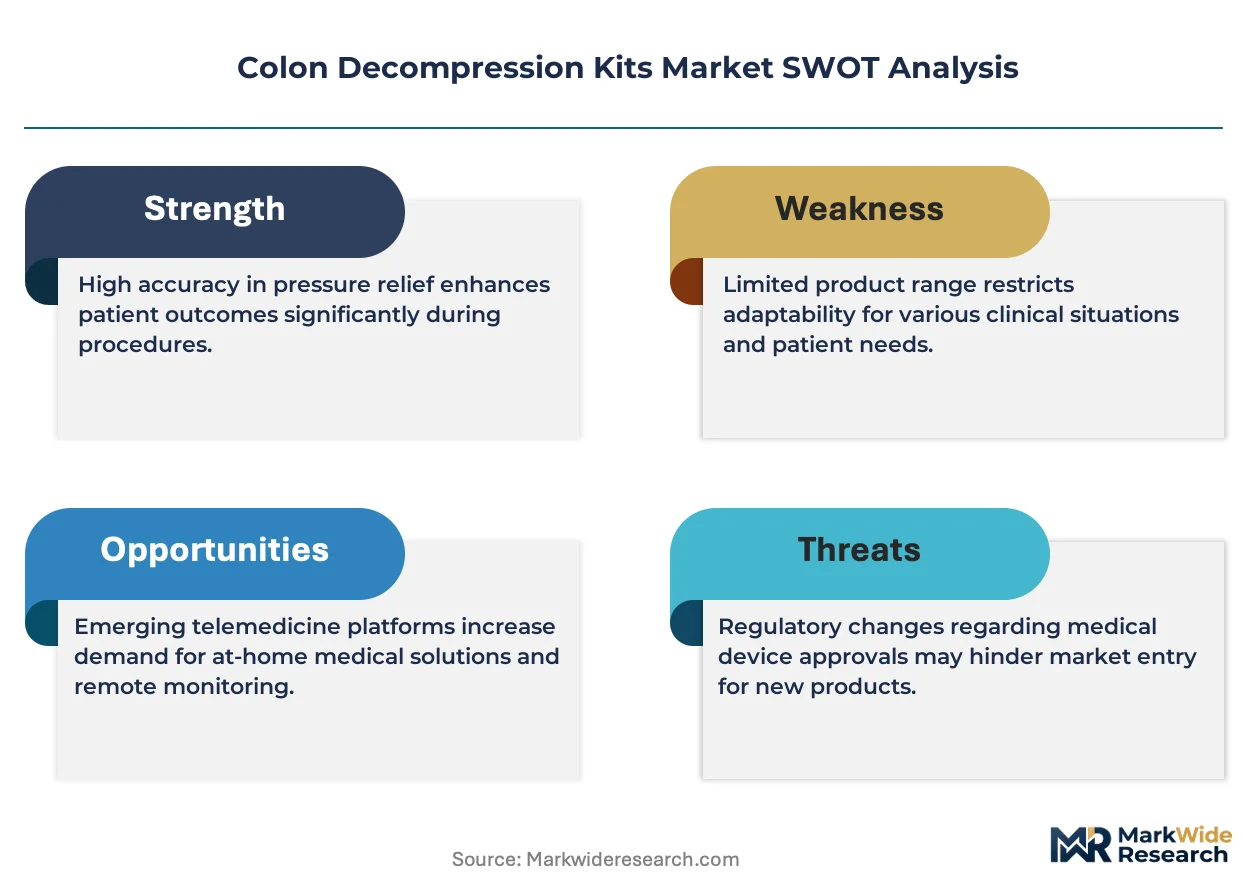
Single-use sterile catheter architecture is displacing reusable endoscope-dependent workflows across acute care settings, compressing sterilization infrastructure requirements while elevating per-procedure material costs for hospital procurement departments.
Growth Catalysts
- Aging Demographics:Population cohorts over 65 in the United States, Germany, and Japan are expanding acute colonic intervention volumes, driving scheduled and emergency decompression procedure demand.
- FDA 510(k) Streamlining:Expedited review pathways for breakthrough device designations are accelerating market entry timelines for novel catheter configurations with integrated pressure monitoring.
- Trauma Inventory Pre-positioning:Emergency department preparedness mandates are expanding stocking requirements for rapid-deployment decompression kits in Level I and Level II trauma centers.
Market Restraints
- Silicone Elastomer Price Volatility:Medical-grade silicone feedstock costs fluctuate with petrochemical indices, compressing gross margins for catheter manufacturers without long-term supply contracts.
- European Notified Body Bottlenecks:CE marking timelines under the Medical Device Regulation have extended to 18-24 months, freezing new product introductions for manufacturers dependent on European revenue.
- Endoscopic Stent Substitution:Self-expanding metal stents for malignant colonic obstruction reduce repeat intervention frequency, cannibalizing recurring decompression kit utilization in oncology patient populations.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:Freestanding ASC networks in Texas and Florida are procuring point-of-care decompression platforms for same-day discharge protocols.
- ISO 13485 Certification Arbitrage:Contract manufacturers in Costa Rica and Malaysia are attracting kit assembly relocation to serve North American demand with reduced labor cost structures.
- Telehealth-Enabled Remote Monitoring:Post-procedure pressure telemetry integration creates subscription revenue streams for device vendors managing home-based recovery protocols.
Industry Challenges
- Polymer Extrusion Technician Scarcity:Multi-lumen catheter fabrication requires specialized extrusion operators with 3-5 year training horizons, constraining production scale-up for demand spikes.
- Legacy EHR Integration Friction:Proprietary data formats from decompression pressure monitors require middleware development for seamless integration with Epic and Cerner hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colon Decompression Kits Market |
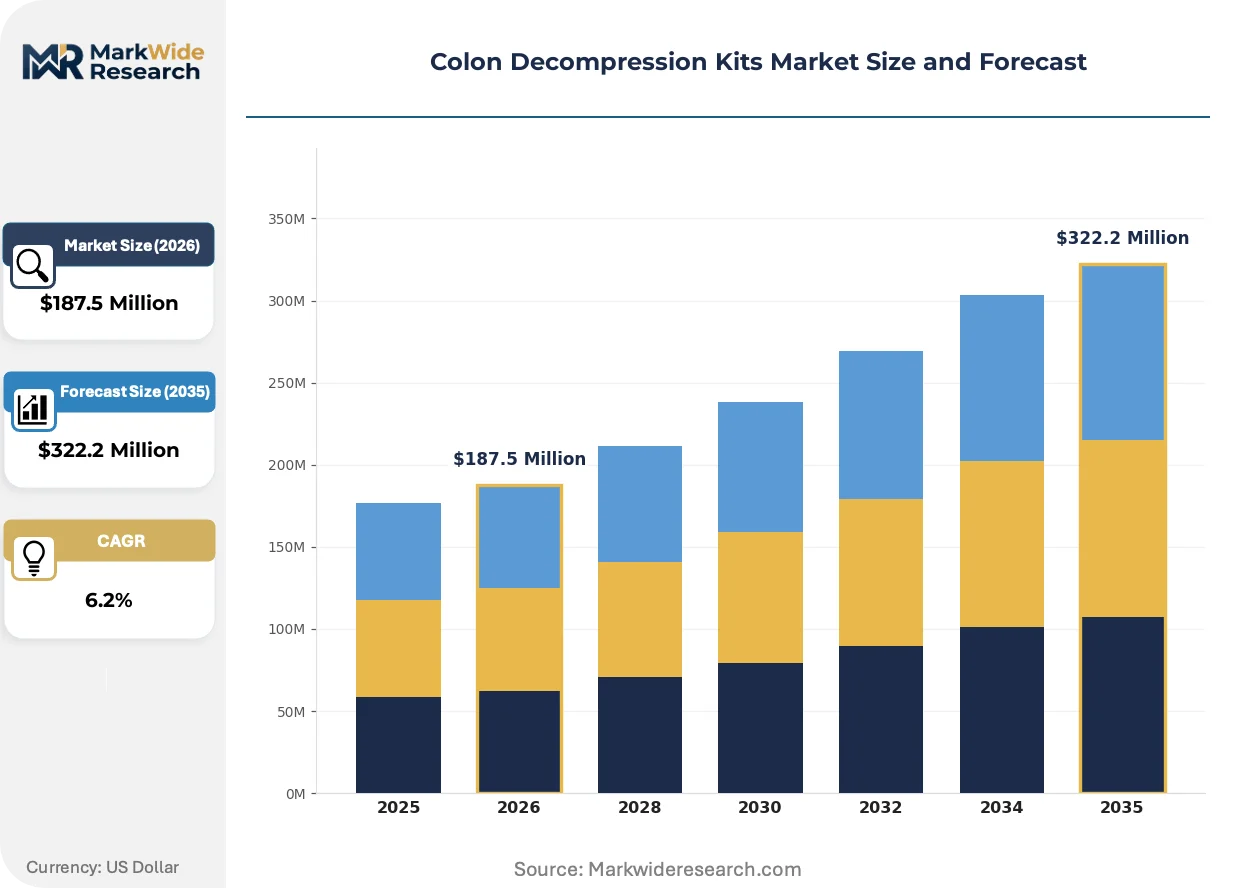
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $322.2 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lumen Kits, Double Lumen Kits, Triple Lumen Kits, Drainage Kits End User: Hospitals, Surgical Centers, Emergency Departments, Home Care Application: Trauma Cases, Post-operative Care, Bowel Obstruction, Diverticulitis Technology: Manual Systems, Automated Systems, Guided Systems, Emergency Kits |
| Companies Covered | Olympus Corporation, KARL STORZ SE & Co. KG, Fujifilm Holdings Corporation, Boston Scientific Corporation, Medtronic plc, Cook Medical LLC, Teleflex Incorporated, B. Braun Melsungen AG, Supremex Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colon Decompression Kits Market Strategic Shifts
Catheter-based decompression platforms are undergoing rapid functional specialization as manufacturers integrate sensing capabilities and disposable electronics that were previously confined to capital equipment.
Closed-system decompression catheters with embedded pressure transducers are migrating from tertiary academic medical centers to community hospital emergency departments. These devices transmit real-time cecal pressure data to bedside monitors, eliminating manual manometer attachment. The technology is compressing the clinical learning curve for non-specialist operators while enabling earlier intervention thresholds.
The European Medical Device Regulation's Unique Device Identification mandate is forcing manufacturers to reconfigure labeling and traceability systems. Lot-level digital records must now integrate with EUDAMED, elevating serialization infrastructure costs. Smaller kit producers without enterprise ERP systems are outsourcing compliance to specialized contract partners.
Hospital value-analysis committees are consolidating decompression device purchasing into broader acute care episode bundles. This behavioral shift is displacing standalone product negotiations with multi-year supply agreements tied to total cost-of-care metrics. The transformation is most visible in integrated delivery networks across California and Pennsylvania, where procurement authority has centralized from individual hospitals to system-level contracting offices.
Colon Decompression Kits Market Segmentation
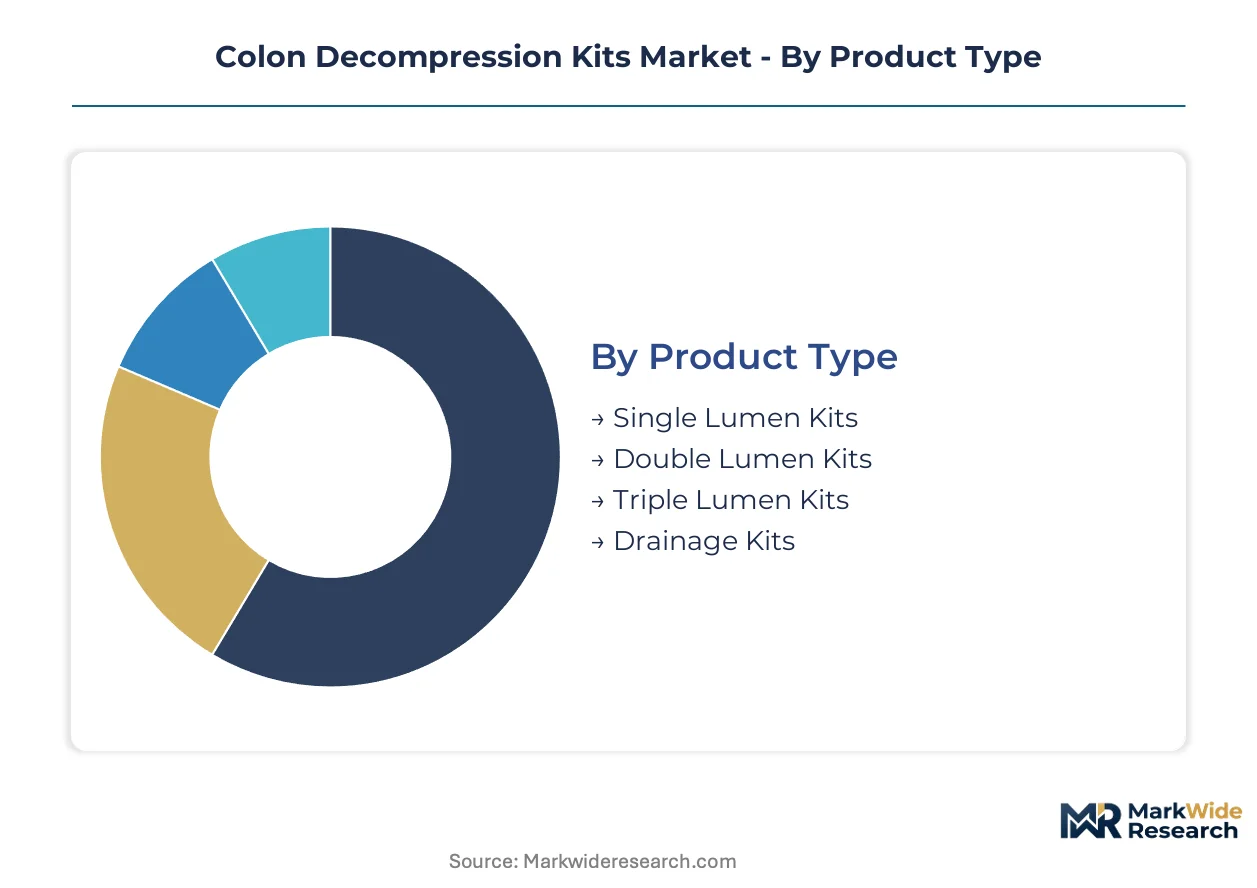
Colon decompression kit manufacturers configure product portfolios across four intersecting dimensions that determine reimbursement pathways, procurement cycles, and clinical training requirements. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape competitive positioning.
Product Type:
Catheter architecture complexity determines sterilization protocols, shelf-life validation costs, and per-procedure reimbursement tiers.
- Double Lumen Kits:These assemblies incorporate parallel irrigation and suction channels within a single flexible catheter body. Hospital procurement departments in the United States and Germany concentrate orders here for scheduled interventional procedures, driven by physician preference for simultaneous pressure monitoring without instrument exchange.
- Emergency Kits:Pre-configured sterile packs with rapid-deployment packaging and color-coded connection ports. Trauma centers across Texas and Florida are expanding inventory positions as Level I preparedness mandates tighten, compressing deployment time for non-specialist operators.
- Single Lumen Kits:Basic drainage-focused configurations with reduced manufacturing complexity and lower per-unit cost.
- Triple Lumen Kits:Advanced multi-channel designs supporting irrigation, suction, and dedicated pressure monitoring lines.
- Drainage Kits:Simplified assemblies prioritizing passive decompression without active irrigation capabilities.
Double Lumen Kits command the established base. The steepest expansion runs through Emergency Kits.
End User:
Institutional purchasing authority determines contract structures, with centralized procurement displacing individual hospital negotiations.
- Hospitals:Integrated delivery networks in California and Pennsylvania bundle decompression devices into acute care episode payments. Value-analysis committees now mandate multi-year supply agreements tied to total cost-of-care metrics rather than standalone product pricing.
- Emergency Departments:Level I and Level II trauma centers face federal preparedness mandates requiring pre-positioned rapid-deployment inventory. The FDA's sterility validation requirements for Class II devices extend procurement lead times for these channels.
- Surgical Centers:Freestanding ASC networks in Texas and Florida are procuring point-of-care platforms for same-day discharge protocols.
- Home Care:Reimbursement constraints and caregiver training requirements limit penetration despite remote monitoring technology advances.
Hospitals anchor volume concentration. Emergency Departments are climbing the fastest as federal mandates expand.
Application:
Clinical indication determines procedure urgency, reimbursement coding, and repeat intervention frequency.
- Bowel Obstruction:Malignant and non-malignant obstructions drive the highest procedure volumes. Self-expanding metal stents are cannibalizing recurring decompression kit utilization in oncology populations, compressing addressable demand for repeat interventions.
- Post-operative Care:Ileus management following abdominal surgery generates predictable demand curves tied to elective procedure scheduling. Japanese hospital networks emphasize early decompression protocols to prevent cecal perforation in this population.
- Trauma Cases:Acute colonic dilation from blunt abdominal injury requires immediate intervention without diagnostic delay.
- Diverticulitis:Recurrent episodes create intermittent demand patterns with lower per-patient procedure counts.
Bowel Obstruction retains the largest procedure base. Post-operative Care is gaining share fastest as enhanced recovery protocols proliferate.
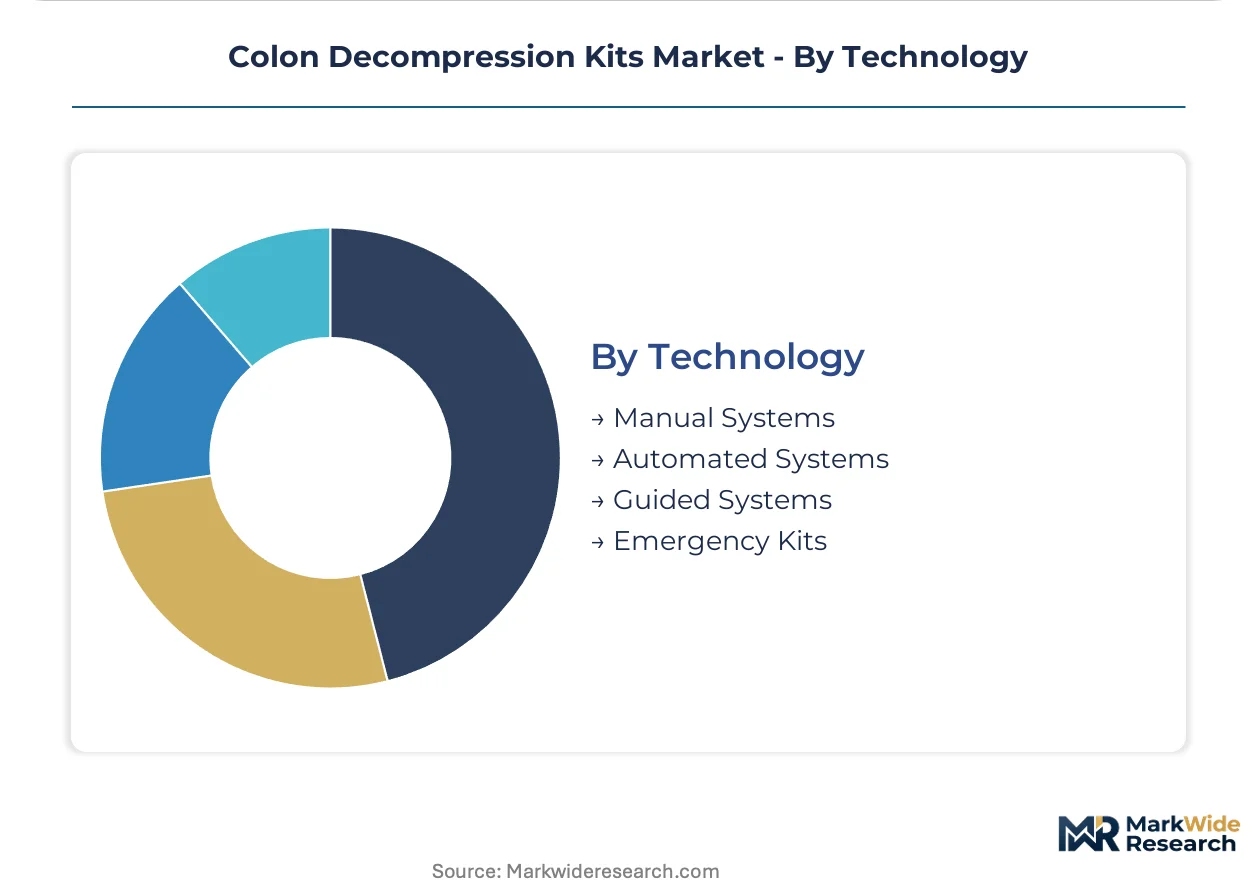
Technology:
Automation depth determines capital equipment requirements, training infrastructure, and subscription revenue potential.
- Automated Systems:Catheter platforms with embedded pressure transducers transmitting real-time cecal data to bedside monitors. Community hospital emergency departments are migrating to these configurations, eliminating manual manometer attachment and compressing the clinical learning curve.
- Guided Systems:Endoscopically assisted placement with imaging confirmation. Tertiary academic medical centers maintain preference for these approaches in complex anatomical presentations.
- Manual Systems:Operator-dependent placement without electronic feedback or imaging integration.
- Emergency Kits:Simplified rapid-deployment configurations prioritizing speed over precision monitoring.
Guided Systems hold the incumbent position. Automated Systems are expanding most quickly as sensing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and Japan concentrate the majority of institutional purchasing authority for colon decompression platforms. These three markets anchor demand through distinct reimbursement architectures and regulatory validation requirements.
United States
Level I and Level II trauma centers in Texas and Florida face federal preparedness mandates requiring pre-positioned rapid-deployment decompression inventory. FDA 510(k) clearance pathways for Class II medical devices are tightening sterility validation requirements, extending procurement lead times for emergency departments. Integrated delivery networks across California and Pennsylvania have centralized purchasing authority into system-level contracting offices.
Germany
Hospital procurement departments in Bavaria and North Rhine-Westphalia emphasize ISO 13485 quality management standards for catheter assembly validation. The European Medical Device Regulation mandates notified body oversight, extending CE marking timelines to 18-24 months for manufacturers seeking market entry. Freiburg and Tübingen medical technology clusters host specialized polymer extrusion operations serving kit assembly demand.
Japan
PMDA regulatory frameworks govern biocompatibility testing for silicone elastomer components used in multi-lumen catheter fabrication. The Kanto region around Tokyo concentrates tertiary academic medical centers maintaining preference for endoscopically assisted placement systems. METI industrial policy supports domestic manufacturing of minimally invasive surgical devices through targeted subsidy programs.
United Kingdom
NHS procurement frameworks in England are consolidating decompression device purchasing into acute care episode bundles rather than standalone product negotiations. MHRA post-Brexit regulatory autonomy has created parallel conformity assessment requirements distinct from EU MDR pathways. London and Southeast hospital networks drive the majority of interventional gastroenterology procedure volumes.
Canada
Health Canada Class II medical device licensing requirements align with FDA sterility validation standards, facilitating cross-border supply chain integration for North American kit manufacturers. Provincial health authorities in Ontario and Quebec manage centralized tender processes for hospital procurement. Toronto and Montreal anchor the majority of acute colonic intervention capacity outside the United States.
Colon Decompression Kits Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement environments. The vendor base organizes around three strategic archetypes: diversified endoscopy platform holders, interventional catheter specialists, and regional contract manufacturers. Consolidation pressure runs through integrated delivery network purchasing centralization and multi-year supply agreement mandates. Competitive moves concentrate on geographic certification arbitrage and physician training infrastructure deployment.
Among diversified medical technology conglomerates, Olympus Corporation and Fujifilm Holdings Corporation exemplify platform-integrated positioning through endoscopy ecosystem control. Boston Scientific Corporation and Cook Medical LLC occupy positions within the interventional catheter specialist tier, anchoring North American supply relationships. Medtronic plc represents the scale-driven archetype with cross-specialty distribution infrastructure spanning multiple acute care device categories.
| Leading Market Players |
|---|
| Olympus Corporation |
| KARL STORZ SE & Co. KG |
| Fujifilm Holdings Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| Cook Medical LLC |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Supremex Equipment |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific freight corridors connecting Malaysian contract manufacturers to California distribution hubs transmit silicone elastomer cost volatility directly into hospital procurement negotiations, concentrating pricing power among kit assemblers with captive polymer extrusion capacity while forcing smaller competitors toward ISO 13485 certification arbitrage in Costa Rica.
Pricing Analysis
Cost-plus contracts indexed to medical-grade silicone feedstock benchmarks dominate procurement agreements between catheter manufacturers and integrated delivery networks. Price differentiation rests on FDA 510(k) clearance tier and volume scale, with emergency kit configurations commanding premium positioning against standard drainage assemblies. Pricing pressure stems from European notified body bottlenecks extending CE marking timelines, compressing margin recovery for manufacturers dependent on dual-market revenue. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge protocol economics, while Level I trauma centers prioritize deployment speed over unit cost.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities have become standard for polymer extrusion houses serving kit assemblers, transferring working capital burden upstream while preserving downstream liquidity. Geographic concentration centers on Malaysia, Costa Rica, and Germany for catheter assembly, with medical-grade silicone sourcing tethered to Japanese and German chemical producers. Single-source vulnerability runs through specialized multi-lumen extrusion operators requiring 3-5 year training horizons. Distribution runs through GPO contracts managers and hospital value-analysis committees consolidating purchasing into acute care episode bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colon decompression kits market exhibits cyclical recovery characteristics anchored to elective procedure scheduling patterns and trauma preparedness mandate cycles.
For Market Incumbents: Pre-empt endoscopic stent substitution in oncology populations by embedding pressure telemetry into automated catheter platforms, creating subscription revenue stickiness. Deepen backward integration into silicone elastomer compounding to insulate margins from petrochemical index volatility. Prioritize physician training infrastructure deployment in Texas and Florida ASC networks before competitor channel lock-in solidifies. For New Entrants and Emerging Players: Pursue emergency kit white-space in Level II trauma centers facing federal preparedness mandates with underdeveloped supplier relationships. Target home care channels despite reimbursement constraints, leveraging telehealth-enabled remote monitoring as differentiated entry angle. Lead with rapid-deployment packaging innovation and color-coded connection protocols that compress non-specialist operator learning curves. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core interventional catheter portfolios. Long-term viability hinges on automated system subscription economics and ASC network penetration depth. Watch FDA breakthrough device designation velocity as inflection signal for platform technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | European MDR notified body engagement determines 18-24 month market entry timelines for catheter manufacturers. |
| Hospital System Partnership | Integrated delivery network contracting offices in California and Pennsylvania centralize procurement authority into multi-year agreements. |
| Software Companion Development | Real-time pressure telemetry integration with Epic and Cerner EHR systems eliminates middleware friction for community hospitals. |
| Reimbursement Strategy | CMS procedural coding decisions for decompression devices shape acute care episode payment bundling and margin pools. |
| Backward Integration | In-house polymer extrusion capacity insulates manufacturers from medical-grade silicone feedstock price volatility and technician scarcity. |
Study Parameters
Operator-level perspectives from interventional gastroenterologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up procedure volume estimates triangulated against top-down market sizing across catheter architecture segments.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories by product type, end user channel, clinical application, and automation technology tier. CAGRs derived from procedure volume elasticity to aging demographic cohorts and trauma preparedness mandate expansion. Forecast inputs incorporated silicone elastomer price indices, notified body capacity constraints, and ASC network growth curves.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock costs, freight corridor rates, or hospital capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance timelines and reimbursement stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Anti Venom Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Pressure Relief Mattress Market