
 Breast Shells Market | 2026-2036
Breast Shells Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Shells Market Intelligence
Subscription-based replacement programs for breast shell components is expanding how manufacturers monetize patient relationships beyond initial device sales. Medela leverages its hospital-grade pump ecosystem to anchor recurring shell purchases through bundled lactation support services. Philips Avent competes via retail channel control, sustaining shelf visibility across pharmacy chains in Western Europe. Pigeon Corporation specializes in contoured silicone designs, dominating maternity specialty stores across East Asian markets.
Breast shells are medical-grade or consumer silicone, plastic, hydrogel, or foam devices shaped as round, oval, or contoured forms that create protective space between breast tissue and clothing to promote healing, milk collection, or comfort. Most silicone variants employ food-grade platinum-cured elastomer with wall thickness between 0.8 and 1.5 millimeters to balance pliability with structural retention. Post-surgery and nursing usage segments lead volume, while cosmetic applications command higher per-unit margins due to custom fitting requirements. Online retail distribution is accelerating fastest, though hospital procurement channels still capture the bulk of post-surgical volume in reimbursed markets.
The FDA's 510(k) clearance pathway governs breast shells marketed for medical indications in the United States, while the EU Medical Device Regulation (MDR) mandates notified body certification for post-surgical shell claims across European member states. Japan's Ministry of Health, Labour and Welfare (MHLW) via PMDA oversight adds another compliance layer for silicone-based devices intended for nursing support. Stakeholders must monitor evolving MDR clinical evidence requirements and reimbursement coding changes that could shift competitive advantage between direct-to-consumer and clinical-channel business models.
Market Dynamics
Post-surgical recovery protocols in ambulatory surgical centers are compressing hospital stays and shifting breast shell procurement toward outpatient reimbursement codes, altering volume concentration across clinical channels.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter notified body certification for post-surgical claims is filtering out lower-quality competitors and consolidating certified manufacturer market presence across Germany, France, and Italy.
- Platinum-cured silicone adoption:Food-grade elastomer formulations with 0.8-1.5 millimeter wall thickness are displacing lower-grade alternatives in reimbursed markets due to superior biocompatibility profiles and extended wear durability.
- Ambulatory surgical center expansion:Same-day discharge protocols for breast reconstruction are routing device procurement through outpatient durable medical equipment channels rather than inpatient supply chains.
Market Restraints
- Silicone raw material concentration:Platinum-cured elastomer supply clusters among specialty chemical producers in Germany and Japan, exposing manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) pathway friction:Medical indication claims require substantial equivalence demonstrations that extend clearance timelines for novel shell geometries or material innovations.
- Hydrogel substitute encroachment:Cooling and compression alternatives for post-surgical recovery are capturing price-sensitive segments unwilling to pay silicone premiums.
Strategic Opportunities
- Japan nursing support segment:PMDA oversight of silicone-based devices creates compliance barriers that favor established entrants with regulatory affairs infrastructure already deployed.
- Direct-to-consumer channel expansion:Online retail distribution is bypassing traditional pharmacy and hospital procurement gatekeepers, enabling margin capture and patient data accumulation.
- Subscription replacement programs:Component refresh models for shells and liners are converting one-time device sales into recurring revenue streams anchored to lactation support services.
Industry Challenges
- MDR technical documentation gaps:Clinical evidence requirements for post-surgical claims are forcing retrospective data collection that delays product line extensions and geographic expansion.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies are bottlenecking at contract laboratories, extending time-to-market for material formulation changes.
- Legacy hospital procurement integration:Electronic health record and materials management system compatibility issues are complicating automated reorder workflows for outpatient surgical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Shells Market |
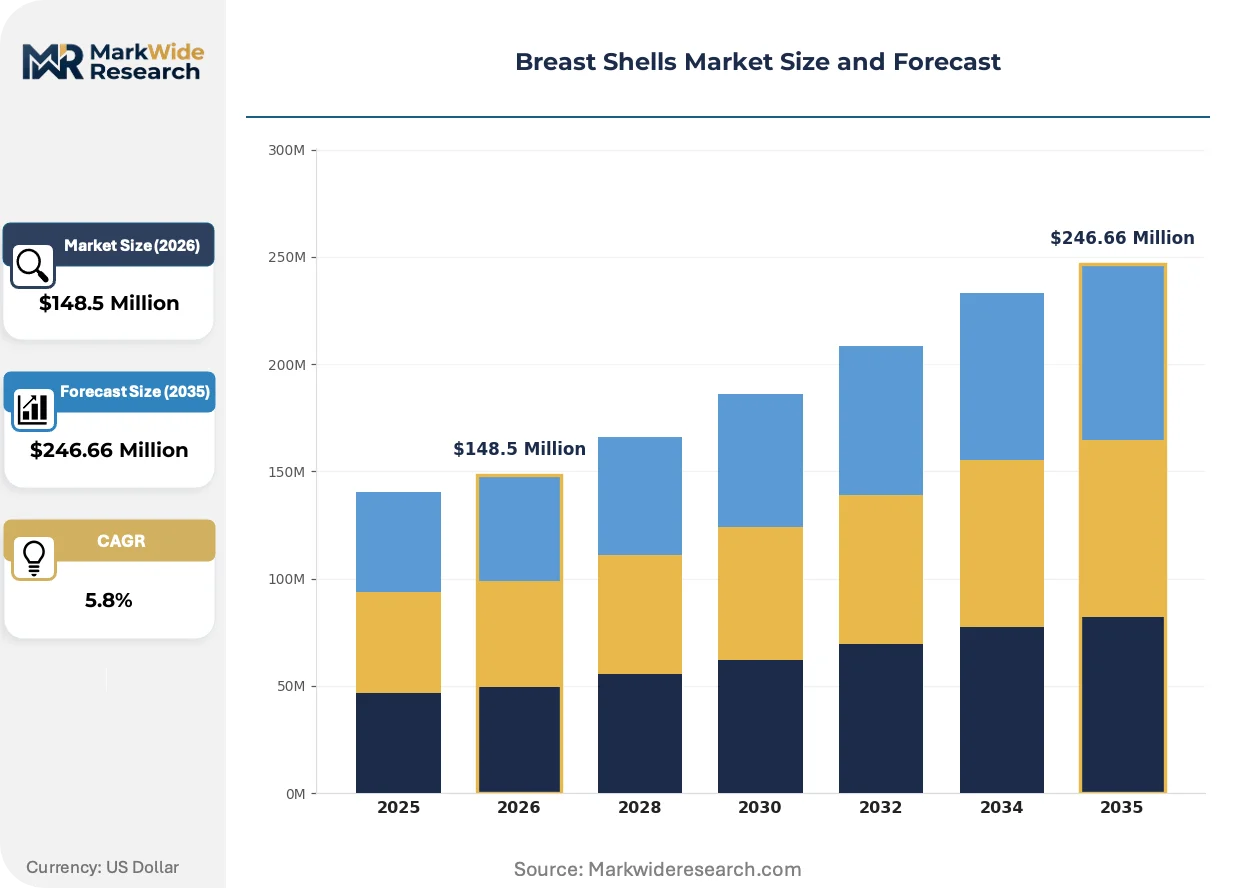
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $246.66 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Shells, Plastic Shells, Hydrogel Shells, Foam Shells Form: Round, Oval, Contoured, Custom Usage: Post-Surgery, Nursing, Comfort, Cosmetic Distribution Channel: Online Retail, Pharmacies, Hospitals, Specialty Stores |
| Companies Covered | Medela, Koninklijke Philips N.V. (Philips Avent), Pigeon Corporation, Newell Brands, Lansinoh Laboratories, Inc., Ameda, Inc., Ardo Medical Ltd., Silverette, Chicco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Shells Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization pressures are compressing product development cycles while channel fragmentation is redistributing buyer power across direct and institutional pathways.
Contoured silicone designs with anatomically matched geometries are expanding into post-mastectomy recovery applications where flat or round legacy shapes created pressure points and tissue compromise. Reconstructive surgeons in German university hospitals are adopting these variants fastest, driven by reimbursement coverage for custom-fitted accessories. The shift is compressing demand for standardized shell formats and elevating premium pricing tiers for patient-matched solutions.
REACH substance restrictions on certain plasticizers are forcing reformulation of polycarbonate and thermoplastic elastomer shell components intended for European markets. Manufacturers with centralized EU regulatory affairs functions are responding faster than those managing compliance through distributed country offices. The regulatory pressure is most acute for economy-tier products that previously relied on cost-optimized material specifications now facing authorization sunset dates.
Hospital materials management departments are unbundling after-sales service from device procurement, negotiating shell purchases separately from fitting consultation and patient education components. This purchasing behavior change is disrupting bundled pricing models that historically cross-subsidized clinical support through device margins. The unbundling is most visible in United States health systems operating under value-based care contracts where line-item cost transparency is mandatory.
Breast Shells Market Segmentation
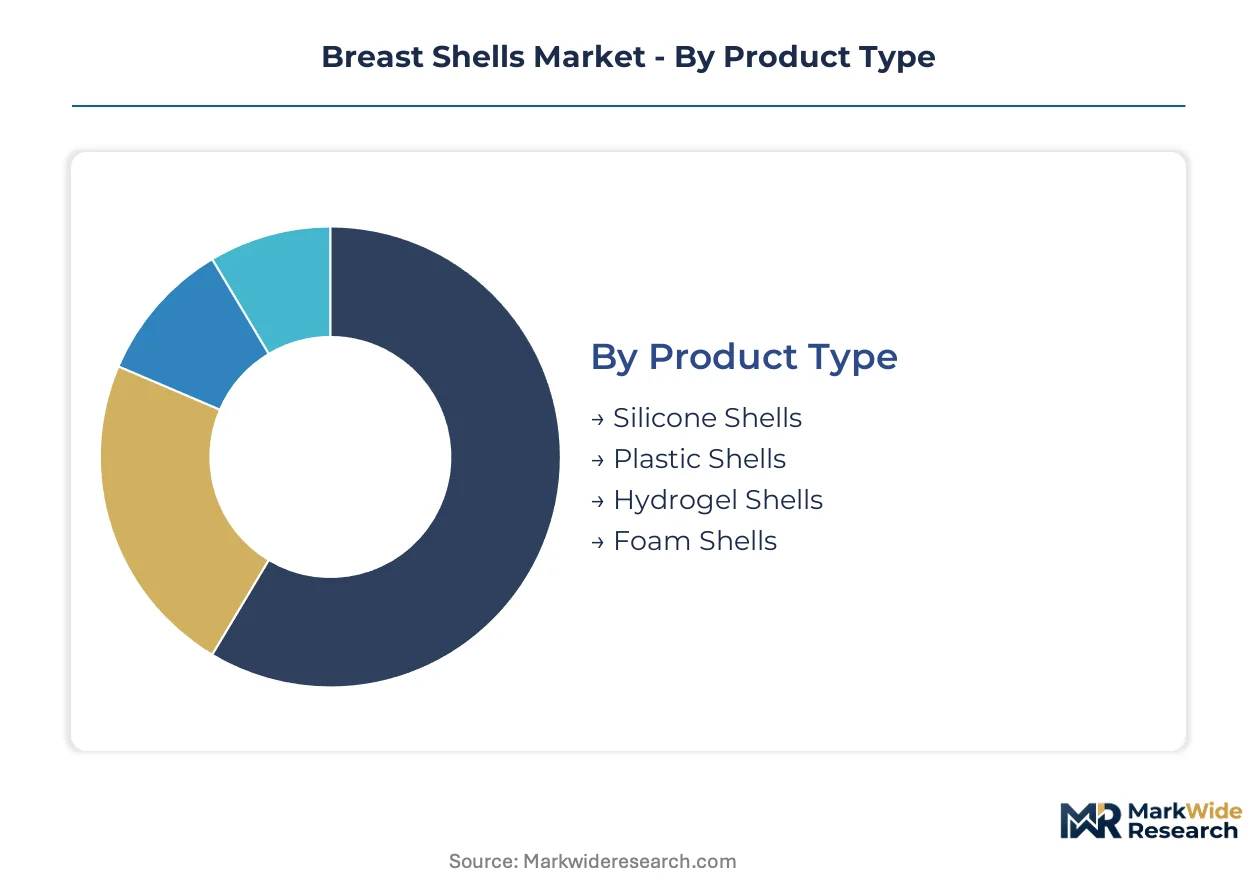
Breast shell manufacturers engineer distinct product architectures to match tissue interaction requirements across post-surgical recovery, lactation support, and cosmetic applications. Material selection and geometric configuration directly determine reimbursement eligibility, wear duration, and patient compliance rates in clinical versus consumer channels.
Product Type:
Replacement cycles for breast shell components vary dramatically by material chemistry, with platinum-cured silicone formulations commanding premium refresh intervals versus disposable foam alternatives.
- Silicone Shells:Food-grade platinum-cured elastomer constructions with 0.8-1.5 millimeter wall thickness balance pliability against structural retention for extended wear protocols. German ambulatory surgical centers route procurement through reimbursed durable medical equipment channels, favoring biocompatibility certifications that satisfy EU MDR clinical evidence mandates.
- Plastic Shells:Polycarbonate and thermoplastic elastomer variants serve price-sensitive segments with shorter replacement horizons. REACH substance restrictions on legacy plasticizers are forcing reformulation timelines that disadvantage manufacturers without centralized EU regulatory affairs infrastructure.
- Hydrogel Shells:Cooling and compression properties target post-surgical recovery segments seeking alternatives to silicone premiums.
- Foam Shells:Single-use disposable economics dominate maternity ward sampling programs and initial patient trial kits.
Volume placements concentrate in Silicone Shells; the faster expansion belongs to Hydrogel Shells.
Form:
Geometric precision in shell architecture determines pressure distribution patterns and tissue compromise risk in post-mastectomy applications.
- Round:Legacy standardized formats face compressing demand as reconstructive protocols prioritize anatomical matching over inventory efficiency.
- Oval:Intermediate geometries capture transitional demand from hospitals modernizing fitting workflows toward contoured alternatives.
- Contoured:Anatomically matched silicone designs with patient-specific curvature mapping are expanding fastest in German university hospital systems where reimbursement coverage for custom-fitted accessories is strongest.
- Custom:Patient-matched solutions command premium pricing tiers through direct-to-consumer channels that bypass traditional procurement gatekeepers.
Contoured variants are climbing the fastest as reimbursement frameworks shift toward outcome-based accessory coverage.
Usage:
Application context dictates material specification, wear protocol, and channel economics across the breast shell value chain.
- Post-Surgery:Medical-grade silicone constructions with FDA 510(k) clearance or EU MDR certification dominate reimbursed procurement through ambulatory surgical center channels.
- Nursing:Lactation support applications concentrate volume in maternity specialty retail, with subscription replacement programs converting one-time sales into recurring revenue anchored to pump ecosystem bundling.
- Comfort:Non-medical positioning applications in direct-to-consumer channels face lower regulatory barriers but compressed margins.
- Cosmetic:Custom fitting requirements command highest per-unit margins through aesthetic clinic channels, though volume remains constrained by elective procedure cyclicality.
Post-Surgery captures the steepest expansion trajectory as same-day discharge protocols proliferate across reimbursed markets.
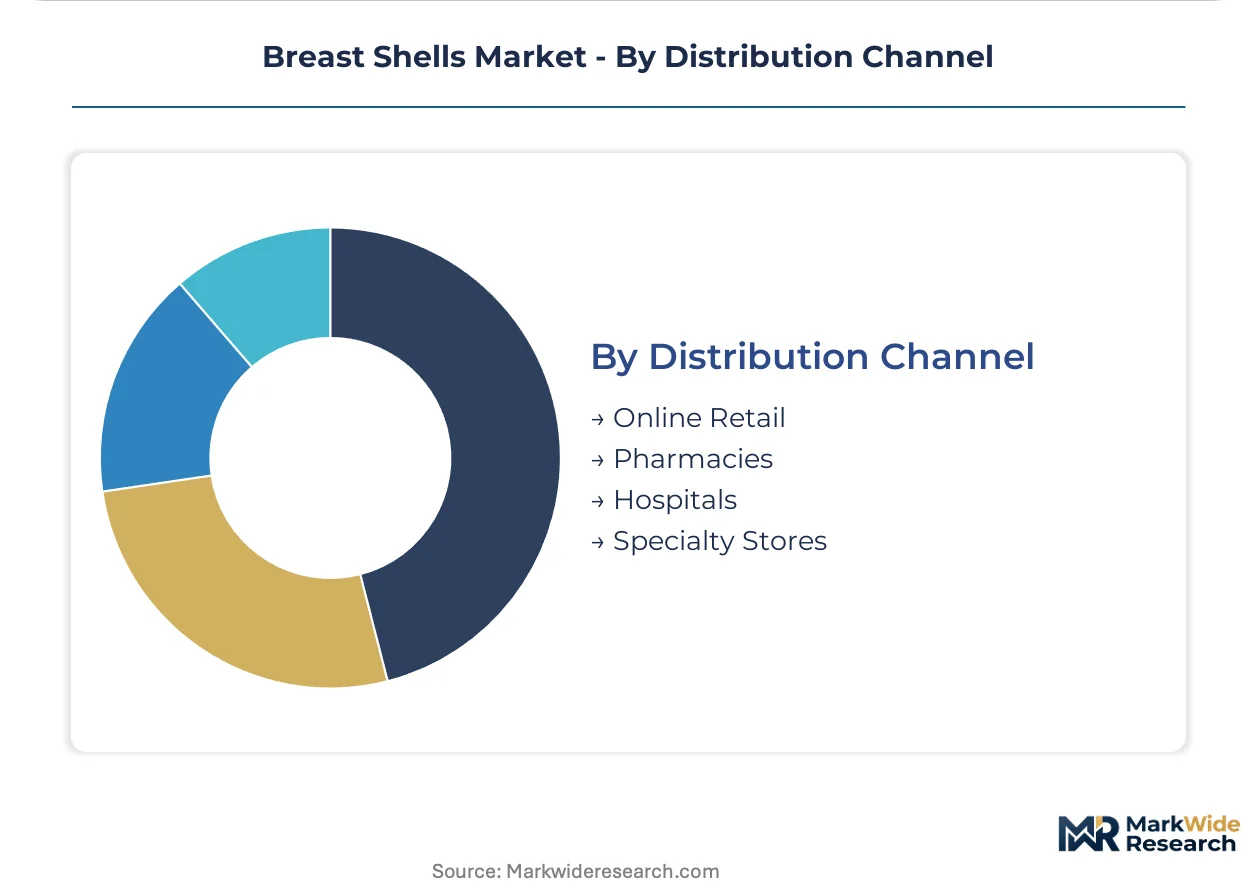
Distribution Channel:
Channel fragmentation is redistributing buyer power between institutional procurement gatekeepers and direct patient access models.
- Online Retail:Direct-to-consumer expansion enables margin capture and patient data accumulation outside traditional pharmacy and hospital procurement hierarchies.
- Pharmacies:Western European chains maintain shelf visibility for consumer-grade nursing applications, though cross-selling to clinical segments faces reimbursement coding friction.
- Hospitals:Inpatient and outpatient materials management departments still capture bulk post-surgical volume in reimbursed markets, with electronic health record integration complicating automated reorder workflows.
- Specialty Stores:Maternity-focused retail in East Asian markets concentrates demand for contoured silicone designs with localized fitting services.
Hospital procurement maintains volume concentration; online retail is gaining share fastest through subscription component refresh models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European demand concentration for post-surgical breast shells, with university hospital procurement networks radiating reimbursement-covered volume across southern Germany.
United States
FDA 510(k) clearance pathways govern medical indication claims, with ambulatory surgical centers in Texas and Florida driving outpatient procurement volume through durable medical equipment channels.
Germany
EU MDR notified body certification filters competitor entry, while REACH substance restrictions force reformulation of polycarbonate components in the Ruhr industrial corridor's specialty chemical production.
Japan
PMDA oversight of silicone-based nursing devices creates compliance barriers favoring established entrants, with Tokyo metropolitan maternity specialty retail concentrating demand for contoured designs.
United Kingdom
NHS procurement frameworks for post-mastectomy accessories route volume through designated medical device suppliers, with Greater London hospital trusts piloting unbundled service contracting.
Australia
TGA medical device regulations align with MDR evidence standards, while Melbourne and Sydney private reconstructive surgery clinics drive premium-tier custom-fitted shell adoption.
Breast Shells Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the breast shell value chain, with medical-grade silicone manufacturing concentrating among specialized elastomer compounders while direct-to-consumer brands outsource fabrication. The vendor base stratifies across three archetypes: hospital-grade pump ecosystem bundlers, retail channel shelf-space controllers, and maternity specialty contoured-design specialists. M&A activity targets regulatory affairs infrastructure and subscription platform capabilities, while geographic expansion prioritizes PMDA-compliant market entry in East Asia.
Among Swiss-based pump ecosystem specialists, Medela exemplifies the hospital-grade bundling archetype through lactation support service integration. Koninklijke Philips N.V. occupies a position as a retail channel anchor with pharmacy chain visibility across Western Europe. Pigeon Corporation represents the contoured silicone specialization archetype dominating East Asian maternity retail. These three players illustrate how regulatory infrastructure investment and channel control separate tier positions in reimbursed versus consumer markets.
| Leading Market Players |
|---|
| Medela |
| Koninklijke Philips N.V. (Philips Avent) |
| Pigeon Corporation |
| Newell Brands |
| Lansinoh Laboratories, Inc. |
| Ameda, Inc. |
| Ardo Medical Ltd. |
| Silverette |
| Chicco |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap silicone compounders in southern Germany and Osaka prefecture anchor platinum-cured elastomer supply, translating raw material scarcity into disciplined pricing tiers that resist commoditization pressure from hydrogel substitutes.
Pricing Analysis
Value-based pricing anchored to EU MDR certification tiers stratifies the market across premium medical-grade silicone, standard consumer variants, and economy foam disposables. Price differentiation rests on biocompatibility certification depth and after-sales bundling intensity, with German ambulatory surgical centers least sensitive due to reimbursement coverage while direct-to-consumer nursing segments face acute cost compression from private-label entrants. Pricing pressure stems from hydrogel cooling alternatives capturing price-sensitive post-surgical recovery volumes unwilling to pay silicone premiums.
Supply Chain Analysis
Freight cost volatility from Asia-Europe routes is reshourcing component fabrication toward Czech and Polish contract manufacturers serving EU markets. Geographic supply concentrates in Germany, Japan, and China for platinum-cured silicone, polycarbonate resins, and hydrogel polymers respectively. Raw material dependencies span medical-grade silicone elastomer, food-safe colorants, and antimicrobial additives. Single-source vulnerability in German specialty chemical producers exposes manufacturers to allocation constraints. Distribution runs through hospital materials management systems, pharmacy chain logistics, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platinum-cured silicone capacity constraints at notified-body-certified compounders prop pricing discipline, creating supply-constrained conditions that favor incumbents with locked-in raw material offtake.
For Market Incumbents: Deploy subscription platform infrastructure to convert one-time device sales into recurring revenue streams anchored to lactation support services. Defensive consolidation should prioritize backward integration into platinum-cured silicone compounding to secure input supply against allocation risk from German and Japanese specialty chemical producers. Channel control investments in electronic health record integration will automate reorder workflows for ambulatory surgical centers facing unbundled procurement mandates.
For New Entrants and Emerging Players: Direct-to-consumer contoured design tools represent the most penetrable wedge, bypassing hospital procurement gatekeepers through online retail distribution with patient-matched fitting algorithms. White-space targets include Japan's nursing support segment where PMDA compliance barriers disadvantage asset-light competitors, and Australia's private reconstructive surgery clinics seeking premium-tier custom solutions. Go-to-market execution should anchor on influencer-led education campaigns targeting post-mastectomy patient communities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regulatory affairs infrastructure plays in EU MDR transition markets where clinical evidence backlogs are forcing smaller competitors toward exit. Long-term viability over a decade horizon hinges on subscription platform capabilities and PMDA-compliant market access in East Asia. Acquisition target archetypes include contoured-design specialists with maternity retail channel control and notified-body-certified manufacturers with retrospective clinical data libraries. The signal to watch is REACH substance restriction enforcement accelerating reformulation costs for polycarbonate-dependent economy-tier producers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Clinical evidence mandates filter competitors and consolidate certified manufacturer presence across reimbursed European markets. |
| Subscription Component Replacement Programs | Recurring revenue models anchored to lactation support services convert one-time device sales into predictable income streams. |
| Direct-to-Consumer Channel Expansion | Online retail bypasses pharmacy and hospital procurement gatekeepers, enabling margin capture and patient data accumulation. |
| Backward Integration into Silicone Compounding | In-house platinum-cured elastomer production secures supply against allocation constraints from German and Japanese specialty chemical producers. |
| Electronic Health Record Integration | Automated reorder workflows address unbundled procurement mandates in United States health systems under value-based care contracts. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and lactation consultants. FDA 510(k) clearance databases, EU MDR notified body certification registries, and PMDA device listings provided structured secondary validation. Bottom-up volume estimates from ambulatory surgical center procurement records reconciled against top-down market sizing from durable medical equipment channel audits.
Reconciliation of shipment data, reimbursement coding analysis, and patient discharge protocol surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, geometric form, application context, and distribution channel archetype. CAGRs derived from weighted average of historical volume trajectories and protocol adoption curves, with specific inputs from post-mastectomy same-day discharge rate projections and nursing support subscription attach rate assumptions.
Several conditions sit outside the modeled scope, including regulatory timeline delays, raw material allocation shocks, and reimbursement coding revisions. Forecasts reflect assumptions about protocol adoption and certification completion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Trauma Products Market
Medical Supplies
Centrifuge Bottles Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Europe Hospital Supplies Market