
 Woven Medical Tape Market | 2026-2036
Woven Medical Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Woven Medical Tape Market Analytics
Home care is pivoting toward woven medical tape solutions as post-acute patients seek alternatives to extended hospital stays. 3M leverages its adhesive science portfolio to dominate high-performance breathable tape segments. Johnson & Johnson sustains brand strength across hospital procurement channels with broad cotton and silk tape lines. Smith & Nephew specializes in advanced wound care applications, anchoring its position through clinical validation protocols.
Woven medical tape comprises a fabric substrate—typically cotton, silk, or synthetic weave—coated with medical-grade acrylic or zinc-oxide adhesive, designed to secure dressings and devices while permitting moisture vapor transmission. Cotton tape maintains volume leadership in general-purpose hospital settings where cost efficiency governs procurement decisions. Elastic tape captures expanding share in sports medicine and ambulatory surgery centers where conformability and dynamic support matter. Breathable functionality commands premium positioning as clinicians prioritize skin integrity during extended wear periods.
FDA biocompatibility standards under ISO 10993 govern adhesive safety for prolonged skin contact, while EMA MDR requirements enforce traceability and clinical evidence for European market access. Japan's PMDA maintains stringent quality protocols that favor established manufacturers with documented manufacturing histories. Stakeholders must monitor evolving polymer regulations and patient-shift economics to align portfolio development with where care delivery actually moves.
Market Dynamics
Patient migration toward home-based recovery is compressing hospital procurement cycles while amplifying demand for breathable, skin-safe adhesives that tolerate extended wear without clinical supervision.
Growth Catalysts
- ISO 10993 biocompatibility mandates:FDA enforcement of cytotoxicity and sensitization testing is elevating adhesive chemistry standards, disqualifying commodity suppliers and expanding addressable market for validated manufacturers.
- Japan's aging demographic:PMDA-registered tape demand accelerates as chronic wound prevalence rises among patients over 65 requiring long-term dressing retention.
- Silicone-acrylic hybrid adhesives:Advanced polymer formulations enable gentler removal trajectories, opening pediatric and geriatric segments previously closed to traditional zinc-oxide tapes.
Market Restraints
- Medical-grade cotton supply volatility:Egyptian and Indian long-staple cotton price swings compress margin predictability for woven substrate producers.
- EMA MDR clinical evidence requirements:Extended device-class certification timelines delay European market entry for novel tape constructions by 18-24 months.
- Film-based adhesive alternatives:Transparent polyurethane dressings with integrated fixation zones substitute woven tape in IV catheter and surgical drape applications.
Strategic Opportunities
- German ambulatory surgery centers:Outpatient procedure volume expansion creates demand for elastic, conformable tapes supporting mobilization protocols.
- Telehealth-integrated wound monitoring:Smart dressings with embedded sensors require compatible adhesive substrates, converging electronics with medical textiles.
- US IRA preventive care incentives:Medicare reimbursement shifts favor home-based chronic wound management, expanding durable medical equipment channel penetration.
Industry Challenges
- Adhesive polymer chemist scarcity:Formulation expertise at the intersection of skin biology and pressure-sensitive adhesion commands premium compensation and extended recruitment cycles.
- ISO 13485 quality management implementation:Small and mid-size converters face capital-intensive cleanroom and traceability infrastructure upgrades to maintain hospital supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woven Medical Tape Market |
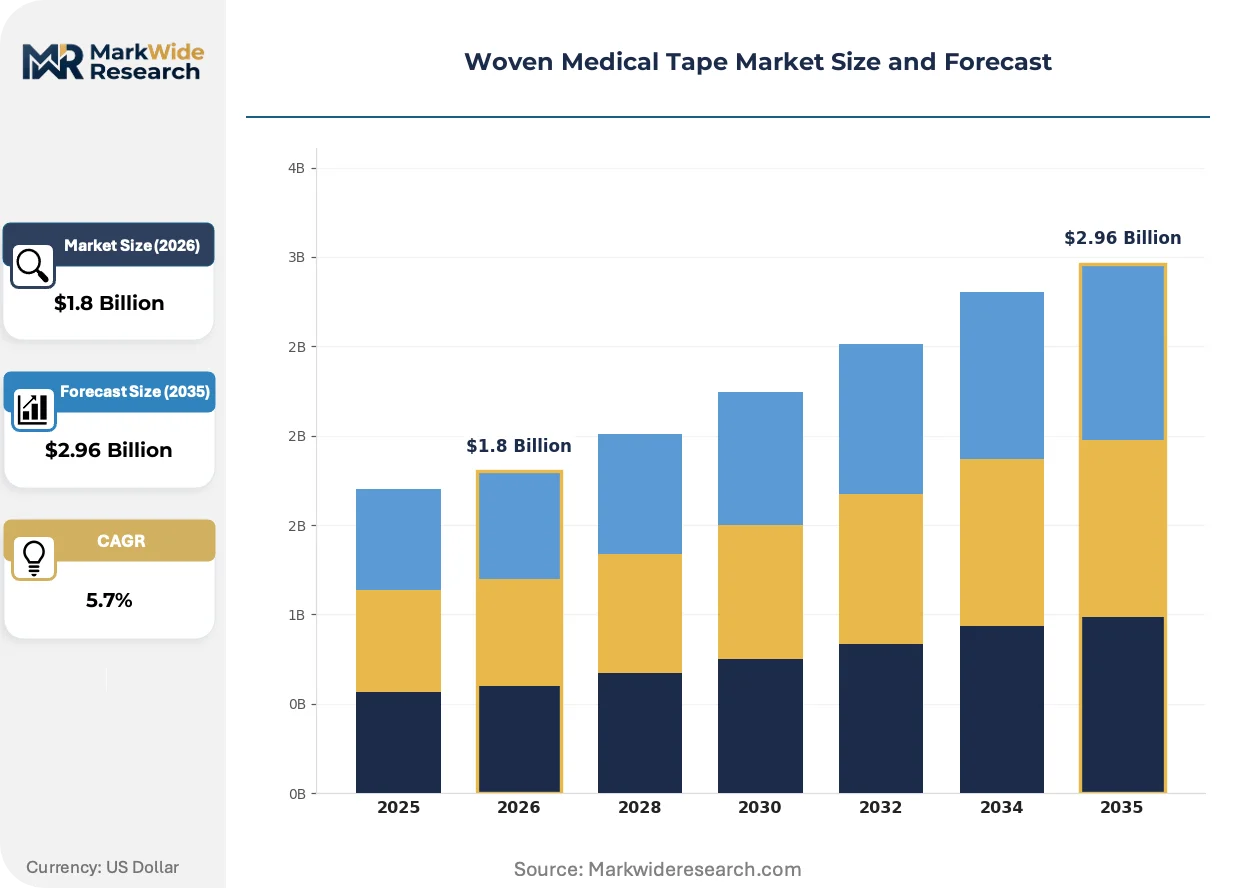
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silk Tape, Cotton Tape, Adhesive Fabric Tape, Elastic Tape End User: Hospitals, Clinics, Home Care, Ambulatory Surgery Centers Application: Wound Care, Surgical Procedures, Dressings, Sports Medicine Functionality: Breathable, Waterproof, Lightweight, Stretchable |
| Companies Covered | 3M, Johnson & Johnson, Smith & Nephew, Medtronic, NICHIBAN Co., Ltd., Berry Global, Inc, Cardinal Health, Avery Dennison Corporation, Tekra Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woven Medical Tape Market Evolving Landscape
Breathable adhesive technologies and regulatory harmonization pressures are converging to redefine product specifications and procurement criteria across wound care and device fixation applications.
Silicone-acrylic hybrid adhesive systems are rewriting the performance envelope for extended-wear medical tapes. Post-acute home care nurses in the United States and Germany are adopting these formulations at accelerating rates for patients requiring 7-14 day dressing intervals. The technology is compressing replacement frequency and reducing skin trauma incidence, shifting value capture toward premium-tier suppliers with polymer science capabilities.
EMA Medical Device Regulation (MDR) traceability mandates are restructuring European supply chain documentation. Manufacturers must now maintain clinical evidence portfolios and unique device identifiers for adhesive tapes previously classified as low-risk accessories. German and French hospital procurement consortia are consolidating supplier lists to entities with established MDR technical files, accelerating market concentration.
Home care distributors are disintermediating traditional hospital supply intermediaries as wound care consumption shifts to residential settings. United States durable medical equipment providers and German pharmacy networks are capturing direct patient relationships previously managed by acute-care materials management departments. This channel rotation is most visible in diabetes-related foot ulcer management, where patients self-administer dressing changes with telehealth oversight.
Woven Medical Tape Market Segmentation
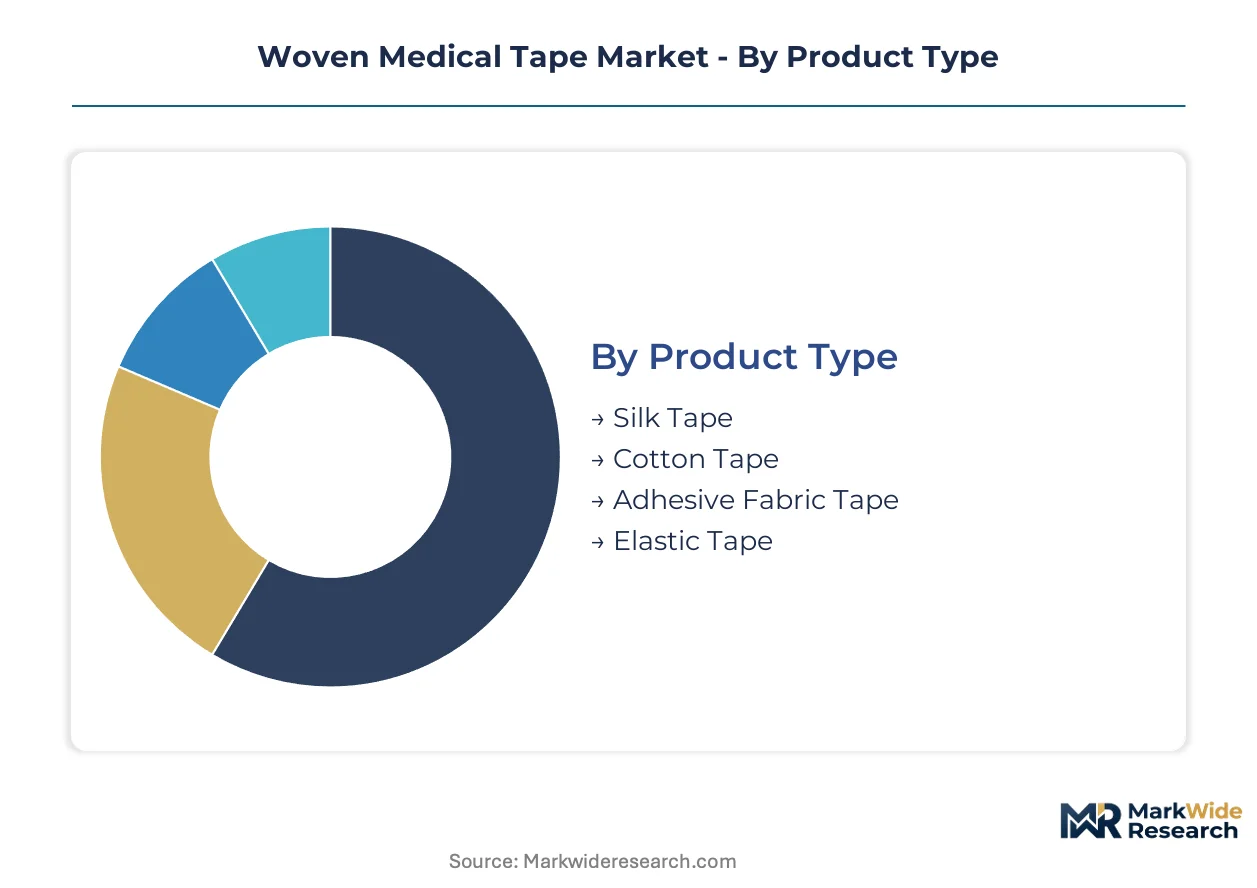
Woven medical tape segmentation reveals how substrate chemistry, care setting economics, and functional specifications fragment procurement patterns across acute and post-acute channels. Manufacturers configure product portfolios around the tension between high-volume cotton commoditization and premium silicone-acrylic hybrid positioning.
Product Type:
Cotton tape dominates procurement volumes in cost-sensitive hospital settings, while silk and elastic variants capture margin through specialized conformability and extended-wear performance.
- Cotton Tape:Woven from long-staple Egyptian or Indian cotton fibers coated with zinc-oxide or acrylic adhesives, cotton tape serves general-purpose dressing fixation in United States and German hospital systems where unit economics govern formulary decisions. Volume concentration in central supply procurement creates pricing pressure that favors converters with backward integration into textile sourcing.
- Elastic Tape:Spandex-cotton or synthetic weave constructions deliver longitudinal and latitudinal stretch for dynamic support applications. German ambulatory surgery centers and United States sports medicine clinics are expanding procurement of these conformable substrates for post-operative mobilization protocols where rigid fixation impedes rehabilitation.
- Silk Tape:Fine-weave silk substrates provide low-profile, hypoallergenic fixation for facial and pediatric applications requiring minimal adhesive mass.
- Adhesive Fabric Tape:Synthetic-polyester or rayon-based woven backings offer moisture resistance and dimensional stability for device fixation in humid environments.
Mature deployment sits with cotton tape across legacy hospital supply chains. Newer deployment is concentrated in elastic tape as outpatient procedure volumes expand.
End User:
Channel economics are fragmenting as wound care consumption migrates from centralized materials management to distributed patient-direct fulfillment.
- Hospitals:Integrated delivery networks in the United States and German university hospitals maintain formulary-controlled procurement of cotton and silk tapes through group purchasing organizations, prioritizing ISO 13485-certified suppliers with documented biocompatibility testing.
- Home Care:Durable medical equipment providers and pharmacy networks are capturing direct patient relationships for chronic wound management, driving demand for breathable, extended-wear adhesives that tolerate 7-14 day intervals without clinical supervision.
- Clinics:Outpatient wound centers and dermatology practices require rapid-turnover tape inventories with diverse size configurations.
- Ambulatory Surgery Centers:German and United States freestanding surgical facilities prioritize elastic and lightweight tapes supporting same-day discharge protocols.
Procurement authority is concentrating in hospital supply chains. Patient-direct channel expansion is climbing the fastest as reimbursement shifts favor home-based recovery.
Application:
Clinical use case determines adhesive specification, wear duration, and replacement frequency across acute intervention and chronic maintenance settings.
- Wound Care:Chronic ulcer management—diabetic foot, venous stasis, pressure injuries—requires breathable, moisture-vapor-permeable tapes securing advanced dressings for extended intervals. United States home care nurses and German community nursing services are standardizing on silicone-acrylic hybrids for gentler removal trajectories in fragile skin populations.
- Surgical Procedures:Operating room fixation demands conformable substrates maintaining adhesion under irrigation and draping stress, with elastic tape gaining preference in German orthopedic and United States cardiovascular suites for dynamic support.
- Dressings:General-purpose gauze and composite dressing retention represents volume concentration in cotton tape.
- Sports Medicine:Athletic training and rehabilitation applications favor high-tack elastic tapes with cohesive properties enabling joint support without rigid immobilization.
Volume deployment remains anchored in surgical dressing fixation. Steepest expansion trajectory is visible in wound care as aging demographics amplify chronic condition prevalence.
Functionality:
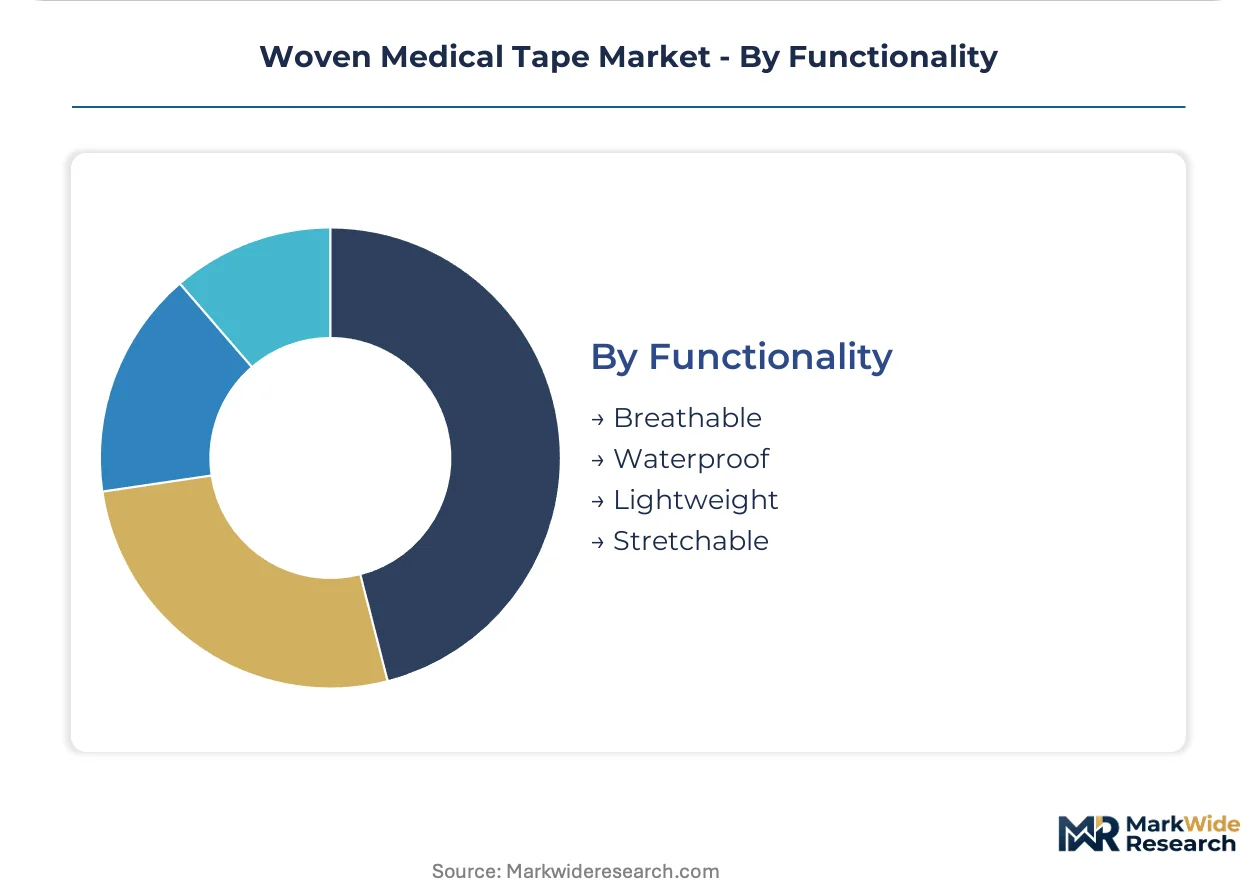
Performance attributes are segmenting price tiers and regulatory qualification pathways as clinicians prioritize skin integrity outcomes.
- Breathable:Acrylic adhesive systems with microporous coatings permit moisture vapor transmission rates exceeding standard zinc-oxide formulations, commanding premium positioning in United States post-acute and German long-term care settings where maceration prevention drives formulary decisions.
- Stretchable:Elastomeric adhesive and substrate combinations enable dynamic conformity to joint movement and tissue edema, penetrating German ambulatory surgery and United States orthopedic rehabilitation channels.
- Waterproof:Polyurethane-coated or film-laminated woven constructions resist fluid penetration for shower-tolerant dressing protection.
- Lightweight:Low-basis-weight substrates reduce adhesive mass for pediatric, geriatric, and facial applications requiring minimal mechanical loading.
Established functionality resides in standard breathable constructions. Emerging specification concentration is visible in stretchable formats as mobilization protocols shorten hospital stays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the United States, Germany, and Japan concentrate woven medical tape manufacturing capacity through tariff-advantaged import-export corridors and specialized medical device clusters.
United States
Post-acute home care expansion and Medicare reimbursement shifts toward outpatient wound management drive procurement of breathable silicone-acrylic tapes. FDA ISO 10993 biocompatibility enforcement elevates adhesive chemistry standards, disqualifying commodity suppliers. Minneapolis-St. Paul anchors 3M's adhesive science operations, while Cardinal Health distributes through integrated delivery networks across the Midwest and Southeast.
Germany
Ambulatory surgery center proliferation and aging demographic chronic wound prevalence accelerate demand for elastic, conformable tapes. EMA MDR traceability mandates compress European supplier lists to entities with established technical files. Baden-Württemberg's medical technology corridor around Tübingen and Freiburg hosts specialized converters serving university hospital procurement consortia.
Japan
PMDA-registered tape demand intensifies as patients over 65 require long-term dressing retention for diabetic foot and pressure injuries. METI industrial standards favor manufacturers with documented quality histories spanning decades. Osaka-Kobe manufacturing clusters supply domestic hospital systems while exporting premium silk and cotton constructions across Asia-Pacific.
United Kingdom
NHS procurement consolidation and community nursing service expansion shift volume toward home-care-compatible breathable adhesives. MHRA post-Brexit regulatory autonomy maintains alignment with ISO 13485 quality protocols. Greater Manchester and West Midlands industrial zones host contract converters serving NHS Supply Chain formulary decisions.
China
Domestic medical device self-sufficiency policies and hospital procurement localization mandates redirect volume toward NMPA-registered domestic manufacturers. Yangtze River Delta special economic zones in Suzhou and Shanghai concentrate woven substrate and adhesive coating capacity for both domestic consumption and export assembly.
Woven Medical Tape Market Competitive Landscape
Top-tier vendors anchor premium silicone-acrylic and breathable tape segments, while mid-tier converters compete on cotton substrate volume and regional distribution density. Market structure tilts toward consolidation as EMA MDR and FDA biocompatibility requirements raise qualification barriers. Three archetypes dominate: diversified adhesive science conglomerates, specialized wound care houses, and regional textile converters. Competitive moves concentrate on backward integration into medical-grade cotton sourcing and strategic partnerships with home care distributors.
Among diversified adhesive science conglomerates, 3M and Avery Dennison Corporation occupy positions exemplifying polymer formulation capabilities spanning industrial and medical applications. Johnson & Johnson and Smith & Nephew represent the specialized wound care archetype, anchoring clinical validation-intensive segments where hospital formulary acceptance determines market access. NICHIBAN Co., Ltd. sits within the precision-converter tier, reflecting Japanese manufacturing quality protocols and PMDA-registered export positioning.
| Leading Market Players |
|---|
| 3M |
| Johnson & Johnson |
| Smith & Nephew |
| Medtronic |
| NICHIBAN Co., Ltd. |
| Berry Global, Inc |
| Cardinal Health |
| Avery Dennison Corporation |
| Tekra Corporation |
| Others |
Value Network & Pricing Analysis
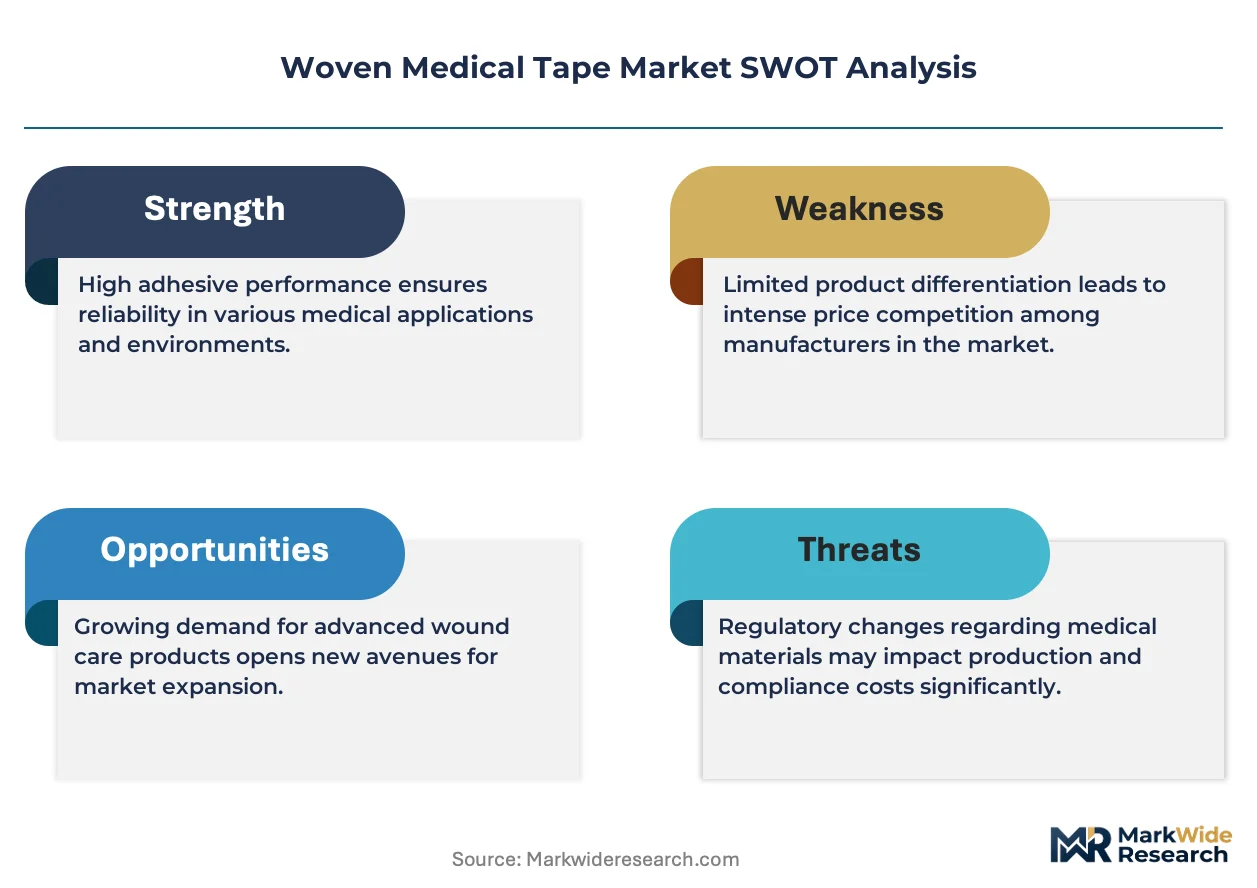
Silicone-acrylic hybrid adhesive manufacturing is compressing production economics for converters lacking polymer science capabilities while concentrating margin capture among backward-integrated specialists with captive coating operations. This technology transition simultaneously elevates quality-tier pricing thresholds and disqualifies commodity substrate suppliers from hospital formulary access.
Pricing Analysis
Short lead-time premiums of 15-25% apply to silicone-acrylic hybrid tapes stocked in regional distribution centers serving United States home care networks. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 10993 certification grade and biocompatibility documentation depth. Cost compression in cotton substrate tiers is intensifying because Egyptian and Indian long-staple cotton price volatility erodes converter margins. Ambulatory surgery centers exhibit highest price sensitivity due to bundled reimbursement constraints, while German university hospitals prioritize certified supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul, Baden-Württemberg, and Osaka-Kobe anchor hub-and-spoke patterns reaching hospital systems and home care networks. Manufacturing concentrates in the United States, Germany, and Japan where FDA, EMA MDR, and PMDA registrations create qualification moats. Medical-grade cotton, acrylic polymer resins, and silicone release liners constitute critical input dependencies. Single-source vulnerability in Egyptian long-staple cotton sourcing exposes margin predictability to climate-driven harvest volatility. Distribution runs through group purchasing organizations in acute care and durable medical equipment providers in post-acute channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade adhesive polymer chemist scarcity props pricing for qualified manufacturers, creating supply-constrained conditions that favor incumbents with established formulation teams and cleanroom infrastructure.
For Market Incumbents: To counter film-based adhesive substitution in IV catheter applications, 3M and Johnson & Johnson should deepen backward integration into medical-grade cotton sourcing through long-staple fiber procurement agreements with Egyptian and Indian suppliers. Capacity addition in Baden-Württemberg serving EMA MDR-registered European demand represents the priority defensive lever against mid-tier converter consolidation. For New Entrants and Emerging Players: Begin with German ambulatory surgery center elastic tape segments where conformability requirements and shorter qualification cycles reduce incumbent lock-in. Telehealth-integrated wound monitoring substrates for United States home care networks represent the most penetrable white-space opportunity. A direct-to-durable-medical-equipment-provider go-to-market angle bypasses hospital GPO exclusion. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified adhesive science conglomerates seeking wound care verticalization. Long-term viability hinges on ISO 13485 certification maintenance and silicone-acrylic hybrid formulation capability across a 5-10 year window. Acquisition target archetype: mid-size converters with PMDA registrations and established Japanese distribution. The signal to watch is EMA MDR technical file submission velocity as inflection indicator for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Acrylic Hybrid Formulation Investment | Captures premium positioning in United States post-acute home care channels requiring 7-14 day wear intervals. |
| EMA MDR Technical File Development | Secures European hospital procurement consortia access as supplier lists compress to registered entities. |
| Backward Cotton Fiber Integration | Insulates margin predictability from Egyptian and Indian long-staple price volatility exposure. |
| Home Care Distributor Partnership | Captures patient-direct relationships as wound care consumption shifts from acute to residential settings. |
| PMDA Registration Expansion | Unlocks Japanese chronic wound management demand among patients over 65 requiring long-term retention. |
Research Methodology
FDA 510(k) filings, EMA MDR technical file databases, and hospital procurement contract records formed the secondary backbone for volume and pricing calibration. Primary interviews with adhesive polymer chemists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated secondary estimates and identified technology transition timelines. Bottom-up and top-down triangulation reconciled converter shipment data with end-user consumption patterns across acute and post-acute channels.
Bottom-up modeling anchored volume projections to individual substrate-adhesive combinations and end-user segment procurement cycles. Segmentation dimensions included product type, care setting, clinical application, and functional specification tier. CAGRs were derived from regression analysis against demographic drivers and reimbursement policy shifts. Key inputs encompassed ISO 10993 testing adoption rates, ambulatory surgery center procedure volume trajectories, and telehealth wound monitoring penetration curves.
Underlying measurement precision varies by segment; silicone-acrylic hybrid and breathable functional tiers carry tighter precision than commodity cotton constructions due to concentrated manufacturer disclosure. Forecasts reflect assumptions regarding regulatory enforcement continuity, cotton harvest stability, and home care reimbursement policy durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Swab Cups Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Ostomy Drainage Bags Market