
 Transfusion Dependent Thalassaemia Management Market | 2026-2036
Transfusion Dependent Thalassaemia Management Market Size, Share, and Industry Trends Forecast 2026-2036
Transfusion Dependent Thalassaemia Management Market Analytics
Specialized thalassaemia centers is rotating toward dominance as the primary buyer archetype, displacing fragmented general hematology practices across high-burden regions. Novartis AG leverages its established transfusion medicine infrastructure to sustain market presence in chelation and emerging gene therapy portfolios. bluebird bio, Inc. anchors its competitive position through specialized manufacturing capabilities for lentiviral vector-based treatments. Bristol Myers Squibb Company differentiates via its depth in immunohematology and transfusion support therapies.
Transfusion Dependent Thalassaemia Management encompasses the clinical protocols, pharmaceutical interventions, blood product logistics, and monitoring systems required to sustain patients with beta-thalassaemia major and related hemoglobinopathies who require lifelong erythrocyte replacement, typically involving leukoreduced packed red blood cells administered every 2-4 weeks alongside iron burden quantification through serum ferritin and liver MRI. The primary purpose is to maintain hemoglobin thresholds above 9-10.5 g/dL while preventing transfusional hemosiderosis through chelation. Blood Transfusion remains the mature revenue backbone with established reimbursement, while Gene Therapy represents the fastest-expanding segment as curative intent shifts long-term economics from chronic to episodic high-value intervention. Iron Chelators command concentrated margin pools due to limited generic erosion in deferasirox and the specialized manufacturing requirements for deferoxamine parenteral formulations.
The U.S. FDA and the European Medicines Agency have established distinct but converging frameworks for gene therapy approval in hemoglobinopathies, with the FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme both compressing review timelines and reshaping clinical trial investment patterns. The International Society for Blood Transfusion guidelines and national hemovigilance programs govern blood product quality and traceability, directly determining which collection and processing technologies achieve market access. Stakeholders must monitor how curative gene therapy penetration reshapes blood bank demand forecasting and chelation drug procurement cycles.
Market Dynamics
The transition from chronic transfusion-chelation protocols toward curative gene therapy is compressing lifetime patient value into single-intervention episodes, forcing blood banks and pharmaceutical suppliers to restructure demand forecasting and inventory management around episodic rather than recurring revenue streams.
Growth Catalysts
- EMA Priority Medicines Scheme:Compressed review timelines for hemoglobinopathy gene therapies accelerate clinical trial investment and reduce time-to-market for curative interventions.
- Leukoreduction Technology:Advanced filtration systems reduce alloimmunization rates in multi-transfused patients, extending transfusion program viability and improving patient outcomes.
- Mediterranean Basin Carrier Prevalence:Concentrated disease burden in Cyprus, Greece, and Italy sustains large addressable populations and specialized treatment infrastructure.
Market Restraints
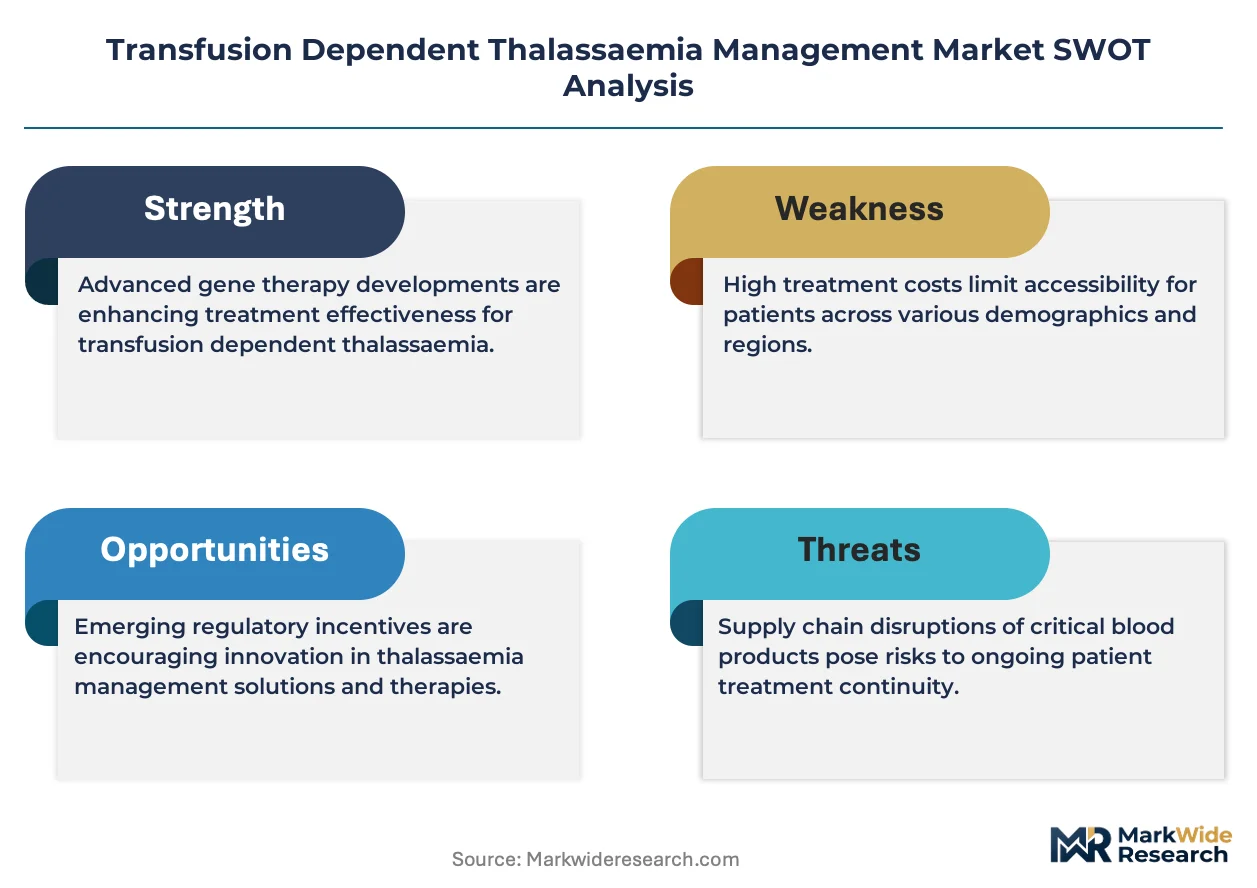
- Gene Therapy Manufacturing Concentration:Lentiviral vector production capacity clusters in select biomanufacturing hubs, creating supply bottlenecks for personalized treatments.
- Deferasirox Patent Thickets:Limited generic erosion in oral iron chelation maintains elevated pricing and restricts payer flexibility in cost management.
- Alloimmunization Complexity:Extended red cell antigen matching requirements strain rare donor registries and extend blood bank operational costs.
Strategic Opportunities
- Sub-Saharan Africa Expansion:Underpenetrated screening and transfusion infrastructure in Nigeria and Ghana offers first-mover advantage for integrated thalassaemia management programs.
- Real-World Evidence Mandates:FDA post-approval study requirements for gene therapies create demand for long-term patient monitoring platforms and data infrastructure.
- Telemedicine Integration:Remote ferritin monitoring and chelation adherence tracking reduce clinic burden while maintaining therapeutic thresholds in dispersed populations.
Industry Challenges
- Vector Manufacturing Workforce Gap:Shortage of qualified personnel in GMP-compliant viral vector production limits capacity expansion for gene therapy commercialization.
- Legacy Blood Bank IT Integration:Hemovigilance traceability requirements demand costly upgrades to interoperable systems connecting collection, processing, and patient administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfusion Dependent Thalassaemia Management Market |
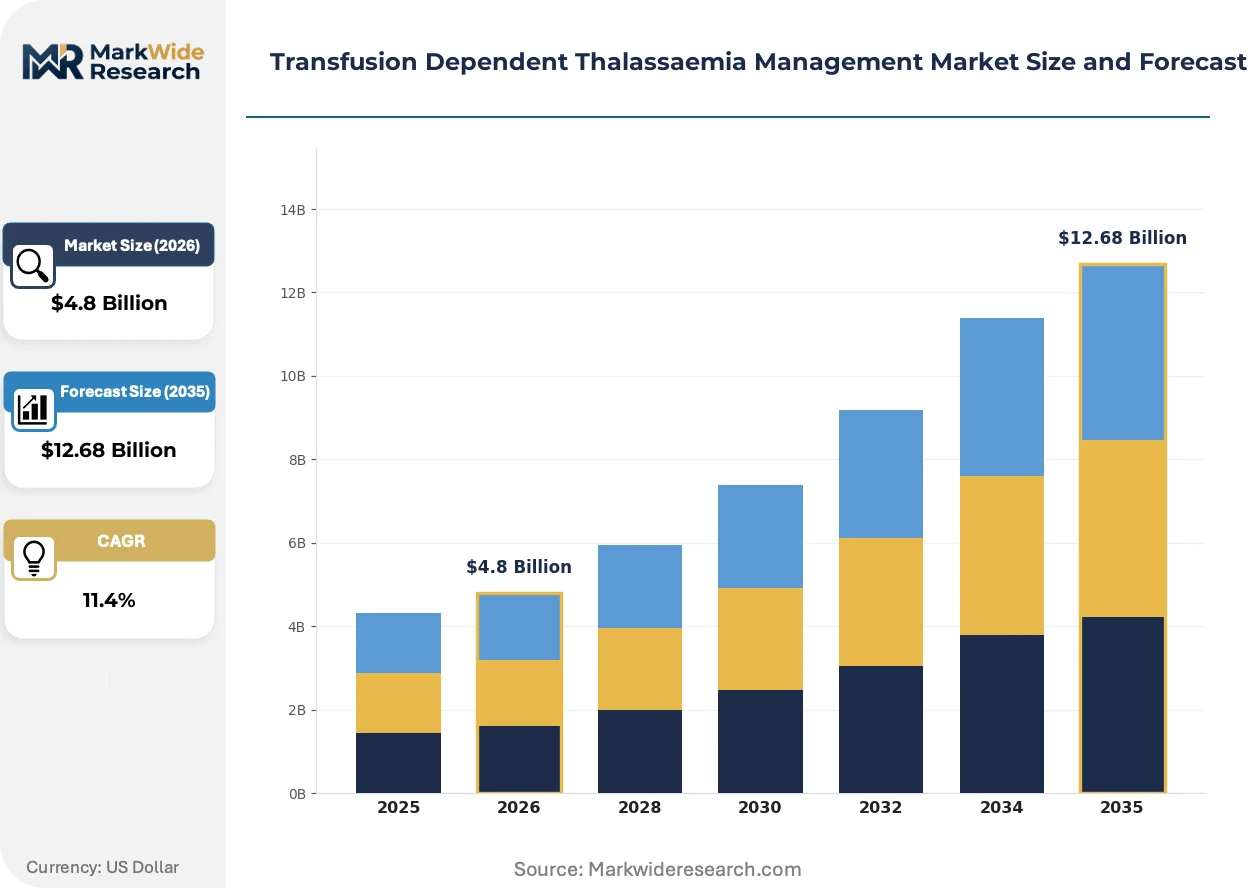
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Blood Transfusion, Chelation Therapy, Gene Therapy, Iron Supplementation End User: Hospitals, Blood Banks, Clinics, Home Care Technology: Automated Blood Collection, Stem Cell Therapy, Laboratory Testing, Mobile Health Solutions Medication Type: Iron Chelators, Blood Products, Vitamins, Antioxidants |
| Companies Covered | Novartis AG, bluebird bio, Inc., Vertex Pharmaceuticals Incorporated, Bristol Myers Squibb Company, Chiesi Farmaceutici S.p.A., Grifols, S.A., Octapharma AG, ApoPharma Inc, Ciplia Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfusion Dependent Thalassaemia Management Market Evolving Landscape
Curative intent is displacing palliative protocols across the treatment hierarchy, compressing investment timelines and reshaping how stakeholders value long-term patient relationships versus episodic high-margin interventions.
Point-of-care hemoglobin analyzers is miniaturizing diagnostic infrastructure for transfusion timing decisions. Rural clinics in high-burden regions adopt palm-sized spectrophotometric devices to reduce travel-dependent hospital visits. This decentralization is compressing the interval between symptomatic decline and therapeutic response, shifting volume toward distributed care models.
REACH authorization requirements for novel chelation excipients impose extended toxicology testing on reformulation programs. European manufacturers face eighteen-month delays for modified-release deferasirox variants. Pediatric formulation developers bear the greatest compliance burden, redirecting R&D investment toward adult-indication extensions.
Consolidated purchasing by specialized thalassaemia centers displaces fragmented hospital procurement. National health systems in Italy and Greece centralize blood product contracting through designated reference centers. This buyer concentration shifts negotiation leverage toward volume-based pricing and exclusive supply agreements with preferred blood services.
Transfusion Dependent Thalassaemia Management Market Segmentation
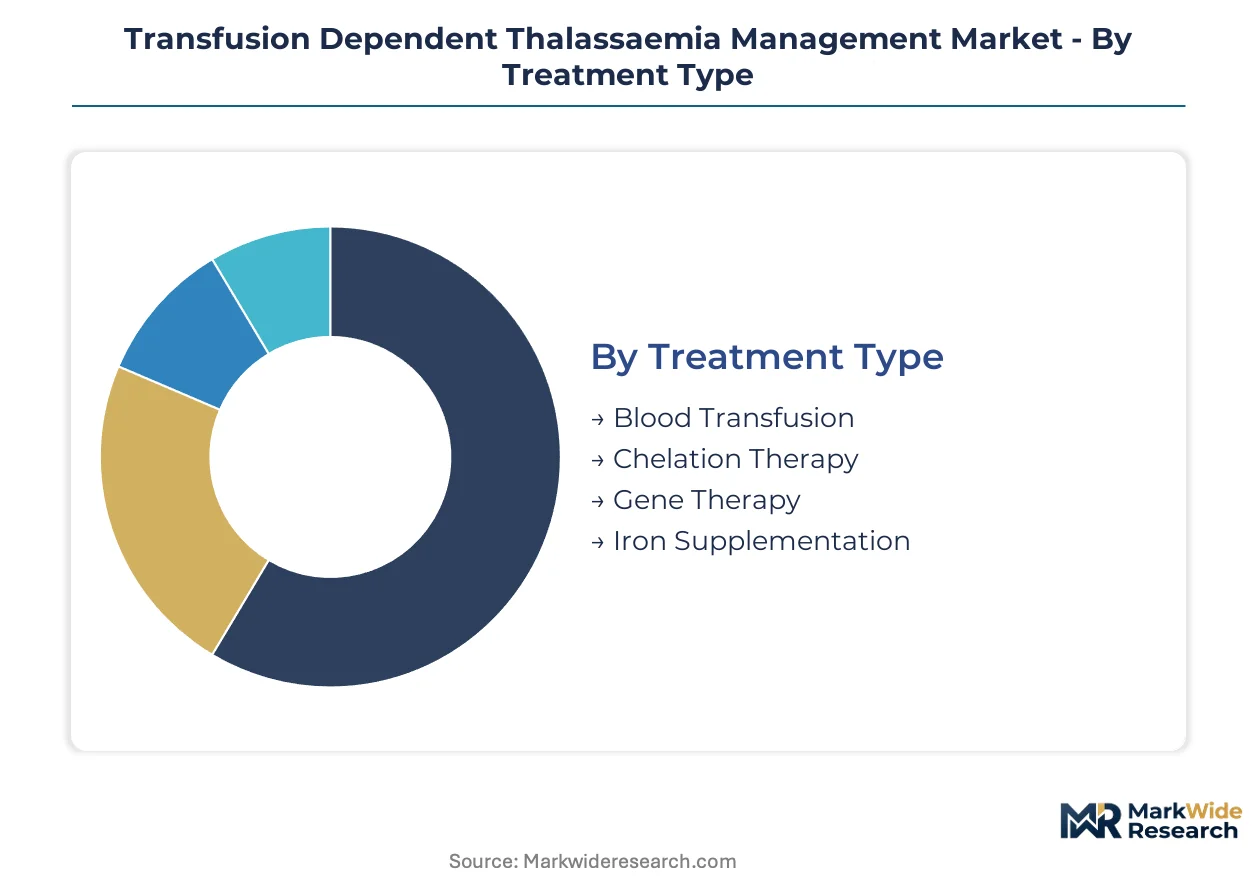
Transfusion-dependent thalassaemia management fragments across intervention modalities, care settings, and technical infrastructure. Each segment carries distinct regulatory pathways, margin structures, and consolidation dynamics that determine competitive positioning.
Treatment Type:
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme create divergent approval timelines across curative versus chronic modalities.
- Blood Transfusion:Leukoreduced packed red blood cells administered every 2-4 weeks constitute the established standard of care. Demand concentrates in Mediterranean basin reference centers in Cyprus, Greece, and Italy where carrier prevalence sustains large addressable populations and specialized transfusion infrastructure.
- Gene Therapy:Lentiviral vector-based beta-globin gene addition delivers curative intent through single-intervention episodes. Investment is accelerating fastest in the United States and Western Europe where accelerated approval pathways compress development timelines and reshape lifetime patient value economics.
- Chelation Therapy:Deferasirox, deferoxamine, and deferiprone protocols manage transfusional hemosiderosis through daily or continuous administration.
- Iron Supplementation:Adjunctive ferrous formulations address concurrent nutritional deficiencies in pediatric and adolescent patient cohorts.
Blood Transfusion handles the majority of throughput; Gene Therapy is the fastest mover on share.
End User:
Care delivery is consolidating into specialized centers as volume thresholds justify dedicated hemovigilance and transfusion medicine expertise.
- Hospitals:Tertiary academic medical centers with integrated transfusion services, hematology departments, and cardiac iron monitoring capabilities capture complex multi-transfused patients requiring extended red cell antigen matching.
- Blood Banks:National and regional blood services manage collection, processing, leukoreduction, and rare donor registry coordination. Procurement is shifting toward centralized contracting through designated reference centers in Italy and Greece.
- Clinics:Community hematology practices and day-hospital facilities handle stable patients on established transfusion-chelation protocols.
- Home Care:Subcutaneous deferoxamine infusion and oral chelation administration reduce hospital burden for adherent adult patients.
Hospitals anchor the revenue base; Blood Banks are expanding most quickly as national health systems centralize procurement.
Technology:
Automation and decentralization are compressing diagnostic intervals while vector manufacturing constraints limit gene therapy scale-up.
- Automated Blood Collection:Apheresis systems and component separation technologies optimize red cell yield and reduce donor exposure frequency.
- Stem Cell Therapy:Autologous hematopoietic stem cell harvest and ex vivo modification underpin lentiviral vector-based gene therapy commercialization.
- Laboratory Testing:Serum ferritin quantification, liver MRI T2* imaging, and HLA typing infrastructure concentrate in high-volume specialized centers.
- Mobile Health Solutions:Point-of-care hemoglobin analyzers and remote ferritin monitoring platforms extend reach into rural high-burden regions.
Laboratory Testing commands the installed base; Mobile Health Solutions are climbing the fastest on adoption curves.
Medication Type:
Patent thickets and specialized manufacturing requirements sustain margin concentration in oral iron chelation despite biosimilar pressures elsewhere.
- Iron Chelators:Deferasirox oral tablets, deferoxamine parenteral formulations, and deferiprone tablets manage iron burden through distinct pharmacokinetic profiles and compliance profiles.
- Blood Products:Leukoreduced packed red blood cells, washed red cells for alloimmunized patients, and rare phenotype units constitute the transfusion backbone.
- Vitamins:Folic acid supplementation supports erythropoiesis in hypertransfused patients with suppressed marrow activity.
- Antioxidants:Vitamin E and other free radical scavengers address oxidative stress in iron-overloaded tissues.
Iron Chelators generate the dominant margin pool; Blood Products represent the highest absolute volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy exports specialized transfusion services and gene therapy expertise to Greece and Cyprus, consolidating Mediterranean basin patient flows into reference centers with established hemovigilance infrastructure.
United States
FDA's regenerative medicine advanced therapy designation accelerates beta-globin gene therapy trials at Boston and San Francisco biomanufacturing clusters. The National Institutes of Health funds sickle cell and thalassaemia research consortia. Philadelphia anchors lentiviral vector production capacity for personalized treatments.
Italy
Carrier prevalence in Sicily and Sardinia sustains Europe's largest addressable population for beta-thalassaemia major. The National Health Service centralizes blood product contracting through designated reference centers in Milan and Rome. Lombardy consolidates transfusion medicine expertise at Policlinico di Milano.
Greece
Thalassaemia carrier rates exceed 7% in Aegean island populations, driving demand for leukoreduced blood units and chelation protocols. EMA's priority medicines scheme compresses review timelines for gene therapy access. Athens hosts the Hellenic National Blood Center coordinating rare donor registries.
Cyprus
The highest global carrier prevalence at 12% supports specialized thalassaemia centers in Nicosia and Limassol with integrated cardiac iron monitoring. National screening programs mandate premarital testing. The Cyprus Institute of Neurology and Genetics anchors regional diagnostics capacity.
United Kingdom
NHS England's specialized commissioning framework consolidates complex thalassaemia care at London and Manchester tertiary centers. The Medicines and Healthcare products Regulatory Agency aligns gene therapy approval with EMA pathways. Oxford and Cambridge bioclusters advance ex vivo stem cell modification research.
Transfusion Dependent Thalassaemia Management Market Competitive Landscape
Listed leaders compete with private specialists across vector manufacturing and transfusion medicine infrastructure, creating a tiered structure where scale-driven pharmaceutical conglomerates hold chronic care portfolios while venture-backed biotechs capture curative gene therapy development. Three archetypes dominate: integrated hematology conglomerates with transfusion medicine depth, specialized gene therapy developers with captive manufacturing, and regional plasma fractionators with blood product logistics. Competitive moves center on manufacturing capacity reservation agreements and backward integration into GMP-compliant viral vector production.
Among Swiss-based integrated pharmaceutical groups, Novartis AG occupies a position exemplifying established transfusion medicine infrastructure applied to chelation and emerging curative portfolios. Within the gene therapy specialist tier, bluebird bio, Inc. and Vertex Pharmaceuticals Incorporated represent archetypes of lentiviral vector-based and CRISPR-edited approaches respectively, each anchoring distinct technical pathways toward beta-globin restoration. Bristol Myers Squibb Company sits within the immunohematology-focused conglomerate category, leveraging depth in transfusion support therapies.
| Leading Market Players |
|---|
| Novartis AG |
| bluebird bio, Inc. |
| Vertex Pharmaceuticals Incorporated |
| Bristol Myers Squibb Company |
| Chiesi Farmaceutici S.p.A. |
| Grifols, S.A. |
| Octapharma AG |
| ApoPharma Inc |
| Ciplia Limited |
| Others |
Value Network & Pricing Analysis
Gene therapy substitution for chronic transfusion protocols redraws supply geography toward Philadelphia and Boston biomanufacturing clusters while collapsing pricing economics from recurring lifetime revenue to single-episode curative interventions. This substitution simultaneously elevates upfront manufacturing costs and compresses total addressable spend per patient, forcing blood banks and pharmaceutical suppliers to restructure inventory and contracting models around episodic demand spikes rather than predictable replenishment cycles.
Pricing Analysis
Current-generation lentiviral vector gene therapies command premium positioning against prior-generation chronic transfusion-chelation protocols, while next-generation CRISPR-edited approaches promise manufacturing cost reductions that will reshape tiered pricing structures. Three-tier pricing stratifies across curative gene therapy, branded oral chelation, and generic deferoxamine parenteral formulations, with price differentiation driven by FDA regenerative medicine advanced therapy designation status and manufacturing scale constraints. Pricing pressure stems from EMA priority medicines scheme acceleration compressing exclusivity windows for first movers. National health systems in Mediterranean basin countries exhibit highest price sensitivity due to large patient volumes, while U.S. academic medical centers demonstrate lowest sensitivity given research funding offsets and specialized commissioning frameworks.
Supply Chain Analysis
Lentiviral vector manufacturing concentration in Philadelphia, Boston, and selected Swiss biomanufacturing hubs creates supply bottlenecks that constrain gene therapy commercialization scale-up. Raw material dependencies center on fetal bovine serum, plasmid DNA templates, and GMP-grade cell culture media, with distribution running through cold-chain logistics networks connecting vector production facilities to specialized thalassaemia treatment centers. Tariff exposure on Chinese-sourced cell culture media and single-use bioreactor components amplifies cost volatility. Blood product supply chains maintain parallel structures, with leukoreduced packed red blood cells sourced from national blood services in Italy, Greece, and Cyprus through centralized reference center contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating into specialized thalassaemia centers as national health systems in Italy and Greece consolidate procurement through designated reference facilities, fragmenting negotiating leverage away from fragmented general hematology practices.
For Market Incumbents: Fortify vector manufacturing capacity reservations through backward integration into GMP-compliant viral vector production, securing captive supply chains against lentiviral production bottlenecks. Deepen relationships with Mediterranean basin reference centers through exclusive blood service agreements that lock in transfusion volume commitments before gene therapy penetration accelerates. Gene therapy entrants threaten chronic care incumbents by collapsing lifetime patient value; vertical integration into manufacturing is the defensive priority. For New Entrants and Emerging Players: Lead with telemedicine-enabled remote monitoring platforms targeting dispersed rural populations in high-burden regions where clinic infrastructure remains underdeveloped. Sub-Saharan Africa offers the most penetrable geography, with Nigeria and Ghana presenting first-mover advantage for integrated screening and transfusion programs. Partner with national blood services on hemoglobinopathy registry development to establish data infrastructure moats ahead of curative therapy launches. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors manufacturing-capable platforms over pure development-stage assets. Long-term viability over the coming decade hinges on vector production scalability and regulatory approval pathway execution rather than clinical trial success alone. Acquisition targets should demonstrate captive GMP manufacturing or secured capacity agreements; the signal to watch is EMA and FDA post-approval study commitment scope, which indicates real-world evidence infrastructure requirements and follow-on revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Philadelphia and Boston biomanufacturing clusters anchor lentiviral vector production capacity for personalized gene therapies. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses review timelines and reshapes clinical trial investment patterns. |
| Long-term Supply Agreement | Centralized blood product contracting through Italian and Greek reference centers locks in transfusion volume commitments. |
| Platform Integration | Telemedicine-enabled remote ferritin monitoring extends reach into rural high-burden regions while reducing clinic burden. |
| Pipeline Diversification | CRISPR-edited gene therapy approaches promise manufacturing cost reductions against lentiviral vector alternatives. |
Research Methodology
Cross-validation between primary interviews with hematology department heads, blood bank operations directors, gene therapy manufacturing executives, and national health system procurement leads anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converge on segment-level estimates across the analysis window.
Sensitivity analysis frames the quantitative approach, with analytical outputs reflecting modeled segmentation across treatment modality, care setting, patient age cohort, and regional regulatory cluster. CAGRs derive from epidemiological prevalence projections, gene therapy penetration curves, and blood product demand elasticity estimates. Forecast inputs incorporate vector manufacturing capacity expansion timelines, EMA priority medicines scheme approval velocity, and centralized procurement adoption rates in Mediterranean basin health systems.
Underlying assumptions cover gene therapy manufacturing scale-up trajectories, blood bank consolidation timelines, and regulatory pathway convergence between FDA and EMA frameworks, with deviation risk concentrated in vector production workforce availability and alloimmunization complexity escalation. Practitioners should keep alternative scenarios live as curative therapy reimbursement models and real-world evidence mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Hematology Analyzers Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Blood Plasma Market
Hematology
Graft vs Host Disease Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Global Hematology Diagnostics Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Hematopoietic Agents Market
Hematology
Hematologic Malignancies Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market