
 MRSA Antibiotic Preparations Market | 2026-2036
MRSA Antibiotic Preparations Market Size, Share, and Industry Trends Forecast 2026-2036
MRSA Antibiotic Preparations Market Insights
Hospital-grade intravenous formulations is collapsing the gap between empiric therapy and pathogen-directed treatment in serious MRSA infections. Pfizer Inc leverages its manufacturing scale to supply vancomycin across major health systems. Merck & Co., Inc. anchors its position through sustained R&D investment in novel mechanism antibiotics. Basilea Pharmaceutica Ltd. specializes in lipopeptide development for resistant gram-positive pathogens.
MRSA antibiotic preparations comprise antimicrobial agents specifically formulated to inhibit or kill methicillin-resistant Staphylococcus aureus, with vancomycin hydrochloride requiring reconstitution to a final concentration of 5 mg/mL for intravenous infusion. These preparations serve primarily to treat complicated skin and skin structure infections, bloodstream infections, and pneumonia where beta-lactam therapy fails. Glycopeptides occupy the largest revenue share due to decades of clinical familiarity and formulary inclusion, while lipopeptides represent the fastest-expanding category driven by newer agents with improved pharmacokinetic profiles. Intravenous administration routes dominate hospital settings, though oral oxazolidinones capture substantial margin pools in step-down therapy and outpatient parenteral antimicrobial programs.
The FDA's Qualified Infectious Disease Product program shapes development incentives through extended market exclusivity provisions for novel anti-MRSA agents. EMA's antimicrobial resistance strategy and WHO's AWaRE classification system jointly influence formulary restrictions and stewardship protocols across European and international markets. Stakeholders must monitor pipeline progression against evolving resistance mechanisms and reimbursement shifts toward value-based antimicrobial contracts.
Market Dynamics
Hospital stewardship programs are compressing empiric antibiotic use and forcing formularies toward pathogen-directed therapy, reshaping how anti-MRSA agents achieve clinical adoption and reimbursement positioning.
Growth Catalysts
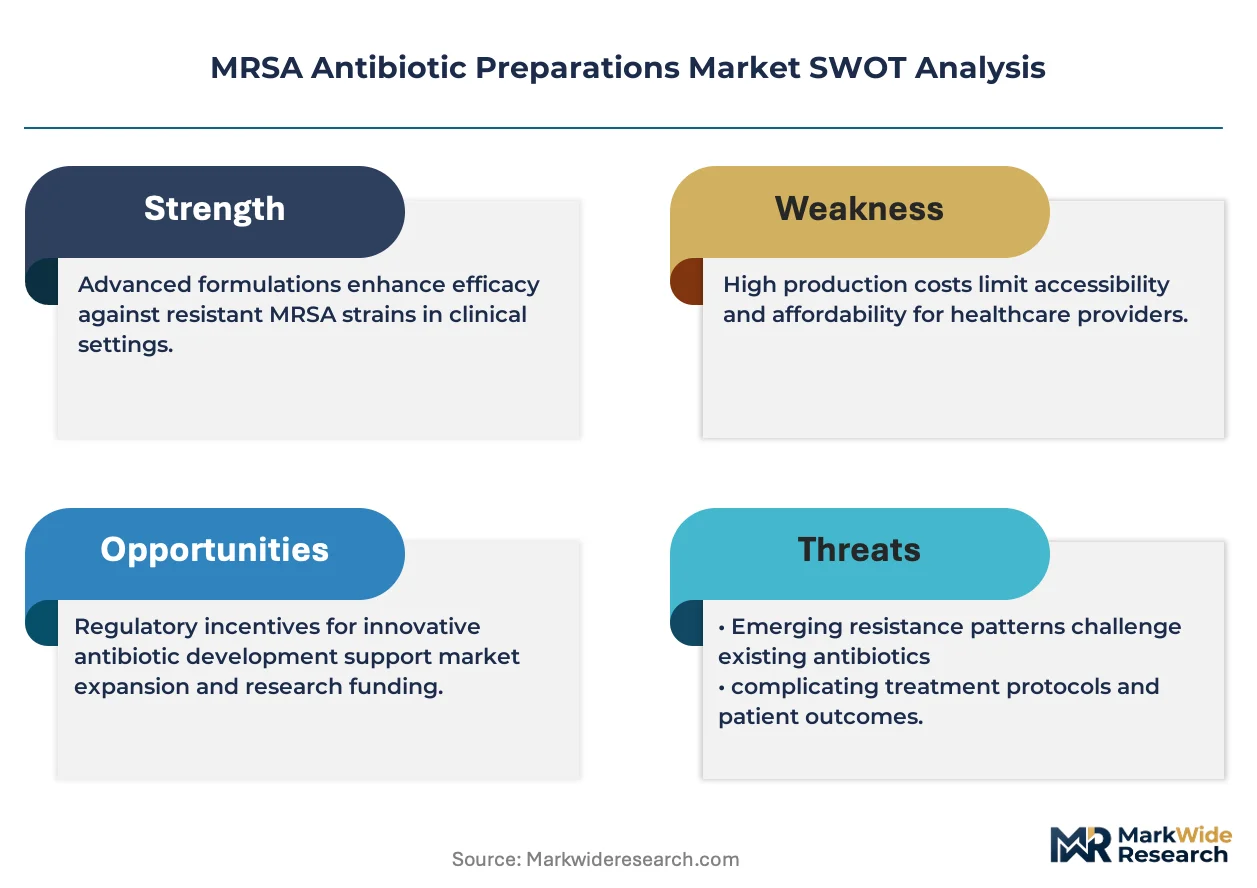
- Qualified Infectious Disease Product designation:The FDA's extended exclusivity provisions accelerate novel mechanism development timelines and incentivize R&D investment in resistant gram-positive pathogens.
- Step-down therapy protocols:Outpatient parenteral antimicrobial programs expand lipopeptide and oxazolidinone utilization beyond inpatient settings into home infusion services.
- United States nosocomial burden:Sustained MRSA prevalence in American health systems drives hospital formulary investment and maintains glycopeptide anchor positioning.
Market Restraints
- Vancomycin nephrotoxicity limitations:Dose-dependent renal toxicity restricts therapeutic windows and necessitates therapeutic drug monitoring infrastructure.
- Active pharmaceutical ingredient concentration:Fermentation-based glycopeptide production concentrates in Asian manufacturing clusters, creating supply vulnerability.
- Generic vancomycin commoditization:Multiple approved suppliers collapse pricing power for standard-of-care intravenous formulations.
Strategic Opportunities
- Oral bioavailability expansion:Oxazolidinone development for early discharge protocols captures margin pools in step-down therapy outside hospital walls.
- AWaRE classification alignment:WHO stewardship frameworks create formulary preference for Watch and Reserve category agents with demonstrated resistance profiles.
- Combination therapy protocols:Beta-lactam plus anti-MRSA pairings for polymicrobial infections open new indication expansion pathways.
Industry Challenges
- Antimicrobial stewardship compliance:Hospital infection control committees impose pre-authorization requirements that lengthen sales cycles and demand clinical pharmacology resources.
- Resistance surveillance infrastructure:Real-time susceptibility testing integration with electronic health records requires capital investment and interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRSA Antibiotic Preparations Market |
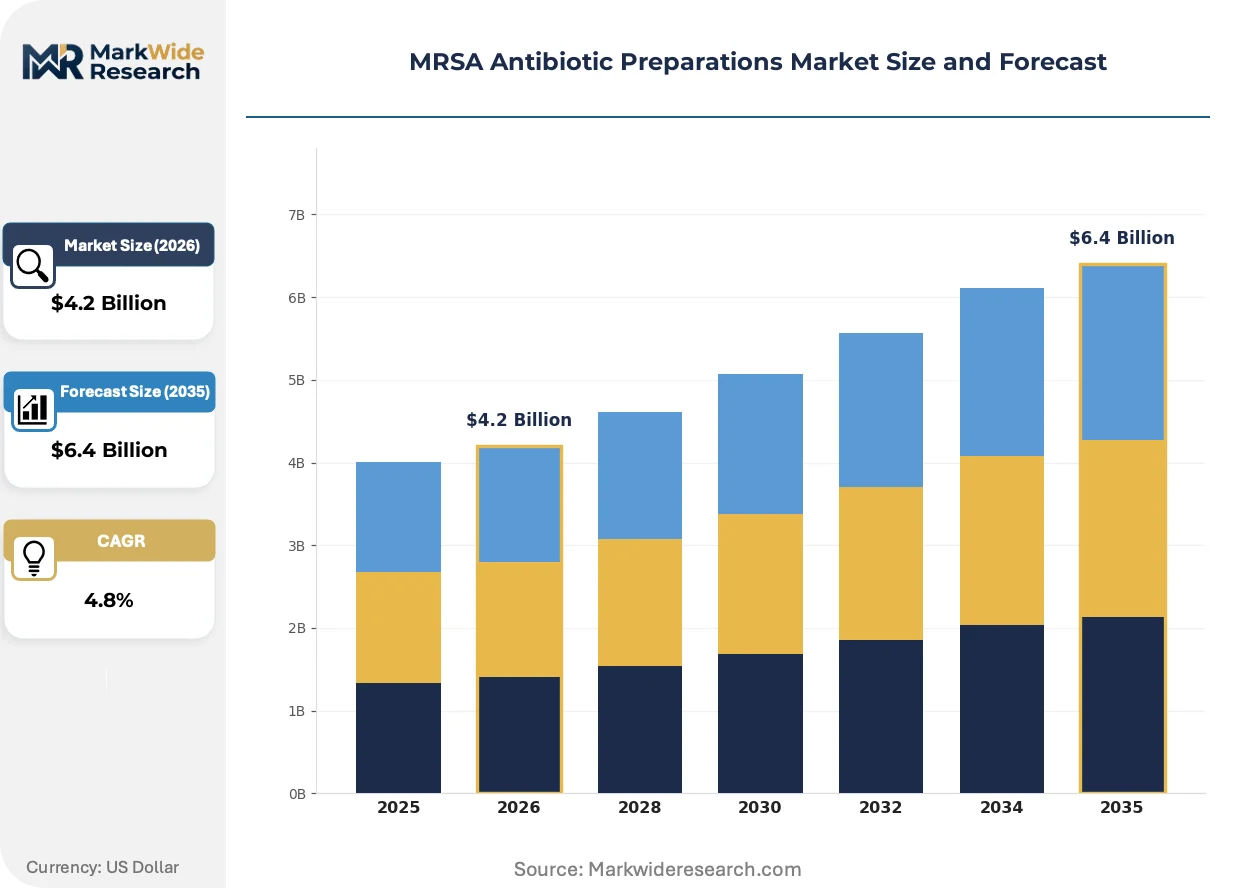
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycopeptides, Oxazolidinones, Lipopeptides, Streptogramins Administration Route: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Clinics, Home Healthcare, Pharmacies Formulation Type: Sterile Solutions, Capsules, Tablets, Powders |
| Companies Covered | Pfizer Inc, Merck & Co., Inc., Melinta Therapeutics, Inc., Allergan plc, Theravance Biopharma, Inc., Cumberland Pharmaceuticals Inc, AbbVie Inc., Basilea Pharmaceutica Ltd., Nabriva Therapeutics plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRSA Antibiotic Preparations Market Trends and Innovations
Novel mechanism antibiotics are displacing legacy glycopeptides in high-acuity settings, while regulatory incentives and procurement models simultaneously reshape development priorities and commercial access pathways.
Lipopeptide engineering is miniaturizing dosing intervals through prolonged half-life modifications. Academic medical centers in the United States are adopting once-daily infusion protocols for complicated bacteremia. This pharmacokinetic improvement is compressing length-of-stay metrics and enabling earlier transition to outpatient care.
EMA's antimicrobial resistance strategy now mandates environmental risk assessments for manufacturing discharge. Active pharmaceutical ingredient producers must install containment infrastructure for fermentation effluent. European contract manufacturers are responding by consolidating production at sites with advanced wastewater treatment capabilities.
Hospital purchasing cooperatives are consolidating antibiotic procurement under value-based contracts that tie reimbursement to clinical outcomes. Group purchasing organizations are displacing individual hospital negotiations. This concentration is most visible in the United States, where integrated delivery networks now control formulary access for multiple facilities simultaneously.
MRSA Antibiotic Preparations Market Segmentation
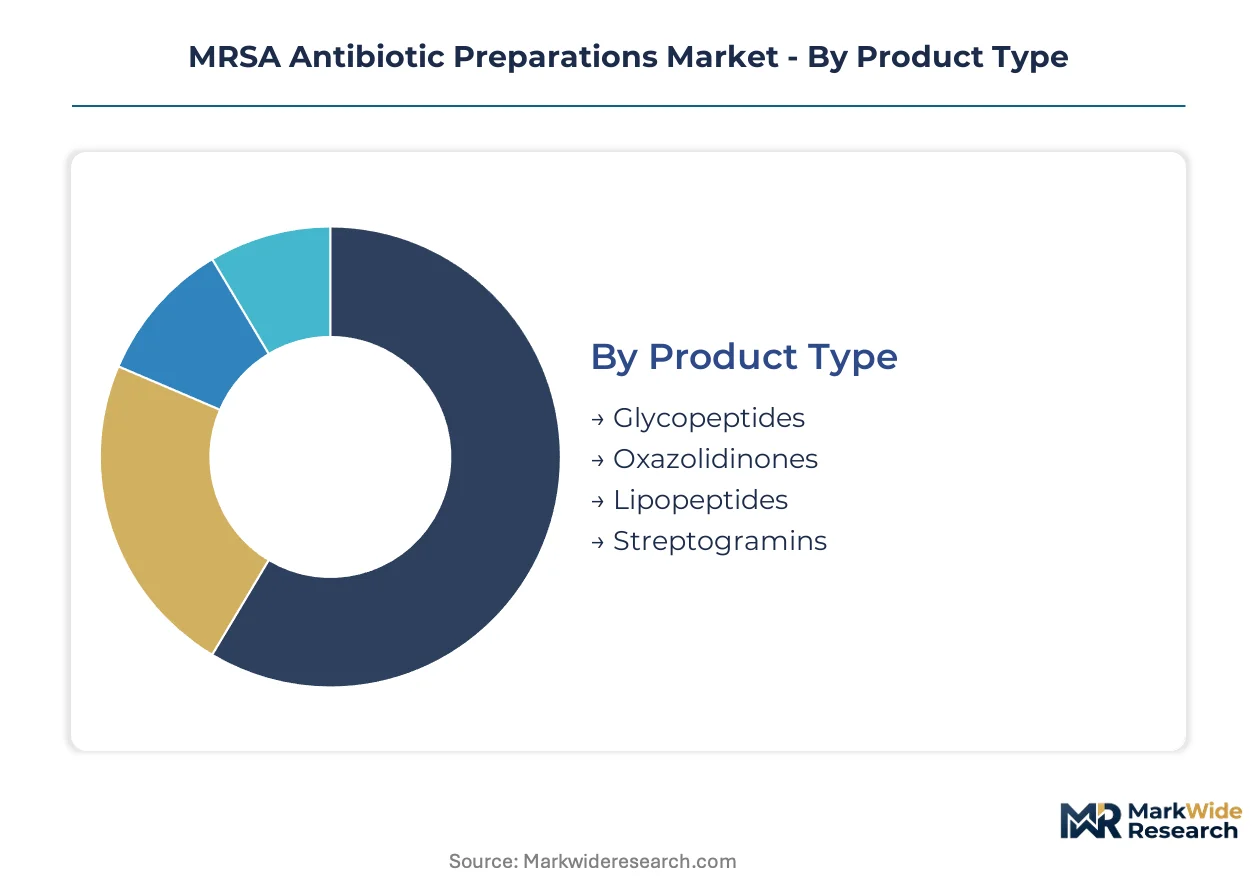
Antibiotic preparation categories in the MRSA market face divergent regulatory pathways and reimbursement protocols. Product chemistry determines FDA exclusivity eligibility, while administration route shapes hospital formulary placement and step-down therapy economics.
Product Type:
FDA's Qualified Infectious Disease Product designation creates tiered development incentives across molecular classes, with novel mechanisms receiving extended exclusivity versus legacy compounds.
- Glycopeptides:Vancomycin hydrochloride and related fermentation-derived agents require therapeutic drug monitoring due to nephrotoxicity risk. United States hospital systems anchor demand through decades of formulary inclusion and clinical familiarity with dosing protocols.
- Lipopeptides:Daptomycin and engineered derivatives feature prolonged half-life modifications enabling once-daily infusion. Academic medical centers in the United States are adopting these protocols for complicated bacteremia to compress length-of-stay metrics.
- Oxazolidinones:Oral bioavailability drives outpatient parenteral antimicrobial program adoption.
- Streptogramins:Combination formulations serve salvage therapy for vancomycin-resistant isolates.
Established volume favors glycopeptides; emerging adoption favors lipopeptides.
Administration Route:
Route selection determines care setting economics, with intravenous formulations commanding hospital reimbursement premiums and oral agents capturing step-down therapy margins.
- Intravenous:Sterile infusion preparations dominate inpatient revenue through glycopeptide and lipopeptide administration. Hospital purchasing cooperatives in the United States consolidate procurement under value-based contracts tied to clinical outcomes.
- Oral:Oxazolidinone tablets enable early discharge protocols and home healthcare transition. Integrated delivery networks favor oral agents for outpatient parenteral antimicrobial programs to reduce readmission exposure.
- Topical:Mupirocin formulations address localized skin and skin structure infections.
- Inhalation:Aerosolized delivery targets respiratory colonization in cystic fibrosis populations.
Hospital stewardship programs favor intravenous for severity-indexed cases; oral formulations are climbing fastest in discharge planning.
End User:
Customer concentration patterns reflect infection severity distribution and reimbursement infrastructure across care settings.
- Hospitals:Tertiary and community facilities generate the majority of anti-MRSA antibiotic consumption through emergency department and intensive care unit admissions. Infection control committees impose pre-authorization requirements that lengthen sales cycles.
- Home Healthcare:Infusion nursing services administer intravenous lipopeptides under outpatient parenteral antimicrobial protocols. United States Medicare reimbursement structures support home-based therapy for stable bacteremia cases.
- Clinics:Ambulatory settings manage uncomplicated skin and soft tissue infections.
- Pharmacies:Retail dispensing captures oral oxazolidinone prescriptions for step-down completion.
Hospital volume anchors manufacturer revenue; home healthcare represents the steepest expansion trajectory as integrated delivery networks push care outside facility walls.
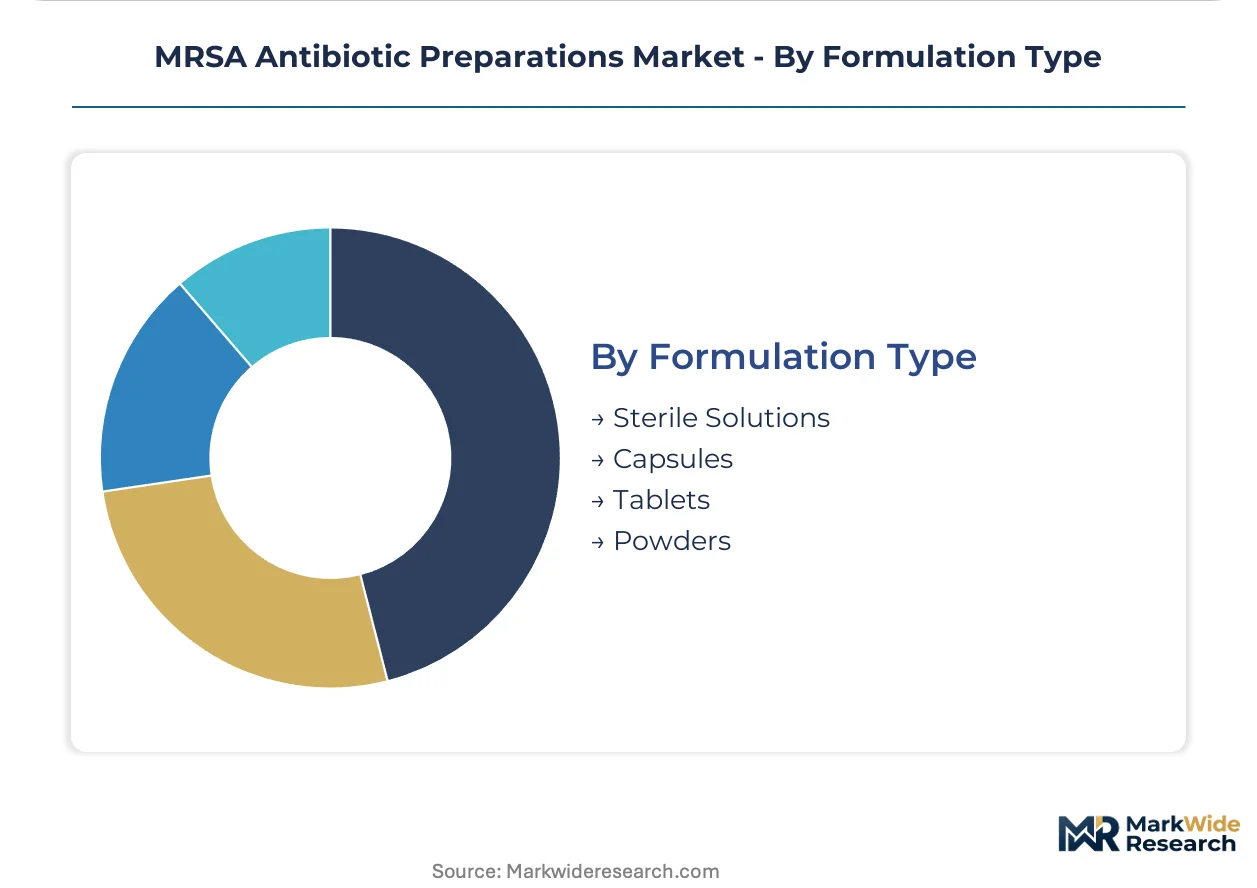
Formulation Type:
Manufacturing complexity and stability requirements create segmentation in production infrastructure and supply chain configuration.
- Sterile Solutions:Parenteral formulations require aseptic processing and cold chain distribution for intravenous glycopeptides and lipopeptides. Fermentation-based active pharmaceutical ingredient production concentrates in Asian manufacturing clusters.
- Tablets:Solid oral dosage forms for oxazolidinones enable patient self-administration and reduce nursing labor costs in outpatient settings.
- Capsules:Encapsulated powders serve pediatric and geriatric populations requiring dose titration flexibility.
- Powders:Reconstitutable vials demand pharmacy compounding infrastructure for final concentration preparation.
Sterile solutions command manufacturing investment; tablets capture margin pools in retail pharmacy dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based active pharmaceutical ingredient production for glycopeptides concentrates in Asian manufacturing clusters, while hospital formulary investment and regulatory incentives drive differentiated demand patterns across major pharmaceutical markets.
United States
Hospital stewardship programs and nosocomial MRSA burden sustain glycopeptide anchor positioning in tertiary care formularies. FDA's Qualified Infectious Disease Product designation accelerates novel mechanism development timelines through extended exclusivity provisions. Academic medical centers in Boston and Baltimore adopt once-daily lipopeptide infusion protocols to compress length-of-stay metrics.
Germany
Integrated delivery networks and outpatient parenteral antimicrobial programs expand lipopeptide utilization beyond inpatient settings. EMA's antimicrobial resistance strategy mandates environmental risk assessments for fermentation effluent discharge. Pharmaceutical manufacturing clusters in North Rhine-Westphalia install advanced wastewater treatment infrastructure to comply with containment requirements.
Japan
Aging demographics and hospital-acquired infection surveillance sustain demand for intravenous anti-MRSA agents in tertiary facilities. PMDA fast-track pathways for qualified infectious disease products align with global regulatory incentives. Tokyo-Osaka pharmaceutical corridors concentrate sterile formulation production for domestic hospital supply.
India
Expanding hospital infrastructure and antimicrobial stewardship program adoption drive formulary investment in anti-MRSA agents. CDSCO streamlined approval pathways for qualified infectious disease products mirror FDA incentive structures. Active pharmaceutical ingredient fermentation facilities in Maharashtra and Gujarat supply glycopeptide intermediates to global formulation networks.
China
Hospital accreditation standards and infection control committee requirements sustain intravenous antibiotic consumption in tier-one medical centers. NMPA priority review channels for novel anti-infectives accelerate domestic development timelines. Yangtze River Delta biopharmaceutical clusters concentrate lipopeptide engineering and sterile manufacturing capacity.
MRSA Antibiotic Preparations Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the MRSA antibiotic preparations market. Large-cap pharmaceutical conglomerates with manufacturing scale dominate glycopeptide supply contracts, while mid-cap specialists concentrate on novel mechanism development. The competitive terrain segments into three strategic archetypes: fermentation-scale incumbents, lipopeptide engineering specialists, and oral bioavailability innovators. M&A activity targets pipeline assets with QIDP designation, while capacity expansion focuses on sterile parenteral manufacturing infrastructure.
Within the fermentation-scale tier, Pfizer Inc and Merck & Co., Inc. anchor hospital formulary relationships through decades of vancomycin supply presence. Basilea Pharmaceutica Ltd. occupies a specialist position in lipopeptide development for resistant gram-positive pathogens. These three entities exemplify the market's structural division between manufacturing-scale incumbents and mechanism-focused innovators.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck & Co., Inc. |
| Melinta Therapeutics, Inc. |
| Allergan plc |
| Theravance Biopharma, Inc. |
| Cumberland Pharmaceuticals Inc |
| AbbVie Inc. |
| Basilea Pharmaceutica Ltd. |
| Nabriva Therapeutics plc |
| Others |
Pricing and Supply Chain Analysis
Value-based procurement contracts lock in multi-year supply commitments for hospital systems while anchoring price visibility through clinical outcome guarantees. These arrangements concentrate purchasing power among United States integrated delivery networks and European hospital alliances, compressing margin pools for generic glycopeptide suppliers while preserving premium positioning for novel mechanism agents with FDA Qualified Infectious Disease Product designation.
Pricing Analysis
FDA's Qualified Infectious Disease Product designation dictates the pricing tier structure across the MRSA antibiotic preparations landscape. Three-tier pricing separates novel mechanism lipopeptides from standard glycopeptides from commoditized generic vancomycin, with QIDP exclusivity commanding substantial formulary premiums. Cost compression in the glycopeptide tier is intensifying because multiple approved suppliers collapse pricing power for intravenous formulations. Community hospitals exhibit highest price sensitivity due to constrained pharmacy budgets, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Inventory buffers for fermentation-derived active pharmaceutical ingredients extend lead times to 18-24 weeks, forcing just-in-time manufacturing coordination between Asian production clusters and Western formulation facilities. Fermentation capacity concentrates in China, India, and South Korea for glycopeptide intermediates, while sterile fill-finish operations draw from Italian, German, and United States contract manufacturing networks. Single-source vulnerability pervades lipopeptide engineering capabilities, with only three global sites qualified for daptomycin derivative production. Distribution runs through hospital purchasing cooperatives and group purchasing organizations in North America, direct tender contracts in European national health systems, and regional distributors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial procurement is shifting toward platform-based stewardship ecosystems where formulary access hinges on interoperability with electronic health record surveillance systems and real-time susceptibility reporting. This interoperability requirement favors developers with health informatics partnerships over pure manufacturing plays.
For Market Incumbents: Shield vancomycin market position through backward integration into fermentation capacity and captive supply of active pharmaceutical ingredients from Maharashtra and Gujarat production clusters. Anchor hospital formulary relationships by embedding clinical pharmacology resources within stewardship committees to deflect pre-authorization requirements that lengthen competitor sales cycles. Counter lipopeptide displacement by emphasizing therapeutic drug monitoring infrastructure investments already sunk across United States health systems. For New Entrants and Emerging Players: Differentiate on oral bioavailability for oxazolidinone development targeting outpatient parenteral antimicrobial program expansion. Home healthcare infusion services represent the most penetrable channel, with Medicare reimbursement structures supporting intravenous therapy outside hospital walls. Pursue QIDP designation early to secure extended exclusivity and formulary preference under WHO AWaRE classification alignment. For Investors and Strategic Acquirers: Lipopeptide engineering specialists with late-stage pipeline assets and existing sterile manufacturing infrastructure offer the strongest acquisition profile for medium-term value creation. Long-term viability rests on resistance surveillance capabilities and environmental compliance infrastructure for fermentation effluent containment. Watch EMA antimicrobial resistance strategy enforcement intensity as the inflection signal for manufacturing consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| QIDP Designation Pursuit | FDA extended exclusivity provisions accelerate novel mechanism development timelines and de-risk R&D investment returns. |
| Stewardship Program Partnership | Hospital infection control committee relationships compress sales cycles and secure pre-authorization pathway preference. |
| Fermentation Capacity Expansion | Asian manufacturing cluster consolidation reduces supply vulnerability for glycopeptide active pharmaceutical ingredients. |
| Home Healthcare Channel Development | Outpatient parenteral antimicrobial program participation captures margin pools in step-down therapy outside facility walls. |
| Environmental Compliance Infrastructure | EMA antimicrobial resistance strategy mandates for effluent containment create competitive barriers for European market access. |
Research Methodology
A standing panel of hospital formulary directors, infectious disease clinicians, regulatory affairs specialists, and group purchasing organization contract managers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with pharmacy procurement leads at tertiary care systems and home healthcare infusion providers with secondary validation against FDA QIDP approval databases, EMA submission trackers, ClinicalTrials.gov enrollment data, and hospital stewardship program documentation. Bottom-up demand modeling for intravenous and oral administration routes triangulated against top-down manufacturer shipment data reported in SEC filings and trade publications.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare Part B reimbursement claims, European hospital procurement tender databases, and Indian CDSCO manufacturing license records. The analytical framework segmented demand across product chemistry classes, administration routes, and end-user settings while modeling patient population severity indices and regional regulatory cluster adoption patterns. CAGRs were derived from infection surveillance trend extrapolation, formulary placement probability weighting, and step-down therapy protocol penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained nosocomial MRSA prevalence, continued QIDP incentive program operation, or stable Medicare outpatient reimbursement would require recalibration. Forecasts reflect documented assumptions regarding resistance surveillance infrastructure deployment and stewardship program compliance intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market