
 Gingival Retraction Kits Market | 2026-2036
Gingival Retraction Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Gingival Retraction Kits Market Foresight
Dental distributor networks across North America and Western Europe are rewriting how gingival retraction kits reach chairside practitioners. 3M Company leverages its direct sales infrastructure to sustain preferred vendor status with large dental service organizations. Ultradent Products anchors its position through specialty channel control in the professional dental supply segment. Dentsply Sirona competes by integrating retraction consumables into its broader digital impression ecosystem.
Gingival retraction kits are sterile or non-sterile assemblies designed to displace gingival tissue laterally or apically, typically incorporating knitted or braided cords impregnated with vasoconstrictive agents such as aluminum chloride or ferric sulfate, or alternatively delivering astringent pastes and polymeric expanding materials via syringe or capsule applicators. Their primary commercial purpose is to achieve controlled moisture management and tissue deflection prior to definitive impression capture or restorative cementation. Cord retraction kits retain the largest installed base among product categories, though expanding polymeric retraction kits are gaining fastest as practitioners seek reduced tissue trauma and simplified technique sensitivity. Among applications, impression making and crown preparation together concentrate the majority of procedure-linked demand, with implant placement representing the emerging margin pool as peri-implant soft tissue protocols standardize.
The FDA regulates gingival retraction cords and pastes as Class I or Class II medical devices depending on active ingredient concentration, while the EU MDR requires notified body involvement for devices containing pharmacologically active substances. ISO 10993 biocompatibility testing and USP Class VI standards further constrain material selection and manufacturing validation. Stakeholders must monitor evolving EPA and REACH restrictions on astringent metal salts, as these chemistry restrictions could force formulation pivots before the next product registration cycle completes.
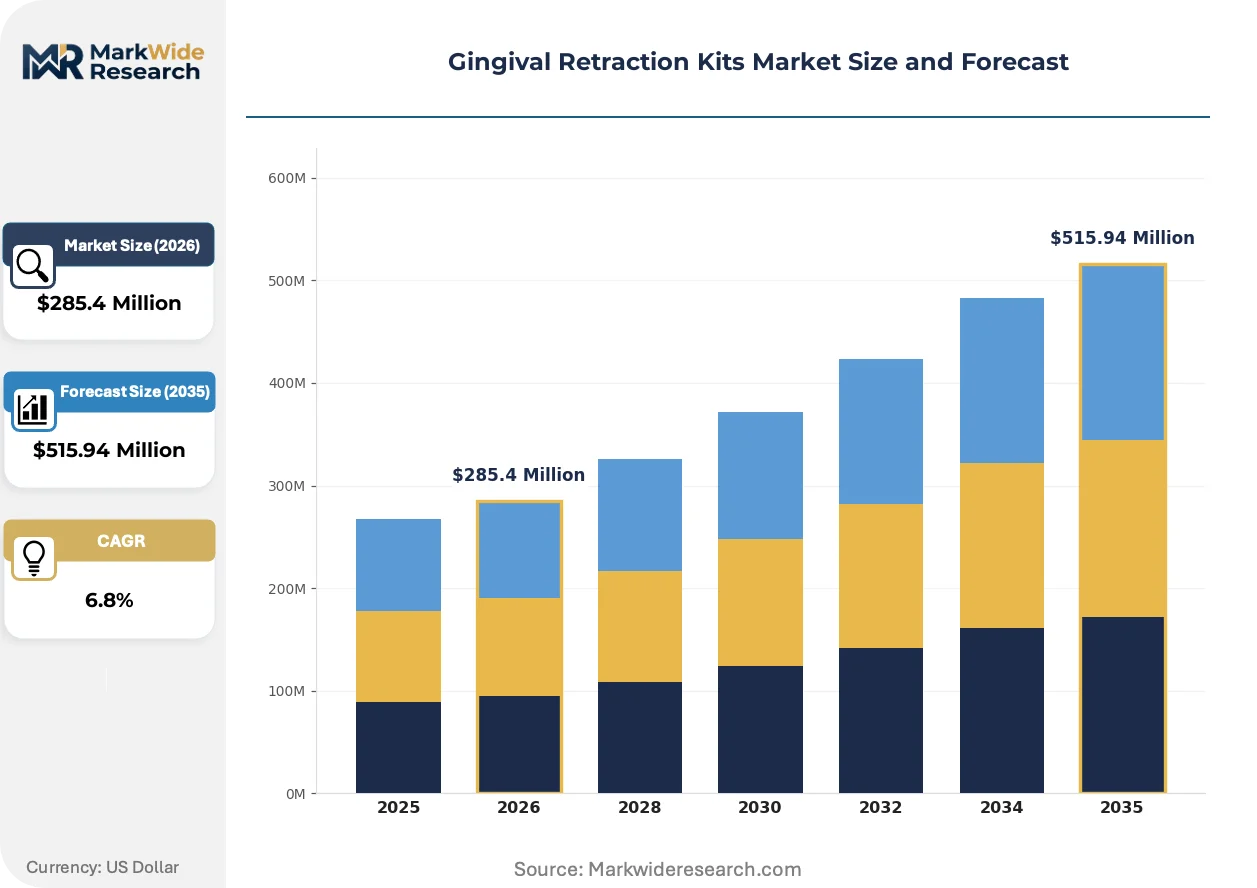
Market Dynamics
EU MDR's tightened conformity assessment for pharmacologically active substances is forcing manufacturers to revalidate entire product lines, compressing margins while elevating barriers for new entrants across the gingival retraction kits landscape.
Growth Catalysts
- Adhesive Dentistry Protocols:Advanced bonding techniques in prosthodontic centers require precise moisture control, expanding procedural indications for retraction kits beyond traditional crown preparations.
- FDA Class II Pathway:Clearer medical device classification for aluminum chloride formulations accelerates time-to-market for validated cord products in United States dental clinics.
- Peri-Implant Soft Tissue Standardization:Implant placement protocols now mandate controlled tissue deflection, creating procedure-linked demand in specialized oral surgery practices.
Market Restraints
- EPA Metal Salt Restrictions:Evolving environmental regulations on astringent chemistry force costly formulation pivots before registration cycles complete.
- Notified Body Bottlenecks:EU MDR's limited conformity assessment capacity extends certification timelines for pharmacologically active devices by 12-18 months.
- Biocompatibility Testing Burden:ISO 10993 validation requirements for braided polyester and cellulose substrates add fixed costs that disadvantage smaller manufacturers.
Strategic Opportunities
- Polymeric Expanding Materials:Hydrogel-based retraction systems reduce tissue trauma and technique sensitivity, opening adoption among general practitioners previously avoiding cord-based methods.
- Digital Impression Ecosystem Integration:Scanner-compatible retraction protocols create bundling potential with intraoral scanning workflows in high-volume prosthodontic centers.
- German Reimbursement Framework:Favorable prosthodontic procedure coding supports premium kit pricing in Europe's densest concentration of specialized dental laboratories.
Industry Challenges
- REACH Compliance Timeline:Chemical substance registration deadlines for ferric sulfate and aluminum chloride variants compress product development windows.
- Technique Sensitivity Gap:Cord packing skill requirements limit consistent outcomes in general dental practices, driving support costs and product returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gingival Retraction Kits Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cord Retraction Kits, Paste Retraction Kits, Capsule Retraction Kits, Expanding Polymeric Retraction Kits Application: Impression Making, Restorative Procedures, Crown Preparation, Implant Placement, Periodontal Treatments End User: Dental Clinics, Dental Laboratories, Orthodontic Practices, Prosthodontic Centers, Dental Academies Distribution Channel: Direct Sales, Dental Distributors, Online Pharmacies, Retail Medical Stores, Professional Dental Supply Companies |
| Companies Covered | Ultradent Products, 3M Company, Dentsply Sirona, Coltene Holding AG, Kerr Corporation, Henry Schein, GC Corporation, Parkell, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gingival Retraction Kits Market Shifts & Advancements
Material science advances and regulatory recalibration are restructuring competitive advantage in gingival retraction, with three concurrent developments reshaping how practitioners achieve tissue deflection and moisture control.
Expanding polymeric retraction systems are migrating from niche specialty applications toward mainstream restorative workflows. Hydrogel and paste-based materials that chemically expand rather than mechanically displace tissue now capture growing share among general practitioners seeking reduced trauma and simplified technique. This migration is compressing the installed base advantage traditionally held by braided cord manufacturers.
EU MDR's substance-based device classification now mandates notified body involvement for all retraction products containing pharmacologically active agents. The regulation elevates documentation requirements for aluminum chloride and epinephrine formulations, disproportionately affecting European manufacturers with legacy product portfolios. German and Swiss suppliers are accelerating biocompatibility dossier preparation to maintain market access.
Direct purchasing by large dental service organizations is consolidating procurement decisions previously fragmented across individual practitioners. These buying entities now negotiate kit pricing and exclusive supply agreements at regional scale, displacing traditional distributor relationships in United States metropolitan markets. The concentration is most visible in Florida and Texas, where DSO-affiliated clinics represent over forty percent of restorative procedure volume.
Gingival Retraction Kits Market Segmentation
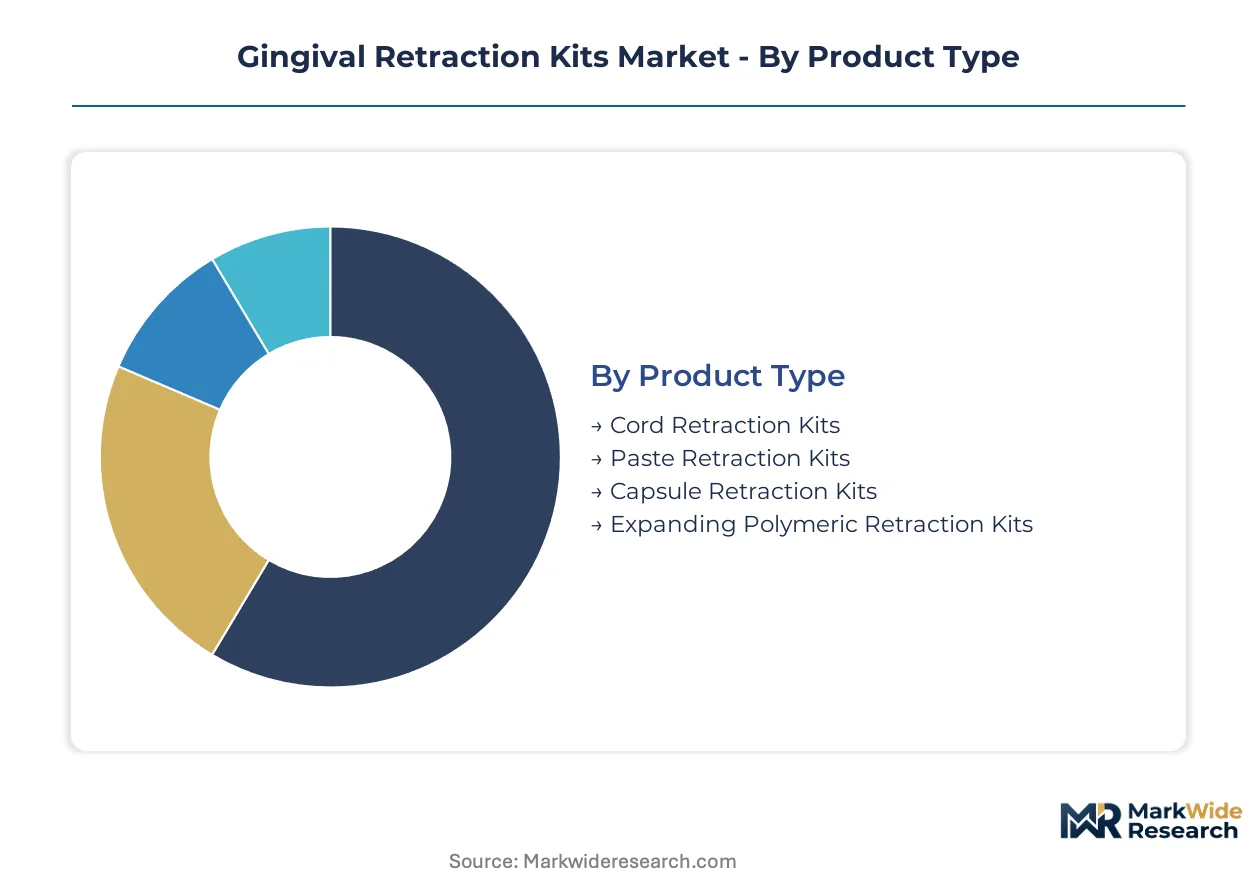
Segmentation in gingival retraction kits reveals distinct procurement patterns and clinical preferences that shape manufacturer portfolio priorities. Product type concentration determines margin structure, while end-user channel dynamics dictate salesforce deployment and distributor relationship investments.
Product Type:
Cord retraction kits turn inventory slowest due to established practitioner familiarity, while expanding polymeric systems cycle rapidly as early adopters trial newer chemistries.
- Cord Retraction Kits:Braided or knitted cords impregnated with aluminum chloride or ferric sulfate remain the clinical default for controlled tissue displacement. Demand concentrates in United States prosthodontic centers where technique predictability outweighs trauma concerns, though EPA metal salt restrictions are forcing formulation audits ahead of registration renewals.
- Expanding Polymeric Retraction Kits:Hydrogel and paste-based materials chemically expand to displace gingival tissue without mechanical packing. German dental clinics are adopting these systems fastest as practitioners seek reduced post-operative recession and simplified chairside workflow.
- Paste Retraction Kits:Astringent pastes delivered via syringe applicator for irregular tissue architecture or narrow sulcus depths.
- Capsule Retraction Kits:Unit-dose capsules containing pre-measured retraction agents for single-tooth applications.
Cord retraction kits anchor the volume base while expanding polymeric retraction kits gain share at the steepest rate.
Application:
Procedure reimbursement tiers separate high-volume restorative work from specialized implant and periodontal interventions.
- Impression Making:Definitive impression capture demands precise moisture control and tissue deflection, making retraction kits indispensable for crown and bridge workflows. United States dental clinics consume the majority of kit volume here, driven by adhesive dentistry protocol adoption and digital scanner compatibility requirements.
- Implant Placement:Peri-implant soft tissue management requires atraumatic retraction to preserve keratinized tissue architecture. German and Swiss oral surgery practices are standardizing these protocols fastest, creating procedure-linked demand for biocompatible expanding materials.
- Restorative Procedures:Direct and indirect restorations requiring temporary or definitive cementation with dry field isolation.
- Crown Preparation:Tooth reduction procedures preceding definitive restoration fabrication.
- Periodontal Treatments:Surgical and non-surgical interventions requiring gingival margin visibility.
Impression making commands the largest procedure volume while implant placement climbs the fastest as peri-implant protocols mature.
End User:
Procurement scale and specification authority vary sharply between independent practitioners and institutional buyers.
- Dental Clinics:General and specialty practices performing chairside restorative and surgical procedures represent the dominant consumption node. Large dental service organizations in Florida and Texas now negotiate direct purchasing agreements, consolidating previously fragmented buying decisions.
- Prosthodontic Centers:Specialized practices with high crown and bridge volumes drive premium kit specification. German centers benefit from favorable procedure coding that supports advanced material adoption.
- Dental Laboratories:Technical facilities supporting chairside practitioners with model work and restoration fabrication.
- Orthodontic Practices:Alignment and bracket placement procedures with intermittent retraction needs.
- Dental Academies:Training institutions standardizing technique curricula for emerging practitioners.
Dental clinics anchor the volume base while prosthodontic centers expand kit specification fastest.
Distribution Channel:
Channel concentration reflects geographic market maturity and regulatory compliance burden.
- Dental Distributors:Regional and national supply houses maintain broad inventory positions across multiple manufacturer lines. Western European distributors face EU MDR documentation requirements that favor established suppliers with complete technical files.
- Direct Sales:Manufacturer-controlled relationships bypass distributor margins for high-volume accounts. United States dental service organizations increasingly demand this channel for price transparency and exclusive supply terms.
- Professional Dental Supply Companies:Specialty channels serving prosthodontic and oral surgery segments.
- Online Pharmacies:E-commerce platforms with limited penetration in regulated dental devices.
- Retail Medical Stores:Consumer-facing outlets with minimal relevance to professional dental procurement.
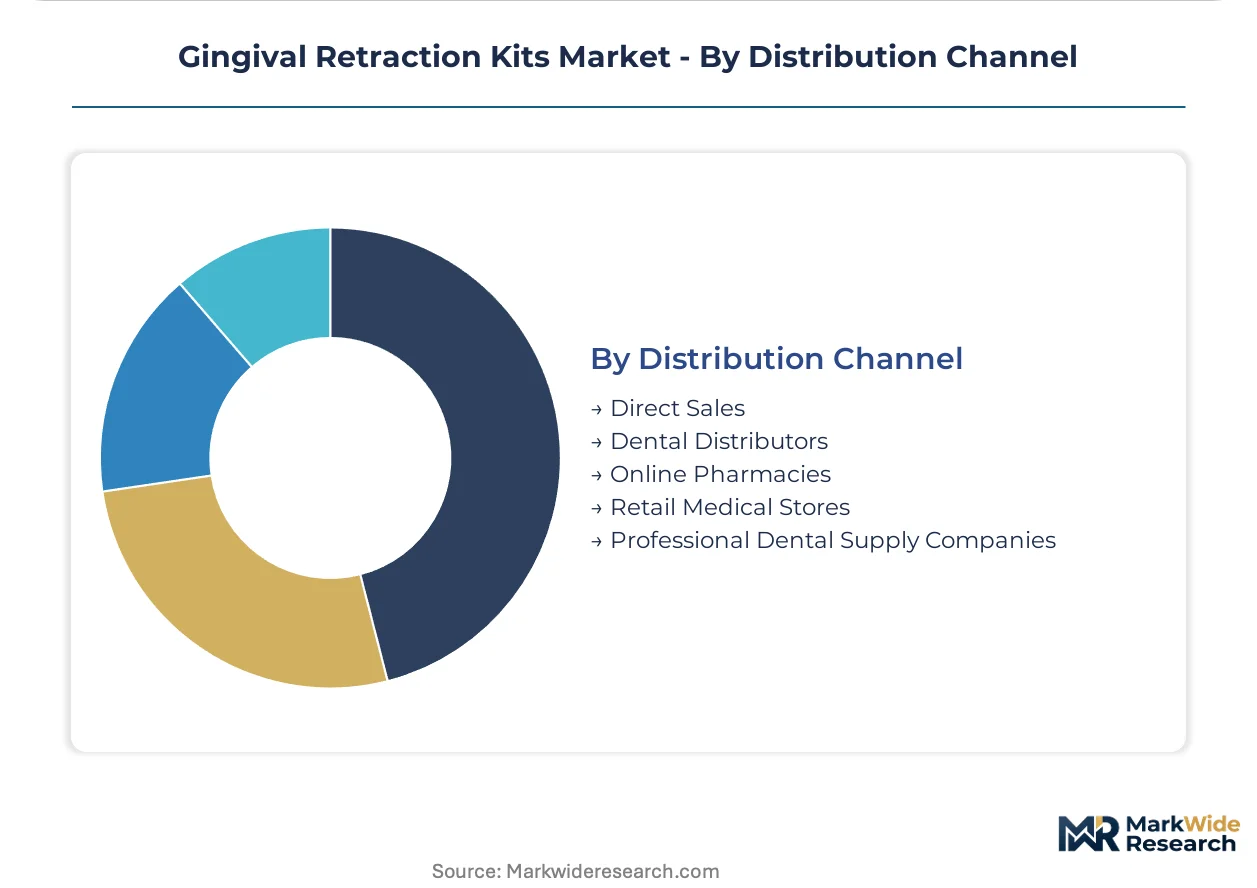
Dental distributors anchor the volume base while direct sales gains share at the steepest rate as institutional buying concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Favorable prosthodontic reimbursement frameworks in Germany and the United States are accelerating premium kit adoption, while regulatory harmonization pressures reshape manufacturing footprints across multiple jurisdictions.
United States
Large dental service organizations in Florida and Texas now negotiate direct purchasing agreements, consolidating procurement decisions that previously fragmented across individual practitioners. FDA Class II medical device pathways for aluminum chloride formulations provide clearer regulatory trajectories for cord-based products. Prosthodontic centers in metropolitan markets drive specification authority for advanced retraction systems.
Germany
Dense concentrations of specialized dental laboratories and prosthodontic practices sustain Europe's highest per-capita kit consumption. EU MDR conformity assessment requirements for pharmacologically active substances force manufacturers to revalidate legacy product lines. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia specialize in biocompatible expanding materials.
Switzerland
Swissmedic oversight elevates documentation standards for retraction products containing epinephrine or ferric sulfate variants. Oral surgery practices in Zurich and Geneva standardize peri-implant soft tissue protocols fastest among European markets. Premium pricing tolerance supports adoption of hydrogel-based systems with reduced tissue trauma profiles.
Japan
PMDA medical device classification aligns with ISO 10993 biocompatibility testing requirements, constraining material selection for imported kits. Prosthodontic centers in Tokyo and Osaka prioritize technique predictability in cord-based retraction for crown and bridge workflows. Domestic distributors face compressed margins as direct sales channels penetrate high-volume accounts.
Brazil
ANVISA regulatory pathways for dental impression materials create certification bottlenecks for multinational suppliers entering Latin America's largest dental market. São Paulo-based prosthodontic centers anchor regional demand for premium retraction systems. Distributor networks in the Southeast region maintain broad inventory positions across multiple manufacturer lines.
Gingival Retraction Kits Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified dental consumables conglomerates and specialized retraction material manufacturers. Three strategic archetypes dominate: diversified multinationals with direct sales infrastructure, regional specialists with channel control in professional dental supply, and materials science firms pivoting from adjacent oral care segments. Competitive moves concentrate on M&A for digital workflow integration and capacity expansion for polymeric expanding materials.
Among diversified dental consumables manufacturers, 3M Company, Ultradent Products, and Dentsply Sirona occupy distinct positions within the competitive hierarchy. 3M exemplifies the scale-driven archetype with established direct sales relationships. Ultradent Products represents specialty channel control in professional dental supply segments. Dentsply Sirona sits within the digital ecosystem integration tier, bundling retraction consumables with intraoral scanning workflows.
| Leading Market Players |
|---|
| Ultradent Products |
| 3M Company |
| Dentsply Sirona |
| Coltene Holding AG |
| Kerr Corporation |
| Henry Schein |
| GC Corporation |
| Parkell |
| Ivoclar Vivadent |
| Others |
Supply & Pricing Matrix
Baden-Württemberg manufacturing clusters in Germany anchor polymeric expanding material capacity, and their output constraints directly transmit to premium kit pricing power in European prosthodontic centers. FDA Class II pathway clarity in the United States compresses registration timelines for aluminum chloride cord formulations, shifting competitive advantage toward validated suppliers with complete technical files.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-cleared and CE-marked kits commanding substantial premiums over non-validated alternatives. Three-tier pricing structure separates premium hydrogel systems from standard cord kits and economy-grade unimpregnated cords. Cost compression in the economy tier is intensifying because EPA metal salt restrictions force formulation audits ahead of registration renewals. General dental practices in the United States exhibit highest price sensitivity, while German prosthodontic centers show lowest sensitivity due to favorable procedure coding.
Supply Chain Analysis
REACH chemical substance registration deadlines function as de facto export controls, limiting ferric sulfate and aluminum chloride variant flows into European markets. Manufacturing concentrates in Germany, Switzerland, and the United States, with braided polyester and cellulose substrate sourcing drawing from specialized textile suppliers in Italy and Portugal. Single-source vulnerability around pharmacologically active ingredient suppliers elevates risk profiles for legacy cord manufacturers. Distribution runs through dental distributor networks in Western Europe and direct sales channels for United States dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Expanding polymeric retraction systems sit at early-cycle penetration among general practitioners previously avoiding cord-based methods, with hydrogel chemistry tailwinds supporting multi-year adoption runway.
For Market Incumbents: Insulate core cord kit revenue by accelerating biocompatibility dossier preparation ahead of EU MDR substance-based reclassification deadlines. Secure backward integration into hydrogel polymer supply to defend margin position against materials science entrants pivoting from adjacent oral care segments. For New Entrants and Emerging Players: Pursue white-space opportunity in implant placement protocols across German and Swiss oral surgery practices, where peri-implant soft tissue standardization creates procedure-linked demand for biocompatible expanding materials. Target direct sales relationships with large dental service organizations in Florida and Texas as the most penetrable channel, leveraging price transparency demands to displace incumbent distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because formulation chemistry expertise and regulatory validation timelines create durable moats around premium positioning. Acquisition targets should profile as regional specialists with channel control in professional dental supply and complete EU MDR technical files. The signal to watch is notified body certification timeline compression, which would indicate regulatory capacity expansion enabling faster new entrant clearance.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR substance-based classification mandates notified body involvement for pharmacologically active retraction products. |
| Backward Integration | In-house hydrogel polymer production secures supply continuity for expanding retraction system manufacturers. |
| Hospital System Partnership | Large dental service organization direct purchasing agreements consolidate fragmented procurement decisions in metropolitan markets. |
| Software Companion Development | Scanner-compatible retraction protocols create bundling potential with intraoral scanning workflows in prosthodontic centers. |
| Reimbursement Strategy | Favorable German prosthodontic procedure coding supports premium kit pricing in Europe's densest laboratory concentration. |
Research Methodology
Operator-level perspectives from prosthodontists, oral surgeons, dental service organization procurement directors, and distributor inventory managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases. Customs data on aluminum chloride and ferric sulfate trade flows supplemented material cost assumptions. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, optimistic, and conservative cases reflecting differential adoption rates for expanding polymeric systems. Segmentation dimensions modeled include product type, application procedure, end-user channel, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to adhesive dentistry protocol penetration and implant placement growth curves. Industry-specific forecast inputs incorporated EPA metal salt restriction timelines and notified body certification capacity constraints.
Sensitivities concentrate around REACH compliance deadlines for active ingredients and notified body bottleneck resolution timelines. Forecasts reflect assumptions on regulatory pathway stability and prosthodontic reimbursement framework continuity. Material shifts in EU MDR implementation rigor or EPA enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Gloves Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Smear Mask Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Blood Bags Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market